
 Injectable Bulking Agents Market | 2026-2036
Injectable Bulking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Bulking Agents Market Foresight
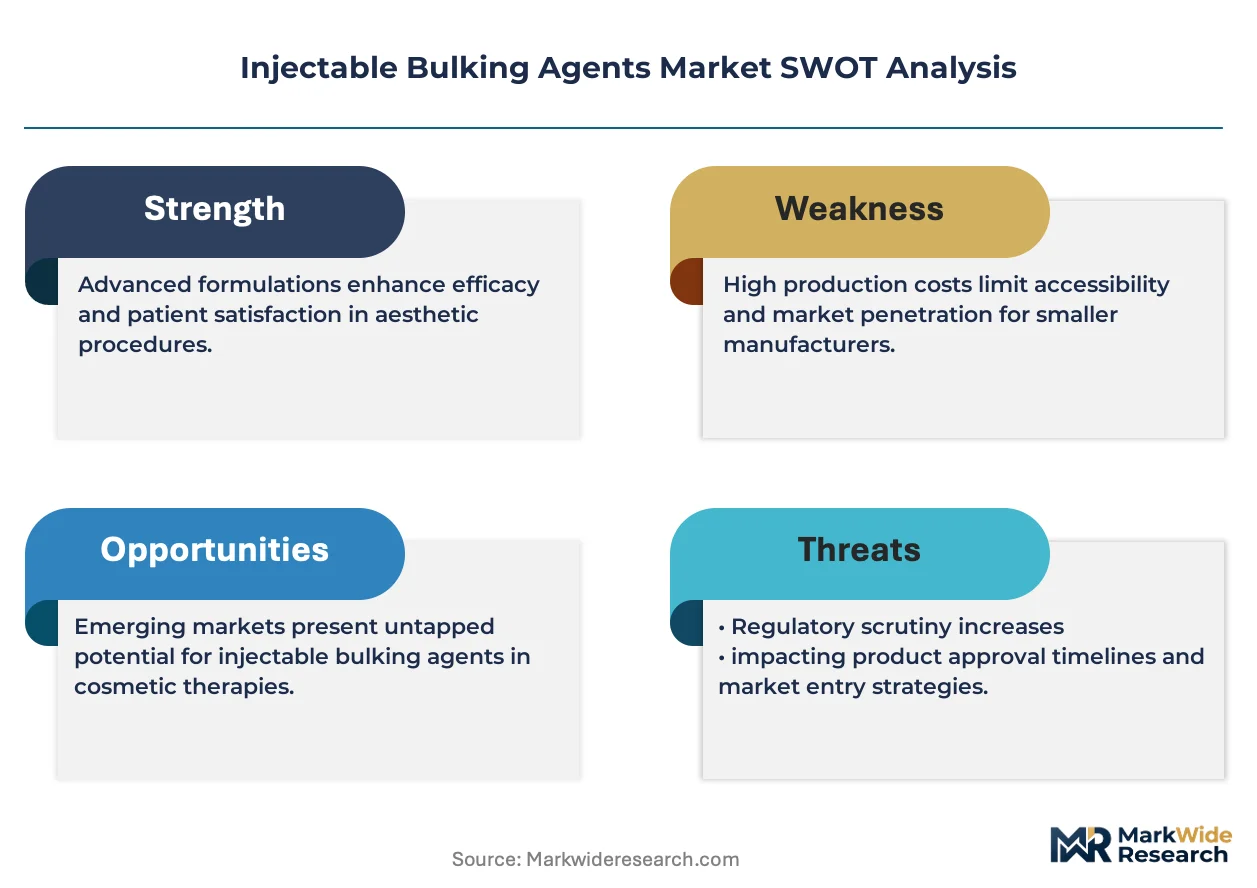
CE-marked and FDA-cleared premium-tier formulations is bifurcating the competitive landscape into permanent and resorbable camps. AbbVie Inc. (Allergan) anchors the hyaluronic acid segment through Juvederm's brand equity and extensive practitioner training networks. Merz Pharmaceuticals GmbH differentiates via its calcium hydroxylapatite portfolio, leveraging R&D intensity to sustain clinical differentiation in facial contouring. Galderma SA competes across both aesthetic and therapeutic indications, extending its dermatology channel control into urological bulking applications.
Injectable bulking agents comprise biocompatible or synthetic materials delivered via minimally invasive injection to restore tissue volume, improve sphincter competence, or correct contour defects; hyaluronic acid formulations typically exhibit particle sizes of 500–1000 μm with cross-linking densities determining residence time from six months to two years. The product-type dimension shows hyaluronic acid occupying the largest revenue pool due to reversibility and established safety profiles, while calcium hydroxylapatite captures premium margins in longer-duration facial applications. Application-level demand concentrates in dermatology for aesthetic volumization, though urology represents the fastest-growing therapeutic avenue as stress urinary incontinence protocols shift toward outpatient cystoscopic injection.
FDA 510(k) pathways and the EU Medical Device Regulation impose distinct biocompatibility and clinical evidence thresholds that filter market access for permanent polyacrylamide implants versus resorbable alternatives. The European Medicines Agency coordinates with notified bodies under MDR to enforce post-market surveillance for novel bulking compositions, while Health Canada and TGA align with ISO 10993 standards for cytotoxicity testing. Stakeholders must monitor evolving regulatory divergence between jurisdictions on permanent filler classifications to anticipate where clinical trial investments will unlock commercial priority.
Market Dynamics
Cross-linked hyaluronic acid formulations with tunable degradation profiles are concentrating R&D investment and reshaping competitive positioning between temporary and permanent filler camps.
Growth Catalysts
- Outpatient urology protocols:Cystoscopic bulking agent injection for stress urinary incontinence is displacing invasive sling procedures in United States ambulatory surgical centers.
- EU MDR harmonization:Streamlined CE marking pathways for resorbable fillers under Medical Device Regulation are accelerating product line extensions across European aesthetic clinics.
- Calcium hydroxylapatite microsphere engineering:Improved particle uniformity is extending duration claims in facial contouring applications.
Market Restraints
- Raw material concentration:Pharmaceutical-grade hyaluronic acid supply concentrates among three fermentation biotechnology suppliers in South Korea and China.
- FDA 510(k) evidentiary thresholds:Permanent polyacrylamide hydrogels face elevated biocompatibility study requirements compared to resorbable alternatives.
- Autologous fat grafting:Lipotransfer techniques using patient-derived adipose tissue present a viable substitute for synthetic volumizing in high-end aesthetic practices.
Strategic Opportunities
- Brazil therapeutic expansion:ANVISA regulatory alignment with ISO 10993 standards is opening outpatient urology applications previously restricted to hospital settings.
- Combination device-drug platforms:Integration of bulking agents with precision injection systems is creating differentiated delivery ecosystems.
- India dermatology channel buildout:Tier-2 city clinic networks remain underpenetrated for premium hyaluronic acid protocols.
Industry Challenges
- Interventional urology training pipelines:Cystoscopic injection technique certification programs face bottlenecks limiting procedure volume scaling.
- Post-market surveillance infrastructure:MDR-mandated vigilance systems require substantial IT investment for adverse event tracking across distributed clinic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Bulking Agents Market |
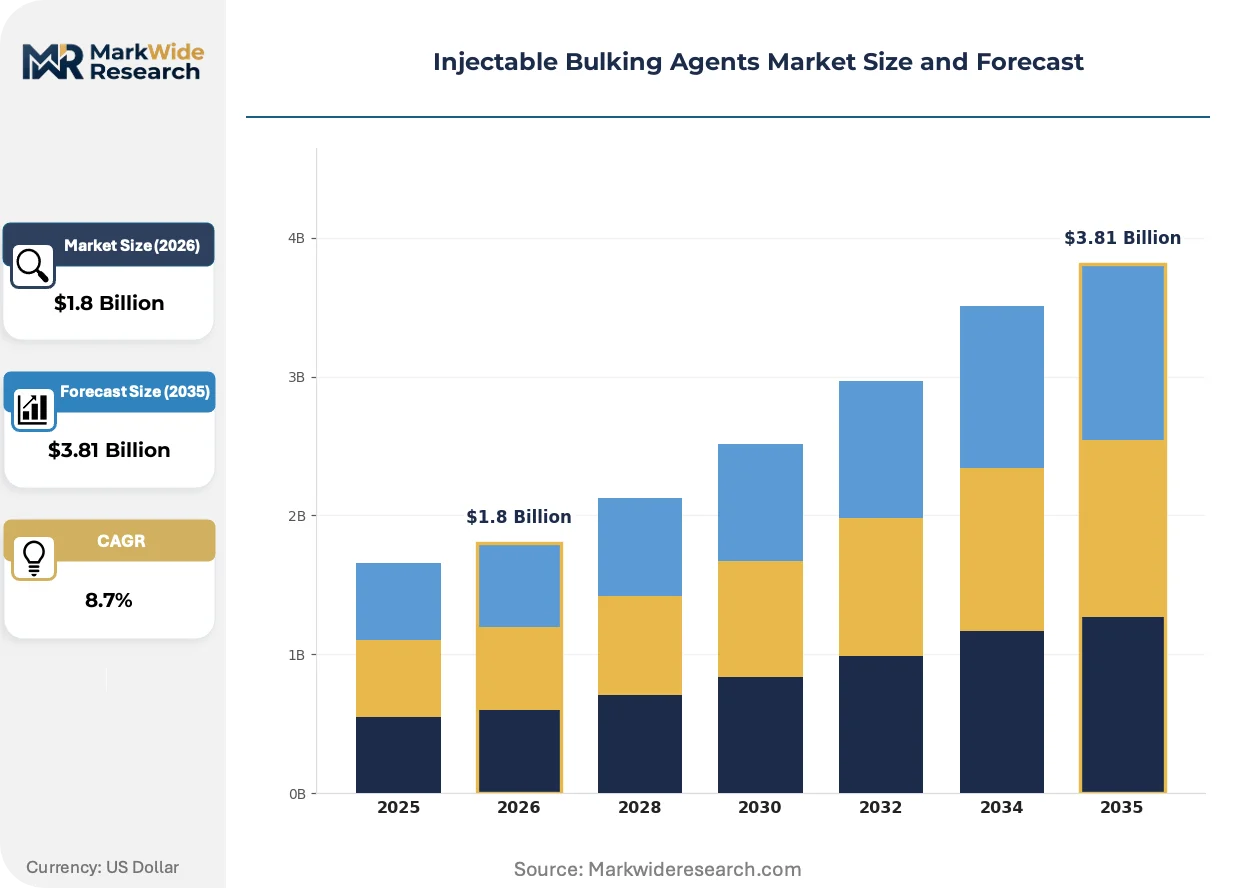
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Polyacrylamide, Calcium Hydroxylapatite, Collagen Application: Dermatology, Urology, Gastroenterology, Gynecology End User: Hospitals, Aesthetic Clinics, Ambulatory Surgical Centers, Dermatology Clinics Delivery Mode: Injectable, Transdermal, Intradermal, Subcutaneous |
| Companies Covered | AbbVie Inc. (Allergan), Merz Pharmaceuticals GmbH, Galderma SA, Coloplast Corp, Suneva Medical Inc, Anika Therapeutics Inc, Sanofi SA, Zimmer Biomet Holdings Inc, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Bulking Agents Market Shifts & Advancements
Injectable bulking agent development is pivoting toward bioengineered matrices that merge immediate volumizing with sustained tissue integration. Three intersecting developments are compressing traditional product lifecycles.
Dual-phase composite fillers combining hyaluronic acid with polycaprolactone microspheres are supplanting single-component formulations in facial rejuvenation protocols. Aesthetic practitioners in Germany and South Korea are adopting these hybrids at accelerating rates for patients seeking intermediate durability between six-month and permanent options. The structural consequence is margin compression for standalone hyaluronic acid portfolios lacking cross-linking innovation.
EMA coordination with notified bodies under EU MDR Article 117 is elevating clinical evidence requirements for novel bulking compositions seeking CE marking. Manufacturers must now submit prospective safety data rather than relying on predicate device equivalence. Permanent filler categories face the steepest compliance burden, with several compositions delayed in German and French market entry timelines.
Direct-to-clinic procurement platforms are disintermediating traditional aesthetic distributor networks in North American metropolitan markets. Group purchasing organizations aggregating independent dermatology practices now negotiate volume contracts previously reserved for hospital systems. This channel shift is most pronounced in California and Texas, where practice consolidation has created purchasing entities exceeding fifty affiliated providers.
Injectable Bulking Agents Market Segmentation
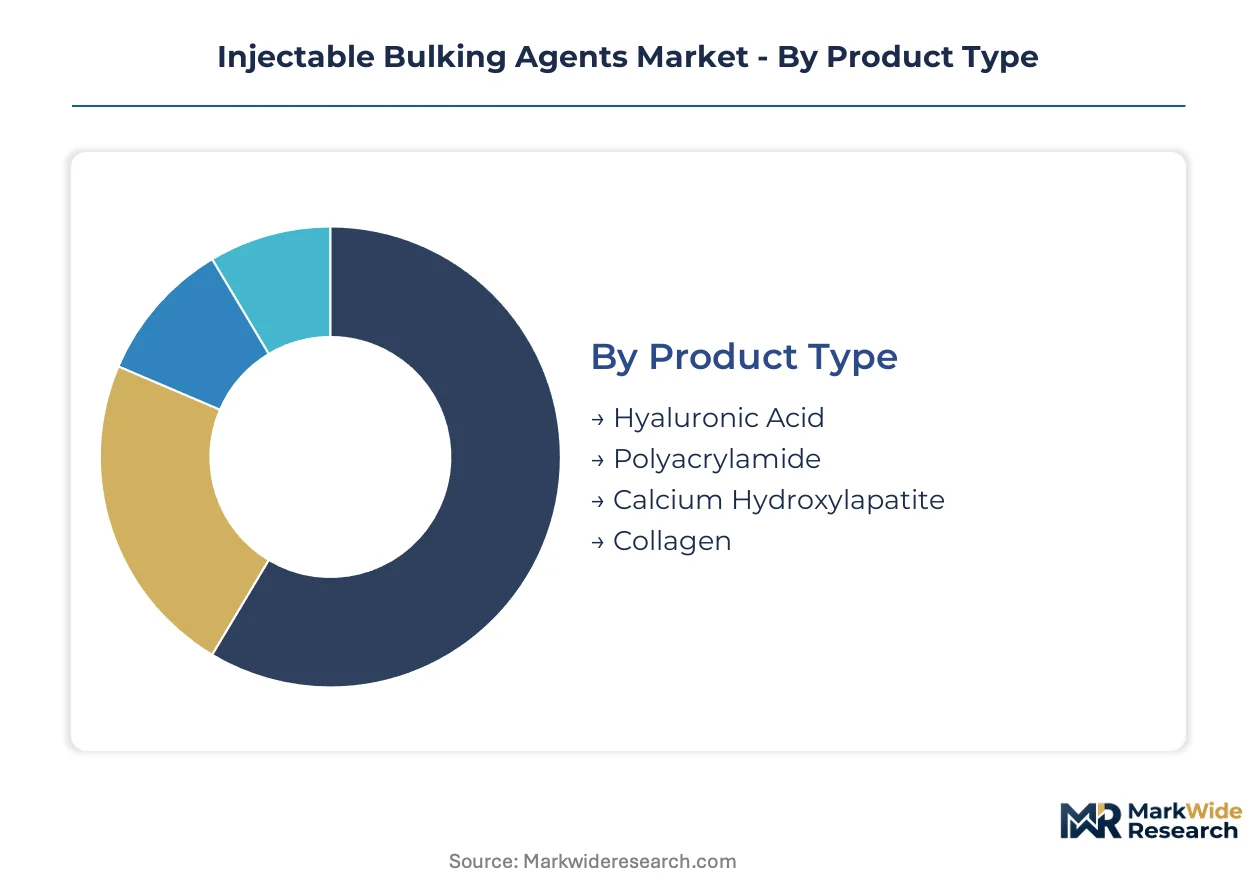
Injectable bulking agents serve heterogeneous clinical endpoints that demand precise material-property matching. Segmentation reveals where formulation chemistry, procedural setting, and regulatory pathway intersect to determine commercial viability.
Product Type:
Substitution pressure from autologous fat grafting and surgical alternatives varies sharply by material permanence and reversibility profile.
- Hyaluronic Acid:Cross-linked polysaccharide gels with tunable particle sizing (500–1000 μm) and degradation windows spanning six months to two years. Demand concentrates in United States aesthetic clinics where reversibility commands premium pricing and practitioner liability exposure remains manageable.
- Calcium Hydroxylapatite:Biosynthetically produced microspheres suspended in aqueous carrier gel, engineered for 12–18 month persistence through neocollagenesis stimulation. Facial contouring applications in Germany and South Korea are expanding most quickly as microsphere uniformity improvements extend duration claims.
- Polyacrylamide:Permanent hydrogel implant with non-resorbable matrix structure.
- Collagen:Bovine or human-derived resorbable protein matrix with shorter residence time.
Hyaluronic acid handles the majority of throughput; calcium hydroxylapatite is climbing the fastest on share as intermediate-duration protocols gain traction.
Application:
Reimbursement architecture and procedure invasiveness create divergent margin profiles across clinical specialties.
- Dermatology:Aesthetic volumization and wrinkle correction protocols utilizing facial injection techniques. United States metropolitan markets sustain the highest procedure densities, though Brazil and South Korea are scaling channel infrastructure for premium hyaluronic acid delivery.
- Urology:Cystoscopic periurethral injection for stress urinary incontinence sphincter competence restoration. Outpatient protocols in United States ambulatory surgical centers are displacing invasive sling surgeries as FDA-cleared formulations accumulate payer coverage.
- Gastroenterology:Endoscopic injection for esophageal or anal sphincter deficiency.
- Gynecology:Vaginal wall prolapse and urinary incontinence applications.
Dermatology retains volume leadership; urology is expanding most quickly as reimbursement frameworks mature.
End User:
Capital equipment requirements and staff certification depth determine which settings can absorb specific procedure types.
- Hospitals:Inpatient and outpatient departments with full surgical backup capability. Complex urological and gynecological bulking procedures requiring anesthesia support concentrate here, particularly in France and Japan where centralized healthcare delivery persists.
- Aesthetic Clinics:Dedicated cosmetic medicine facilities with dermatology-trained injectors. These settings dominate facial volumization in California and Texas, where direct-to-clinic procurement platforms are consolidating purchasing power.
- Ambulatory Surgical Centers:United States outpatient facilities capturing cystoscopic urology volumes.
- Dermatology Clinics:Physician-owned practices with specialized skin-focused service lines.
Aesthetic clinics process the highest facial procedure throughput; ambulatory surgical centers are gaining share fastest in therapeutic urology.
Delivery Mode:
Injection depth and tissue plane targeting dictate device compatibility and practitioner training requirements.
- Injectable:Standard hypodermic or cannula-based delivery into subcutaneous or deep dermal planes. This modality captures nearly all hyaluronic acid and calcium hydroxylapatite volume, with technique certification programs in Germany and South Korea setting quality benchmarks.
- Transdermal:Surface-applied delivery systems without needle penetration.
- Intradermal:Superficial dermal plane injection for fine-line correction.
- Subcutaneous:Deep tissue deposition for structural volumization.
Standard injectable delivery commands the dominant procedure share; subcutaneous protocols are expanding fastest as longer-duration fillers target deeper tissue planes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence for pharmaceutical-grade hyaluronic acid raw material shapes regional manufacturing economics, with finished formulation trade flows concentrating where aesthetic clinic density and urology reimbursement frameworks align.
United States
FDA 510(k) clearance pathways for resorbable fillers sustain premium pricing power in aesthetic clinics across California and Texas. CMS reimbursement codes for cystoscopic bulking agent injection in stress urinary incontinence are displacing invasive sling procedures in ambulatory surgical centers. Greater Boston and Pacific Northwest medical device clusters concentrate precision injection system manufacturing.
Germany
EMA-coordinated CE marking under EU MDR Article 117 elevates clinical evidence requirements for novel bulking compositions seeking market entry. Calcium hydroxylapatite microsphere engineering for facial contouring concentrates in Baden-Württemberg's precision manufacturing corridor. Bavarian aesthetic clinic networks are adopting dual-phase composite fillers at accelerating rates.
South Korea
Fermentation biotechnology suppliers in Seoul Capital Area dominate pharmaceutical-grade hyaluronic acid raw material output for export markets. MFDS regulatory alignment with ISO 10993 standards streamlines domestic aesthetic product registration. Busan-Ulsan industrial complexes host microsphere processing facilities serving regional formulation demand.
Brazil
ANVISA regulatory harmonization with international biocompatibility standards is opening outpatient urology applications previously restricted to hospital settings. São Paulo's dermatology channel infrastructure supports premium hyaluronic acid protocol expansion into tier-2 city clinic networks. Rio de Janeiro aesthetic medicine training centers are scaling practitioner certification programs.
Japan
PMDA marketing authorization pathways for permanent versus resorbable fillers impose distinct biocompatibility study thresholds filtering product entry. Kanto region aesthetic clinics concentrate facial volumization procedure volume. Osaka-Kansai medical device clusters manufacture precision injection delivery systems for regional and export markets.
Injectable Bulking Agents Market Competitive Landscape
Concentration sits with diversified dermatology and urology specialists commanding channel control across both aesthetic and therapeutic indications. Market structure exhibits tiered segmentation between premium hyaluronic acid portfolios, intermediate-duration calcium hydroxylapatite formulations, and permanent implant categories facing elevated regulatory burden. Two dominant archetypes prevail: integrated dermatology channel operators leveraging practitioner training networks, and interventional urology device-drug combination platforms. Competitive moves center on M&A for regional regulatory infrastructure and strategic partnerships for precision injection system integration.
Among North American and European diversified pharmaceutical operators, AbbVie Inc. (Allergan), Merz Pharmaceuticals GmbH, and Galderma SA occupy positions exemplifying the dermatology channel control archetype, each representing distinct formulation chemistry strategies spanning reversible and longer-duration segments. These entities anchor competitive positioning through established practitioner certification ecosystems and direct-to-clinic procurement relationships in key metropolitan markets.
| Leading Market Players |
|---|
| AbbVie Inc. (Allergan) |
| Merz Pharmaceuticals GmbH |
| Galderma SA |
| Coloplast Corp |
| Suneva Medical Inc |
| Anika Therapeutics Inc |
| Sanofi SA |
| Zimmer Biomet Holdings Inc |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Autologous fat grafting substitution is compressing synthetic filler premiums while simultaneously redirecting procurement geography toward South Korean fermentation biotechnology clusters and German precision manufacturing corridors.
Pricing Analysis
Aesthetic clinics anchor pricing stratification across premium, standard, and economy tiers based on cross-linking density and practitioner certification depth. FDA 510(k) evidentiary thresholds for permanent polyacrylamide hydrogels widen price differentiation between resorbable and permanent camps, with cost compression in mid-tier hyaluronic acid formulations intensifying due to raw material concentration among Seoul Capital Area suppliers. Hospital procurement committees exhibit highest price sensitivity; ambulatory surgical centers with direct-to-clinic contracts show least elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for pharmaceutical-grade hyaluronic acid raw material. Finished formulation capacity centers on South Korea, Germany, and the United States, drawing from fermentation biotechnology feedstock, calcium hydroxylapatite microsphere precursors, and aqueous carrier gel chemistries. Single-source vulnerability concentrates in Seoul Capital Area hyaluronic acid fermentation; distribution runs through direct-to-clinic procurement platforms disintermediating traditional aesthetic distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against autologous fat grafting substitution while navigating FDA evidentiary divergence between permanent and resorbable filler pathways.
For Market Incumbents: Fortify practitioner certification ecosystems to lock channel control against emerging combination device-drug platforms. Backward integration into pharmaceutical-grade hyaluronic acid fermentation capacity in South Korea secures raw material cost position against supply concentration risk. For New Entrants and Emerging Players: CE marking fast-tracks under EU MDR Article 117 offer lowest regulatory friction for novel resorbable compositions seeking European aesthetic clinic penetration. Target Brazil outpatient urology protocols via ANVISA alignment with ISO 10993 standards, leveraging cystoscopic injection technique training partnerships as go-to-market anchor. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision injection system manufacturers with device-drug integration capabilities. Long-term viability hinges on reimbursement framework maturation in therapeutic urology; watch CMS coverage expansion for cystoscopic stress urinary incontinence protocols as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner Certification Ecosystem Expansion | Allergan's Juvederm training networks demonstrate channel lock-in power across California and Texas metropolitan markets. |
| CE Marking Pathway Investment | EMA-coordinated Article 117 compliance unlocks German and French aesthetic clinic access for novel bulking compositions. |
| Backward Integration into Fermentation Capacity | Captive pharmaceutical-grade hyaluronic acid production in Seoul Capital Area mitigates raw material concentration risk. |
| Precision Injection System Partnership | Device-drug combination platforms differentiate delivery ecosystems in United States ambulatory surgical centers. |
| Reimbursement Strategy Development | CMS coding accumulation for cystoscopic urology procedures displaces invasive sling surgeries in outpatient settings. |
Research Methodology
Initial hypotheses were tested against primary input from interventional urologists, aesthetic clinic medical directors, biomedical engineers at precision injection system manufacturers, and GPO contracts managers, then refined through secondary validation against FDA 510(k) filings, EMA CE marking databases, CMS reimbursement code updates, and ISO 10993 biocompatibility standards. Bottom-up procedure volume estimates from ambulatory surgical center and aesthetic clinic channels were triangulated against top-down manufacturer revenue attribution across the analysis window.
Variance decomposition across product type, application specialty, end-user setting, and regional regulatory cluster informed the analytical framework. CAGRs were derived from segmented volume projections calibrated to historical procedure growth patterns in dermatology and urology, with cross-linking density innovation cycles and reimbursement framework maturation serving as industry-specific forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA 510(k) pathway stability and EU MDR implementation continuity; material deviation in permanent filler classification stringency would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Liposuction Devices Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Global Casting Devices Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Heated Humidifiers Market