
 Global Blood Processing Devices and Consumables Market | 2026-2036
Global Blood Processing Devices and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Processing Devices and Consumables Market Foresight
The blood processing devices and consumables space is rebalancing between premium automated systems and commodity manual collection sets as health systems prioritize throughput over unit cost. Haemonetics Corporation leverages its end-to-end automation portfolio to anchor hospital blood management programs. BD competes through scale in manual collection sets and coagulation diagnostics. Terumo Corporation differentiates via membrane separation technology for therapeutic apheresis applications.
Blood processing devices and consumables encompass instruments and single-use materials designed to collect, separate, test, and store blood components under controlled conditions, typically operating at centrifugal forces of 4,000–5,000 × g for component separation. These systems serve transfusion medicine, hematology diagnostics, and cellular therapy manufacturing by ensuring component purity, sterility, and traceability. Automated blood collection systems command the dominant margin pool as blood banks consolidate toward high-throughput platforms. Coagulation test kits represent the fastest-growing product category, driven by perioperative monitoring protocols and point-of-care expansion. Membrane separation technology leads innovation in therapeutic apheresis, displacing traditional centrifugation in plasma exchange protocols.
The FDA enforces current Good Manufacturing Practice standards and blood establishment registration requirements that shape device validation timelines and software documentation burdens. The EU MDR and IVDR frameworks impose stricter clinical evidence requirements on blood processing equipment marketed in Europe, elevating compliance costs for non-EU manufacturers. WHO guidelines on blood safety and quality systems influence procurement specifications in emerging health systems. Stakeholders must monitor regulatory divergence between FDA software validation pathways and EU MDR technical documentation requirements when prioritizing product development portfolios.
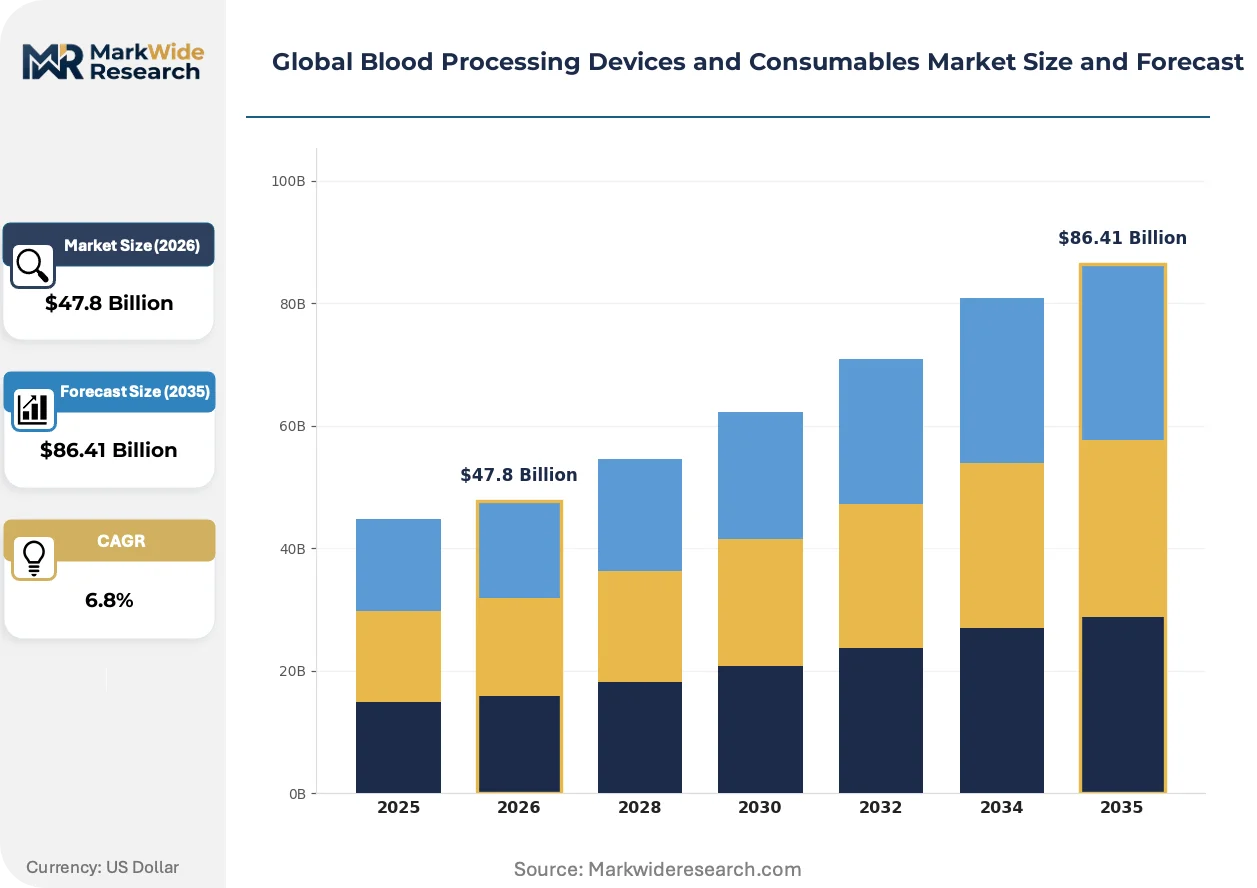
Market Dynamics
Automated blood collection systems are consolidating procurement decisions across integrated health networks, compressing vendor margins while elevating software-integrated platforms that satisfy FDA validation requirements for blood establishment computer systems.
Growth Catalysts
- FDA Blood Establishment Computer System Guidance:Updated software validation mandates are accelerating hospital upgrades to integrated collection platforms that embed traceability and electronic record-keeping.
- Therapeutic Apheresis Expansion:Membrane separation technology is capturing plasma exchange volumes previously served by centrifugation, particularly in neurology and hematology outpatient settings.
- Perioperative Coagulation Monitoring:Surgical protocols mandating point-of-care hemostasis testing are expanding consumable pull-through in trauma centers and cardiac catheterization labs.
Market Restraints
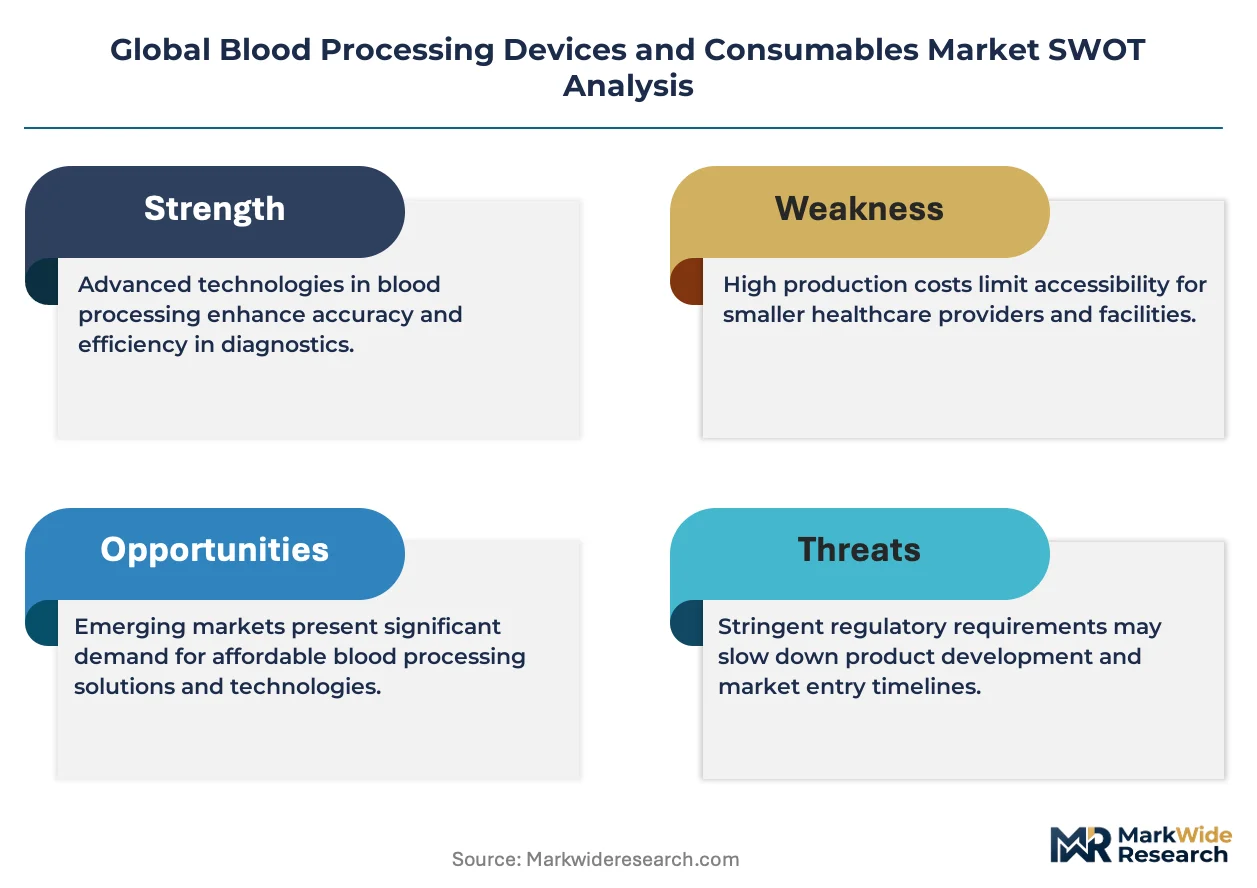
- Plasma-Derived Raw Material Volatility:Fractionation-grade plasma supply concentrates among a limited donor base in the United States and Germany, creating input cost pressure for immunoglobulin and albumin manufacturers.
- EU MDR Technical Documentation Burden:Stricter clinical evidence requirements for blood processing equipment are extending time-to-market for non-EU manufacturers and elevating notified body audit costs.
- Manual Collection Set Commoditization:Standard blood bag configurations face price erosion as procurement consolidators in Brazil and India prioritize unit cost over performance differentiation.
Strategic Opportunities
- Cellular Therapy Manufacturing Infrastructure:CAR-T and gene therapy production facilities require closed-system blood component separation, creating premium equipment demand in Singapore and South Korea bioclusters.
- Leukoreduction Filter Technology Convergence:Integration of pathogen reduction chemistry with filtration media is enabling single-step processing that reduces cold chain handling steps.
- WHO Blood Safety Procurement Specifications:Emerging health systems in sub-Saharan Africa and Southeast Asia are adopting quality system frameworks that favor validated, automated platforms over manual alternatives.
Industry Challenges
- Bioengineer Talent Scarcity:Membrane fabrication and sterile connector design expertise concentrates among specialists in Japan and Switzerland, constraining rapid scale-up for therapeutic apheresis device programs.
- Legacy Blood Bank Information System Integration:Automated collection platforms must interface with decades-old laboratory information management architectures, extending implementation timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Processing Devices and Consumables Market |
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $86.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Blood Collection Systems, Manual Blood Collection Sets, Blood Component Separators, Plasma Extractors, Coagulation Test Kits Application: Cell Salvage, Therapeutic Apheresis, Plasma Exchange, Leukapheresis, Plateletpheresis End User: Diagnostic Laboratories, Blood Banks, Research Institutions, Ambulatory Surgical Centers, Specialty Clinics Technology: Centrifugation, Filtration, Filtrate Recirculation, Membrane Separation, Microfluidics |
| Companies Covered | Haemonetics Corporation, BD, Abbott Laboratories, bioMérieux SA, Bio-Rad Laboratories, Terumo Corporation, F. Hoffmann-La Roche Ltd, Danaher, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Processing Devices and Consumables Market Shifts & Advancements
Membrane-based separation architectures and point-of-care coagulation diagnostics are compressing traditional centrifugation workflows, while regulatory software mandates are reshaping vendor R&D priorities toward validated digital integration.
Membrane separation technology for therapeutic apheresis is integrating plasma exchange, immunoadsorption, and selective filtration into modular platform architectures. Academic medical centers in Germany and Japan are deploying these systems for neuromyelitis optica and myasthenia gravis protocols. The technology is integrating previously discrete processing steps, reducing treatment duration and enabling same-day outpatient administration.
EU MDR and IVDR frameworks are imposing stricter clinical evidence requirements on blood processing equipment marketed in Europe. Manufacturers must now submit post-market surveillance data and risk management files that exceed pre-2021 documentation burdens. Class III device categories and software-driven separation systems face the steepest compliance cost escalation, prompting some vendors to deprioritize EU market entry.
Integrated health networks in the United States are consolidating blood bank procurement under centralized laboratory services, unbundling device purchases from historical consumable bundling arrangements. This procurement compression is forcing vendors to compete on total cost of ownership metrics rather than upfront equipment pricing. The shift is most visible among Catholic health systems and regional hospital alliances consolidating transfusion service operations across multiple states.
Global Blood Processing Devices and Consumables Market Segmentation
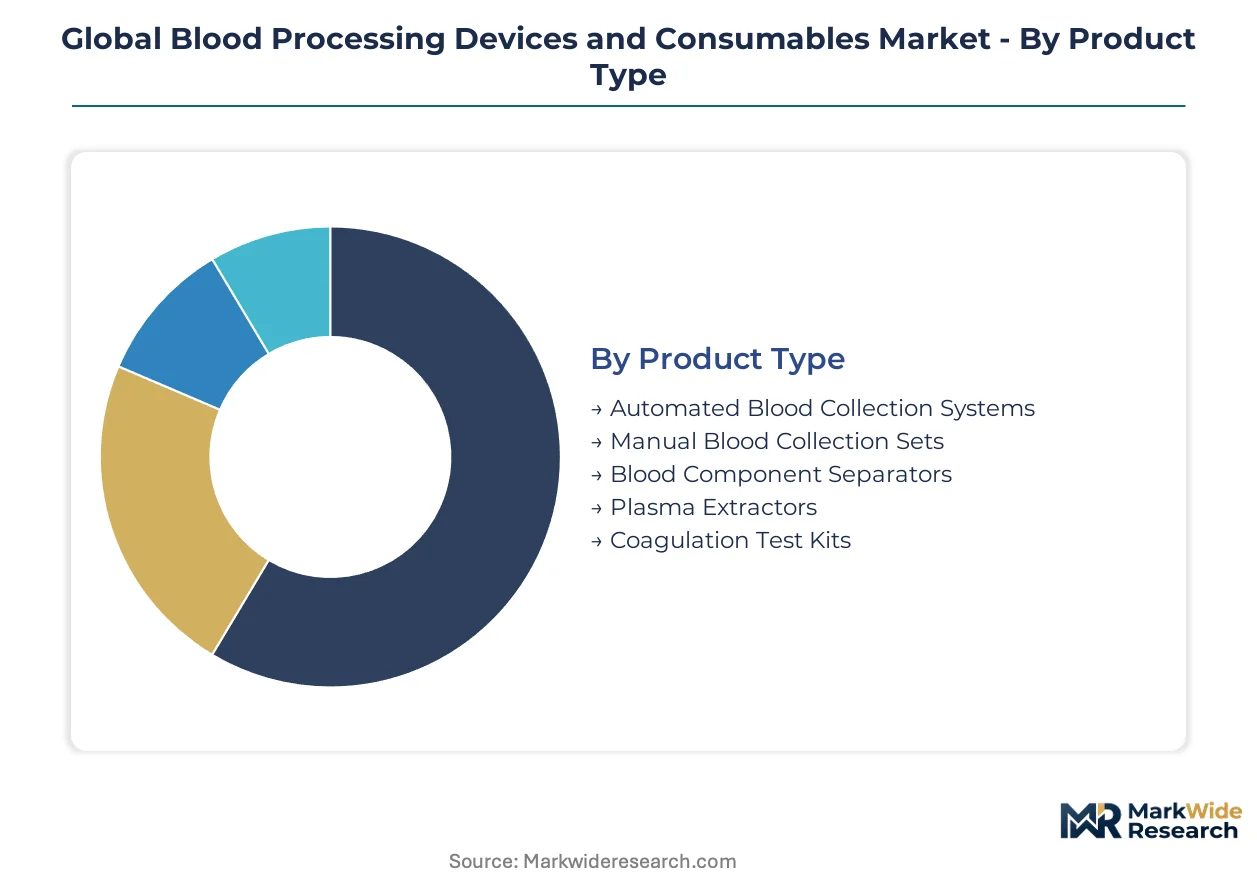
Segmentation in blood processing reveals how procurement priorities diverge between high-throughput automation buyers and cost-sensitive manual set purchasers. Technology choices and application settings determine margin structures, regulatory pathways, and vendor competitive positioning across the value chain.
Product Type:
Cost tier separates buyers seeking validated software-integrated platforms from those prioritizing unit economics in high-volume collection workflows.
- Automated Blood Collection Systems:These platforms integrate donor management software, component separation, and electronic traceability at centrifugal forces of 4,000–5,000 × g. Demand concentrates in United States integrated health networks consolidating transfusion services under centralized laboratory operations, driven by FDA blood establishment computer system validation mandates.
- Coagulation Test Kits:Disposable reagent cartridges and cuvettes enable point-of-care hemostasis monitoring in surgical and trauma settings. Cardiac catheterization labs and trauma centers in Germany and Japan are expanding perioperative testing protocols, compressing turnaround times for transfusion decisions.
- Manual Blood Collection Sets:Standard blood bag configurations with anticoagulant solutions serve resource-limited settings where automation infrastructure is uneconomical.
- Blood Component Separators:Standalone centrifugation units for plasma, platelet, and red cell isolation in blood bank processing laboratories.
- Plasma Extractors:Semi-automated devices for plasma separation from whole blood units in fractionation facilities.
Volume sits with Manual Blood Collection Sets; growth tilts toward Automated Blood Collection Systems.
Application:
Clinical setting determines technology selection, with outpatient neurology and hematology protocols favoring membrane-based approaches over traditional centrifugation.
- Therapeutic Apheresis:Membrane separation platforms perform plasma exchange, immunoadsorption, and selective filtration for autoimmune and neurological indications. Outpatient clinics in Germany and Japan are deploying these systems for neuromyelitis optica and myasthenia gravis, enabling same-day treatment administration.
- Cell Salvage:Intraoperative blood recovery systems wash and concentrate shed red cells for autologous reinfusion. Cardiac and orthopedic surgical suites in United States academic medical centers are standardizing cell salvage protocols to reduce allogeneic transfusion exposure.
- Plasma Exchange:Traditional centrifugation-based removal of patient plasma with replacement fluid administration, still dominant in emergency settings.
- Leukapheresis:White blood cell collection for cellular therapy manufacturing and stem cell transplantation protocols.
- Plateletpheresis:Single-donor platelet collection for transfusion-dependent hematology and oncology patients.
Centrifugation retains volume in Plasma Exchange; membrane technology is gaining share fastest in Therapeutic Apheresis.
End User:
Procurement authority patterns distinguish centralized laboratory services from distributed point-of-care settings with divergent equipment and consumable needs.
- Blood Banks:Regional and hospital-based transfusion services perform component preparation, storage, and distribution. United States Catholic health systems and regional hospital alliances are consolidating blood bank procurement under centralized laboratory services, unbundling device purchases from historical consumable arrangements.
- Diagnostic Laboratories:Hospital and reference laboratories conduct coagulation testing and blood group serology. Point-of-care expansion in cardiac catheterization labs is pulling through high-margin test kit volumes.
- Research Institutions:Academic and biotechnology facilities require flexible processing platforms for protocol development.
- Ambulatory Surgical Centers:Outpatient facilities performing low-complexity procedures with limited transfusion support needs.
- Specialty Clinics:Nephrology, neurology, and hematology outpatient settings performing therapeutic apheresis procedures.
Procurement scale favors Blood Banks; margin expansion targets Diagnostic Laboratories.
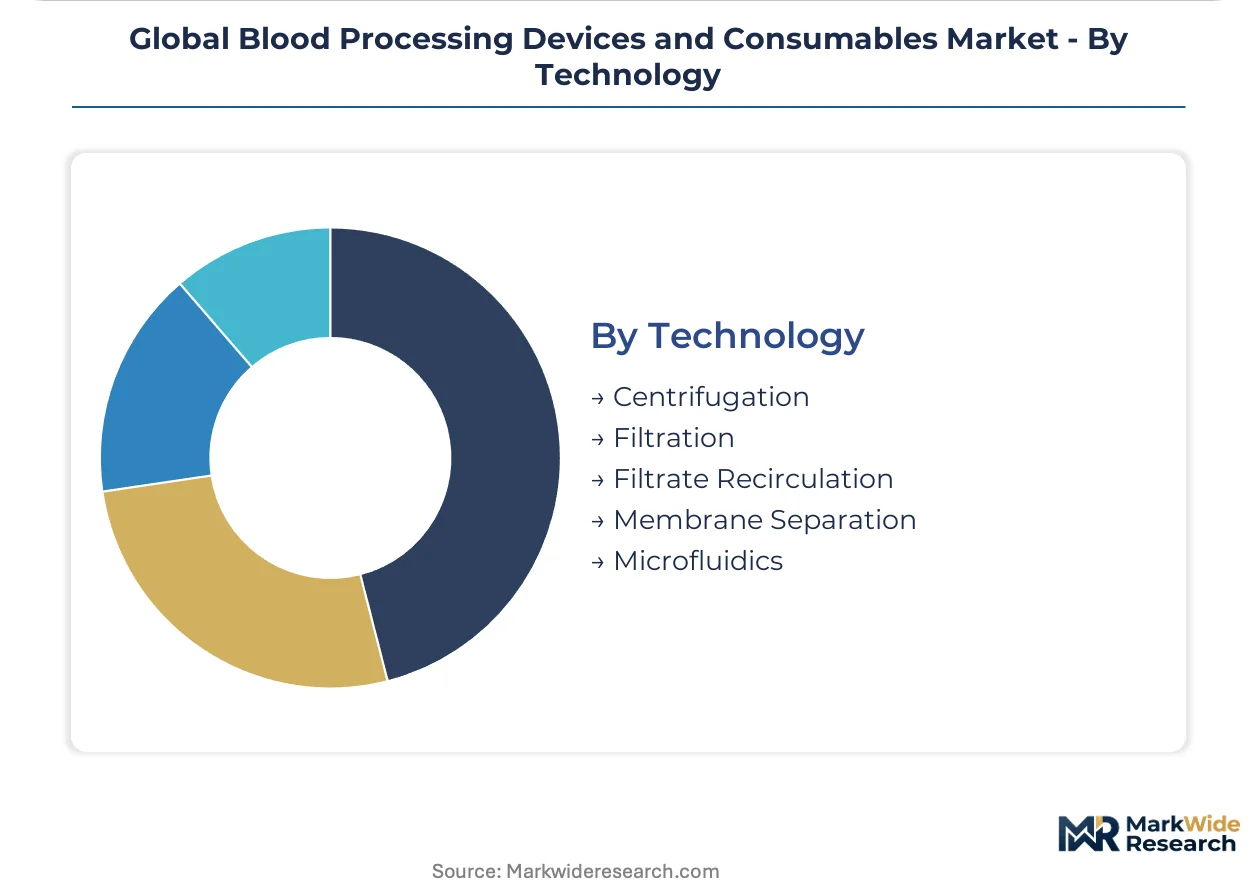
Technology:
Maturity gradient separates established centrifugation infrastructure from emerging membrane and microfluidic platforms competing on processing speed and component purity.
- Membrane Separation:Selective permeability barriers separate plasma and cellular components without centrifugal force, reducing treatment duration and enabling compact device footprints. Academic medical centers in Germany and Japan are displacing centrifugation in outpatient therapeutic apheresis protocols.
- Centrifugation:Density-gradient separation at controlled rotational speeds remains the backbone of blood component manufacturing and most transfusion medicine workflows.
- Filtration:Leukoreduction and pathogen reduction filters process blood components through adsorptive and size-exclusion media.
- Filtrate Recirculation:Closed-loop processing architectures minimize fluid waste and cold chain handling steps in component preparation.
- Microfluidics:Lab-on-chip architectures for point-of-care hematology diagnostics and research-scale cell separation applications.
Installed base concentrates in Centrifugation; technology transition favors Membrane Separation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American blood processing innovation through its concentration of cell therapy manufacturing infrastructure and academic medical center procurement networks. The metropolitan corridor integrates automated collection systems with hospital information architectures across New England health systems. FDA validation requirements for blood establishment computer systems drive technology adoption patterns throughout the region.
United States
Catholic health systems and regional hospital alliances consolidate transfusion services under centralized laboratory operations. FDA blood establishment computer system guidance mandates software-integrated platforms with electronic traceability capabilities. The Boston-Cambridge biocluster deploys membrane separation technology for therapeutic apheresis in neurology and hematology outpatient settings.
Germany
Academic medical centers in Munich and Heidelberg deploy membrane-based plasma exchange systems for autoimmune and neurological indications. EU MDR technical documentation requirements extend validation timelines for blood processing equipment entering the European market. The Rhine-Main biopharma corridor integrates leukoreduction filtration with pathogen reduction chemistry in component manufacturing workflows.
Japan
Tokyo and Osaka metropolitan hospitals standardize automated blood collection platforms to manage aging-population transfusion demand. PMDA quality system regulations align with international harmonization initiatives for medical device software validation. The Kansai medical device manufacturing belt supplies membrane fabrication expertise for therapeutic apheresis equipment programs.
Singapore
Biocluster facilities in Tuas and one-north develop closed-system blood component separation for CAR-T and gene therapy manufacturing. Health Sciences Authority regulatory frameworks accommodate cellular therapy processing equipment under accelerated review pathways. The Biopolis research corridor attracts contract development organizations requiring validated automated collection infrastructure.
South Korea
Seoul-based hematology centers expand therapeutic apheresis protocols for neuromyelitis optica and myasthenia gravis treatment. MFDS medical device registration requirements emphasize clinical evidence for software-driven separation systems. The Songdo biohealth cluster concentrates cellular therapy manufacturing demand for premium blood processing equipment.
Global Blood Processing Devices and Consumables Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and software validation capabilities. Automated blood collection systems concentrate procurement decisions among integrated health networks, compressing vendor margins while elevating platforms that satisfy FDA validation requirements. Three archetypes dominate: end-to-end automation specialists, scale-driven manual collection set manufacturers, and membrane technology innovators. Consolidation through strategic partnerships and portfolio diversification into cellular therapy infrastructure represent the dominant competitive vectors.
Within the automation tier, Haemonetics Corporation and Terumo Corporation exemplify divergent technology strategies. Haemonetics anchors hospital blood management programs through integrated software-traceability platforms. Terumo occupies a position emphasizing membrane separation architectures for therapeutic apheresis applications. BD represents the scale-driven archetype, competing through manufacturing volume in manual collection sets and coagulation diagnostics. Abbott Laboratories and bioMérieux SA sit within the diagnostics-integrated tier, leveraging point-of-care testing expansion in cardiac and trauma settings.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| BD |
| Abbott Laboratories |
| bioMérieux SA |
| Bio-Rad Laboratories |
| Terumo Corporation |
| F. Hoffmann-La Roche Ltd |
| Danaher |
| Grifols |
| Others |
Supply & Pricing Matrix
Centralized laboratory procurement in United States integrated health networks is compressing vendor margins and forcing unbundling of equipment from consumable contracts, which pushes suppliers toward outcome-based pricing models anchored to throughput guarantees rather than unit volumes.
Pricing Analysis
Outcome-based pricing tied to transfusion workflow efficiency anchors vendor contracts in United States hospital systems. Three-tier pricing structure across premium software-integrated platforms, standard automated systems, and economy manual collection sets separates buyers by FDA validation requirements and electronic traceability capabilities. Cost compression in manual blood collection sets intensifies because procurement consolidators in Brazil and India prioritize unit economics over performance differentiation. Blood banks with centralized laboratory authority exhibit least price sensitivity due to total cost of ownership frameworks, while ambulatory surgical centers and resource-limited settings in emerging markets drive hardest unit-cost negotiations.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States operate hub-and-spoke patterns for membrane filtration media and sterile connector components. Manufacturing concentration for precision centrifuge rotors and blood bag films rests on facilities in Japan, Germany, and the United States, with secondary sourcing for anticoagulant solutions drawing from Switzerland and Singapore. Single-source vulnerability in fractionation-grade plasma collection creates structural exposure for immunoglobulin and albumin input costs. Distribution runs through GPO-contracted channels for hospital systems and direct-to-blood-bank arrangements for national health service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood processing market sits in a technology-transition phase where membrane separation architectures displace legacy centrifugation in therapeutic apheresis workflows, creating asymmetric opportunity windows across stakeholder positions.
For Market Incumbents: Anticipate membrane technology substitution in outpatient neurology and hematology protocols by securing bioengineer talent pools in Japan and Switzerland for sterile connector design. Defend hospital blood management program anchors through backward integration into software validation services that satisfy FDA blood establishment computer system mandates. Prioritize certification investment for EU MDR technical documentation to maintain European market access against extending validation timelines. For New Entrants and Emerging Players: FDA guidance on blood establishment computer systems in the United States opens a window for software-native platforms that embed electronic traceability without legacy information system integration burdens. Target cellular therapy manufacturing infrastructure in Singapore and South Korea bioclusters where closed-system separation demand outpaces established supply. Pursue hospital system partnership go-to-market angles that bundle equipment validation with laboratory information management architecture integration services. For Investors and Strategic Acquirers: The window for entry favors membrane fabrication specialists with therapeutic apheresis device programs and validated sterile connector platforms. Long-term viability hinges on positioning for CAR-T and gene therapy manufacturing infrastructure buildout across Asia-Pacific bioclusters. Watch leukoreduction filter technology convergence with pathogen reduction chemistry as inflection indicator for single-step processing platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Software validation for blood establishment computer systems satisfies hospital procurement mandates in United States integrated networks. |
| CE Marking Pathway | EU MDR technical documentation compliance preserves European market access against stricter clinical evidence requirements. |
| Hospital System Partnership | Centralized laboratory procurement consolidation favors vendors with total cost of ownership frameworks and information system integration capabilities. |
| Software Companion Development | Electronic traceability platforms differentiate automated collection systems from commodity manual collection sets in transfusion service workflows. |
| Reimbursement Strategy | Perioperative coagulation monitoring protocols in cardiac catheterization labs and trauma centers expand point-of-care test kit pull-through economics. |
Research Methodology
Multi-period observation of blood bank procurement consolidation patterns, therapeutic apheresis protocol adoption rates, and regulatory validation timeline extensions anchored the trend analysis, supplemented by interviews with hospital purchasing committee directors, biomedical engineers specializing in transfusion medicine, GPO contracts managers, and blood establishment quality assurance leads. Secondary validation drew from FDA guidance documents, EU MDR technical documentation requirements, hospital procurement databases, and CMS Medicare transfusion service reimbursement data. Bottom-up equipment shipment tracking and top-down health system capital expenditure analysis enabled triangulation across market sizing approaches.
Segment-weighting across product type, application setting, end-user procurement authority, and technology maturity gradient informed the analytical framework throughout the projection horizon. Modeled dimensions included automated versus manual collection platforms, therapeutic apheresis versus cell salvage applications, blood bank versus diagnostic laboratory end users, and membrane separation versus centrifugation technology bases. CAGRs were derived from equipment replacement cycle analysis and consumable pull-through coefficients tied to installed base expansion. Forecast inputs incorporated FDA software validation mandate compliance timelines and EU MDR notified body audit capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for membrane separation in plasma exchange would alter the outlook if centrifugation manufacturers accelerate compact system development for outpatient settings. Forecasts reflect documented assumptions regarding health network consolidation velocity and regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Devices Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Global Medical Drones Market
Medical Devices
Bone Allografts Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Flow Diverters Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Patellar Implant Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Global Endotracheal Tubes Market