
 Anti-Creasing Agent Market | 2026-2036
Anti-Creasing Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Creasing Agent Market Analysis
Silicone-based softeners is shifting toward polyurethane-derivative anti-creasing systems in premium textile finishing as mills pursue durable press performance without formaldehyde release. Fineotex Chemical Limited leverages backward integration into specialty polymer intermediates to secure feedstock consistency across South Asian textile belts. Sarex Chemicals anchors its position through concentrated R&D spending on low-temperature curing formulations that reduce energy intensity for denim processors. Zhuhai Lingxiang Chemical Co. dominates export channels into Southeast Asian garment hubs through direct mill relationships and technical service teams stationed in Ho Chi Minh City and Dhaka.
An anti-creasing agent is a surface-active chemical formulation, typically comprising modified polyurethanes, glyoxal resins, or silicone elastomers, applied during textile finishing to impart wrinkle recovery and dimensional stability to cellulosic and blended fabrics through crosslinking or film-forming mechanisms. Synthetic agents command the largest volume share due to cost efficiency and established supply chains, though biodegradable agents represent the fastest-expanding category as ZDHC MRSL conformance becomes a procurement gate for European apparel brands. Liquid formulations lead in application share because of ease of dosing in continuous pad-dry-cure operations, while powder variants retain niche positions in small-batch textile processing units with limited storage infrastructure.
REACH restrictions on formaldehyde-releasing agents and the EU Green Deal chemical sustainability targets compel European formulators to eliminate N-methylol-based chemistries, while China's MEE enforcement of wastewater discharge standards raises compliance costs for domestic producers. India's BIS certification requirements for textile auxiliaries and the PLI scheme for man-made fiber apparel create dual pressure on chemical suppliers to meet quality benchmarks while scaling capacity. Stakeholders must monitor ZDHC conformance timelines and regional carbon border adjustments to align product portfolios with evolving procurement criteria.
Market Dynamics
Formulation chemistry is pivoting away from formaldehyde-releasing systems as ZDHC MRSL conformance becomes a non-negotiable procurement filter for European apparel brands sourcing from South Asian textile belts.
Growth Catalysts
- Denim Processor Energy Mandates:Low-temperature curing formulations cut thermal load by 30-40% in continuous finishing lines, accelerating replacement of conventional high-bake systems.
- REACH Phase-Down of N-Methylol Agents:European formulators face compelled substitution timelines, opening procurement windows for polyurethane-derivative and glyoxal resin alternatives.
- Vietnam Garment Export Volume:Ho Chi Minh City-based finishing houses sustain chemical line investments as export quotas to EU and US markets expand.
Market Restraints
- Specialty Polymer Feedstock Concentration:Isocyanate and silicone intermediate supply clusters in East China, exposing South Asian formulators to shipping cost volatility and inventory squeeze.
- Biodegradable Agent Performance Gap:Cellulosic crosslinking efficiency of plant-derived alternatives trails synthetic benchmarks by 15-20% in industrial wash durability tests.
- China MEE Wewater Enforcement:Domestic producers absorb compliance cost step-ups for COD and AOX discharge limits, compressing margin structures for export-oriented chemical houses.
Strategic Opportunities
- India PLI Scheme for Man-Made Fiber Apparel:BIS-certified auxiliary suppliers capture capacity expansion-linked demand from polyester-cotton blend processors in Tamil Nadu and Gujarat.
- Technical Service Station Models:Direct mill embedding in Dhaka and Jakarta bypasses distributor markups while capturing formulation customization revenue.
- EU Green Deal Chemical Sustainability Targets:Carbon border adjustment preparedness creates first-mover advantage for bio-based agent portfolios with verified lifecycle data.
Industry Challenges
- Formulation Chemist Scarcity:Polyurethane synthesis expertise concentrates in legacy industrial chemical centers, forcing textile auxiliary houses to compete for talent with coatings and adhesives sectors.
- ZDHC Conformance Timeline Compression:Certification audit backlogs delay supplier qualification for Q4 sourcing windows, risking order forfeiture to pre-approved competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Creasing Agent Market |
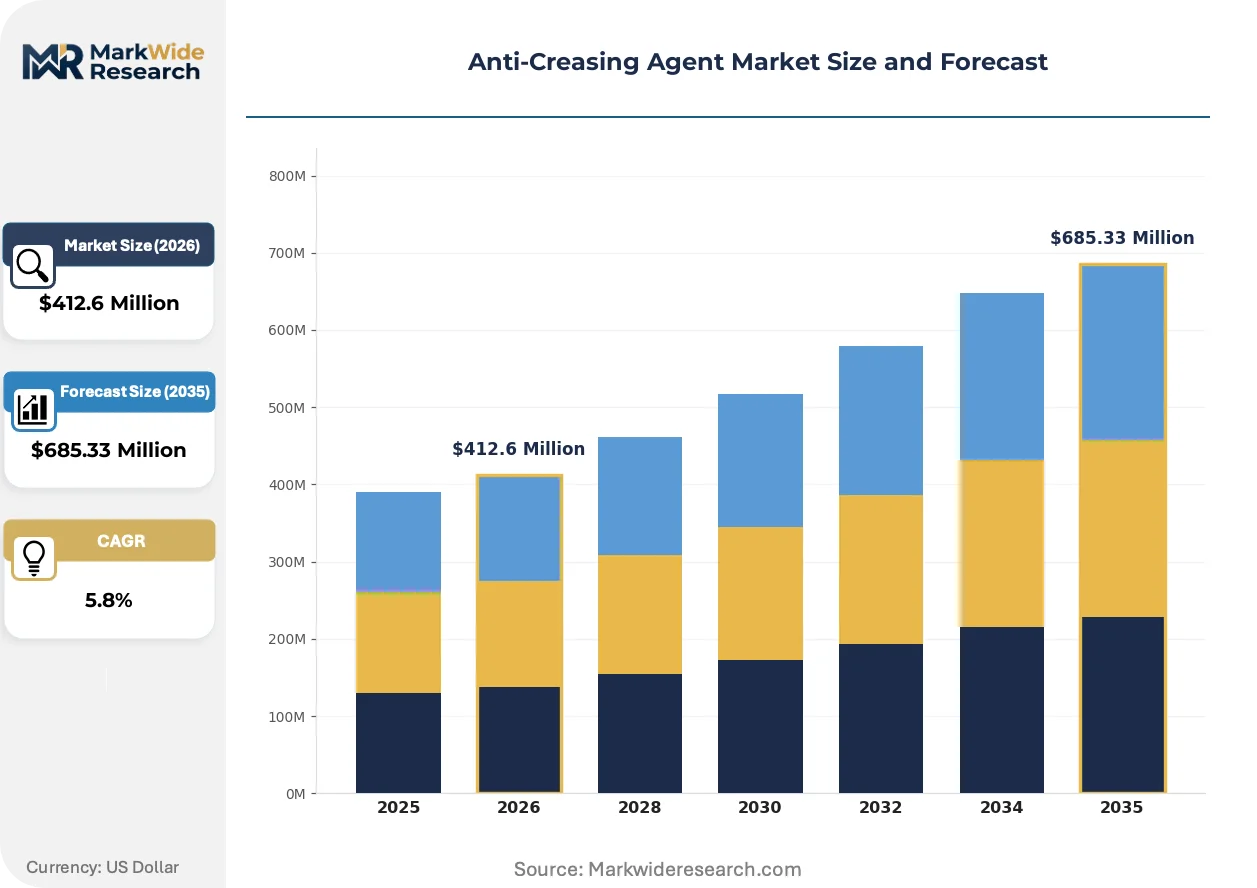
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Agents, Natural Agents, Biodegradable Agents, Organic Polymers Application: Textile Industry, Leather Processing, Paper Industry, Coating Form: Liquid, Powder, Granules, Emulsion End User: Manufacturers, Suppliers, Retailers, Distributors |
| Companies Covered | Fineotex Chemical Limited, Golden Technologia, Kolorjet Chemicals Pvt Ltd, Prochem Ltd, Sarex Chemicals, Siam Pro Dyechem Group, Kunal Organics Pvt Ltd, Neochem Technologies, Zhuhai Lingxiang Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Creasing Agent Market Emerging Trajectories
Active chemistry selection is rewriting competitive positioning as mills abandon legacy systems before regulatory deadlines force compliance costs. Three convergent developments are compressing formulation cycles and redrawing supplier relationships.
Polyurethane-derivative anti-creasing systems are rewriting durability benchmarks in premium textile finishing. European luxury apparel mills specify these agents for wrinkle recovery ratings above 3.5 AATCC Test Method 124 scores. The technology is compressing silicone softener incumbents into commodity positioning as performance differentiation shifts to crosslink density control.
REACH restrictions on formaldehyde-releasing agents are eliminating N-methylol chemistry from EU-facing supply chains. ECHA substance evaluation timelines have accelerated substitution investments among German and Italian formulators. Cellulosic fabric finishers serving Zara and H&M procurement pools now require third-party MRSL testing documentation as a standard order condition.
Buyer concentration among vertically integrated garment exporters is compressing distributor layers in Southeast Asian supply chains. Direct technical service relationships now dominate Ho Chi Minh City and Dhaka procurement patterns. Mills in these clusters prioritize formulation partners with on-site application labs over catalog chemical vendors lacking local troubleshooting capability.
Anti-Creasing Agent Market Segmentation
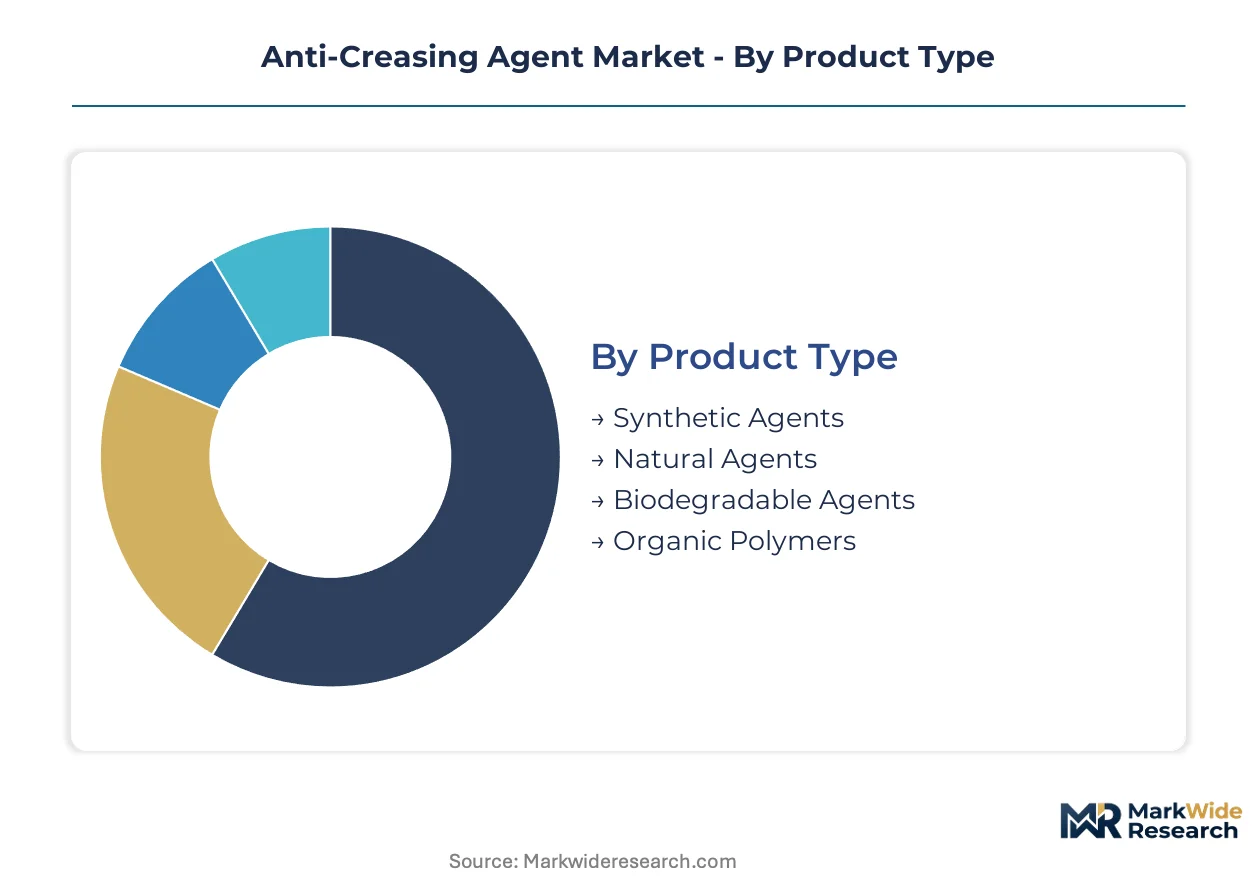
Anti-creasing agent procurement patterns diverge sharply across formulation chemistry, physical form, and downstream application. Mills optimize finishing line configurations by matching agent specifications to fabric substrate requirements and curing equipment constraints.
Product Type:
Replacement cycles accelerate as REACH deadlines force mills to abandon legacy formaldehyde-releasing systems before compliance costs escalate.
- Synthetic Agents:Modified polyurethanes and glyoxal resin formulations deliver crosslink density control for wrinkle recovery ratings above 3.5 AATCC scores. Denim processors in Vietnam specify these agents for durable press performance in EU-bound export lots.
- Biodegradable Agents:Plant-derived chemistries achieve ZDHC MRSL conformance for European apparel brand procurement gates. Cellulosic crosslinking efficiency trails synthetic benchmarks by 15-20% in industrial wash durability, constraining adoption to premium positioning.
- Natural Agents:Starch and protein-based formulations serve niche organic certification requirements in home textiles.
- Organic Polymers:Specialty carbohydrate derivatives target small-batch processors seeking low-temperature curing compatibility.
Volume placements concentrate in Synthetic Agents; the faster expansion belongs to Biodegradable Agents.
Application:
End-use profitability tiers separate commodity processors from technical finishers capable of formulation customization.
- Textile Industry:Continuous pad-dry-cure operations in cotton and blended fabric finishing command the largest chemical offtake. Apparel manufacturers in Bangladesh and India specify liquid formulations for energy-efficient low-temperature curing systems.
- Leather Processing:Crust leather finishing requires elastomeric film-forming agents for grain retention and softness preservation. Italian tanneries serving luxury footwear brands specify polyurethane-derivative systems with specialized hand modifiers.
- Paper Industry:Specialty coatings for packaging and label stock utilize anti-creasing chemistries for fold endurance improvement.
- Coating:Technical textile laminates and industrial fabric treatments employ crosslinking agents for dimensional stability under mechanical stress.
Revenue concentration sits with Textile Industry applications; Leather Processing commands the highest margin per kilogram.
Form:
Physical state selection hinges on dosing equipment compatibility and storage infrastructure constraints across mill scale tiers.
- Liquid:Ease of automated dosing in continuous finishing lines makes this the dominant application format. Large-scale processors in Ho Chi Minh City and Dhaka prefer liquid delivery for real-time concentration adjustment.
- Powder:Extended shelf stability and reduced shipping weight appeal to small-batch textile units with limited climate-controlled storage. Regional distributors in South Asia stock powder variants for remote mill locations.
- Granules:Controlled dissolution rates suit batch processing operations with intermittent production schedules.
- Emulsion:Silicone and hybrid polymer emulsions provide combined softening and anti-creasing functionality for single-bath finishing.
Liquid formulations capture the highest volume share; Powder variants retain defensive positioning in fragmented supply territories.
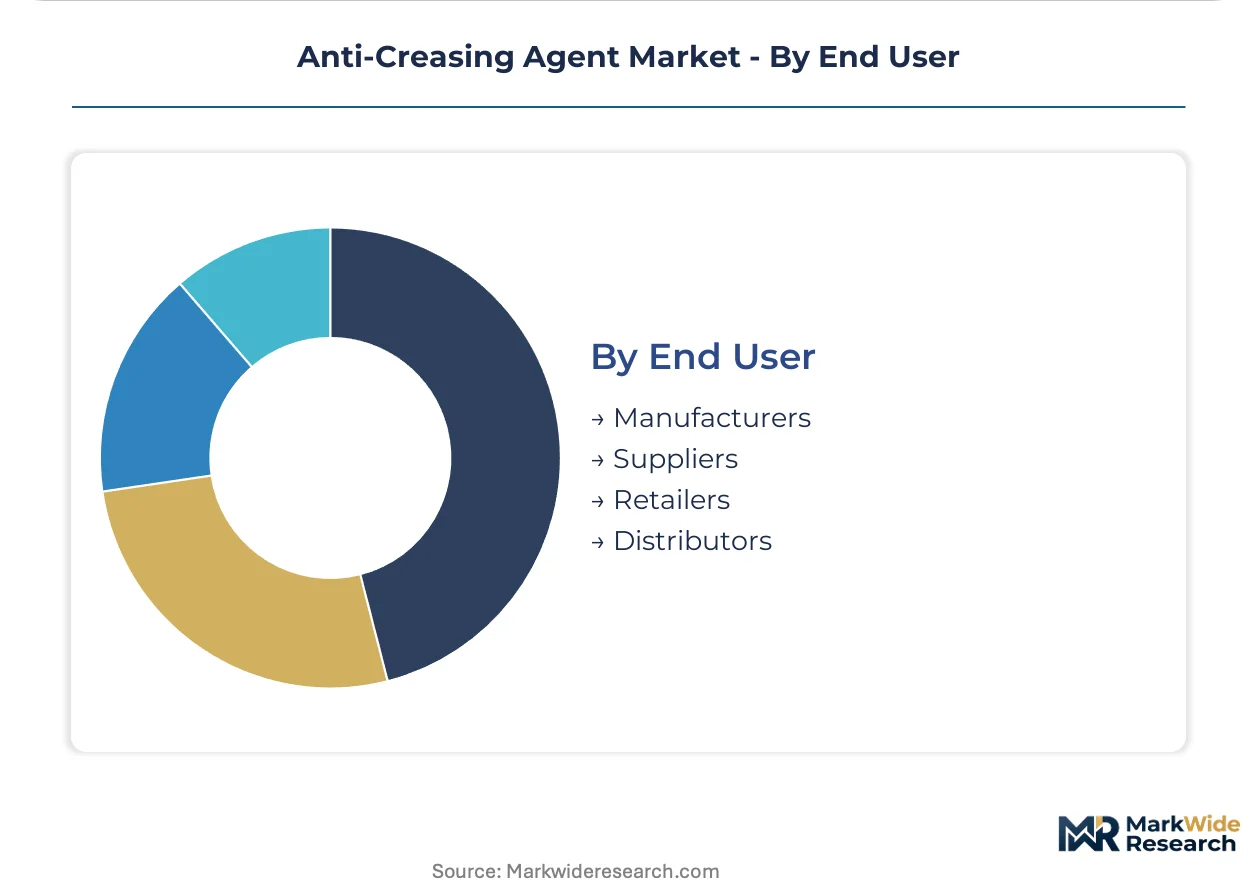
End User:
Channel structure compression favors direct technical service relationships over traditional distributor intermediaries.
- Manufacturers:Vertically integrated textile mills with captive finishing capacity purchase bulk formulations under annual supply agreements. Tamil Nadu and Gujarat polyester-cotton blend processors leverage BIS certification requirements to qualify preferred chemical partners.
- Suppliers:Independent finishing houses serving garment export contractors require flexible procurement terms and rapid technical troubleshooting support.
- Retailers:Private-label apparel brands specify finishing agent conformance as a supplier qualification condition.
- Distributors:Regional chemical traders retain relevance in second-tier textile clusters lacking direct mill relationships.
Procurement authority concentrates in Manufacturers; Suppliers represent the most contested account segment for technical service investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Garment export volumes in Bangladesh, Vietnam, and India concentrate chemical finishing line investments. European REACH deadlines and China's MEE wastewater standards reshape procurement patterns across these manufacturing belts.
China
Isocyanate and silicone intermediate production clusters in Jiangsu and Zhejiang provinces supply South Asian formulators. MEE enforcement of COD and AOX discharge limits raises compliance costs for export-oriented chemical houses in Shaoxing and Nantong textile chemical zones.
India
Tamil Nadu and Gujarat polyester-cotton blend processors drive BIS-certified auxiliary demand under the PLI scheme for man-made fiber apparel. Mumbai-headquartered formulators leverage backward integration into specialty polymer intermediates to secure feedstock consistency.
Vietnam
Ho Chi Minh City-based finishing houses sustain chemical line investments as EU and US export quotas expand. Direct technical service teams from regional suppliers bypass distributor markups while capturing formulation customization revenue.
Bangladesh
Dhaka garment export contractors prioritize finishing partners with on-site application labs over catalog chemical vendors. ZDHC MRSL conformance documentation has become standard for mills supplying H&M and Zara procurement pools.
Germany
ECHA substance evaluation timelines accelerate substitution investments among formulators serving luxury apparel mills. Italian and German finishers specify polyurethane-derivative systems for wrinkle recovery ratings above 3.5 AATCC scores.
Anti-Creasing Agent Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation houses commanding premium positioning in technical finishing while commodity distributors serve fragmented small-batch processors. The vendor base organizes into three archetypes: integrated polymer producers with captive intermediate supply, regional formulators with embedded technical service teams, and trading houses with distributor networks. Capacity expansion and direct mill embedding represent the dominant competitive moves as procurement authority concentrates among vertically integrated garment exporters.
Among South Asia-based specialists, Fineotex Chemical Limited and Sarex Chemicals exemplify the technical service archetype through concentrated R&D positioning. Zhuhai Lingxiang Chemical Co. anchors the export-channel vector with direct mill relationships in Southeast Asian garment hubs. These three represent distinct pathways for securing procurement relationships as distributor layers compress.
| Leading Market Players |
|---|
| Fineotex Chemical Limited |
| Golden Technologia |
| Kolorjet Chemicals Pvt Ltd |
| Prochem Ltd |
| Sarex Chemicals |
| Siam Pro Dyechem Group |
| Kunal Organics Pvt Ltd |
| Neochem Technologies |
| Zhuhai Lingxiang Chemical Co. |
| Others |
Supply Flow & Price Mechanics
Isocyanate feedstock indices in East China cascade through South Asian formulation houses into three-tier pricing stratification across premium polyurethane-derivatives, standard glyoxal resins, and economy-grade silicone softeners. Procurement managers in Ho Chi Minh City and Dhaka absorb shipping cost volatility while negotiating annual offtake contracts that lock in margin protection against intermediate price spikes.
Pricing Analysis
Volume placements concentrate in standard-grade glyoxal resin formulations, while premium polyurethane-derivative agents command 40-60% margin premiums from European luxury apparel mills. Price differentiation hinges on ZDHC MRSL certification tier and low-temperature curing performance grade. Cost compression in economy silicone tiers intensifies as Chinese MEE wastewater compliance raises domestic producer break-even points. Small-batch processors in fragmented South Asian textile clusters exhibit highest price sensitivity, whereas vertically integrated garment exporters in Vietnam prioritize technical service bundling over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with isocyanate intermediate production clusters in Jiangsu and Zhejiang provinces, exposing South Asian formulators to inventory squeeze during shipping disruptions. Specialty polymer feedstock draws from China, Germany, and Japan, with silicone elastomer precursors anchored in East Asian chemical zones. Tariff exposure on cross-border intermediate shipments compounds working capital pressure for Mumbai and Dhaka formulation houses. Distribution runs through direct technical service teams embedded in Ho Chi Minh City and Dhaka, bypassing traditional distributor markups while capturing formulation customization revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-creasing agent procurement is consolidating into a vertical-integration race, with formulators pursuing backward control over specialty polymer intermediates to secure feedstock consistency across South Asian textile belts.
For Market Incumbents: Deploy captive intermediate production to lock in margin structures against isocyanate price volatility from East China supply clusters. Fineotex Chemical Limited's backward integration into specialty polymers exemplifies this defensive posture. Incumbents must simultaneously accelerate ZDHC MRSL certification timelines to preempt audit backlogs that risk Q4 sourcing window forfeiture to pre-approved competitors. Capacity addition in Tamil Nadu and Gujarat captures PLI scheme-linked demand from polyester-cotton blend processors. For New Entrants and Emerging Players: Technical service partnerships with independent finishing houses in second-tier Bangladeshi textile clusters offer the most penetrable entry vector. New entrants should target small-batch denim processors in Indonesia seeking low-temperature curing compatibility without formaldehyde-releasing chemistry. A formulation-customization revenue model anchored in on-site application labs bypasses entrenched distributor relationships while building mill dependency through troubleshooting responsiveness. For Investors and Strategic Acquirers: Distressed-cycle entries favor BIS-certified regional formulators in India facing dual pressure from quality benchmarks and capacity scaling requirements under man-made fiber apparel incentives. Long-term viability hinges on carbon border adjustment preparedness as EU Green Deal chemical sustainability targets harden procurement criteria. Watch ZDHC conformance timeline compression as the inflection signal—certification audit backlogs that delay supplier qualification create acquisition windows for pre-approved assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Intermediates | Fineotex Chemical Limited secures feedstock consistency across South Asian textile belts through captive isocyanate supply. |
| Low-Temperature Curing Formulation R&D | Sarex Chemicals reduces energy intensity for denim processors facing thermal load mandates in Vietnam. |
| Direct Technical Service Embedding | Zhuhai Lingxiang Chemical Co. stations application labs in Ho Chi Minh City and Dhaka to bypass distributor markups. |
| ZDHC MRSL Certification Acceleration | European apparel brands now require third-party testing documentation as standard order condition for H&M and Zara procurement pools. |
| Carbon Border Adjustment Preparedness | Bio-based agent portfolios with verified lifecycle data capture first-mover advantage under EU Green Deal chemical sustainability targets. |
Methodological Framework
Multi-period observation of formulation chemistry substitution rates, REACH compliance timelines, and garment export volume trajectories anchored the trend analysis, supplemented by interviews with textile finishing plant managers, chemical procurement leads at vertically integrated garment exporters, distribution channel partners in South Asia, and technical R&D directors at specialty polymer houses. Secondary validation drew from ECHA substance evaluation databases, ZDHC MRSL conformance registries, Indian BIS certification records, China MEE wastewater discharge filings, and customs trade data on isocyanate intermediate flows. Bottom-up segment sizing triangulated against top-down chemical auxiliary consumption estimates.
Input-output matrices modeled crosslinking agent demand across formulation chemistry tiers, physical form factors, and end-use application intensity through the projection horizon. Segmentation dimensions spanned synthetic versus biodegradable chemistry grade, liquid versus powder delivery format, and textile versus leather processing end-use. CAGRs derived from elasticity-adjusted demand curves incorporating energy mandate compliance rates and regulatory substitution timelines. Industry-specific forecast inputs included denim processor low-temperature curing adoption curves and PLI scheme capacity expansion schedules for man-made fiber apparel.
Caveats apply where ECHA substance evaluation acceleration, China MEE enforcement intensity, or ZDHC audit backlog resolution could materially shift the outlook for formulation substitution timelines. Forecasts embed assumptions about regional carbon border adjustment implementation sequencing and intermediate shipping cost normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Phthalate Plasticizer Market
Additives
Chelating Agents Market
Additives
Anti-Slip Additives Market
Additives
LAMEA Driveline Additives Market
Additives
North America Paints and Coatings Additives Market
Additives
Butyrate Additives Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Antiblock Agents Market
Additives
Fluoropolymer Additives Market
Additives
Plasticizer Alcohols Market
Additives
Lactic Acid Ester Market
Additives
Feedstuff Additives Market
Additives
Coating Additives Market
Additives
Competitive Inhibitors Market
Additives
Gluconic Acid and Derivatives Market