
 Oilfield Drilling Fluid Additive Market | 2026-2036
Oilfield Drilling Fluid Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Drilling Fluid Additive Market Analytics
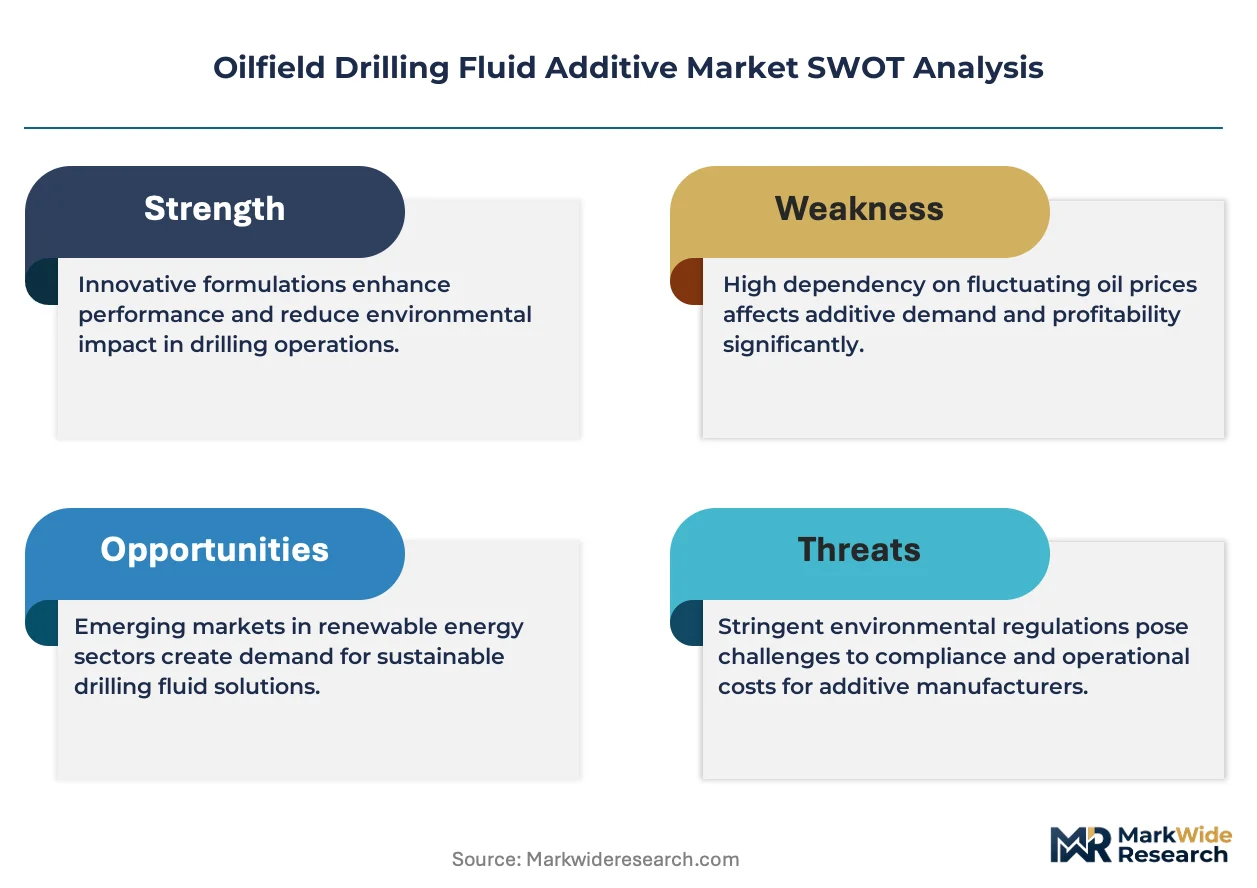
National oil companies are unwinding their historical preference for bundled service contracts, and independent operators now specify additives separately in tender documents. Schlumberger Limited leverages its integrated drilling systems to maintain captive additive volumes in deepwater markets. Baker Hughes Company differentiates through bio-based fluid chemistry platforms that reduce environmental compliance costs. Halliburton Company anchors its position in the Middle East through localized manufacturing of weighting agents and viscosifiers.
Oilfield drilling fluid additives comprise specialty chemicals blended into drilling muds to control viscosity, density, filtration properties, and wellbore stability, typically formulated as liquid concentrates or dry powder blends with active concentrations ranging from five to ninety-five percent depending on function. These additives prevent differential sticking, minimize formation damage, and maintain cuttings suspension during directional and extended-reach drilling operations. Rheology modifiers command the largest product category share due to universal deployment across all mud systems, while biocides represent the fastest-expanding segment as operators combat sulfate-reducing bacteria in high-temperature shale formations. Fluid loss control agents concentrate margin pools in offshore applications where regulatory limits on synthetic-based mud discharge create premium pricing for polymeric alternatives.
The US EPA governs offshore discharge permits under NPDES frameworks, while REACH in Europe restricts certain chrome lignosulfonate chemistries, and China's MEE enforces stricter water-quality standards for onshore drilling waste pits. These regulatory layers are fragmenting formulation standards and raising compliance costs for additive suppliers serving multiple jurisdictions. Stakeholders must monitor how divergent biodegradability thresholds reshape product registration requirements and regional sourcing strategies.
Market Dynamics
The fragmentation of bundled service contracts into discrete additive procurement is redrawing competitive boundaries. National oil companies now unbundle drilling chemicals from integrated service packages, forcing additive suppliers to build direct specification relationships with operators rather than flowing through major service company channels.
Growth Catalysts
- Unconventional well complexity:Extended-reach lateral sections in shale formations require specialized rheology modifiers to maintain cuttings transport over 15,000-foot laterals. Operators in the Permian Basin and Eagle Ford specify these additives separately in tender documents.
- EPA NPDES discharge revisions:Updated offshore discharge standards accelerate substitution of synthetic-based muds with biodegradable alternatives. Fluid loss control polymers meeting enhanced biodegradability thresholds command premium positioning in Gulf of Mexico shelf operations.
- Barite supply diversification:Alternative weighting agents derived from micronized ilmenite and hematite reduce dependency on Chinese barite imports. Domestic sourcing of these minerals is reshaping formulation economics for independent operators.
Market Restraints
- Base fluid cost volatility:Mineral oil and synthetic ester prices track crude oil benchmarks, compressing additive supplier margins when feedstock costs spike without corresponding contract escalation clauses.
- Chrome lignosulfonate phase-outs:ECHA REACH restrictions on chromium-containing chemistries force reformulation of time-tested deflocculants, requiring multi-year product registration cycles in European waters.
- Biocide resistance proliferation:Sulfate-reducing bacteria in high-temperature shale formations develop tolerance to glutaraldehyde and THPS chemistries, necessitating rotation protocols that complicate inventory management.
Strategic Opportunities
- Geothermal drilling crossover:High-temperature stable polymers developed for oilfield applications transfer directly to geothermal well construction, opening specification relationships with renewable energy developers in Nevada and Utah.
- Real-time monitoring integration:Additive dosing systems linked to automated mud property sensors enable just-in-time chemical delivery, reducing surface inventory requirements and waste generation.
- CCUS well construction:Carbon capture injection wells demand specialized cement spacers and fluid systems compatible with CO2-rich environments, creating specification windows for corrosion-resistant additive packages.
Industry Challenges
- Formulation chemist scarcity:Experienced mud engineers with deep knowledge of colloidal chemistry and formation damage mechanisms are retiring faster than universities produce replacements, constraining supplier technical service capacity.
- Multi-jurisdictional registration:Additive suppliers must maintain separate toxicity data packages for EPA, ECHA, and China's MEE, with divergent biodegradability test protocols extending product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Drilling Fluid Additive Market |
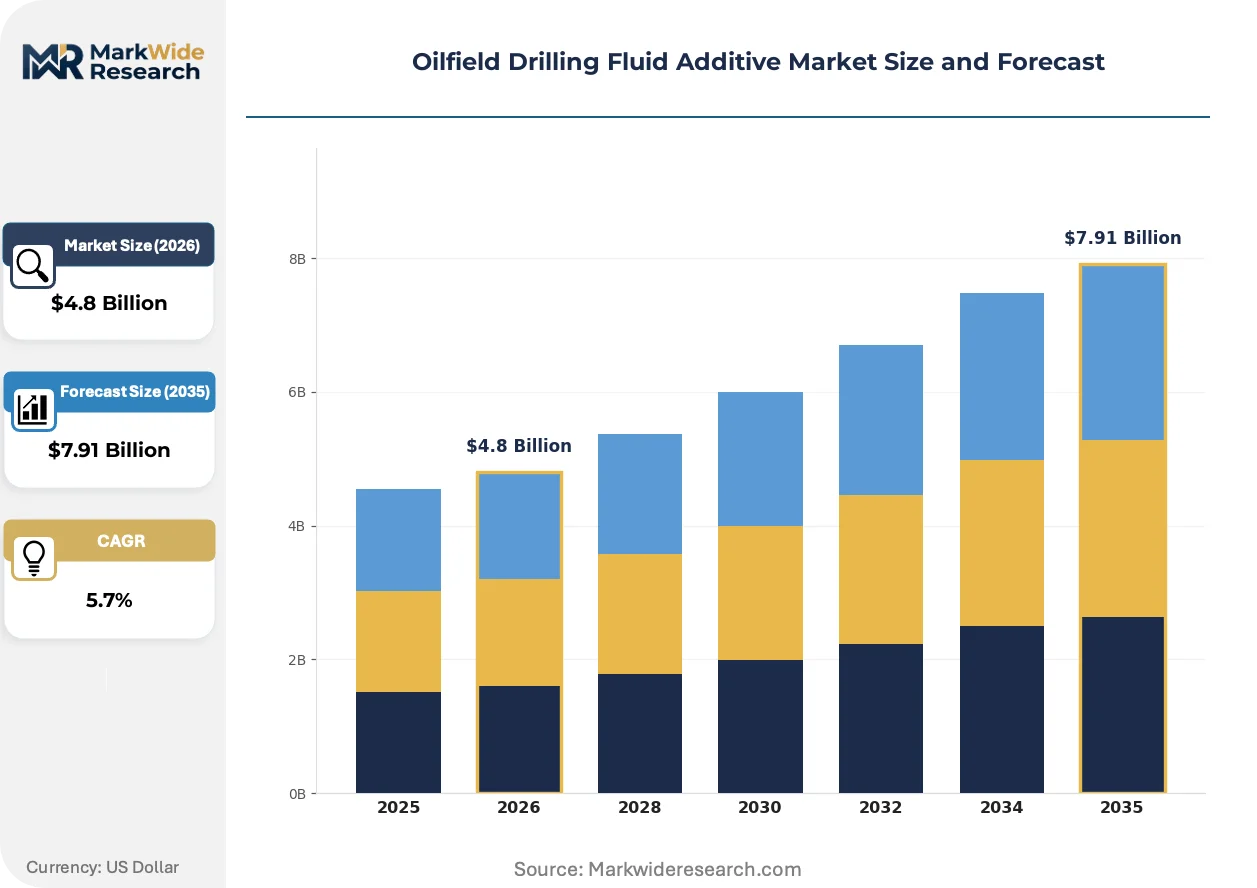
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rheology Modifiers, Fluid Loss Control Agents, Biocides, Extractants Application: Onshore Operations, Offshore Operations, Exploration Activities, Well Completion End User: Independent Operators, National Oil Companies, Oilfield Service Companies, Drilling Contractors Functionality: Emulsifiers, Viscosifiers, Weighting Agents, Clay Control |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton Company, Dow, BASF SE, Innospec Inc., Tetra Technologies Inc., Newpark Resources Inc., Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Drilling Fluid Additive Market Evolving Landscape
Digitalization of drilling fluid management is converging with bio-based chemistry advances to compress traditional supply relationships. These forces are reconfiguring how additives are specified, delivered, and consumed across onshore and offshore operations.
Polyanionic cellulose (PAC) derivatives engineered for thermal stability beyond 400°F are supplanting conventional starch-based fluid loss additives in high-pressure high-temperature wells. Operators in the Gulf of Mexico deepwater segment specify these polymers for wells exceeding 30,000 feet measured depth. The substitution is compressing demand for traditional starch chemistries while elevating technical service requirements for polymer suppliers.
REACH restrictions on microplastic-containing additives are forcing reformulation of synthetic-based mud emulsifiers used in North Sea operations. ECHA's 2023 restriction proposal targets polymeric materials with particle dimensions below five millimeters, directly affecting internal phase stabilizers. Suppliers are responding with bio-ester alternatives that meet OECD 306 biodegradability thresholds but require modified mixing equipment on offshore platforms.
Spot purchasing through digital marketplaces is fragmenting traditional annual volume commitments between operators and additive suppliers. Independent Permian Basin producers now source rheology modifiers through commodity trading platforms rather than negotiated frame contracts. This channel shift is most visible among private equity-backed operators with less than 50,000 barrels per day production, who prioritize working capital flexibility over volume discounts.
Oilfield Drilling Fluid Additive Market Segmentation
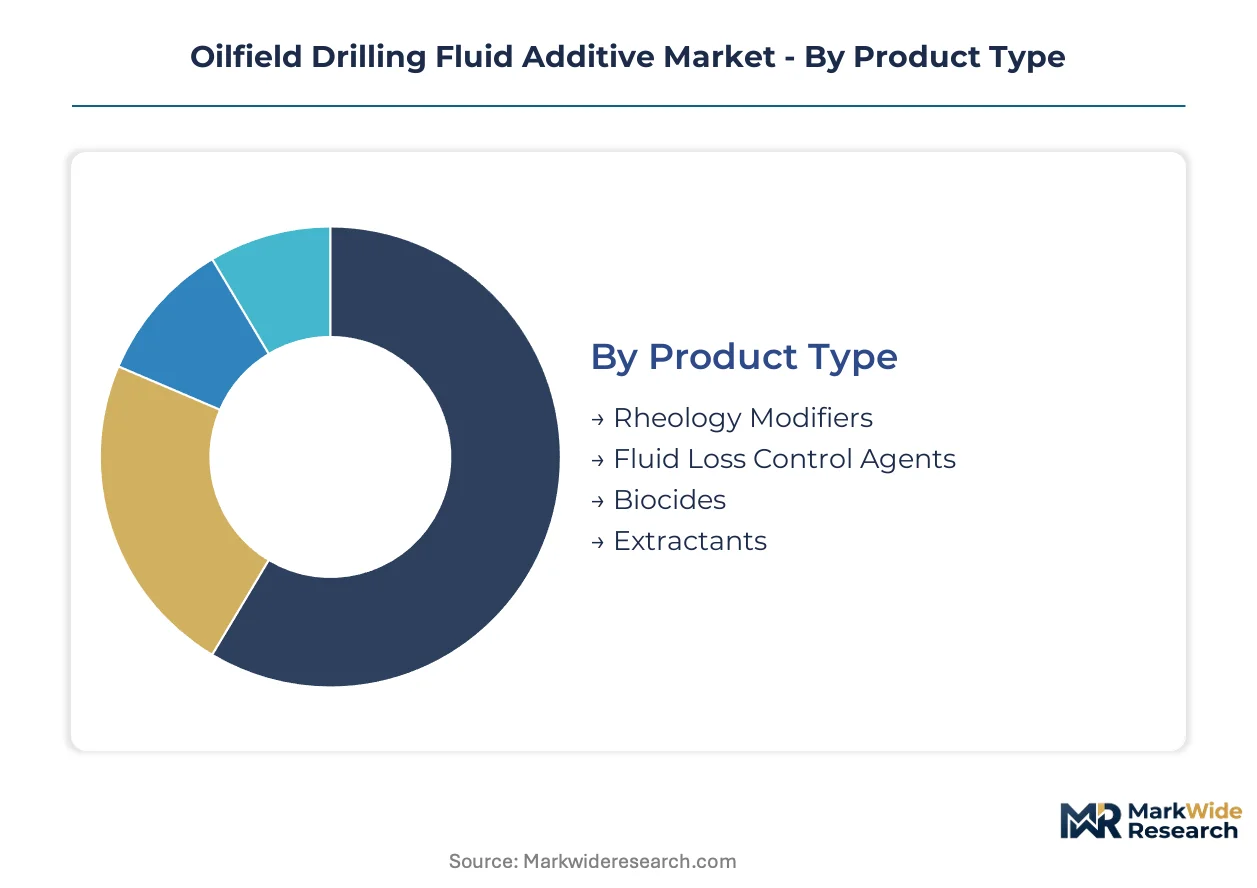
Segmentation in drilling fluid additives determines specification authority and margin capture. Product chemistry dictates technical service intensity, while application context shapes regulatory exposure and pricing power.
Product Type:
Margin pools concentrate in polymers commanding premium positioning for high-temperature stability and biodegradability compliance.
- Rheology Modifiers:These additives control plastic viscosity and yield point through organophilic clays and synthetic polymers. Demand concentrates in Permian Basin extended-reach laterals where cuttings transport over 15,000-foot sections requires specialized viscosifier packages. EPA NPDES discharge thresholds are accelerating substitution toward bio-based alternatives.
- Fluid Loss Control Agents:Polyanionic cellulose derivatives and synthetic polymers reduce filtrate invasion into permeable formations. Gulf of Mexico deepwater operators specify thermal-stable variants for wells exceeding 30,000 feet measured depth, compressing starch-based alternatives.
- Biocides:Glutaraldehyde and THPS chemistries combat sulfate-reducing bacteria in high-temperature shale formations. Resistance proliferation is forcing rotation protocols among Eagle Ford operators.
- Extractants:Specialty surfactants separate hydrocarbon phases from drilling waste streams. REACH restrictions on microplastic-containing formulations are redirecting North Sea procurement toward bio-ester alternatives.
Rheology modifiers hold installed capacity. Biocides are rotating up the share rankings.
Application:
Volume splits reflect the unconventional drilling cycle, with onshore activity driving procurement frequency and offshore commanding specification premiums.
- Onshore Operations:Shale development in the Permian Basin and Eagle Ford consumes rheology modifiers and fluid loss polymers at scale. Independent operators unbundle additive procurement from integrated service contracts, creating direct supplier relationships.
- Offshore Operations:Gulf of Mexico shelf and deepwater drilling face EPA discharge limits that elevate biodegradable fluid system costs. Synthetic-based mud restrictions compress demand for conventional emulsifiers.
- Exploration Activities:Wildcat drilling in frontier basins requires portable additive packages with rapid deployment. Spot purchasing through digital platforms is fragmenting traditional annual commitments.
- Well Completion:Cement spacer fluids and completion brines demand corrosion-resistant additives compatible with CO2-rich CCUS injection environments.
Onshore operations anchor procurement volume. Offshore operations are expanding most quickly as deepwater projects sanction.
End User:
Customer type determines contract structure, with national oil companies unwinding bundled service preferences and independents prioritizing working capital flexibility.
- Independent Operators:Private equity-backed producers under 50,000 barrels per day favor spot purchasing through commodity trading platforms. Working capital efficiency trumps volume discounts in procurement decisions.
- National Oil Companies:Historical preference for integrated service packages is fragmenting into discrete additive tender specifications. Direct supplier relationships are replacing major service company channels.
- Oilfield Service Companies:Schlumberger and Baker Hughes maintain captive additive volumes through integrated drilling systems and bio-based chemistry platforms respectively.
- Drilling Contractors:Day-rate contract structures limit additive specification authority to operator-directed procurement with limited technical input.
National oil companies hold legacy contract volume. Independent operators are gaining share fastest in specification influence.
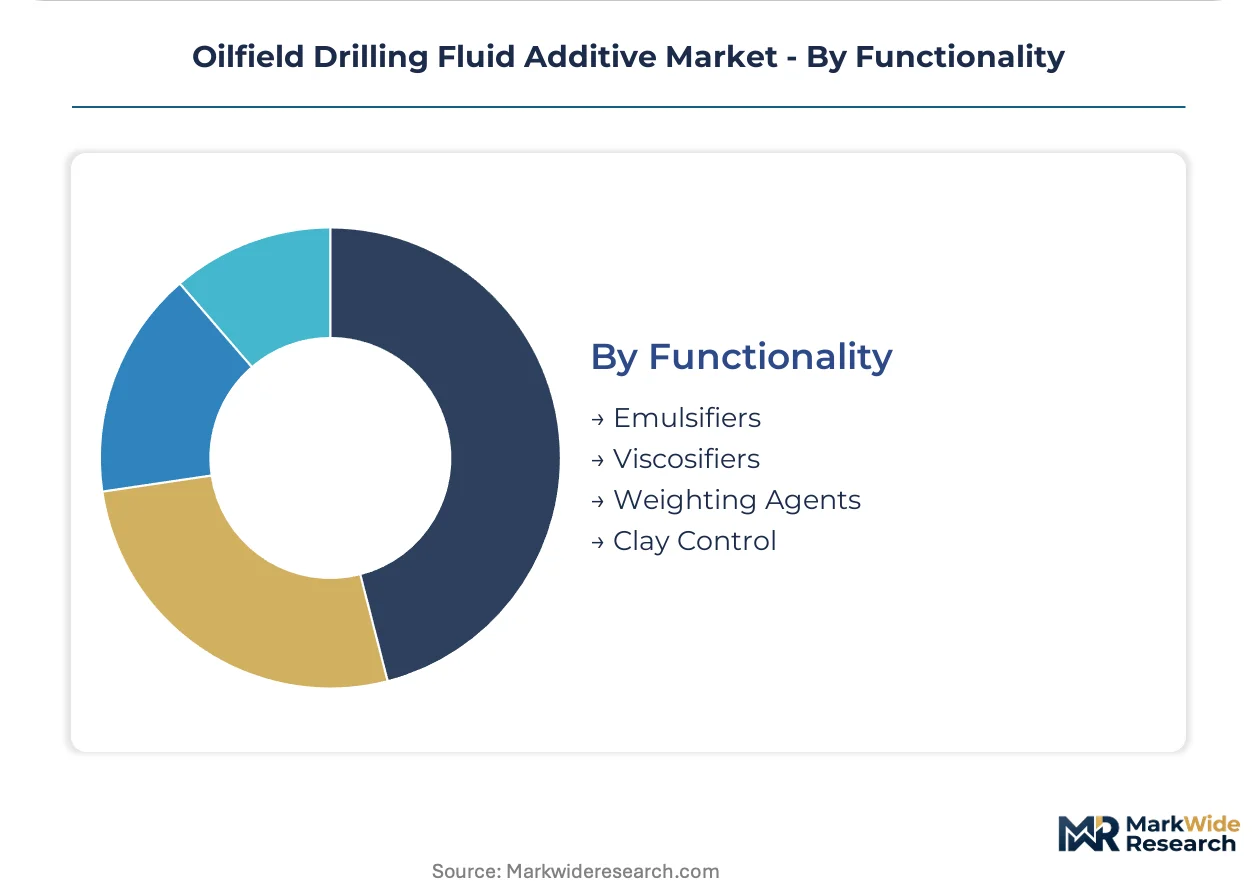
Functionality:
Technical function maps to wellbore challenge severity, with weighting agents and viscosifiers commanding differentiated positioning based on mineral sourcing strategy.
- Emulsifiers:Internal phase stabilizers for synthetic-based muds face REACH microplastic restrictions in North Sea operations. ECHA's 2023 proposal targets polymeric materials below five millimeters.
- Viscosifiers:Xanthan gum and guar derivatives maintain cuttings suspension in directional drilling. Barite supply diversification toward micronized ilmenite is reshaping formulation economics.
- Weighting Agents:Barite remains dominant though Chinese import dependency is driving domestic sourcing of hematite and ilmenite alternatives. Halliburton anchors Middle East positioning through localized manufacturing.
- Clay Control:Potassium chloride and polyamine chemistries prevent shale hydration in water-based systems. High-temperature stability requirements are elevating polymer substitution rates.
Weighting agents hold installed capacity. Emulsifiers are rotating up the share rankings as bio-based reformulations penetrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel underwrites North American supply chain dominance for drilling fluid additives, connecting Gulf Coast chemical manufacturing to Permian Basin and offshore rig demand.
United States
Permian Basin extended-reach laterals and Gulf of Mexico deepwater projects consume rheology modifiers and thermal-stable polymers at scale. The EPA's updated NPDES discharge standards for offshore operations accelerate biodegradable fluid system adoption. Houston and Corpus Christi chemical corridors concentrate blending capacity for both onshore shale and shelf drilling programs.
Saudi Arabia
Aramco's unconventional gas drilling and Red Sea exploration campaigns expand specialty additive procurement beyond traditional barrel-focused formulations. The kingdom's Environmental Protection Department enforces stricter drilling waste management protocols for onshore operations. The Eastern Province industrial city of Jubail hosts localized manufacturing of weighting agents and viscosifiers serving Middle East contracts.
China
Domestic shale development in Sichuan and tight gas operations in Ordos Basin drive demand for high-temperature stable polymers and clay control additives. The Ministry of Ecology and Environment enforces stricter water-quality standards for onshore drilling waste pits. Shandong Province chemical clusters manufacture barite alternatives and fluid loss control agents for regional supply.
Norway
North Sea mature field redevelopment and Barents Sea frontier drilling require biodegradable synthetic-based mud systems compliant with stringent discharge limits. The Norwegian Environment Agency implements OECD 306 biodegradability thresholds for offshore drilling fluid discharge. Stavanger and Bergen serve as specification centers where operators source REACH-compliant emulsifiers and extractants.
Brazil
Pre-salt deepwater development in the Santos Basin demands high-performance fluid loss control polymers for wells exceeding 30,000 feet measured depth. The Brazilian Institute of Environment and Renewable Natural Resources regulates offshore drilling waste discharge through licensing frameworks. The Macaé logistics cluster coordinates additive supply to Campos and Santos Basin floating production units.
Oilfield Drilling Fluid Additive Market Competitive Landscape
Concentration sits with integrated oilfield service providers controlling captive additive volumes through bundled drilling systems. The competitive structure spans three tiers: global service companies with in-house chemical manufacturing, specialized additive suppliers with direct operator relationships, and regional blenders serving spot purchasing demand. Strategic moves center on bio-based chemistry platform development and localized manufacturing investments to circumvent import dependencies.
Within the integrated service tier, Schlumberger Limited, Baker Hughes Company, and Halliburton Company exemplify divergent positioning strategies. Schlumberger anchors deepwater market presence through system-level integration. Baker Hughes occupies the bio-based chemistry specialization vector. Halliburton exemplifies regional manufacturing localization to secure Middle East contract flows.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton Company |
| Dow |
| BASF SE |
| Innospec Inc. |
| Tetra Technologies Inc. |
| Newpark Resources Inc. |
| Chevron Phillips Chemical Company |
| Others |
Value Network & Pricing Analysis
Alternative weighting agent substitution—micronized ilmenite and hematite displacing Chinese barite—simultaneously redraws supply geography toward domestic mineral processing and compresses pricing power for incumbent weighting agent suppliers dependent on legacy import channels. This input shift feeds directly into formulation economics for independent operators in the Permian Basin and Eagle Ford.
Pricing Analysis
Volume-discount tiering structures separate major integrated service companies capturing captive premiums from spot purchasers among private equity-backed independents. Price differentiation rests on thermal stability certification for high-pressure high-temperature applications and biodegradability compliance under EPA NPDES frameworks. Pricing pressure stems from digital marketplace spot purchasing fragmenting traditional annual commitments. Private equity-backed operators under 50,000 barrels per day exhibit highest price sensitivity; Gulf of Mexico deepwater operators show lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Houston Ship Channel transit underwrites North American additive supply chain dominance, connecting Gulf Coast chemical manufacturing to Permian Basin rig demand. Raw material sourcing draws from Shandong Province barite alternatives, Jubail industrial city weighting agents, and Stavanger bio-ester emulsifiers. Single-source vulnerability concentrates in Chinese mineral processing for traditional barite feedstocks. Distribution runs through integrated service company captive channels, direct operator procurement, and emergent commodity trading platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise—colloidal stability, high-temperature polymer engineering, and multi-jurisdictional registration navigation—represents the critical capability gap constraining supplier technical service capacity as experienced mud engineers retire faster than universities produce replacements.
For Market Incumbents: Consolidate technical service capacity through targeted acquisition of regional blenders possessing deep formation damage expertise and established operator relationships. Backward integration into domestic ilmenite and hematite processing secures supply continuity against Chinese barite import volatility. Prioritize bio-based chemistry platform R&D to preempt REACH microplastic restrictions on conventional emulsifiers. For New Entrants and Emerging Players: Lead with geothermal drilling crossover applications as the most penetrable white-space target, transferring oilfield high-temperature polymer expertise to renewable energy developers in Nevada and Utah. CCUS well construction represents a second specification window for corrosion-resistant additive packages. Pursue direct relationships with national oil companies unwinding bundled service preferences rather than competing through major service company channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional blenders serving Permian Basin spot purchasing demand through digital marketplaces. Long-term viability over a five-to-ten year horizon hinges on biodegradability compliance capabilities as EPA, ECHA, and China's MEE diverge on discharge thresholds. Monitor biocide resistance proliferation in Eagle Ford shale formations as an inflection indicator for rotation protocol complexity and inventory management service opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Mineral Processing | Captive ilmenite and hematite supply reduces Chinese barite dependency for Permian Basin operators. |
| Bio-based Chemistry Platform Development | REACH-compliant emulsifiers preempt ECHA microplastic restrictions in North Sea operations. |
| Real-time Monitoring System Integration | Automated mud property sensors enable just-in-time additive delivery reducing surface inventory. |
| Geothermal Drilling Capability Transfer | High-temperature polymer expertise opens specification relationships with Nevada renewable developers. |
| Localized Manufacturing Investment | Jubail and Shandong production hubs circumvent import dependencies for Middle East contracts. |
Research Methodology
Desk research of trade flow databases, EPA NPDES permit filings, and ECHA REACH registration dossiers preceded structured interviews with drilling fluid engineers, procurement managers at independent operators, technical directors at specialty chemical suppliers, and regulatory affairs specialists at integrated service companies. Primary fieldwork across the Houston Ship Channel chemical corridor, Permian Basin drilling operations, and North Sea offshore platforms was cross-validated against customs records, SEC 10-K chemical segment disclosures, and industry association technical publications. Bottom-up rig count and additive consumption intensity models were triangulated against top-down market value estimates.
Variance decomposition across product chemistry, application context, and end-user contract structure informed the analytical framework over the projection horizon. Segmentation dimensions modeled include rheology modifier thermal stability grade, fluid system base type, operator size tier, and regional regulatory cluster. CAGRs were derived from rig activity trajectories, well complexity indices, and substitution rate assumptions for biodegradable alternatives. Industry-specific forecast inputs incorporated EPA discharge standard implementation timelines and REACH restriction proposal progression.
Forecasts assume regulatory continuity in EPA NPDES, ECHA REACH, and China's MEE enforcement regimes; material policy shifts would require re-modeling around divergent biodegradability test protocols or accelerated chrome lignosulfonate phase-outs. Practitioners should keep alternative scenarios live as biocide resistance patterns, barite trade flow disruptions, and national oil company procurement unbundling velocities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Inhibited Propylene Glycol Market
Additives
Flux Injection System Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Nucleotide Premix Market
Additives
Global Matting Agents Market
Additives
Benzoates Market
Additives
Global Anti-Fog Additives Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Global Corrosion Inhibitor Market
Additives
Inorganic Rheology Modifiers Market
Additives
Feed Additives Market
Additives
China Feed Additives Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Pectin Market
Additives
Polysorbate-80 Market
Additives
Paint Additives Market