
 Green Chelates/Natural Chelating Agents Market | 2026-2036
Green Chelates/Natural Chelating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Green Chelates/Natural Chelating Agents Market Analysis
The capital-intensity divergence between fermentation-based and extraction-based production is unwinding legacy cost structures in green chelate manufacturing. BASF SE leverages its integrated biotechnology platforms to sustain cost leadership in microbial-derived chelating agents. Jungbunzlauer Suisse AG anchors European supply through specialized citric acid fermentation capacity. Kemira Oyj competes in industrial water treatment segments with tailored biodegradable sequestrant portfolios.
Green chelates and natural chelating agents comprise biologically derived compounds—primarily organic acids and their salts—that form stable coordination complexes with metal ions through multiple donor atoms, typically achieving stability constants between 10^5 and 10^15 depending on ligand structure and pH conditions. These compounds serve industrial and commercial markets by replacing synthetic aminopolycarboxylic acids in applications requiring metal ion control, biodegradability, or regulatory compliance. Citric acid and lactic acid product types dominate current volume flows given mature fermentation supply chains and broad regulatory acceptance, while malic acid represents the fastest-expanding category due to emerging pharmaceutical-grade specifications and premium pricing in personal care formulations. Water treatment applications command the largest share of value pools, though agriculture segments show the steepest trajectory as fertilizer manufacturers reformulate micronutrient delivery systems.
REACH restrictions on persistent synthetic chelators and EPA Safer Choice program criteria reshape product standards across European and North American markets, forcing reformulation investments and supply chain recertification. India's BIS quality mandates and CDSCO pharmaceutical excipient guidelines create parallel compliance layers for exporters targeting subcontinent manufacturing. Stakeholders must monitor regulatory divergence between biodegradability testing protocols, as OECD standardized methods and region-specific pass criteria determine market access windows and competitive positioning.
Market Dynamics
REACH restrictions on persistent aminopolycarboxylic acids are forcing European formulators to rebuild supply chains around biodegradable alternatives, compressing certification timelines and recalibrating procurement specifications across industrial water treatment and agricultural micronutrient segments.
Growth Catalysts
- REACH Phase-Out Mandates:ECHA restrictions on EDTA and DTPA derivatives accelerate substitution programs in German and French industrial clusters, pulling fermentation-derived alternatives into cooling water and boiler treatment formulations.
- Indian Fertilizer Reformulation:Domestic manufacturers under BIS quality mandates are integrating citric acid and gluconate chelates into micronutrient fertilizers, creating volume pull for agricultural-grade specifications.
- Precision Fermentation Advances:Strain engineering breakthroughs cut citric acid production cycles by 15-20%, narrowing cost gaps with petrochemical-derived chelators in bulk industrial applications.
Market Restraints
- Molasses Price Volatility:Sugar feedstock fluctuations in Brazil and India transmit directly to fermentation economics, compressing margins for citric acid and gluconic acid producers during commodity spikes.
- Chinese Citric Acid Dominance:Three state-backed producers control 60% of global fermentation capacity, creating concentration risk for European and North American formulators seeking supply diversification.
- Performance Ceiling in High-Temperature Applications:Thermal stability limitations of organic acid chelates below 120°C restrict penetration into geothermal and high-pressure boiler segments where synthetic alternatives retain technical advantages.
Strategic Opportunities
- Pharmaceutical-Grade Malic Acid:CDSCO and FDA excipient guidelines create premium positioning for USP-grade specifications in parenteral nutrition and diagnostic reagent applications, commanding 3-4x standard industrial pricing.
- Biodegradable Scale Inhibitors:EPA Safer Choice program criteria open municipal water treatment procurement in California and Great Lakes states to polyaspartate and phytate-based alternatives.
- Digital Agriculture Integration:Variable-rate fertilization platforms in Iowa and São Paulo state enable chelate-microbiome combination products with sensor-triggered release profiles.
Industry Challenges
- Fermentation Scale-Up Expertise Gap:Industrial biotech talent shortages in process engineering and strain optimization delay commercial timelines for novel chelate platforms by 18-24 months.
- OECD 301B Certification Bottlenecks:Biodegradability testing backlogs at European laboratories extend product registration cycles, freezing market access for 6-9 months.
- Legacy Equipment Retrofit Costs:Water treatment facilities with EDTA dosing infrastructure require tank cleaning and line flushing investments before green chelate conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Chelates/Natural Chelating Agents Market |
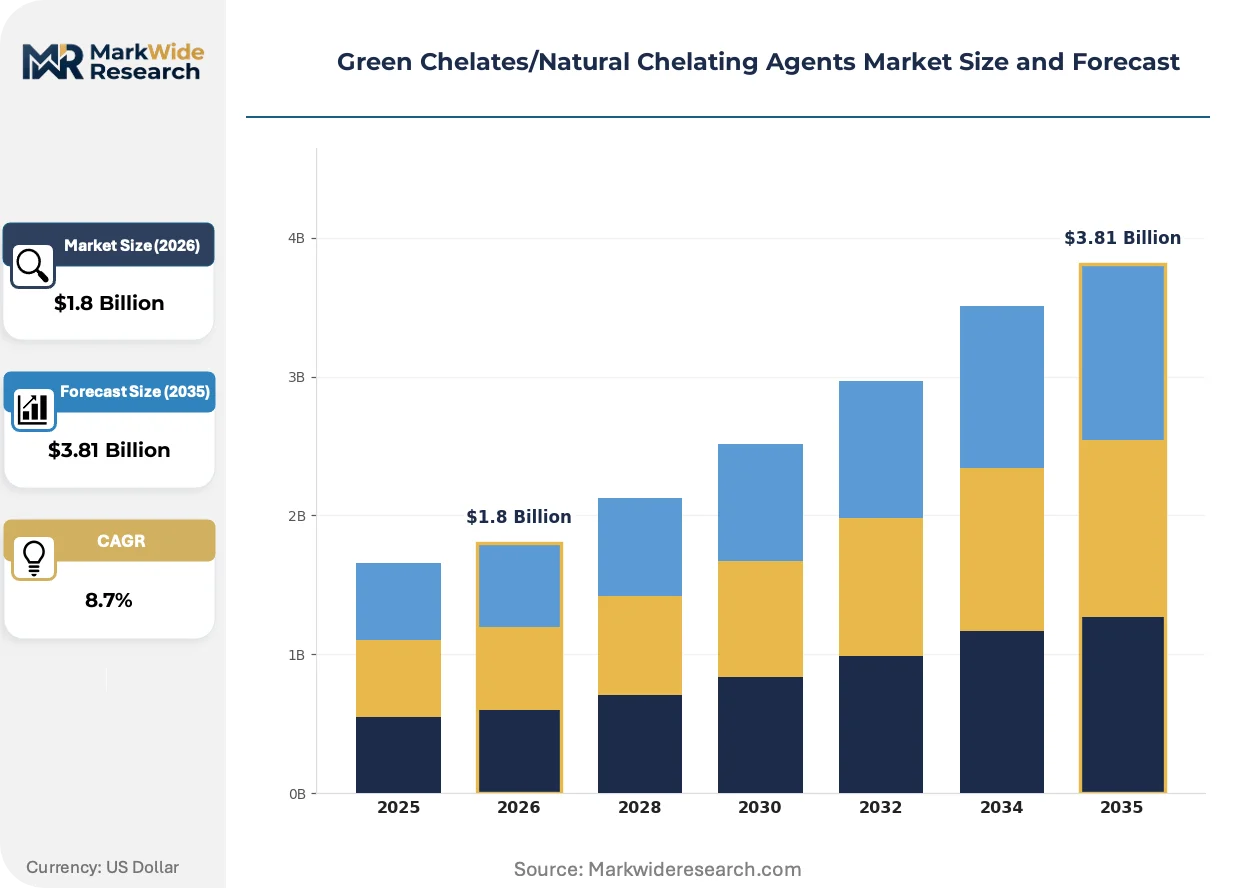
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EDTA, Citric Acid, Lactic Acid, Malic Acid Application: Agriculture, Food Preservation, Water Treatment, Pharmaceuticals End User: Fertilizer Manufacturers, Food Processors, Industrial Facilities, Healthcare Providers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Innospec, Nippon Shokubai Co., Ltd., BASF SE, Jungbunzlauer Suisse AG, LANXESS AG, Nouryon, Kemira Oyj, Evonik Industries AG, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Chelates/Natural Chelating Agents Market Emerging Trajectories
Biotechnology platforms are fragmenting the traditional citric acid value chain, enabling regional production models that bypass concentrated Asian supply while regulatory pressure accelerates performance standardization across biodegradable alternatives.
Enzymatic modification of lignocellulosic feedstocks is fragmenting conventional fermentation economics by enabling agricultural residue utilization for gluconic acid production. Pilot facilities in Ontario and Bavaria demonstrate comparable yields to molasses-based routes at 30% lower feedstock cost. Specialty chemical distributors in the Great Lakes region are building dedicated storage and blending capacity for these second-generation chelates.
EU F-Gas Regulation amendments tighten requirements on fluorinated greenhouse gases in industrial cooling, indirectly elevating biodegradable scale inhibitors as complementary technologies in closed-loop systems. German chemical parks now specify chelate biodegradability in combined heat and power plant tenders. BASF and LANXESS anchor local supply through integrated fermentation and downstream processing assets in Ludwigshafen and Leverkusen.
Formulator procurement teams are consolidating supplier bases from 8-12 vendors to 3-4 strategic partners with integrated certification support. Agricultural cooperatives in Iowa and São Paulo state now require chelate suppliers to bundle soil microbiome testing with product delivery. This bundled service model displaces traditional commodity trading relationships in North American and Latin American fertilizer channels.
Green Chelates/Natural Chelating Agents Market Segmentation
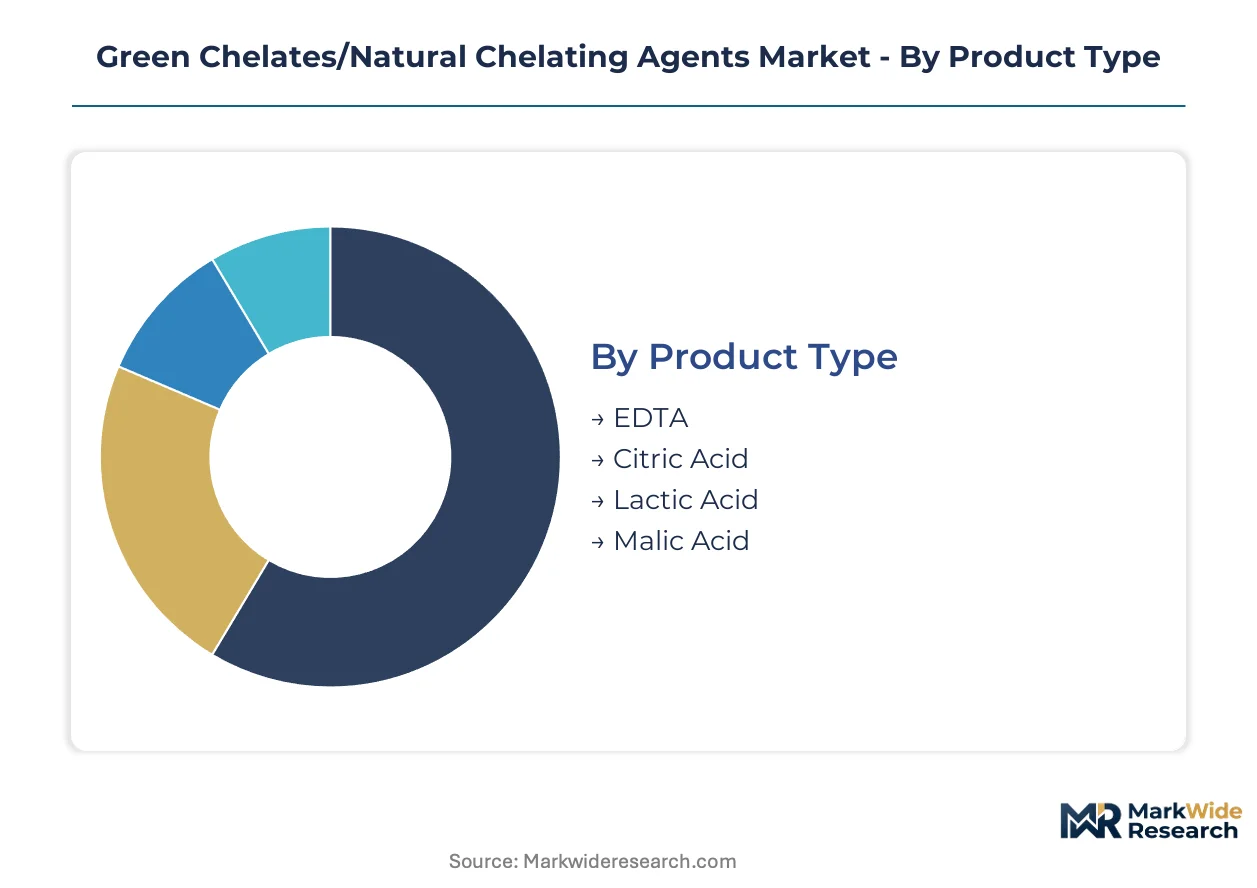
Green chelate manufacturers prioritize segment-specific fermentation economics and regulatory compliance tiers when allocating R&D budgets. Product type and application dimensions drive the steepest margin divergence across the value chain.
Product Type:
Margin pools concentrate in fermentation-derived organic acids where strain optimization and feedstock flexibility create cost advantages over synthetic alternatives.
- Citric Acid:Fermentation-produced tricarboxylic acid forms stable metal complexes across pH 3-6, dominating agricultural micronutrient formulations. Indian fertilizer manufacturers under BIS mandates drive volume absorption for technical-grade specifications.
- Lactic Acid:Bacterial fermentation yields alpha-hydroxy acid chelators with GRAS status for food contact applications. European food processors specify this grade for metal ion control in dairy and beverage stabilization.
- Malic Acid:Pharmaceutical-grade specifications command premium positioning in parenteral nutrition and diagnostic reagents.
- EDTA:Aminopolycarboxylic acid faces substitution pressure from REACH restrictions in German industrial clusters.
Citric acid holds installed capacity. Malic acid is rotating up the share rankings.
Application:
Application selection determines certification burden and pricing power, with water treatment demanding OECD 301B biodegradability documentation.
- Water Treatment:Cooling water and boiler treatment formulations specify biodegradable sequestrants to meet EPA Safer Choice criteria. German chemical parks now bundle chelate biodegradability requirements in combined heat and power tenders.
- Agriculture:Micronutrient fertilizer reformulation integrates citric acid and gluconate chelates for improved metal ion bioavailability. Iowa agricultural cooperatives require bundled soil microbiome testing with chelate procurement.
- Food Preservation:Metal ion chelation extends shelf stability in processed foods and beverages.
- Pharmaceuticals:USP-grade specifications for parenteral applications carry 3-4x industrial pricing multiples.
Water treatment anchors current value capture. Agriculture is climbing the fastest.
End User:
End user procurement sophistication varies sharply, with industrial facilities consolidating vendor bases while healthcare providers demand excipient traceability.
- Fertilizer Manufacturers:Indian producers under BIS quality mandates integrate citric acid chelates into micronutrient delivery systems.
- Industrial Facilities:Cooling tower operators in Great Lakes states specify biodegradable scale inhibitors for municipal procurement compliance.
- Food Processors:Dairy and beverage stabilization applications drive GRAS-certified lactic acid demand.
- Healthcare Providers:Parenteral nutrition and diagnostic reagent applications require pharmaceutical-grade malic acid with full excipient documentation.
Industrial facilities hold procurement volume concentration. Healthcare providers are gaining pricing power fastest.
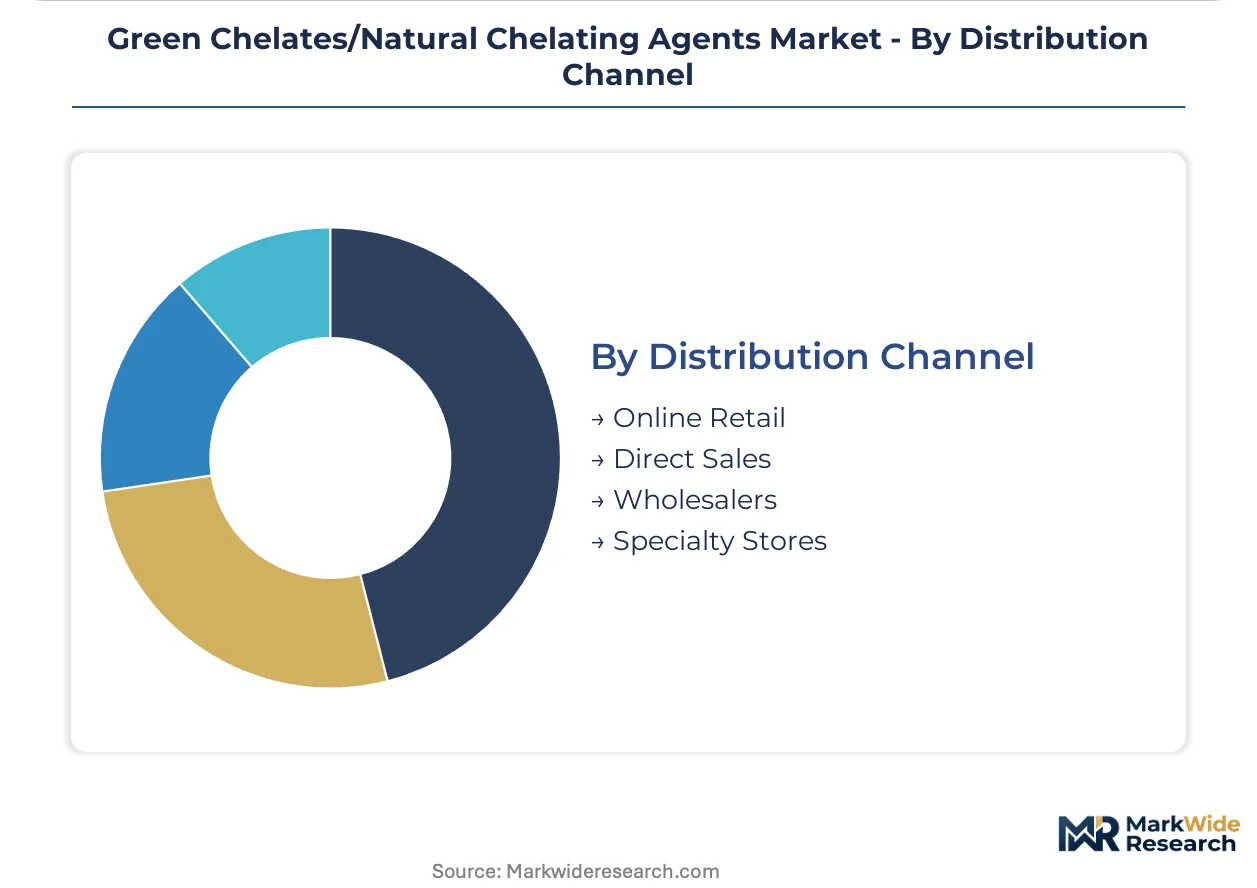
Distribution Channel:
Channel selection reflects customer technical support requirements and certification bundling needs.
- Direct Sales:Large fertilizer manufacturers and industrial water treatment operators negotiate volume contracts with integrated technical service and biodegradability certification support.
- Wholesalers:Regional chemical distributors in the Great Lakes region build dedicated storage and blending capacity for second-generation lignocellulosic chelates.
- Online Retail:Laboratory and small-scale food processing customers source technical-grade specifications.
- Specialty Stores:Niche agricultural supply channels serve precision farming operations with chelate-microbiome combination products.
Direct sales holds contract value concentration. Wholesalers are expanding coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India exhibit the highest price elasticity, squeezing margins on agricultural-grade citric acid chelates, while German industrial facilities absorb premiums for REACH-compliant biodegradable specifications. Demand fragmentation across these poles forces suppliers to run dual-tier pricing architectures.
Germany
Industrial water treatment operators in the Rhine-Ruhr and Ludwigshafen chemical parks drive demand for biodegradable sequestrants. ECHA REACH restrictions on persistent aminopolycarboxylic acids mandate substitution timelines. BASF and LANXESS anchor integrated fermentation and downstream processing assets in these clusters.
India
Fertilizer manufacturers under BIS quality mandates integrate citric acid and gluconate chelates into micronutrient delivery systems. CDSCO pharmaceutical excipient guidelines create parallel compliance layers for exporters. Production concentrates in Gujarat and Maharashtra industrial corridors serving domestic reformulation programs.
United States
EPA Safer Choice program criteria reshape municipal water treatment procurement in California and Great Lakes states. Cooling tower operators specify biodegradable scale inhibitors for compliance. Agricultural cooperatives in Iowa require bundled soil microbiome testing with chelate procurement.
China
State-backed producers control concentrated fermentation capacity for citric acid exports. MIIT industrial standards and dual carbon goals pressure domestic manufacturers toward cleaner production routes. Shandong Peninsula clusters house integrated molasses-to-citrate processing infrastructure.
Brazil
Sugar feedstock volatility in São Paulo state transmits directly to fermentation economics for gluconic acid derivatives. Variable-rate fertilization platforms enable chelate-microbiome combination products with sensor-triggered release. ANVISA regulatory alignment with OECD biodegradability protocols governs export qualification.
Green Chelates/Natural Chelating Agents Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated biotechnology platforms command premium positioning in pharmaceutical-grade specifications, while scale-driven fermentation specialists anchor agricultural and industrial volume segments. The market exhibits tiered consolidation with three strategic archetypes: integrated chemical conglomerates with captive fermentation assets, specialized organic acid producers with regional feedstock advantages, and diversified water treatment chemical suppliers with formulation expertise. Dominant competitive moves include backward integration into molasses and lignocellulosic feedstock sourcing, plus capacity expansion in pharmaceutical-grade malic acid to capture excipient premiums.
Among European integrated chemical conglomerates, BASF SE and LANXESS AG occupy positions exemplifying biotechnology platform leverage, while Jungbunzlauer Suisse AG represents specialized fermentation expertise anchored in citric acid supply chains. These three entities illustrate the archetype spectrum from diversified conglomerate to focused organic acid specialist, each sitting within distinct competitive tiers based on vertical scope and certification depth.
| Leading Market Players |
|---|
| Innospec |
| Nippon Shokubai Co., Ltd. |
| BASF SE |
| Jungbunzlauer Suisse AG |
| LANXESS AG |
| Nouryon |
| Kemira Oyj |
| Evonik Industries AG |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
REACH biodegradability certification gates both supplier qualification and price tiering simultaneously, forcing European formulators to pay premiums for OECD 301B-documented alternatives while Indian fertilizer buyers squeeze agricultural-grade margins through volume consolidation.
Pricing Analysis
After-sales technical service contracts drive lifetime value for green chelate suppliers, with fermentation specialists bundling soil microbiome testing and biodegradability documentation to justify recurring revenue streams. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and agricultural-grade specifications separates premium malic acid for parenteral applications from commodity citric acid for micronutrient fertilizers. Cost compression in agricultural-grade citric acid is intensifying because Indian fertilizer manufacturers under BIS mandates consolidate procurement volumes. Healthcare providers exhibit lowest price sensitivity due to excipient traceability requirements, while commodity fertilizer buyers absorb highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement behavior among German industrial water treatment operators, who maintain buffer inventories to hedge against OECD 301B certification backlogs that freeze market access for six to nine months. Supply concentrates in China, India, and Germany, with Shandong Peninsula clusters controlling fermentation capacity for citric acid exports. Raw material dependencies center on Brazilian and Indian molasses for sugar feedstock, plus emerging lignocellulosic agricultural residues for second-generation gluconic acid routes. Single-source vulnerability runs through concentrated Chinese state-backed producers controlling sixty percent of global fermentation capacity. Distribution runs through direct sales contracts for large fertilizer manufacturers and industrial operators, supplemented by regional chemical distributors building dedicated storage for lignocellulosic alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indian fertilizer manufacturers and German industrial water treatment operators, who consolidate vendor bases from eight-to-twelve suppliers down to three-to-four strategic partners with integrated certification support.
For Market Incumbents: Shield margin pools in pharmaceutical-grade malic acid by deepening captive fermentation capacity and USP-grade certification depth before specialty chemical distributors replicate bundled service models. Prioritize backward integration into lignocellulosic feedstock sourcing in Ontario and Bavaria to bypass Brazilian molasses price volatility. Defend against emerging precision fermentation entrants by locking long-term offtake contracts with Iowa agricultural cooperatives requiring soil microbiome testing bundles. For New Entrants and Emerging Players: Bundled technical service gaps in biodegradability certification and regulatory documentation support present white-space entry points where incumbents under-serve mid-sized formulators. Target municipal water treatment procurement in California and Great Lakes states under EPA Safer Choice criteria, where cooling tower operators seek alternatives to synthetic aminopolycarboxylic acids. Penetrate through partnership with regional chemical distributors building dedicated storage capacity for second-generation lignocellulosic chelates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pharmaceutical-grade malic acid production as precision fermentation advances compress citric acid production cycles by fifteen to twenty percent. Long-term viability favors specialized fermentation platforms with regional feedstock advantages and integrated downstream processing assets over commodity traders lacking certification depth. Acquisition target archetype: mid-cap organic acid specialists with existing OECD 301B documentation and established relationships with German chemical park operators. Signal to watch: strain engineering breakthroughs that narrow cost gaps with petrochemical-derived chelators in bulk industrial applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignocellulosic Feedstocks | Ontario and Bavaria pilot facilities demonstrate thirty percent lower feedstock costs than molasses routes. |
| Pharmaceutical-Grade Malic Acid Capacity Expansion | USP-grade specifications command three-to-four times standard industrial pricing in parenteral nutrition applications. |
| Long-term Supply Agreement with Agricultural Cooperatives | Iowa and São Paulo state buyers now require bundled soil microbiome testing with chelate procurement. |
| Joint Venture for Regional Fermentation Assets | German chemical parks specify chelate biodegradability in combined heat and power plant tenders. |
| Green Manufacturing Transition Certification | EPA Safer Choice program criteria open municipal water treatment procurement in California and Great Lakes states. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, procurement leads at fertilizer manufacturers, technical R&D directors at water treatment chemical suppliers, and distribution channel partners in the Great Lakes region; plus secondary validation through customs and trade data, ACC and Cefic industry reports, SEC filings, and OECD biodegradability testing protocols. Bottom-up volume estimates from product-type and application segments were triangulated against top-down market sizing from regional production capacity and trade flow analysis.
Across the projection horizon, the analytical framework modeled green chelate demand through segmentation dimensions including product type, application, end user, and distribution channel, with additional granularity on certification grade tiers and regional regulatory clusters. CAGRs were derived from regression analysis of historical volume trends, capacity expansion announcements, and substitution elasticity estimates for REACH-compliant alternatives. Forecast inputs incorporated strain engineering productivity gains, molasses price volatility indices, and BIS mandate implementation timelines in Indian fertilizer markets.
Underlying assumptions cover sustained REACH enforcement in German industrial clusters, continued BIS quality mandate rollout in India, and stable EPA Safer Choice program criteria, with deviation risk concentrated in OECD 301B certification backlogs, Brazilian sugar feedstock supply shocks, and Chinese state-backed producer export policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Chelated Selenium Market
Additives
Pectin Market
Additives
Biosaccharide Gum Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Sodium Caprylate Market
Additives
Impact Modifier Market
Additives
Polysorbate-80 Market
Additives
Ascorbyl Stearate Market
Additives
Global Calcium Formate Market
Additives
Green Polymer Additive Market
Additives
Printing Ink Additives Market
Additives
Micronized Powder Market
Additives
Global Mold Release Agents Market
Additives
Texture Modifier Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Global Pearlizing Agent Market