
 Global Artificial Tear Market | 2026-2036
Global Artificial Tear Market Size, Share, and Industry Trends Forecast 2026-2036
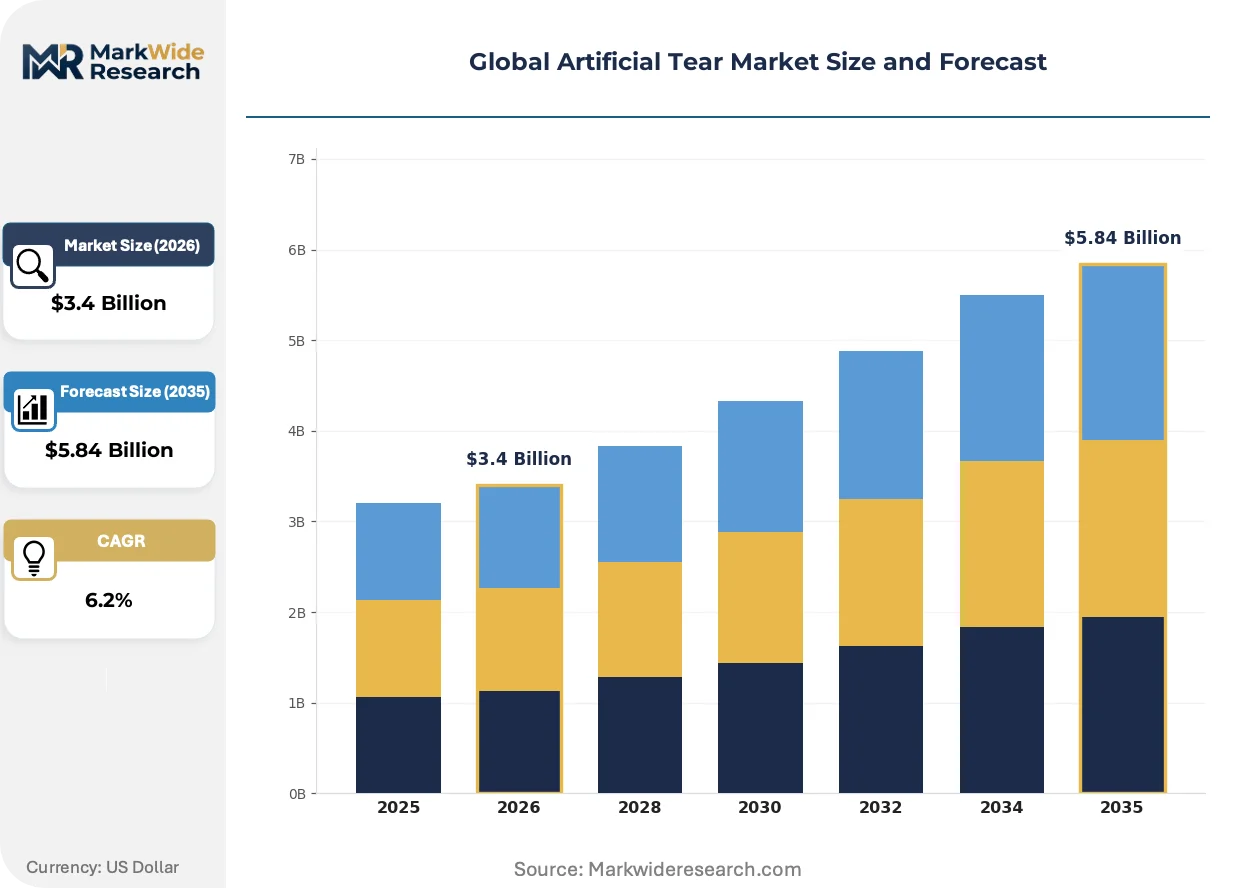
Global Artificial Tear Market Foresight
Preservative-free tier upgrades are unwinding across the artificial tear category as clinicians and patients prioritize ocular surface safety over commodity formulations. Alcon Inc. leverages its surgical heritage to anchor premium positioning in ophthalmology practices. Santen Pharmaceutical Co., Ltd. dominates prescription-grade dry eye therapies across Asian markets. AbbVie Inc. competes through its integrated eye care portfolio spanning diagnostics through chronic disease management.
Artificial tears are sterile ophthalmic solutions or suspensions formulated with electrolytes, polymers, and viscosity agents to supplement or substitute natural tear film on the corneal surface. These products typically specify osmolarity between 150-320 mOsm/L and pH ranges of 6.5-8.0 to ensure biocompatibility with ocular tissue. Gel formulations command margin pools in severe dry eye cases where prolonged corneal contact justifies higher unit economics. E-commerce platforms represent the fastest-growing distribution channel as direct-to-patient subscription models bypass traditional pharmacy intermediaries.
FDA ophthalmic manufacturing guidelines, EU MDR device classification pathways, and Japan's PMDA pharmaceutical standards collectively shape formulation complexity, clinical trial requirements, and market access timelines for new entrants. The FDA's tightened expectations for sterile processing and container-closure integrity are forcing manufacturers to retool legacy filling lines. Stakeholders must monitor how regulatory divergence between the FDA and EMA on preservative safety thresholds reshapes global product portfolios and regional launch sequencing.
Market Dynamics
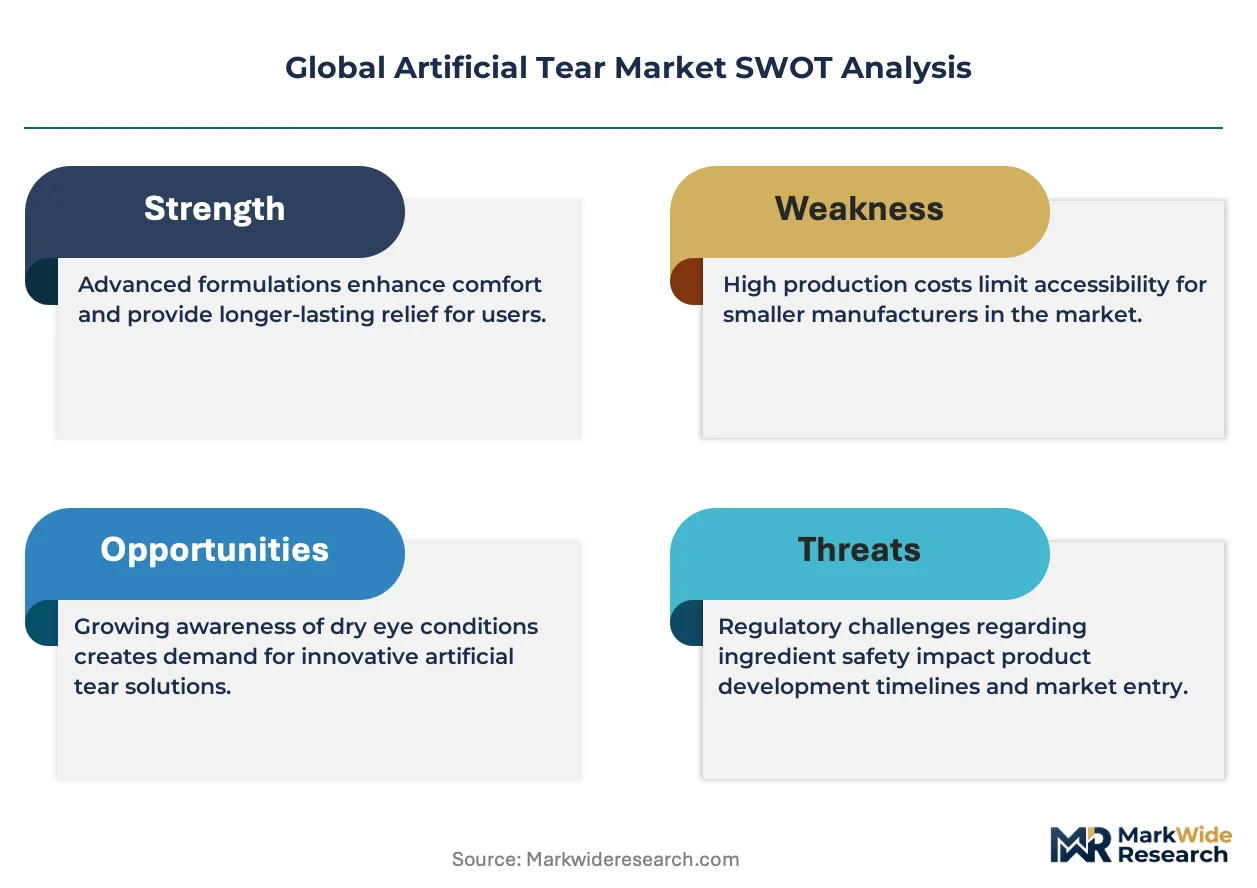
Preservative-free formulation upgrades are compressing commodity margins while FDA sterility mandates force capital retooling across ophthalmic manufacturing facilities. The tension between ocular surface safety demands and legacy polyquad preservation systems defines current competitive positioning.
Growth Catalysts
- Japan's PMDA pharmaceutical standards:Accelerated approval pathways for novel polymer-based tear substitutes are shortening market access timelines for biocompatible formulations targeting severe dry eye.
- Post-surgical ophthalmology:Cataract and refractive surgery volumes in Germany and the United States are expanding the addressable base for prescription-grade lubrication therapies.
- Hyaluronic acid cross-linking:Advanced viscosity engineering is extending corneal contact duration, enabling premium pricing in gel-based severe dry eye segments.
Market Restraints
- Propylene glycol supply volatility:Input cost fluctuations for key viscosity agents are squeezing formulation margins, particularly for mid-tier polymeric solutions.
- Single-use vial manufacturing concentration:Blow-fill-seal capacity clusters in Switzerland and Ireland, creating geographic supply vulnerability for preservative-free unit-dose formats.
- EU MDR device classification friction:Reclassification of certain lubricant devices as Class III medical devices is extending certification timelines and elevating clinical evidence requirements.
Strategic Opportunities
- India's underserved dry eye population:Low diagnosis rates among urban screen-workers present whitespace for over-the-counter artificial tear penetration through pharmacy modernization.
- E-commerce subscription models:Direct-to-patient replenishment platforms are bypassing traditional pharmacy intermediaries, capturing recurring revenue streams in the United States.
- Contact lens wearers:Daily disposable lens expansion in Japan is creating adjacent demand for compatible lubricating drops without preservative incompatibility.
Industry Challenges
- Container-closure integrity engineering:FDA sterility validation requirements for multi-dose preservative-free systems are demanding specialized aseptic filling expertise that outstrips available talent pools.
- Legacy line retrofitting:Existing blow-fill-seal equipment requires substantial capital reinvestment to meet tightened FDA guidance on particulate control and environmental monitoring.
- ISO 11980 biocompatibility testing:Extended ophthalmic irritation study timelines are compressing product development cycles and delaying competitive responses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Tear Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drop Formulation, Gel Formulation, Ointment, Preservative-Free End User: Hospitals, Clinics, Retail Pharmacies, E-commerce Platforms Application: Dry Eye Syndrome, Contact Lens Lubrication, Post-surgery Care, Eye Fatigue Distribution Channel: Offline, Online, Wholesalers, Distributors |
| Companies Covered | Alcon Inc., AbbVie Inc., Bausch & Lomb, Johnson & Johnson Services, Inc., Santen Pharmaceutical Co., Ltd., Akorn, Inc., Sun Pharmaceutical Industries Ltd., Bayer AG, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Tear Market Shifts & Advancements
Formulation chemistry and delivery system engineering are converging to redefine ocular surface therapy standards. Three distinct vectors are compressing legacy product architectures while opening premium positioning pathways.
Lipid-based nanoemulsion technology is supplanting conventional aqueous polymer solutions in moderate-to-severe evaporative dry eye management. Post-menopausal women and meibomian gland dysfunction patients are migrating toward these formulations at accelerating rates in Germany and Japan. The structural shift is enabling 40-60% unit price premiums over commodity carboxymethylcellulose alternatives while compressing volume share for single-polymer legacy SKUs.
REACH restrictions on quaternary ammonium compounds are forcing preservative system reformulation across EU-manufactured ophthalmic portfolios. The industrial consequence is accelerated R&D allocation toward oxidative preservation and ionic buffer systems that bypass regulatory scrutiny. Multi-dose preservative-free formats are absorbing disproportionate development resources as manufacturers anticipate parallel FDA tightening on benzalkonium chloride safety thresholds.
Hospital and ambulatory surgery center procurement committees are consolidating artificial tear purchasing around integrated eye care vendors. Traditional pharmaceutical distributors are losing shelf access as bundled diagnostic-therapeutic contracts displace standalone product negotiations. The United States exhibits the most visible consolidation, with ophthalmology practice management platforms centralizing formulary decisions across multi-site networks.
Global Artificial Tear Market Segmentation
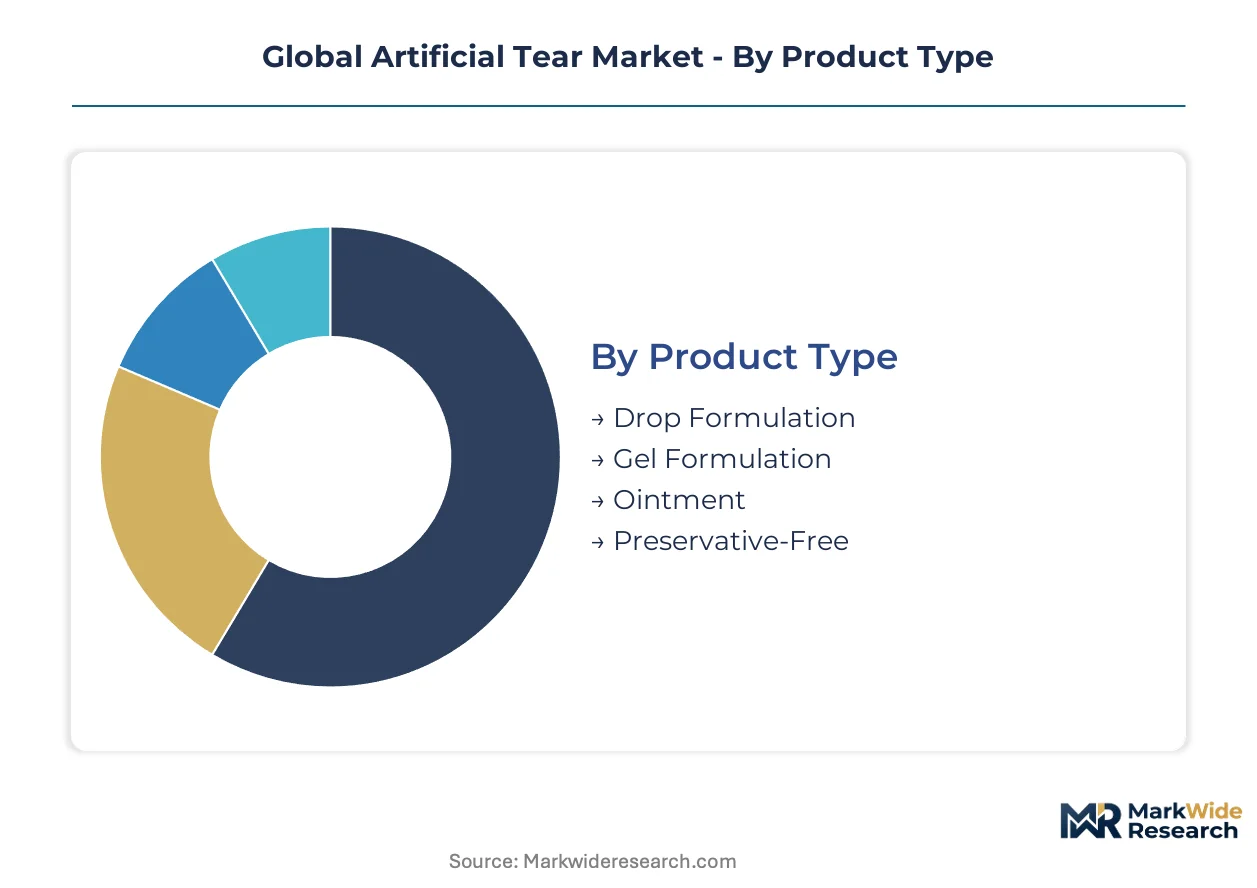
Artificial tear segmentation reflects divergent clinical requirements and purchasing behaviors across patient populations. Channel economics and formulation complexity create distinct margin profiles that manufacturers must navigate through targeted portfolio architecture.
Product Type:
Pharmacy and e-commerce channels favor different viscosity formats based on patient self-selection patterns versus clinician guidance.
- Drop Formulation:Aqueous polymer solutions with osmolarity calibrated to 150-320 mOsm/L dominate OTC aisles in the United States and Germany. Convenience positioning drives repeat purchase frequency among mild dry eye sufferers seeking immediate relief without prescription barriers.
- Gel Formulation:Cross-linked hyaluronic acid matrices extend corneal contact duration for severe evaporative dry eye. Post-surgical patients in Japan's refractive surgery centers generate concentrated demand for overnight retention properties that justify premium unit economics.
- Ointment:Petrolatum-based occlusive preparations serve nocturnal lubrication needs with prolonged residence time.
- Preservative-Free:Single-use vial formats bypass benzalkonium chloride exposure for contact lens wearers and chronic users.
By volume, drop formulations lead. By growth pace, preservative-free formats are climbing the fastest.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional and direct-to-patient channels.
- Hospitals:Integrated eye care vendors capture formulary decisions through bundled diagnostic-therapeutic contracts. Cataract and refractive surgery volumes in the United States concentrate purchasing around surgical heritage suppliers.
- Clinics:Ophthalmology practice management platforms centralize replenishment decisions across multi-site networks. Germany's ambulatory surgery centers exhibit similar consolidation patterns favoring prescription-grade portfolios.
- Retail Pharmacies:Shelf space allocation prioritizes recognized polymer brands with established consumer pull-through.
- E-commerce Platforms:Subscription models bypass traditional intermediaries, capturing recurring revenue through direct-to-patient replenishment algorithms.
Retail pharmacies move the highest unit volumes. E-commerce platforms are expanding most quickly.
Application:
Clinical severity and etiology determine formulation specifications and pricing tolerance across patient segments.
- Dry Eye Syndrome:Chronic aqueous deficiency and evaporative subtypes require tailored osmoprotectant and lipid supplementation strategies. Post-menopausal women in Germany and Japan migrate toward nanoemulsion technologies at accelerating rates.
- Contact Lens Lubrication:Daily disposable lens expansion creates adjacent demand for compatible drops without preservative incompatibility. Japan's high lens penetration rate concentrates this application geographically.
- Post-surgery Care:Cataract and LASIK protocols mandate prescription-grade lubrication with documented biocompatibility.
- Eye Fatigue:Screen-worker populations in urban India present whitespace for OTC penetration through pharmacy modernization.
Dry eye syndrome commands the largest patient base. Post-surgery care offers the steepest expansion trajectory.
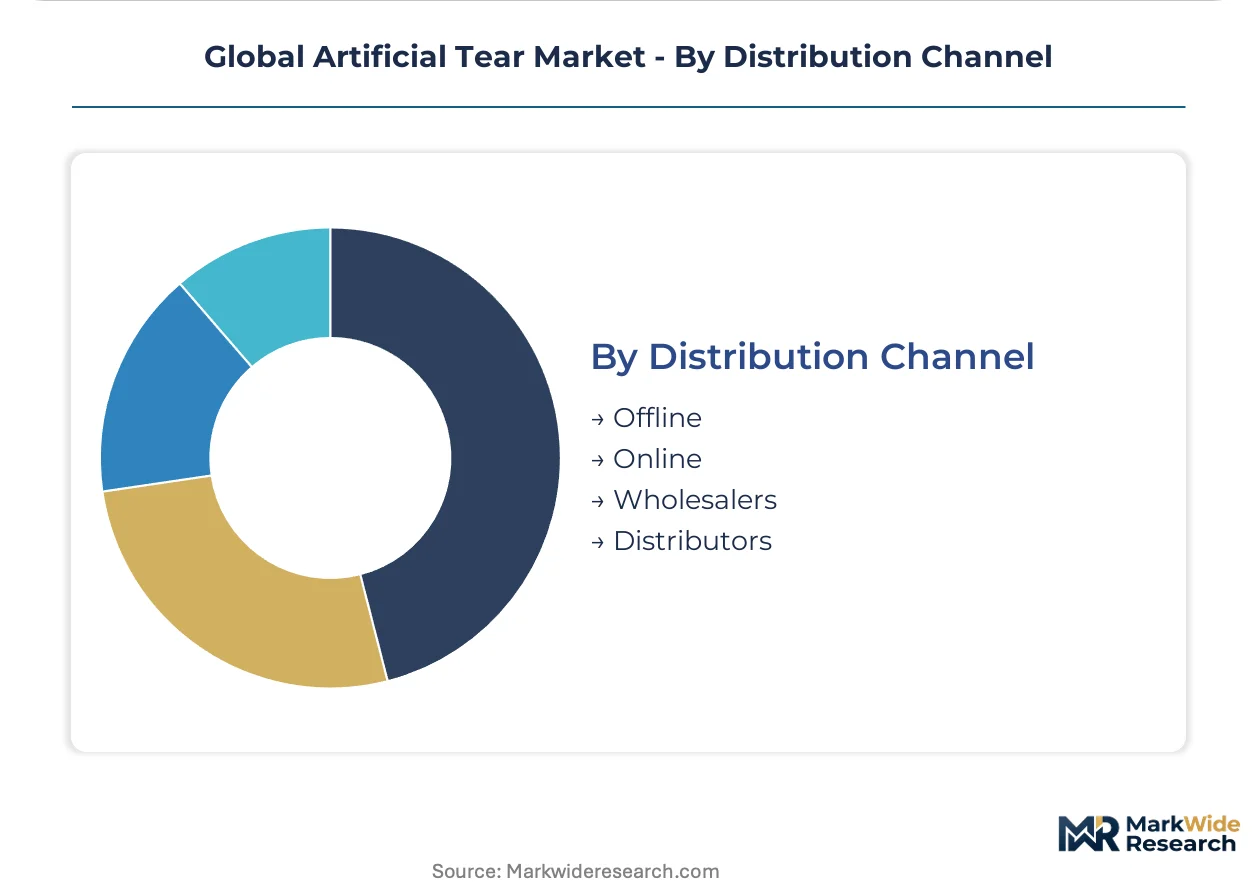
Distribution Channel:
Physical versus digital fulfillment shapes inventory requirements and margin capture mechanisms.
- Offline:Brick-and-mortar pharmacy networks depend on cold-chain integrity for preservative-free inventory turnover.
- Online:Direct-to-patient platforms aggregate purchasing data to optimize subscription algorithms and forecast replenishment cycles.
- Wholesalers:Regional distribution hubs buffer manufacturer production schedules against demand volatility.
- Distributors:Specialized ophthalmic distributors retain relevance in institutional procurement for bundled surgical supplies.
Offline channels retain volume leadership. Online distribution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Swiss and Irish manufacturing clusters supply preservative-free unit-dose formats to deficit markets in Japan and the United States. Import dependency for hyaluronic acid raw materials concentrates in German and Japanese formulation facilities. Regional regulatory divergence on benzalkonium chloride safety thresholds fragments product registration strategies.
United States
Cataract and refractive surgery volumes at ambulatory surgery centers drive prescription-grade lubricant procurement. FDA sterility validation requirements for multi-dose preservative-free systems force capital retooling among domestic manufacturers. The Research Triangle Park corridor in North Carolina hosts specialized ophthalmic contract manufacturing organizations serving both diagnostic and therapeutic portfolios.
Germany
Post-menopausal women with evaporative dry eye subtype migrate toward lipid-based nanoemulsion formulations at accelerating rates. EU MDR device classification friction extends certification timelines for lubricant devices reclassified as Class III medical devices. The Mannheim-Heidelberg metropolitan cluster concentrates blow-fill-seal engineering expertise for preservative-free ophthalmic packaging.
Japan
Daily disposable contact lens expansion creates adjacent demand for compatible lubricating drops without preservative incompatibility. PMDA accelerated approval pathways for novel polymer-based tear substitutes shorten market access timelines for severe dry eye therapies. The Kanto region surrounding Tokyo anchors domestic formulation capacity and surgical ophthalmology practice networks.
Switzerland
Single-use vial manufacturing concentration for preservative-free formats generates export surpluses to EU and Asian markets. REACH restrictions on quaternary ammonium compounds force preservative system reformulation across ophthalmic portfolios produced for EU distribution. The Basel pharmaceutical manufacturing corridor integrates sterile processing capabilities with specialized aseptic filling expertise.
India
Low diagnosis rates among urban screen-workers present whitespace for over-the-counter artificial tear penetration through pharmacy modernization. CDSCO regulatory pathways for ophthalmic solutions require bioequivalence documentation that extends generic product timelines. The Mumbai-Pune pharmaceutical belt hosts contract manufacturing organizations supplying commodity polymer formulations to Middle East and African markets.
Global Artificial Tear Market Competitive Landscape
Listed leaders compete with private specialists across capital access and portfolio breadth dimensions. The vendor base stratifies between integrated eye care conglomerates with surgical heritage and standalone lubricant specialists with formulation chemistry depth. Three archetypes dominate: surgical-platform integrators leveraging diagnostic-therapeutic bundling, polymer chemistry specialists commanding viscosity engineering premiums, and private-label manufacturers capturing pharmacy channel volume. Competitive moves concentrate on sterile processing capacity expansion and oxidative preservation technology licensing.
Within the surgical-platform integrator tier, Alcon Inc. and Johnson & Johnson Services, Inc. occupy positions anchored by multi-site ophthalmology practice management relationships. Among prescription-grade specialists, Santen Pharmaceutical Co., Ltd. exemplifies the Asian-market-focused archetype with concentrated presence in refractive surgery centers. AbbVie Inc. represents the integrated pharmaceutical conglomerate model spanning diagnostics through chronic disease management portfolios.
| Leading Market Players |
|---|
| Alcon Inc. |
| AbbVie Inc. |
| Bausch & Lomb |
| Johnson & Johnson Services, Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Akorn, Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Bayer AG |
| Novartis AG |
| Others |
Supply & Pricing Matrix
FDA sterility validation protocols for multi-dose preservative-free systems gate both manufacturing qualification and tiered pricing power simultaneously, compressing commodity margins while enabling premium capture for specialized aseptic filling capabilities.
Pricing Analysis
Hospital and ambulatory surgery center procurement committees anchor pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on ISO 11980 biocompatibility certification grade and bundled diagnostic-therapeutic contract structures. Pricing pressure stems from REACH-driven preservative system reformulation costs in EU-manufactured portfolios. Retail pharmacy channel buyers exhibit highest price sensitivity, while integrated eye care vendors at multi-site ophthalmology networks tolerate premium positioning for surgical heritage brands.
Supply Chain Analysis
Inventory lead times for preservative-free unit-dose formats extend due to blow-fill-seal capacity concentration in Switzerland and Ireland. Raw material dependencies center on hyaluronic acid feedstocks from German and Japanese suppliers, propylene glycol viscosity agents, and polymer electrolytes. Single-source vulnerability in Swiss-Irish aseptic filling infrastructure creates geographic concentration risk. Distribution runs through specialized ophthalmic distributors for institutional procurement, with e-commerce platforms capturing direct-to-patient subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aseptic filling expertise for multi-dose preservative-free systems represents the critical capability gap constraining competitive entry, with FDA sterility validation requirements outstripping available engineering talent pools and capital equipment availability.
For Market Incumbents: Secure blow-fill-seal capacity expansion in Swiss and Irish manufacturing corridors before equipment lead times extend further. Lock in long-term hyaluronic acid supply agreements with German and Japanese raw material suppliers to defend margin position against propylene glycol cost volatility. Prioritize oxidative preservation technology licensing to preempt FDA tightening on benzalkonium chloride safety thresholds.
For New Entrants and Emerging Players: Lead with preservative-free formulation development targeting India's underserved urban screen-worker population through pharmacy modernization partnerships. Exploit whitespace in contact lens-compatible lubricating drops for Japan's daily disposable lens expansion. Establish e-commerce direct-to-patient subscription models to bypass entrenched retail pharmacy distribution.
For Investors and Strategic Acquirers: FDA guidance evolution on ophthalmic drug manufacturing reshapes the acquisition landscape toward specialized aseptic filling capabilities. Target contract manufacturing organizations with validated multi-dose preservative-free lines and established ophthalmic sterile processing expertise. Monitor EU MDR device classification friction as signal for extended certification timelines elevating clinical evidence requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Manufacturing Scale-Up | Captures premium positioning as FDA sterility mandates compress commodity margins. |
| Oxidative Preservation Technology Licensing | Bypasses REACH restrictions on quaternary ammonium compounds in EU distribution. |
| Hospital System Partnership | Secures formulary access through bundled diagnostic-therapeutic contracts at ambulatory surgery centers. |
| E-Commerce Direct-to-Patient Launch | Aggregates replenishment data to optimize subscription algorithms and recurring revenue capture. |
| Reimbursement Strategy Development | Aligns prescription-grade lubrication protocols with cataract and refractive surgery coverage. |
Research Methodology
The analysis maps preservative-free formulation tiers, gel-based severe dry eye segments, and e-commerce distribution channels, each validated through ophthalmology practice managers, hospital procurement committees, and pharmaceutical regulatory affairs specialists. Primary interviews with blow-fill-seal equipment engineers and sterile processing consultants combined with secondary validation from FDA guidance documents, EMA submissions, PMDA pharmaceutical standards, and ISO 11980 biocompatibility protocols. Bottom-up demand modeling across patient severity subtypes triangulates with top-down market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by formulation chemistry, end-user procurement authority, clinical application severity, and distribution channel type. CAGRs derive from patient population expansion, surgery volume trajectories, and channel shift elasticity. Forecast inputs incorporate regulatory approval pathway timelines and preservative system reformulation R&D allocation patterns.
Forecasts assume regulatory continuity in FDA ophthalmic manufacturing guidance, EU MDR device classification pathways, and Japan's PMDA pharmaceutical standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Tonometry Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Neurotrophic Keratitis Market