
 Presbyopia Treatment Market | 2026-2036
Presbyopia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Presbyopia Treatment Market Outlook
Software-defined vision correction is hardening as a recurring revenue layer atop traditional device sales, with subscription-based presbyopia management programs bundling diagnostic apps, lens replacement schedules, and telehealth follow-ups. Carl Zeiss Meditec leverages its optical coherence tomography installed base to anchor premium screening workflows in European and Asian clinics. LENZ Therapeutics sustains clinical momentum through its aceclidine-based pupil-modulating approach, while Alcon competes across the full spectrum from multifocal contact lenses to presbyopia-correcting intraocular lenses.
Presbyopia treatment encompasses optical, pharmaceutical, and surgical interventions that restore near visual acuity in individuals with age-related loss of lens elasticity, typically involving materials with specific refractive indices, pupil-modulating agents such as aceclidine or carbachol, or multifocal intraocular lens designs with diffractive or refractive optic profiles. Pharmaceutical solutions represent the fastest-expanding margin pool as eye drop formulations circumvent the surgical risks and fitting complexity of lens-based alternatives. Surgical implants retain premium positioning for patients seeking permanent correction, while contact lenses and eyeglasses occupy mature, volume-driven segments where EssilorLuxottica controls retail channel access through integrated manufacturing and distribution networks.
The FDA's ophthalmic drug review standards and the European Medicines Agency's centralized marketing authorization procedures shape development timelines and label claims for presbyopia-correcting pharmaceuticals, with both agencies scrutinizing duration of action and driving safety profiles. The EU Medical Device Regulation imposes additional conformity assessment burdens on intraocular lens manufacturers seeking CE marking access. Stakeholders must monitor regulatory precedent for combination product classifications and anticipate how pharmacovigilance requirements for novel mechanisms will influence post-market commitment scales.
Market Dynamics
Pharmaceutical presbyopia correction is compressing the traditional surgical and optical device value chain, as pupil-modulating eye drops deliver functional near-vision restoration without invasive intervention or fitting complexity.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated review pathways for novel ophthalmic mechanisms compress development timelines and reduce capital-at-risk for late-stage programs.
- Telehealth Integration:Remote diagnostic platforms enable asynchronous prescription workflows for presbyopia-correcting drops, expanding prescriber capacity beyond traditional ophthalmology clinics.
- Aging Workforce Retention:Employers in precision manufacturing and knowledge-intensive sectors subsidize near-vision correction to sustain productivity among workers aged 45-60.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of aceclidine and carbachol derivatives depends on contract manufacturers concentrated in Zhejiang Province, creating single-source vulnerability.
- Reimbursement Fragmentation:Medicare Part D coverage gaps for non-surgical presbyopia treatments limit out-of-pocket affordability across United States patient populations.
- Duration-of-Action Ceiling:Current pupil-modulating formulations require twice-daily dosing, creating adherence friction versus single-intervention surgical alternatives.
Strategic Opportunities
- Combination Product Pathway:Pairing sustained-release eye drops with diagnostic wearable devices creates differentiated positioning under FDA combination product jurisdiction.
- Direct-to-Consumer Channels:Subscription-based lens replacement programs bypass traditional optical retail gatekeepers in United Kingdom and Germany.
- Japan's Super-Aged Society:PMDA priority review vouchers for geriatric-targeted ophthalmic therapies accelerate market entry for novel mechanisms.
Industry Challenges
- Specialized Formulation Talent:Ophthalmic drug delivery expertise in mucoadhesive polymers and tear-film pharmacokinetics commands premium compensation and limited supply.
- CE Marking Transition:EU Medical Device Regulation recertification burdens for multifocal intraocular lens manufacturers compress margins during conformity assessment periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Presbyopia Treatment Market |
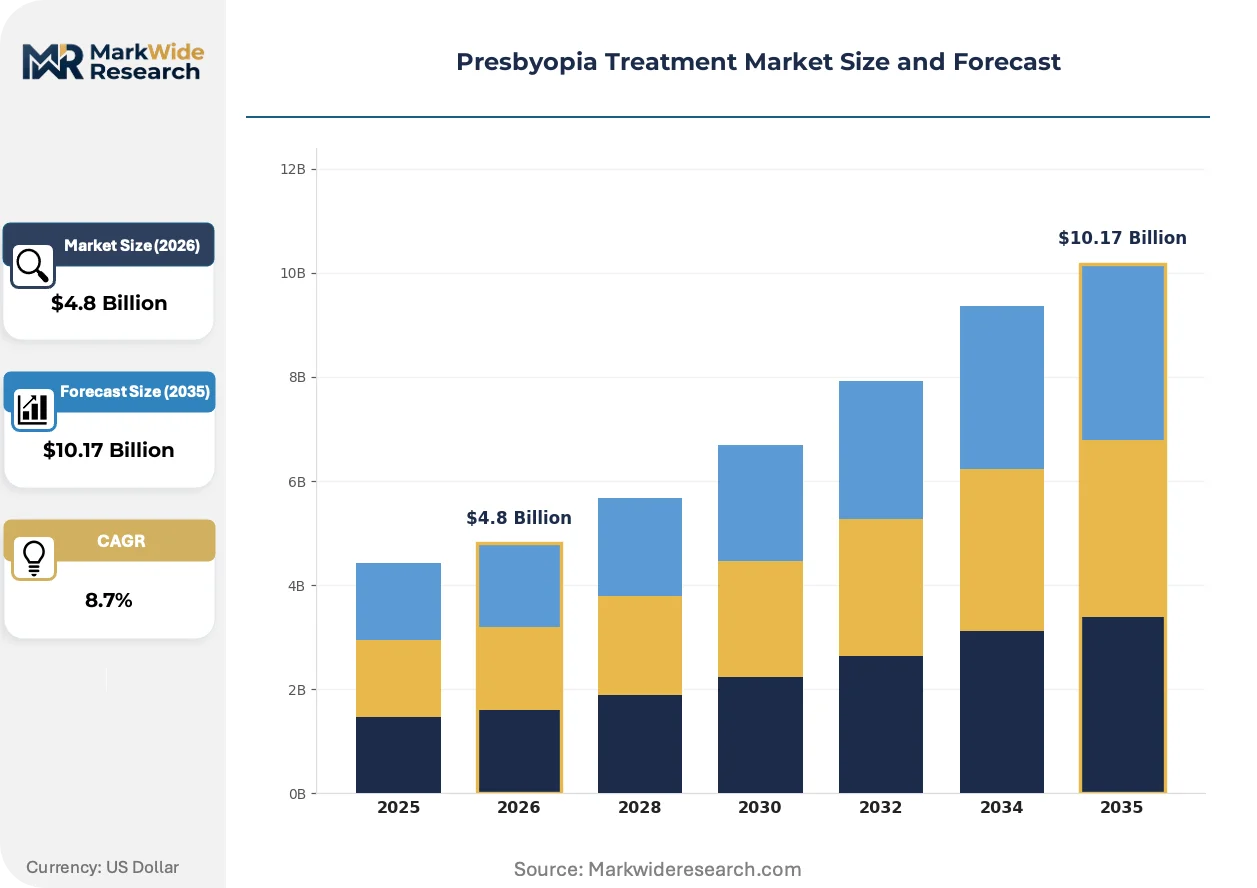
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Lenses, Eyeglasses, Surgical Implants, Pharmaceutical Solutions Delivery Mode: In-Clinic, Home Use, OTC Medications, Prescription End User: Clinics, Hospitals, Optical Stores, Home Care Application: Vision Correction, Eye Surgery, Prophylactic Use, Aesthetic Enhancements |
| Companies Covered | Carl Zeiss Meditec, LENZ Therapeutics, Johnson & Johnson Vision, Orasis Pharmaceuticals, Eyenovia, Alcon, EssilorLuxottica, NIDEK, Bausch & Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Presbyopia Treatment Market Strategic Shifts
Software-defined vision correction is redefining competitive boundaries, with digital therapeutics and AI-guided refraction systems creating new value capture points between pharmaceutical and device incumbents.
Extended-release ocular drug delivery is unifying pharmacokinetic and pharmacodynamic requirements through proprietary mucoadhesive hydrogel platforms. Ophthalmology clinics in South Korea and Singapore are piloting once-daily formulations that match surgical convenience profiles. This convergence is unifying prescriber preference around drop-based regimens that previously required patient education campaigns.
EMA's centralized marketing authorization procedures for ophthalmic pharmaceuticals are tightening evidentiary standards for duration claims and driving safety endpoints. Manufacturers must now generate 12-month stability data and real-world evidence protocols prior to submission. Multifocal intraocular lens suppliers with European manufacturing footprints are restructuring quality management systems to accommodate enhanced pharmacovigilance requirements.
Patient self-selection behaviors are fragmenting the traditional optometrist-mediated purchase pathway for near-vision correction. Digital-native consumers in urban United States markets initiate treatment journeys through online symptom checkers and direct-to-prescriber platforms. This disintermediation concentrates margin pressure on independent optical retailers while rewarding vertically integrated manufacturers with captive e-commerce infrastructure.
Presbyopia Treatment Market Segmentation
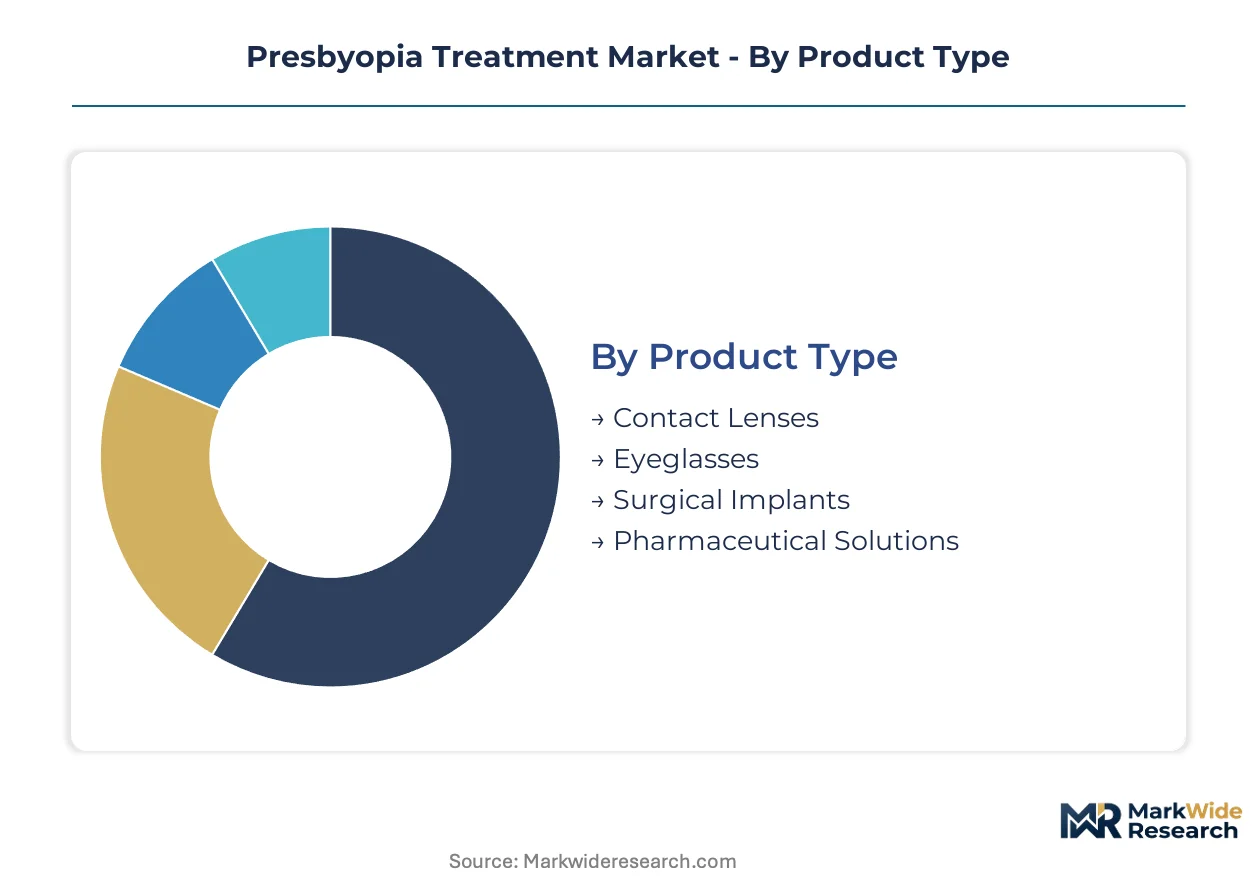
Presbyopia treatment spans optical, pharmaceutical, and surgical modalities with divergent margin profiles and patient selection criteria. Segmentation reveals where capital allocation concentrates and which delivery innovations compress traditional value chains.
Product Type:
Customization intensity varies sharply across this category, from mass-produced optical goods to patient-matched surgical implants.
- Contact Lenses:Multifocal and monovision designs utilize silicone hydrogel materials with specific oxygen permeability ratings. Demand clusters among working-age presbyopes in urban United States markets seeking cosmetic alternatives to reading glasses. Daily disposable formats command premium positioning through subscription fulfillment models.
- Pharmaceutical Solutions:Pupil-modulating eye drops employ aceclidine or carbachol derivatives to create a pinhole optical effect without lens intervention. United States ophthalmology clinics drive adoption as FDA breakthrough designations accelerate prescriber familiarity. Twice-daily dosing regimens create adherence friction that formulation innovation targets.
- Eyeglasses:Progressive addition lenses dominate volume with polycarbonate and high-index substrates.
- Surgical Implants:Multifocal and accommodating intraocular lenses require biometric matching and sterile supply chains.
Most installed capacity flows through Eyeglasses. Expansion is steepest in Pharmaceutical Solutions.
Delivery Mode:
Cost tier stratification separates reimbursed clinical procedures from direct-pay convenience formats.
- Prescription:Physician-supervised dispensing of pupil-modulating drops and specialty contact lenses requires documented near-vision impairment. United States telehealth platforms expand prescriber reach beyond traditional ophthalmology clinics. Medicare Part D coverage gaps limit patient affordability for chronic pharmaceutical regimens.
- Home Use:Self-administered drop protocols and lens care systems reduce clinical visit burden. South Korean and Singaporean clinics pilot once-daily formulations that match surgical convenience profiles. Digital therapeutics integration enables asynchronous monitoring and dose optimization.
- In-Clinic:Surgical implantation and professional lens fitting occur in controlled settings.
- OTC Medications:Lubricating drops and reading glasses occupy retail pharmacy channels.
Volume concentrates in Prescription pathways. Margin expansion concentrates in Home Use formats.
End User:
Customer type determines procurement authority and reimbursement eligibility across settings.
- Clinics:Specialized ophthalmology practices control access to surgical implants and novel pharmaceuticals. European clinics navigate EMA centralized authorization and enhanced pharmacovigilance requirements. Optical coherence tomography screening workflows anchor premium positioning.
- Optical Stores:Retail chains and independent dispensaries dominate eyeglass and contact lens volume. EssilorLuxottica controls channel access through integrated manufacturing and distribution networks. Direct-to-consumer subscription programs bypass traditional gatekeepers in United Kingdom and Germany.
- Hospitals:Integrated health systems perform complex surgical interventions.
- Home Care:Self-directed patients manage chronic drop regimens and lens replacement schedules.
Patient flow concentrates through Optical Stores. Value capture is shifting toward Clinics.
Application:
Maturity stage separates established correction markets from emerging prophylactic and aesthetic categories.
- Vision Correction:Restoration of near visual acuity drives the core revenue base across all product modalities. Aging workforce retention programs in precision manufacturing sectors subsidize correction costs for employees aged 45-60. Functional outcomes metrics determine prescriber preference between optical, pharmaceutical, and surgical options.
- Eye Surgery:Permanent correction through lens replacement or corneal inlays addresses patients seeking single-intervention solutions. FDA review standards and EMA marketing authorization procedures shape development timelines and label claims. Duration-of-action advantages over drop-based alternatives justify premium pricing.
- Prophylactic Use:Early intervention targets pre-presbyopic patients with emerging accommodative decline.
- Aesthetic Enhancements:Cosmetic lens tints and surgical outcomes beyond pure functional correction.
Revenue concentrates in Vision Correction. Investment intensity is highest in Eye Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement clarity outpaces European fragmentation, while Japanese regulatory incentives accelerate novel mechanism entry. Country-specific demand drivers and policy frameworks reshape competitive positioning across major ophthalmic markets.
United States
Medicare Part D coverage gaps for non-surgical treatments limit affordability despite strong prescriber adoption of pupil-modulating drops. FDA breakthrough therapy designations compress review timelines for aceclidine-based formulations. Ophthalmology clinics in metropolitan New York and Los Angeles anchor premium screening workflows tied to optical coherence tomography infrastructure.
Germany
Direct-to-consumer subscription programs bypass traditional optical retail gatekeepers in urban centers. EU Medical Device Regulation recertification burdens compress margins for multifocal intraocular lens manufacturers during conformity transitions. The Rhine-Ruhr and Bavarian manufacturing clusters host quality management system restructuring for enhanced pharmacovigilance compliance.
Japan
PMDA priority review vouchers for geriatric-targeted ophthalmic therapies accelerate market entry timelines. Super-aged demographics concentrate demand for convenient dosing regimens among patients aged 65-plus. Tokyo and Osaka clinical networks pilot once-daily formulations matching surgical convenience profiles.
South Korea
Digital-native consumers initiate treatment journeys through online symptom checkers and direct-to-prescriber platforms. The country's national pharmaceutical regulator tightens evidentiary standards for duration claims prior to submission. Seoul-based ophthalmology clinics lead adoption of extended-release ocular drug delivery platforms.
United Kingdom
Telehealth platforms expand prescriber capacity beyond traditional ophthalmology clinics in London and Manchester. NHS reimbursement frameworks create tiered access for premium therapeutic interventions versus standard optical correction. The Southeast England corridor concentrates software-defined vision correction pilot programs bundling diagnostic apps with subscription fulfillment.
Presbyopia Treatment Market Competitive Environment
Top-tier vendors anchor premium surgical and pharmaceutical tiers, while mid-scale specialists occupy optical device segments. The market structures around three concentration nodes: integrated optical conglomerates controlling retail channel access, pharmaceutical developers pursuing FDA accelerated pathways, and precision diagnostic equipment manufacturers leveraging installed base advantages. Dominant competitive moves include strategic partnerships between drop formulation developers and telehealth platforms, plus portfolio diversification into subscription-based patient management programs.
Within the pharmaceutical development tier, LENZ Therapeutics and Orasis Pharmaceuticals represent pupil-modulating mechanism pioneers. Alcon occupies a position spanning multifocal contact lenses through presbyopia-correcting intraocular lenses, exemplifying full-spectrum portfolio architecture. Carl Zeiss Meditec anchors the diagnostic equipment vector, leveraging optical coherence tomography infrastructure to secure screening workflow integration in European and Asian clinics.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| LENZ Therapeutics |
| Johnson & Johnson Vision |
| Orasis Pharmaceuticals |
| Eyenovia |
| Alcon |
| EssilorLuxottica |
| NIDEK |
| Bausch & Lomb |
| Others |
Value Chain & Pricing Dynamics
Extended-release ocular drug delivery platforms are compressing manufacturing cost curves while concentrating API synthesis in specialized contract manufacturing clusters. This dual shift simultaneously lowers per-unit production economics and tightens supply-side bargaining power for pupil-modulating formulations.
Pricing Analysis
Capacity additions in South Korea and Singapore are reshaping price floors for once-daily aceclidine formulations. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated therapies from follow-on entrants and generic lubricating drops. Pricing pressure stems from Medicare Part D coverage gaps that push out-of-pocket costs toward patient-sensitive thresholds. Employer-sponsored programs for precision manufacturing workforces exhibit lowest price sensitivity; self-pay retail consumers in urban United States markets show highest elasticity.
Supply Chain Analysis
Aceclidine and carbachol derivative synthesis rests on contract manufacturers concentrated in Zhejiang Province, China, with secondary capacity in South Korea and Japan. Key inputs span specialty chiral reagents, mucoadhesive polymer feedstocks, and sterile packaging components. Single-source vulnerability in Zhejiang creates tariff exposure and regulatory inspection risk. Distribution runs through ophthalmology clinic networks for prescription drops, direct-to-consumer subscription platforms for contact lenses, and integrated retail chains for eyeglasses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in presbyopia treatment hinges on formulation innovation driving premium tier migration and telehealth-enabled patient acquisition cost reduction.
For Market Incumbents: Deploy diagnostic equipment installed bases to anchor screening workflows and lock in downstream pharmaceutical dispensing. Alcon and Carl Zeiss Meditec exemplify this hybrid hardware-therapeutic model. Deepen backward integration into aceclidine API supply through captive manufacturing partnerships in South Korea. Consolidate position against pupil-modulating drop entrants by bundling surgical implant consultations with optical coherence tomography screening protocols. For New Entrants and Emerging Players: Launch via direct-to-consumer telehealth platforms targeting United Kingdom and Germany where optical retail gatekeepers retain weaker channel control. White-space concentrates in once-daily extended-release formulations matching surgical convenience profiles. Japan's PMDA priority review voucher pathway offers fastest regulatory validation for geriatric-targeted mechanisms. Target employer-sponsored workforce retention programs as anchor accounts with volume contracting potential. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale ophthalmic drug delivery specialists with proprietary mucoadhesive platforms and incomplete clinical pipelines. Long-term viability favors assets with FDA breakthrough therapy designation momentum and European CE marking pathway clarity. Watch FDA advisory committee scheduling for pupil-modulating mechanisms as inflection signal for competitive timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Pursuit | Accelerated review compresses capital-at-risk timelines for aceclidine-based programs. |
| Telehealth Platform Integration | Asynchronous prescription workflows expand prescriber capacity beyond traditional ophthalmology clinics. |
| Extended-Release Formulation Development | Once-daily dosing protocols match surgical convenience and improve adherence metrics. |
| Diagnostic Equipment Bundling | Optical coherence tomography screening anchors premium positioning for downstream therapeutic dispensing. |
| Direct-to-Consumer Channel Establishment | Subscription fulfillment models bypass EssilorLuxottica-controlled optical retail gatekeepers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged drug development executives at pupil-modulating formulation developers, regulatory affairs leads navigating FDA ophthalmic division pathways, formulary directors at United States payers, and ophthalmology clinic administrators in metropolitan New York and Los Angeles. Secondary validation drew from FDA 510(k) and NDA filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov presbyopia intervention records, and Medicare Part D coverage policy databases. Bottom-up prescription volume modeling triangulated against top-down therapeutic category expenditure estimates.
Segment-weighting across product type, delivery mode, end user, and application dimensions anchored volume and value outputs throughout the forecast period. Pharmaceutical Solutions received expanded weighting reflecting fastest-expanding margin pool dynamics. CAGRs derived from patent cliff modeling for incumbent surgical implants, telehealth adoption curves for prescription pathways, and aging workforce demographic projections. Formulation innovation timelines and regulatory approval velocity served as key forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA advisory committee adverse determinations or API supply disruptions in Zhejiang Province. Forecasts reflect assumptions around reimbursement pathway expansion and prescriber education campaign effectiveness. Regulatory precedent for combination product classifications and pharmacovigilance commitment scales warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market