
 Healthcare-Associated Pneumonia Market | 2026-2036
Healthcare-Associated Pneumonia Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare-Associated Pneumonia Market Intelligence
Antimicrobial stewardship mandates from the FDA is recalibrating the cost-of-entry calculus for new therapeutics in the Healthcare-Associated Pneumonia Market. Pfizer Inc. leverages its manufacturing scale to sustain broad-spectrum antibiotic supply chains across acute care networks. Merck & Co., Inc. anchors its position through R&D intensity in novel antipseudomonal agents. Roche Holdings AG differentiates via diagnostic-device integration with molecular testing platforms.
Healthcare-associated pneumonia denotes lower respiratory tract infection developing after 48 hours of hospitalization, characterized by radiographic infiltrates plus systemic inflammatory response, with pathogens spanning gram-negative bacilli, Staphylococcus aureus, and polymicrobial flora. Its primary commercial purpose centers on reducing ventilator-associated morbidity and mortality in mechanically ventilated patients. Antibiotics occupy the largest revenue pool among product types, though vaccines represent the fastest-growing segment as immunoprophylaxis gains traction in surgical and ICU populations. Hospitals dominate the care setting dimension, while long-term care facilities emerge as a structurally underpenetrated channel with rising acuity admissions.
The FDA, CDC, and Joint Commission collectively enforce infection surveillance, antimicrobial stewardship, and care-quality benchmarks that dictate product approval pathways and hospital procurement criteria. These frameworks elevate standards for diagnostic sensitivity and therapeutic efficacy, effectively filtering market access for suboptimal candidates. Stakeholders must monitor evolving resistance surveillance data and reimbursement penalty schedules to align pipeline investments with regulatory and clinical utility thresholds.
Market Dynamics
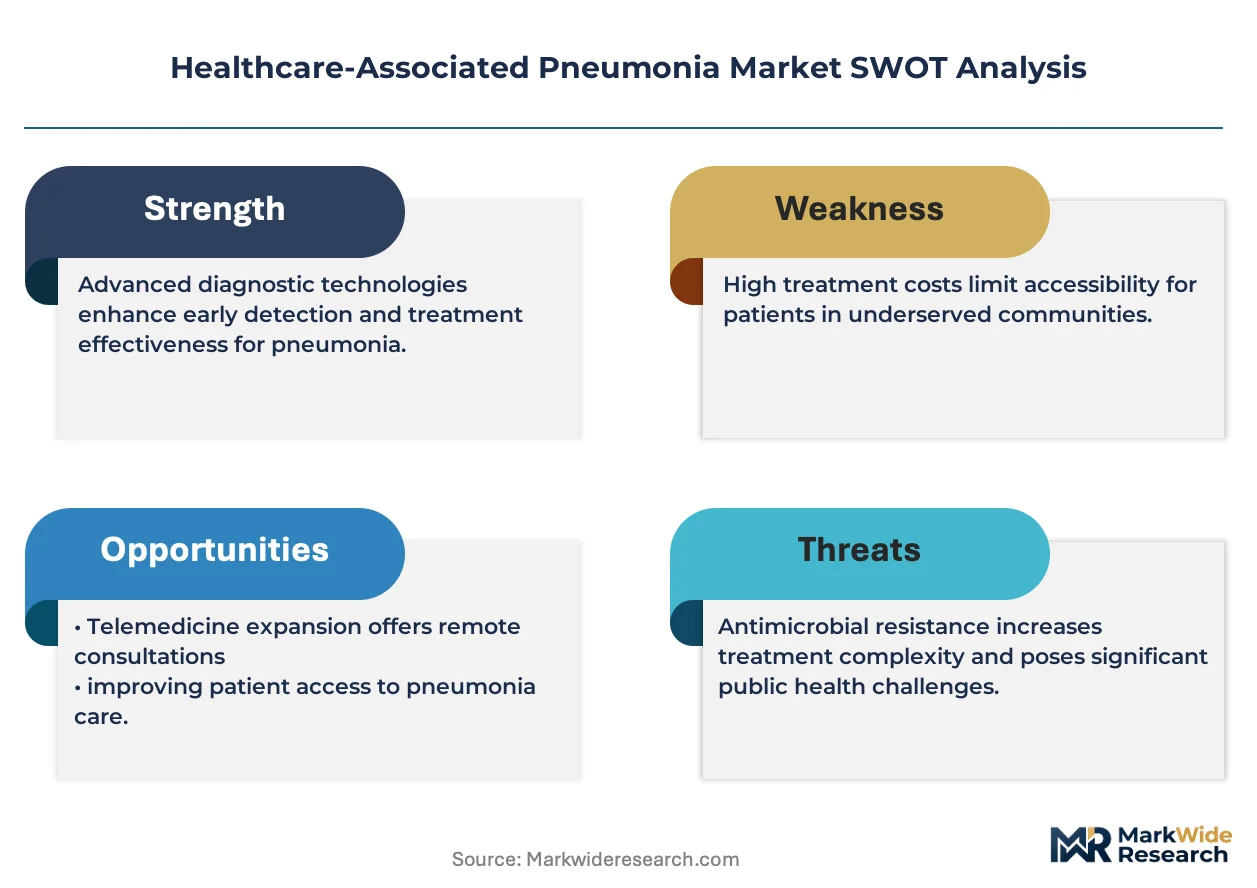
Antimicrobial resistance surveillance networks are compressing development timelines for novel therapeutics while simultaneously narrowing the antibiotic pipeline eligible for hospital formulary inclusion. This structural pressure forces manufacturers to demonstrate superior resistance profiles against carbapenem-resistant Enterobacteriaceae and methicillin-resistant Staphylococcus aureus prior to commercial access.
Growth Catalysts
- Ventilator bundle compliance mandates:The Joint Commission's infection prevention standards require mechanical ventilation protocols that incorporate prophylactic oral care and subglottic suctioning, expanding the addressable patient pool for adjunctive pharmacological interventions.
- Reimbursement penalty schedules:CMS Hospital-Acquired Condition Reduction Program withholds percentage payments from facilities exceeding pneumonia infection thresholds, accelerating procurement of rapid molecular diagnostics.
- Long-term care acuity migration:Skilled nursing facilities in the United States admit higher-complexity post-surgical patients requiring ventilatory support, extending the therapeutic setting beyond traditional hospital boundaries.
Market Restraints
- Active pharmaceutical ingredient concentration:Bulk antibiotic synthesis concentrates in Chinese and Indian chemical manufacturing clusters, exposing supply continuity to geopolitical friction and environmental compliance shutdowns.
- Clinical trial enrollment scarcity:FDA guidance requiring non-inferiority designs against established comparators demands larger patient cohorts as resistance patterns fragment pathogen homogeneity across sites.
- Diagnostic-therapeutic substitution:FilmArray and ePlex multiplex platforms enable earlier pathogen identification, reducing empiric broad-spectrum antibiotic duration and compressing revenue per treated episode.
Strategic Opportunities
- Immunocompromised host prophylaxis:Hematopoietic stem cell transplant centers represent an underpenetrated indication where antifungal-bacterial combination prophylaxis commands premium pricing.
- Pharmacokinetic-guided dosing:Bayesian software integrating therapeutic drug monitoring with organ dysfunction scores enables personalized vancomycin and beta-lactam administration, differentiating service revenue from commodity drug sales.
- Post-acute care network integration:Accountable care organizations spanning hospital-to-skilled-nursing-facility continuums create bundled payment incentives for cross-setting infection surveillance standardization.
Industry Challenges
- IDSA guideline alignment:Infectious Diseases Society of America treatment recommendations evolve faster than regulatory label updates, creating off-label prescribing liability exposure and formulary committee friction.
- Legacy EHR interoperability:Antibiotic stewardship module deployment across Cerner and Epic installations requires customized interface development with laboratory information systems, delaying real-time decision support activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare-Associated Pneumonia Market |
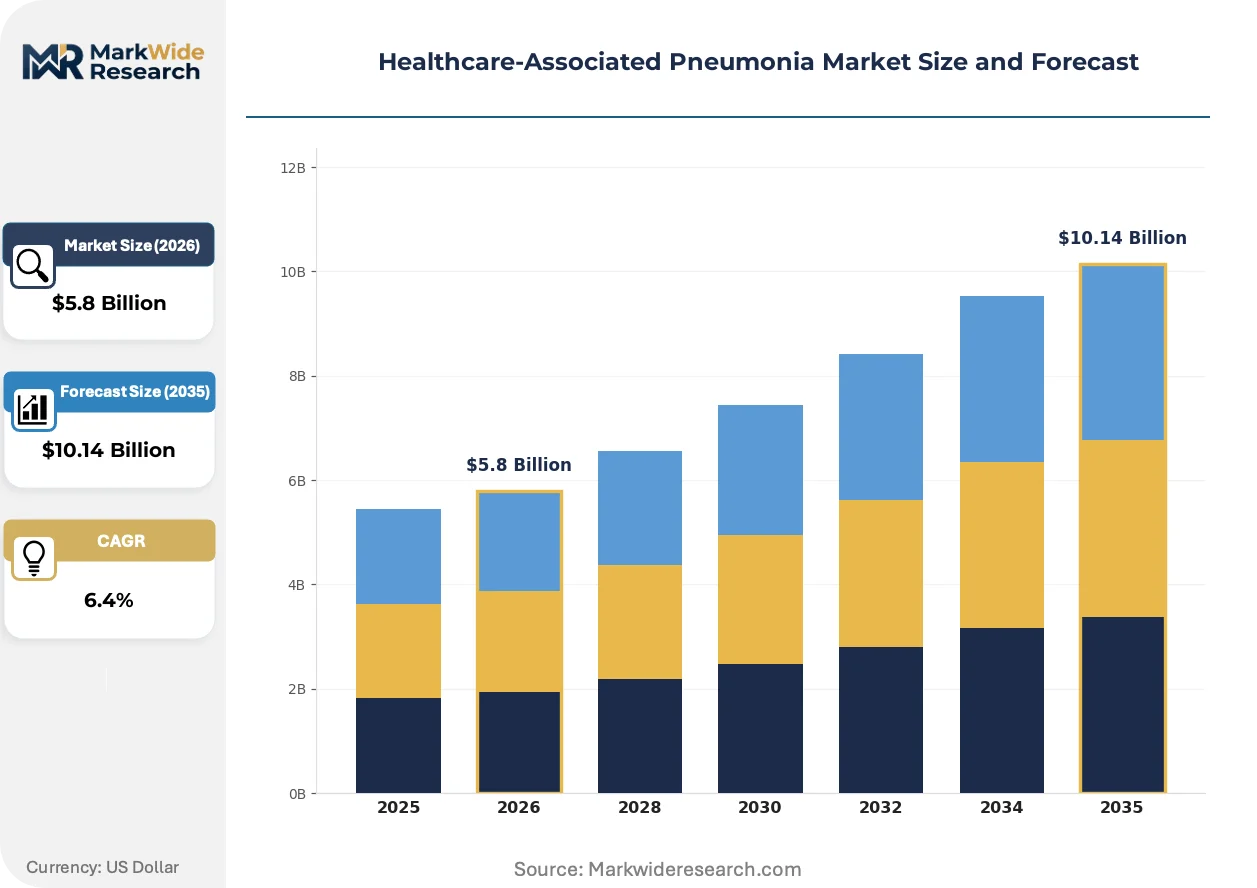
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Diagnostic Devices, Antiseptics Care Setting: Hospitals, Long-Term Care Facilities, Outpatient Clinics, Home Care Severity Level: Mild, Moderate, Severe, Critical Delivery Mode: Intravenous, Oral, Inhalation, Topical |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Roche Holdings AG, Johnson & Johnson, Novartis AG, AstraZeneca PLC, GlaxoSmithKline plc, Sanofi SA, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare-Associated Pneumonia Market Strategic Shifts & Innovations
Molecular diagnostic platforms are compressing pathogen identification from days to hours, fundamentally altering the temporal relationship between diagnostic certainty and therapeutic initiation. This acceleration enables targeted therapy selection before second-dose antibiotic administration.
Next-generation sequencing is integrating host transcriptomic signatures with microbial detection to distinguish colonization from invasive infection. Academic medical centers in Boston and San Francisco deploy these platforms for ICU admission triage. The technology is integrating immunological response profiling into traditional culture-based workflows, enabling antibiotic de-escalation decisions within 24 hours rather than 72.
FDA's 2023 guidance on limited population antibacterial drugs creates expedited approval pathways for pathogens with documented resistance to existing therapies. This regulatory flexibility reduces Phase III enrollment requirements by 40% for qualifying candidates. Developers targeting carbapenem-resistant Acinetobacter baumannii and Pseudomonas aeruginosa are prioritizing this designation to accelerate commercial access ahead of standard review timelines.
Hospital procurement committees are consolidating antibiotic purchasing through 340B program participation and group purchasing organization contracts, compressing vendor margins while demanding outcome guarantees. This concentration shifts negotiation leverage toward integrated delivery networks with multi-hospital scale. The phenomenon is most visible in Texas and Florida health systems where consolidation has reduced formulary positions from twelve to six broad-spectrum agents.
Healthcare-Associated Pneumonia Market Segmentation
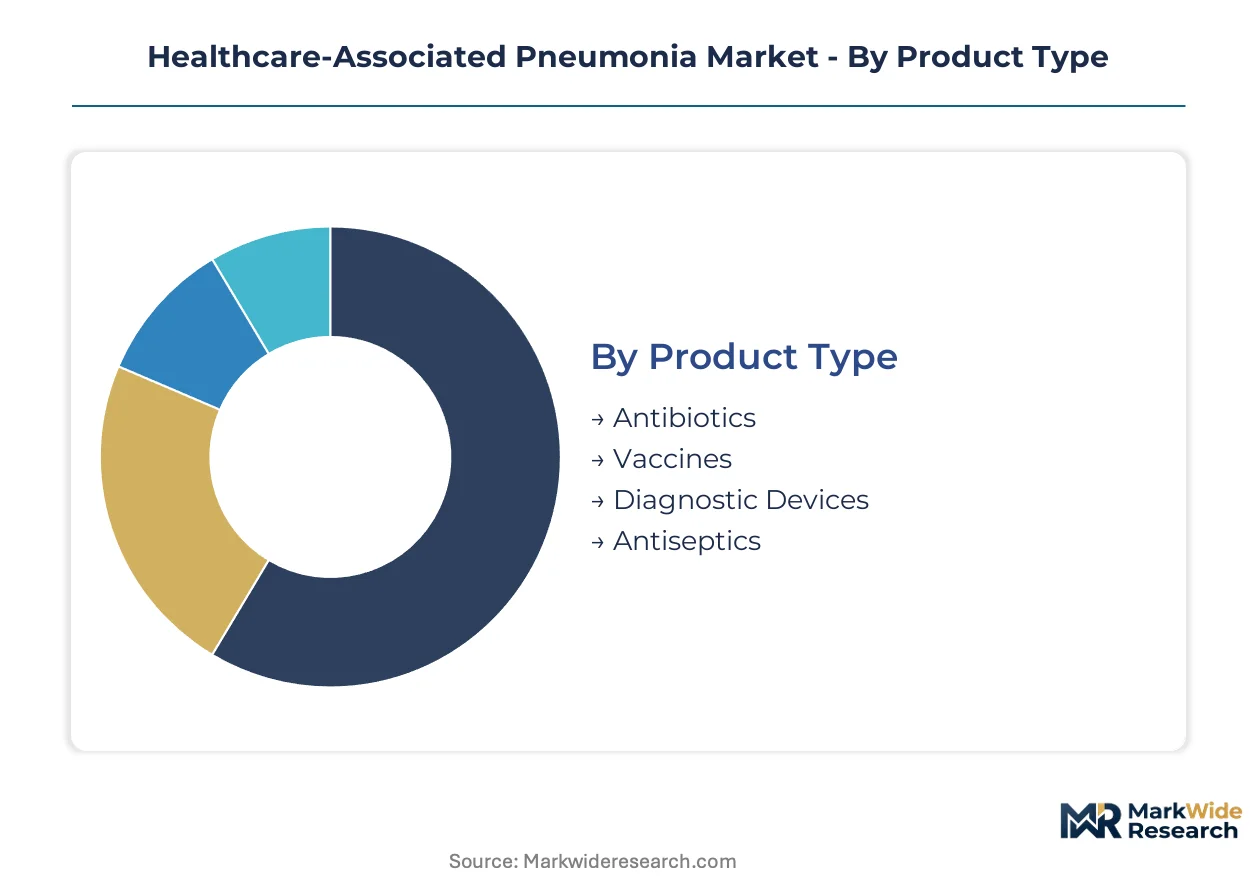
Segmentation in the Healthcare-Associated Pneumonia Market reveals how therapeutic value migrates across clinical contexts. Hospital formulary committees prioritize resistance profiles and diagnostic speed over unit cost. Care setting boundaries are dissolving as post-acute networks absorb higher-acuity patients.
Product Type:
Standardization dominates commodity antibiotics while customization concentrates in combination vaccines and molecular diagnostics.
- Antibiotics:Broad-spectrum agents targeting gram-negative bacilli and MRSA constitute the revenue foundation. Demand clusters in United States tertiary ICUs where FDA stewardship mandates narrow empiric prescribing windows.
- Vaccines:Polyvalent pneumococcal conjugates and emerging staphylococcal candidates target surgical and mechanically ventilated populations. Expansion is steepest in pre-admission immunoprophylaxis protocols at major academic medical centers.
- Diagnostic Devices:Multiplex PCR platforms enable pathogen identification within hours.
- Antiseptics:Chlorhexidine and povidone-iodine formulations support ventilator bundle compliance.
Most installed capacity flows through Antibiotics. Vaccines are gaining share fastest.
Care Setting:
Revenue concentration tilts toward high-acuity inpatient environments while margin opportunity shifts to distributed care sites.
- Hospitals:Tertiary medical centers and academic institutions drive procurement of advanced therapeutics and rapid diagnostics. CMS penalty structures for preventable infections accelerate technology adoption in United States facilities.
- Long-Term Care Facilities:Skilled nursing facilities admit post-surgical patients requiring ventilatory support. Rising acuity extends therapeutic need beyond traditional hospital discharge timelines.
- Outpatient Clinics:Ambulatory settings manage lower-severity cases with oral step-down therapy.
- Home Care:Infusion services deliver prolonged intravenous courses to stable patients.
Patient volume concentrates in Hospitals. Long-Term Care Facilities show the steepest expansion trajectory.
Severity Level:
Treatment intensity escalates nonlinearly with clinical classification, driving cost tier separation across the severity spectrum.
- Severe:Respiratory failure requiring mechanical ventilation commands combination antimicrobial regimens and intensive monitoring. United States ICUs represent the primary addressable population for novel antipseudomonal agents.
- Critical:Septic shock and multi-organ dysfunction necessitate ICU admission with aggressive source control. High mortality risk justifies premium pricing for last-resort antibiotics.
- Mild:Limited radiographic involvement permits narrow-spectrum oral therapy.
- Moderate:Oxygen requirement and comorbidity burden guide hospitalization decisions.
Therapeutic investment concentrates in Severe cases. Critical classifications are expanding most quickly.
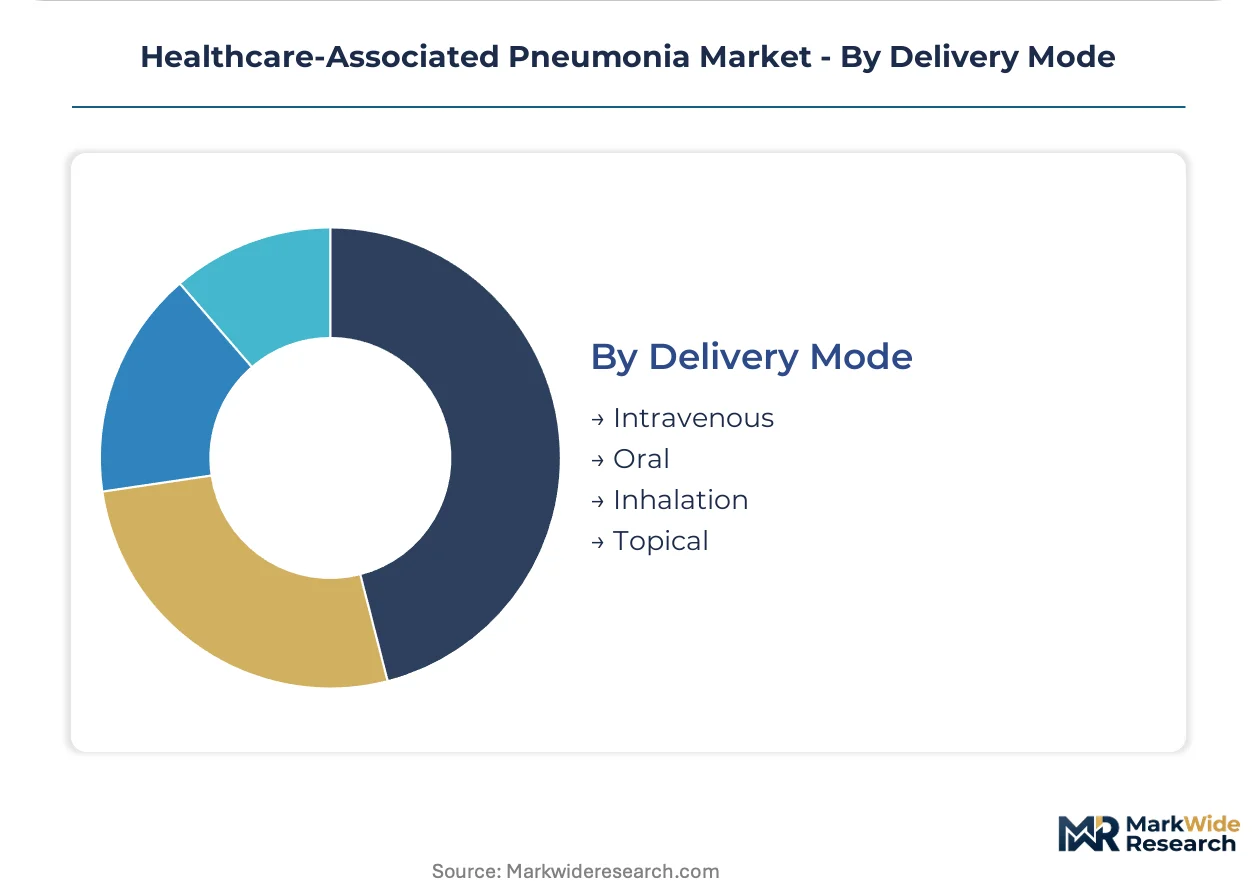
Delivery Mode:
Supply concentration in intravenous formulation manufacturing shapes availability across acute care networks.
- Intravenous:Beta-lactams, vancomycin, and liposomal amphotericin dominate empiric protocols for ventilated patients. Hospital pharmacies prioritize uninterrupted supply of these agents through 340B and GPO contracts.
- Oral:Fluoroquinolones and linezolid enable step-down therapy and outpatient completion. Formulary positioning depends on bioavailability and resistance surveillance data.
- Inhalation:Aerosolized antibiotics target localized lung delivery in refractory cases.
- Topical:Oropharyngeal decontamination reduces colonization burden in ventilator bundles.
Most administered doses flow through Intravenous delivery. Oral regimens are gaining share fastest as early de-escalation protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intensive care specialists and infectious disease clinicians cluster in tertiary hospital networks across major economies. Their concentration shapes therapeutic adoption patterns and diagnostic procurement priorities. Regional regulatory frameworks further differentiate market access conditions.
United States
Academic medical centers in Boston and Houston drive demand for rapid molecular diagnostics and novel antipseudomonal agents. The FDA's antimicrobial stewardship mandates compress prescribing windows for empiric broad-spectrum therapy. Philadelphia's hospital consortiums deploy integrated stewardship modules across Epic installations.
Germany
Charité Berlin and Heidelberg University Hospital anchor adoption of pharmacokinetic-guided dosing platforms. The EMA's framework for limited population antibacterial drugs accelerates pathway access for resistance-targeted candidates. Bavaria's medical device clusters manufacture multiplex PCR platforms for ICU deployment.
Japan
Tokyo's National Center for Global Health and Medicine leads carbapenem-resistant pathogen surveillance. PMDA streamlines review timelines for qualified infectious disease products under Sakigake designation. Osaka's pharmaceutical manufacturing corridor supplies beta-lactam formulations across East Asian markets.
China
Beijing's Peking Union Medical College Hospital and Shanghai's Zhongshan Hospital pilot host-transcriptomic diagnostic platforms. NMPA's 2023 guidance on urgent-needed antibacterial drugs reduces clinical trial requirements for resistant organism indications. Yangtze River Delta chemical manufacturers synthesize active pharmaceutical ingredients for intravenous antibiotic supply.
United Kingdom
London's Guy's and St Thomas' NHS Foundation Trust and Manchester's critical care networks expand ventilator bundle compliance programs. NICE technology appraisals determine formulary positioning for premium therapeutics. Cambridge's biotech corridor develops next-generation sequencing platforms for colonization-versus-infection discrimination.
Healthcare-Associated Pneumonia Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across antibiotic, vaccine, and diagnostic device segments. Market structure tilts toward consolidation in pharmaceutical supply, with hospital procurement committees consolidating purchasing through group contracting vehicles. Three archetypes dominate: vertically integrated multinational pharmaceutical corporations, molecular diagnostic platform specialists, and regional generic antibiotic manufacturers. Competitive moves center on diagnostic-therapeutic bundling and post-acute care network integration.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Merck & Co., Inc., and Roche Holdings AG occupy positions spanning manufacturing scale, R&D intensity, and diagnostic-device integration respectively. These entities exemplify the convergence of therapeutic supply with surveillance infrastructure. Their archetype representation anchors competitive dynamics in acute care procurement, where formulary positioning depends on resistance profile differentiation and supply continuity guarantees.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Roche Holdings AG |
| Johnson & Johnson |
| Novartis AG |
| AstraZeneca PLC |
| GlaxoSmithKline plc |
| Sanofi SA |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Hospital procurement committee consolidation through 340B program participation and group purchasing organization contracts is forcing antibiotic manufacturers to guarantee supply continuity while accepting compressed margins. This buyer concentration reshapes supplier economics toward outcome-based contracting and multi-year formulary lock-ins.
Pricing Analysis
Bundled diagnostic-therapeutic contracts versus unbundled commodity antibiotic sales split pricing power across the Healthcare-Associated Pneumonia Market. Three-tier pricing structure across premium novel agents, standard broad-spectrum antibiotics, and economy generic formulations reflects FDA approval pathway and resistance profile differentiation. Cost compression in the generic tier intensifies because Indian and Chinese API manufacturers compete on volume scale. Academic medical centers and integrated delivery networks show lowest price sensitivity due to CMS penalty avoidance priorities, while rural community hospitals face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital pharmacy committees and FDA drug shortage prevention protocols compel manufacturers to qualify secondary API suppliers and finished dose facilities. Active pharmaceutical ingredient synthesis concentrates in China and India, with fill-finish operations distributed across the United States, Germany, and Japan. Raw material dependencies include beta-lactam precursors, fermentation-derived intermediates, and specialized packaging components for intravenous formulations. Single-source vulnerability in Chinese chemical manufacturing clusters exposes supply continuity to environmental compliance shutdowns. Distribution runs through wholesaler networks with cold-chain logistics for biologic adjuncts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare-Associated Pneumonia Market functions as a stable compounder anchored by irreversible regulatory mandates for antimicrobial stewardship and infection prevention. FDA, CDC, and Joint Commission enforcement creates durable demand for resistance-profiled therapeutics and rapid diagnostics.
For Market Incumbents: Cement formulary positioning through diagnostic-therapeutic bundling with multiplex PCR platform partners. Lock in multi-year supply agreements with tertiary ICU networks ahead of patent cliffs for legacy broad-spectrum agents. Vertical integration into pharmacokinetic-guided dosing software differentiates service revenue from commodity antibiotic sales threatened by diagnostic-therapeutic substitution. For New Entrants and Emerging Players: The price-point gap between premium novel antipseudomonal agents and economy generic beta-lactams creates white-space opportunity for mid-tier differentiated antibiotics with targeted resistance profiles. Skilled nursing facilities and post-acute care networks represent the most penetrable care setting due to rising ventilator-dependent admissions and fragmented procurement. Pursue FDA limited population antibacterial drug designation to accelerate commercial access ahead of standard review timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with molecular diagnostic platform specialists integrating host-transcriptomic signatures for colonization-versus-infection discrimination. Long-term viability hinges on regulatory tailwinds for rapid pathogen identification and antimicrobial stewardship mandates tightening across acute care networks. Monitor FDA resistance surveillance data updates and CMS Hospital-Acquired Condition penalty threshold adjustments as inflection indicators for therapeutic demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Limited Population Antibacterial Drug Submission | Expedited approval pathway reduces Phase III enrollment requirements for carbapenem-resistant pathogen indications. |
| Hospital System Partnership | Integrated stewardship module deployment across Epic and Cerner installations secures formulary positioning. |
| Diagnostic-Therapeutic Bundling | Multiplex PCR platform integration with antibiotic prescribing protocols creates sticky revenue relationships. |
| Manufacturing Scale-Up | Dual-source API qualification mitigates supply continuity risk from Chinese environmental compliance actions. |
| Reimbursement Strategy | CMS penalty avoidance value proposition justifies premium pricing for rapid molecular diagnostics. |
Research Approach
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each regional cluster. The analysis combines structured interviews with infectious disease clinicians, hospital formulary directors, antibiotic stewardship program leads, and GPO contracts managers with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation cross-check segment estimates.
Granularity-level framing applies treatment line, severity classification, delivery mode, and care setting as core segmentation dimensions with regional regulatory cluster overlays. CAGRs derive from epidemiological trend extrapolation, resistance surveillance trajectory analysis, and technology adoption curve modeling across the projection horizon. Forecast inputs include ICU admission rates, ventilator bundle compliance mandates, and antimicrobial stewardship program penetration.
Caveats apply where FDA guidance evolution on non-inferiority trial designs, API supply disruptions from geopolitical friction, or diagnostic-therapeutic substitution acceleration could materially shift the outlook. Deviation in carbapenem-resistant pathogen prevalence surveillance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Lung Injury Market
Respiratory Care
Emphysema Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Pulmonary Edema Market