
 Respiratory Measurement Devices Market | 2026-2036
Respiratory Measurement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Measurement Devices Market Outlook
ISO 13485 certification is reorganizing competitive access in respiratory diagnostics, filtering out contract manufacturers lacking documented quality management systems. Koninklijke Philips NV leverages its integrated imaging-to-ventilation portfolio to dominate hospital enterprise contracts across Western Europe. ResMed sustains technology leadership in cloud-connected home respiratory monitoring through its SaaS-integrated device architecture. Drägerwerk AG & Co. KGaA anchors critical care measurement workflows in German-speaking markets with anesthesia-to-ICU system interoperability.
Respiratory measurement devices comprise instruments that quantify pulmonary function, gas exchange, or airway mechanics through pressure transduction, optical spectroscopy, or ultrasonic flow sensing, typically resolving breath volumes to ±3% accuracy per ATS/ERS standards for diagnostic spirometry. These instruments serve chronic disease management, perioperative monitoring, and occupational health screening by delivering reproducible lung function metrics that guide therapeutic escalation or de-escalation. Pulse oximetry and wireless-enabled capnography represent the fastest-expanding technology clusters, driven by ambulatory care decentralization and remote patient monitoring reimbursement tailwinds. Home care end users command expanding margin pools as channel economics shift from capital equipment sales toward disposable sensor recurring revenue models.
FDA 510(k) clearance pathways and EU MDR Class IIa conformity requirements shape product development timelines, testing burdens, and post-market surveillance obligations for manufacturers seeking dual-territory commercialization. The EPA's Good Laboratory Practice standards for inhalation toxicology further constrain research-application device validation protocols in preclinical pharmaceutical settings. Stakeholders must monitor evolving CMS remote therapeutic monitoring billing codes and NICE technology appraisal frameworks to calibrate portfolio investments between acute hospital and decentralized care settings.
Market Dynamics
Hospital procurement of wireless spirometry systems is accelerating as healthcare networks modernize respiratory wards, while FDA premarket notification requirements for Class II diagnostic devices tighten quality thresholds for new entrants seeking commercialization pathways.
Growth Catalysts
- CMS Remote Therapeutic Monitoring Codes:Reimbursement tailwinds for ambulatory pulse oximetry and capnography expand addressable markets for home care device manufacturers.
- Pulmonary Rehabilitation Reimbursement:Germany's statutory Diagnosis-Related Group frameworks concentrate demand for diagnostic spirometry systems in acute care networks.
- Cloud-Connected Architecture:SaaS-integrated respiratory monitors enable recurring revenue models that displace capital equipment sales in chronic disease management.
Market Restraints
- EU MDR Class IIa Conformity Burden:Extended testing timelines and post-market surveillance obligations compress development budgets for dual-territory manufacturers.
- Optical Sensor Supply Concentration:Dependence on specialized photodiode foundries in East Asia creates input vulnerability for pulse oximetry producers.
- ATS/ERS Accuracy Standards:The ±3% diagnostic spirometry tolerance threshold limits cost-down engineering options for volume-tier competitors.
Strategic Opportunities
- Perioperative Monitoring Expansion:Anesthesia-to-ICU system interoperability creates white space for integrated measurement workflows in German-speaking critical care markets.
- Occupational Health Screening Mandates:EPA Good Laboratory Practice standards for inhalation toxicology research drive validation-protocol demand in pharmaceutical preclinical settings.
- Disposable Sensor Economics:Channel economics pivot toward recurring revenue from single-use flow sensors, opening margin pools outside traditional equipment leasing.
Industry Challenges
- ISO 13485 Certification Timeline:Documented quality management system requirements filter out contract manufacturers lacking respiratory-specific regulatory expertise.
- Legacy System Interoperability:Hospital enterprise contracts demand backward compatibility with existing ventilation platforms, complicating new entrant integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Measurement Devices Market |
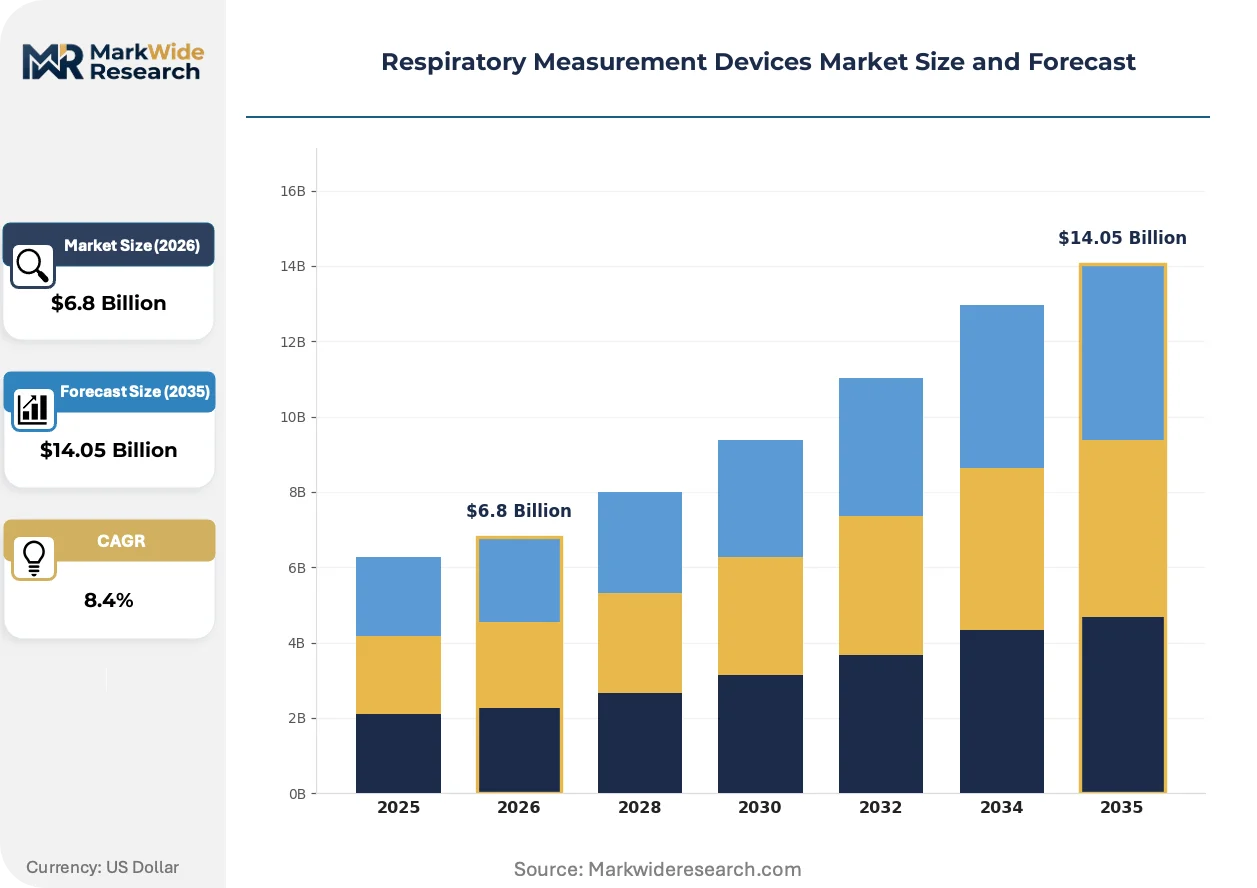
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirometers, Peak Flow Meters, Pulse Oximeters, Capnometers End User: Hospitals, Clinics, Home Care, Diagnostic Labs Technology: Digital, Analog, Wireless, Portable Application: Chronic Obstructive Pulmonary Disease, Asthma, Fitness Monitoring, Research |
| Companies Covered | Koninklijke Philips NV, ResMed, Medtronic, GE Healthcare, Drägerwerk AG & Co. KGaA, Siemens Healthineers, Nihon Kohden Corporation, Vyaire Medical, Hamilton Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Measurement Devices Market Strategic Shifts
Wireless-enabled respiratory diagnostics are fragmenting traditional hospital-centric supply chains, while regulatory convergence between FDA 510(k) pathways and EU MDR frameworks compresses product development calendars.
Ultrasonic flow sensing is decomposing conventional pressure-transduction spirometry by enabling turbine-free measurement of breath volumes. German hospital procurement teams are specifying ultrasonic platforms for new ward installations. The technology is decomposing incumbent sensor supply relationships and enabling Asian contract manufacturers to enter diagnostic-grade markets.
The EU MDR Class IIa conformity assessment is extending technical documentation requirements for respiratory measurement devices marketed in Europe. Manufacturers face expanded clinical evaluation obligations and notified body queue delays. German device producers are responding by concentrating regulatory affairs resources on legacy product line renewals rather than novel platform launches.
Hospital buying committees are consolidating vendor relationships around integrated imaging-to-ventilation portfolios. Single-source procurement contracts displace standalone spirometry suppliers in Western European acute care networks. This concentration is most visible in Germany, where Diagnosis-Related Group reimbursement frameworks incentivize enterprise-level equipment standardization.
Respiratory Measurement Devices Market Segmentation
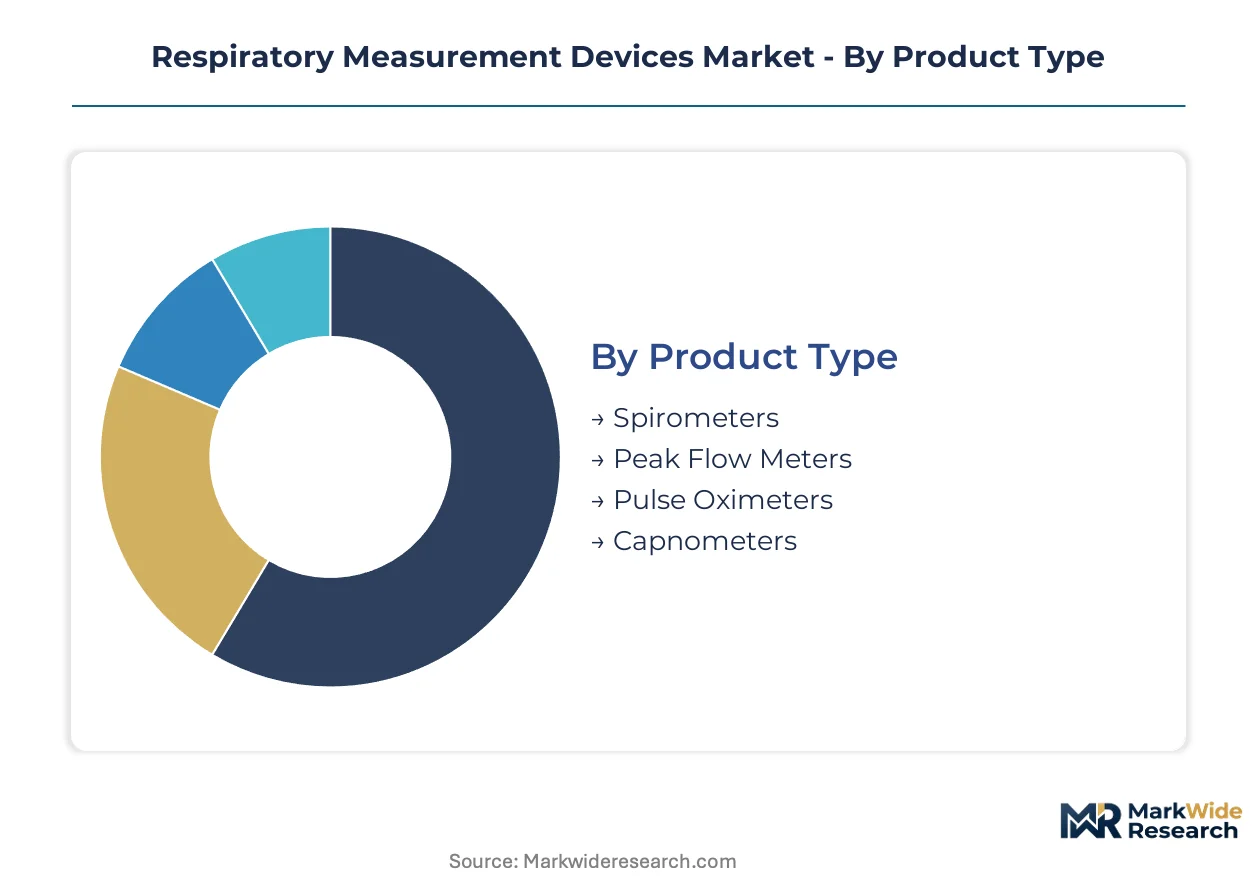
Respiratory measurement devices fragment across four critical dimensions that determine reimbursement pathways, regulatory classification, and channel economics. Product type dictates technical standards and accuracy requirements. End user concentration shapes pricing power and service attach rates. Technology architecture separates capital equipment from recurring revenue models. Application focus determines clinical validation burdens and addressable patient populations.
Product Type:
Margin pools concentrate in devices that combine diagnostic-grade accuracy with disposable sensor economics, particularly where cloud connectivity enables SaaS revenue layering.
- Spirometers:Pressure-transduction and ultrasonic flow-sensing instruments measure forced expiratory volumes per ATS/ERS ±3% accuracy standards. German hospital procurement teams specify wireless-enabled platforms for pulmonary rehabilitation wards under Diagnosis-Related Group reimbursement frameworks.
- Pulse Oximeters:Optical spectroscopy devices using red and infrared LED wavelengths calculate arterial oxygen saturation non-invasively. Home care demand concentrates in the US where CMS Remote Therapeutic Monitoring billing codes reimburse ambulatory pulse oximetry for chronic respiratory conditions.
- Peak Flow Meters:Mechanical or digital devices measuring peak expiratory flow rate for asthma self-management. Compact form factors dominate retail pharmacy distribution in patient-directed markets.
- Capnometers:Infrared or mainstream sensors quantify end-tidal carbon dioxide for perioperative and critical care monitoring. Integration with anesthesia workstations drives hospital enterprise contract specifications.
The dominant share belongs to spirometers, while pulse oximeters are closing the gap fastest.
End User:
Channel economics diverge sharply between acute care capital budgets and home care recurring consumables, with reimbursement policy determining viable business models.
- Hospitals:Enterprise procurement contracts demand ISO 13485-certified devices with HL7 interoperability and backward compatibility with existing ventilation platforms. Western European networks consolidate vendor relationships around integrated imaging-to-ventilation portfolios.
- Home Care:Wireless-enabled devices with cloud-connected architecture displace traditional equipment sales through disposable sensor recurring revenue models. Patient adherence data becomes a secondary monetization stream for manufacturers.
- Clinics:Point-of-care diagnostic requirements favor portable platforms with rapid calibration cycles and minimal maintenance protocols.
- Diagnostic Labs:Centralized pulmonary function testing demands high-throughput systems with automated quality control and centralized data management.
Hospitals retain the largest revenue concentration, though home care is expanding most quickly as reimbursement shifts toward decentralized monitoring.
Technology:
Architecture choices determine regulatory pathway complexity, with wireless platforms facing FCC and EU radio equipment directives alongside medical device frameworks.
- Wireless:Bluetooth and proprietary radio protocols enable real-time data transmission to cloud platforms and electronic health records. FDA 510(k) clearance pathways tighten electromagnetic compatibility testing requirements for connected respiratory monitors.
- Digital:Microprocessor-controlled signal processing replaces analog circuitry for improved measurement stability and automated error detection.
- Portable:Battery-operated designs with compact form factors serve ambulatory and emergency settings where mains power is unavailable.
- Analog:Legacy electromechanical systems persist in cost-sensitive markets and occupational health screening programs with minimal connectivity requirements.
Wireless platforms command premium positioning, while portable configurations are gaining share fastest in prehospital and resource-limited settings.
Application:
Clinical validation requirements scale with diagnostic stakes, with pharmaceutical research applications demanding EPA Good Laboratory Practice compliance.
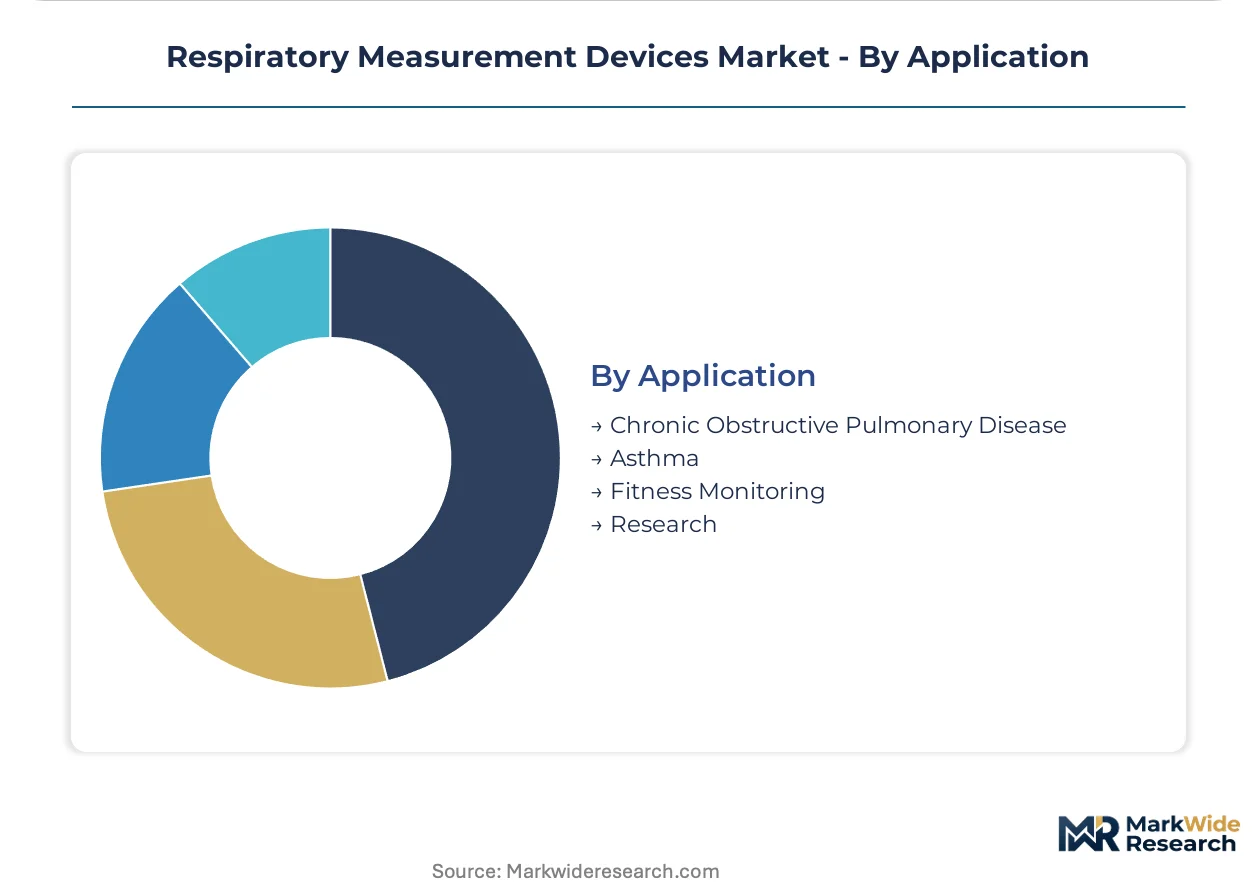
- Chronic Obstructive Pulmonary Disease:Longitudinal spirometry and pulse oximetry track disease progression and guide therapeutic escalation. Medicare coverage determinations in the US specify device performance criteria for reimbursement eligibility.
- Asthma:Peak flow monitoring and fractional exhaled nitric oxide measurement support self-management and medication adjustment protocols. Pediatric applications drive demand for child-appropriate interfaces and gamified adherence tools.
- Fitness Monitoring:Consumer-grade pulse oximetry and respiratory rate sensing integrate with wearable platforms for athletic performance optimization. Regulatory classification as general wellness or medical device varies by jurisdiction.
- Research:Inhalation toxicology studies require calibrated exposure systems meeting EPA Good Laboratory Practice standards for preclinical pharmaceutical validation.
Chronic Obstructive Pulmonary Disease applications anchor revenue, while fitness monitoring is climbing the fastest as consumer health technology converges with clinical-grade sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory Diagnosis-Related Group reimbursement frameworks concentrate pulmonary rehabilitation demand, while FDA 510(k) pathways and CMS Remote Therapeutic Monitoring codes reshape commercial priorities in the United States.
United States
CMS Remote Therapeutic Monitoring billing codes reimburse ambulatory pulse oximetry and capnography for chronic respiratory conditions, expanding home care addressable markets. FDA electromagnetic compatibility testing requirements tighten for wireless-connected respiratory monitors under 510(k) clearance pathways. The Boston-Cambridge medical device corridor anchors cloud-connected diagnostic platform development.
Germany
Diagnosis-Related Group frameworks incentivize enterprise-level equipment standardization across acute care networks. EU MDR Class IIa conformity assessments extend technical documentation timelines for respiratory devices. The Ruhr-Rhine industrial corridor concentrates anesthesia-to-ICU system interoperability manufacturing.
China
NMPA medical device registration requirements accelerate for wireless respiratory monitors under updated Class II technical review guidelines. Dual carbon goals drive energy-efficient manufacturing standards for diagnostic equipment producers. The Yangtze River Delta cluster specializes in photodiode foundry supply for pulse oximetry sensor modules.
Japan
METI industrial standards promote miniaturized respiratory sensors for home care applications. PMDA quality management system inspections align with MHLW post-market surveillance requirements for connected devices. The Kansai-Osaka medical technology corridor concentrates ultrasonic flow sensing R&D.
India
CDSCO medical device rules classify respiratory measurement systems under notified device categories requiring import license or manufacturing authorization. PLI scheme incentives attract domestic production of pulse oximetry components. Karnataka's Bengaluru-Tumkur corridor hosts contract manufacturing for portable spirometry platforms.
Respiratory Measurement Devices Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with integrated imaging-to-ventilation portfolios. Consolidation pressure intensifies as hospital buying committees demand single-source procurement contracts with backward-compatible interoperability. Two strategic archetypes dominate: enterprise-scale platform integrators and cloud-native home monitoring specialists. Competitive moves center on regulatory affairs resource concentration and SaaS-integrated device architecture licensing.
Within the diversified medical technology tier, Koninklijke Philips NV and Siemens Healthineers exemplify enterprise-scale platform integrators with imaging-to-ventilation portfolio breadth. ResMed occupies a position among cloud-native specialists leveraging SaaS-integrated architecture for recurring revenue models. Drägerwerk AG & Co. KGaA anchors the anesthesia-to-ICU interoperability segment in German-speaking critical care markets. Medtronic and GE Healthcare sit within the acute care monitoring tier, representing capital equipment leasing archetypes. These five entities collectively illustrate the competitive spectrum from hospital enterprise contracts to decentralized home care channels.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| ResMed |
| Medtronic |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Siemens Healthineers |
| Nihon Kohden Corporation |
| Vyaire Medical |
| Hamilton Medical |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price tiering simultaneously, forcing contract manufacturers to absorb documentation costs while OEMs extract premiums for audited quality management systems. Hospital procurement committees leverage this bifurcation to squeeze mid-tier vendors on unit pricing while locking in enterprise contracts with certified incumbents.
Pricing Analysis
Cost-plus contracts with photodiode indexation dominate pulse oximetry supply agreements, tying sensor module pricing to East Asian foundry output costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from wellness-grade consumer devices and uncertified occupational screening tools. Cost compression in standard-tier spirometry intensifies because ultrasonic flow sensing enables Asian contract manufacturers to bypass incumbent turbine supply relationships. Home care channels exhibit highest price sensitivity due to direct patient out-of-pocket exposure, while German hospital networks show lowest sensitivity where Diagnosis-Related Group reimbursement frameworks decouple capital procurement from operational budgets.
Supply Chain Analysis
Just-in-time inventory strategies dominate wireless-enabled device assembly, though strategic stockpiling of specialized photodiodes persists among pulse oximetry producers exposed to single-source foundry concentration. Component sourcing draws from China's Yangtze River Delta for sensor modules, Germany's Ruhr-Rhine corridor for anesthesia workstation integration hardware, and Japan's Kansai-Osaka cluster for ultrasonic transducer elements. Single-source vulnerability concentrates in epitaxial wafer supply for near-infrared LEDs. Distribution runs through hospital GPO contracts in Western Europe, direct-to-patient e-commerce in North American home care, and government tender processes in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The respiratory measurement devices market sits in early-cycle expansion, with CMS Remote Therapeutic Monitoring reimbursement codes accelerating ambulatory pulse oximetry penetration beyond traditional hospital-centric deployment models.
For Market Incumbents: Shield installed base margins by deepening backward integration into disposable flow sensor production, capturing recurring revenue streams that SaaS-integrated architectures unlock. Accelerate ISO 13485 certification timelines for contract manufacturing partners before EU MDR Class IIa conformity assessments filter out unqualified suppliers. Prioritize HL7 interoperability investments that hospital buying committees mandate for enterprise contract renewal.
For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways offer fastest clearance for wireless spirometry platforms with predicate device alignment, opening acute care access without multi-year PMA timelines. Target German pulmonary rehabilitation wards where Diagnosis-Related Group reimbursement concentrates procurement authority in standardized equipment tenders. Pursue white-label partnerships with established cloud platform providers to bypass SaaS infrastructure build-out costs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized respiratory device divisions lacking cloud connectivity roadmaps. Five-to-ten-year viability favors platforms with recurring consumable economics over capital equipment leasing models. Monitor CMS billing code expansion for capnography and fractional exhaled nitric oxide as inflection signal for home care addressable market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Conformity Pathway | Accelerated technical documentation investment reduces notified body queue exposure for German manufacturers. |
| Cloud Platform Integration Partnership | SaaS-integrated device architecture enables recurring revenue displacement of capital equipment sales in home care. |
| Photodiode Supply Agreement | Long-term foundry contracts mitigate single-source vulnerability in East Asian sensor module production. |
| Hospital GPO Contract Expansion | Enterprise procurement consolidation in Western European networks locks out standalone spirometry competitors. |
| Reimbursement Strategy Development | CMS Remote Therapeutic Monitoring code alignment expands ambulatory pulse oximetry addressable markets. |
Study Parameters
Operator-level perspectives from hospital biomedical engineers, GPO contracts managers, pulmonary rehabilitation clinicians, and home care device reimbursement specialists anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, CMS Medicare billing code determinations, and hospital procurement contract registries. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, end user, technology architecture, and application dimensions.
Sensitivity analysis tested forecast robustness across reimbursement policy scenarios, regulatory timeline delays, and supply chain disruption assumptions over the projection horizon. Segmentation modeling captured spirometry, pulse oximetry, capnography, and peak flow measurement platforms across hospital, home care, clinic, and diagnostic lab channels. CAGRs derived from weighted average of historical volume trends, penetration rate assumptions, and price trajectory modeling. Forecast inputs incorporated wireless connectivity adoption curves and disposable sensor attach rate evolution.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion or EU MDR notified body capacity constraints would require recalibration. Forecasts reflect documented assumptions regarding pulmonary rehabilitation program growth and cloud platform interoperability standards. Revision becomes warranted when FDA 510(k) clearance timelines for wireless devices exceed historical medians or photodiode foundry concentration triggers supply allocation protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Emphysema Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Lung Injury Market