
 Global Respiratory Disposable Market | 2026-2036
Global Respiratory Disposable Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory Disposable Market Foresight
Home care providers is reorganizing demand patterns across the respiratory disposable landscape, pulling procurement decisions away from centralized hospital supply chains. Medtronic leverages its integrated critical care portfolio to sustain direct channel relationships with outpatient respiratory clinics. Fisher & Paykel Healthcare anchors its position through specialized humidification interfaces that pair with disposable circuits. Drägerwerk AG & Co. KGaA differentiates via industrial safety certifications that extend its reach beyond clinical settings.
Respiratory disposables encompass single-use devices—including masks, filters, breathing circuits, and oxygen delivery accessories—manufactured from non-woven polypropylene, thermoplastic elastomers, or medical-grade silicone, designed to maintain sterile airway management and prevent cross-contamination between patients. Their primary purpose spans mechanical ventilation support, oxygen therapy delivery, and airborne pathogen protection across clinical and occupational environments. N95 Respirators and Surgical Masks dominate the product type landscape, with antiviral variants capturing expanding margin pools as filtration performance standards tighten. Hospital Settings remain the largest application segment, though Home Care represents the fastest-growing channel as payors push for shorter inpatient stays.
The FDA governs 510(k) clearance pathways for new disposable respiratory devices, while the EU MDR and REACH frameworks impose biocompatibility and chemical disclosure requirements on manufacturers serving European markets. OSHA's respiratory protection standards in the United States mandate fit testing and compliance documentation for workplace N95 deployment, directly influencing institutional purchasing volumes. Stakeholders must monitor how diverging national stockpiling strategies and pandemic preparedness frameworks reshape tender specifications and long-term supply agreements across key markets.
Market Dynamics
Post-acute care decentralization is pulling procurement authority from hospital central supply offices toward distributed home care networks, fragmenting volume commitments and forcing manufacturers to reconfigure distribution architectures around last-mile delivery rather than bulk institutional contracts.
Growth Catalysts
- OSHA respiratory protection mandates:Workplace fit-testing requirements and compliance documentation obligations in the United States sustain institutional purchasing volumes for N95 respirators across industrial safety programs.
- EU MDR biocompatibility frameworks:Stricter chemical disclosure and material safety standards for devices contacting mucous membranes are accelerating replacement cycles as older products face compliance sunset.
- Non-woven polypropylene filtration advances:Electrostatic charging improvements in meltblown media are extending particulate capture efficiency without corresponding pressure-drop penalties, expanding clinical application ranges.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer production clusters in Germany and Japan create input vulnerability for high-performance mask skirt and seal components.
- REACH chemical registration burdens:Novel polymer additives for antiviral surface treatments face extended toxicity evaluation timelines, delaying product differentiation.
- Reusable elastomeric respirator substitution:Industrial buyers facing extended N95 lead times are retrofitting half-mask platforms with P100 cartridges, compressing disposable volume in occupational segments.
Strategic Opportunities
- India outpatient respiratory clinic expansion:Government diagnostic center proliferation under national health mission programs is creating first-time institutional demand for humidification circuits and oxygen delivery accessories.
- Antiviral coating convergence with nanofiber substrates:Copper-ion and quaternary ammonium surface treatments integrated into electrospun media are opening premium positioning in immunocompromised patient settings.
- Direct-to-patient subscription channels:Sleep apnea and COPD home therapy providers are bypassing durable medical equipment intermediaries through automated resupply platforms.
Industry Challenges
- ISO 18562 biocompatibility testing bottlenecks:Respiratory gas pathway evaluation capacity constraints at notified bodies are extending 510(k) clearance timelines for novel mask designs.
- Thermoplastic elastomer compounding expertise scarcity:Formulation chemistry talent capable of balancing resilience, sterilization stability, and skin-contact safety remains concentrated among legacy medical device material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory Disposable Market |
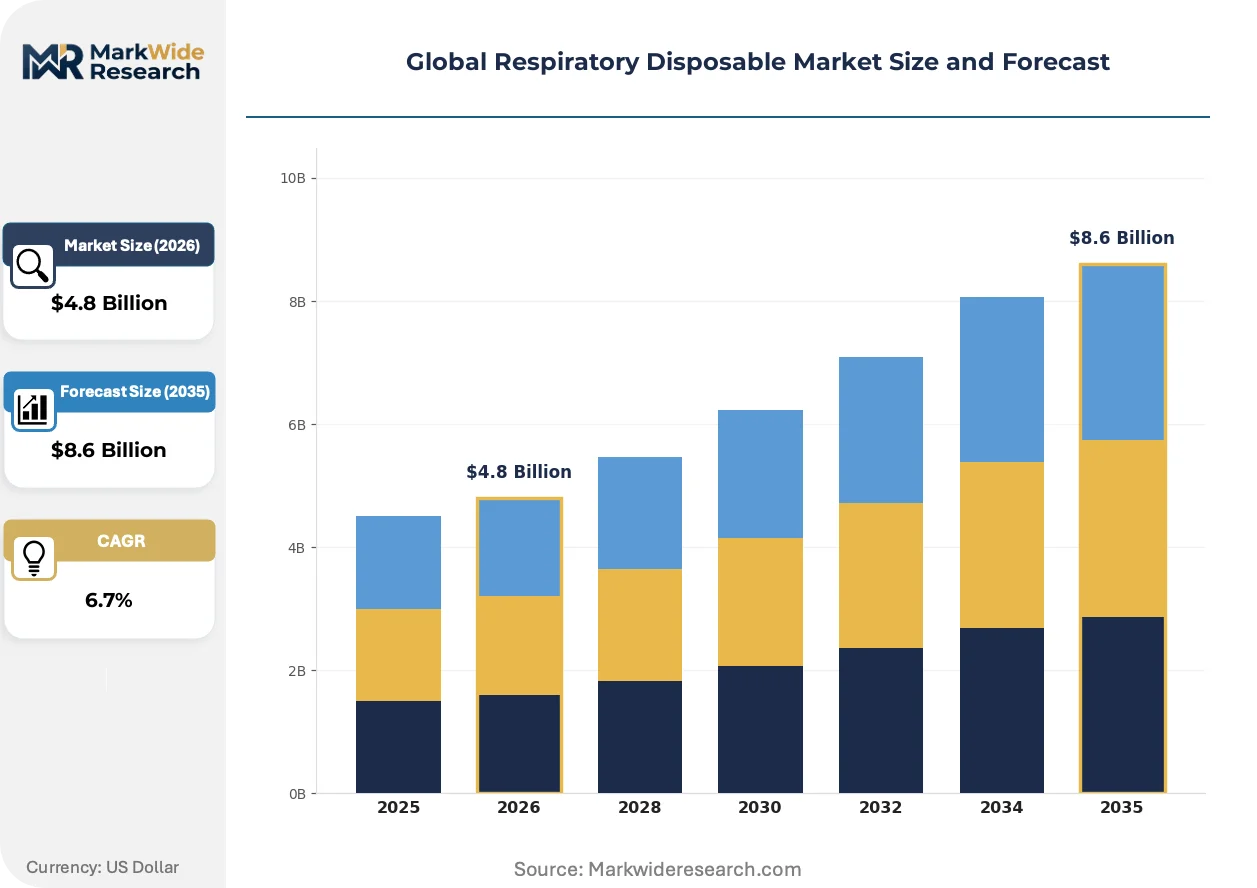
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Masks, N95 Respirators, Face Shields, Antiviral Masks, Dust Masks Application: Hospital Settings, Home Care, Industrial Safety, Public Spaces, Emergency Response End User: Medical Facilities, Emergency Medical Services, Manufacturing Units, Commercial Offices, Educational Institutions Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Fisher & Paykel Healthcare, Medtronic, Teleflex, Philips Respironics, Drägerwerk AG & Co. KGaA, Smiths Medical, Hamilton Medical, Getinge, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory Disposable Market Shifts & Advancements
Material science advances and regulatory recalibration are simultaneously elevating performance floors and fragmenting product tiers, creating parallel demand tracks for premium clinical-grade devices and cost-optimized alternatives serving price-sensitive channels.
Electrospun nanofiber filtration media is bifurcating the respiratory protection landscape. Hospital networks in the United States and Germany are adopting these ultra-fine fiber matrices for extended-wear surgical N95s that maintain breathability across twelve-hour shifts. The technology is bifurcating procurement patterns as premium clinical facilities separate from industrial and general healthcare buyers who retain conventional meltblown alternatives.
REACH chemical disclosure expansions are forcing material transparency across European supply chains. Manufacturers must now document full substance compositions down to 0.1% weight thresholds for respiratory devices contacting skin or mucosa. Disposable mask producers serving France and the Netherlands are reformulating colorants and plasticizers ahead of 2026 enforcement windows, compressing margins on legacy product lines.
Home care providers are consolidating purchasing through group purchasing organizations that unbundle device selection from clinical service contracts. Sleep therapy and oxygen concentrator suppliers in the United States are ceding equipment specification authority to regional buying coalitions that standardize on lowest-total-cost disposable circuits. This consolidation is most visible in Florida and Texas, where large home health networks have displaced independent respiratory equipment dealers.
Global Respiratory Disposable Market Segmentation
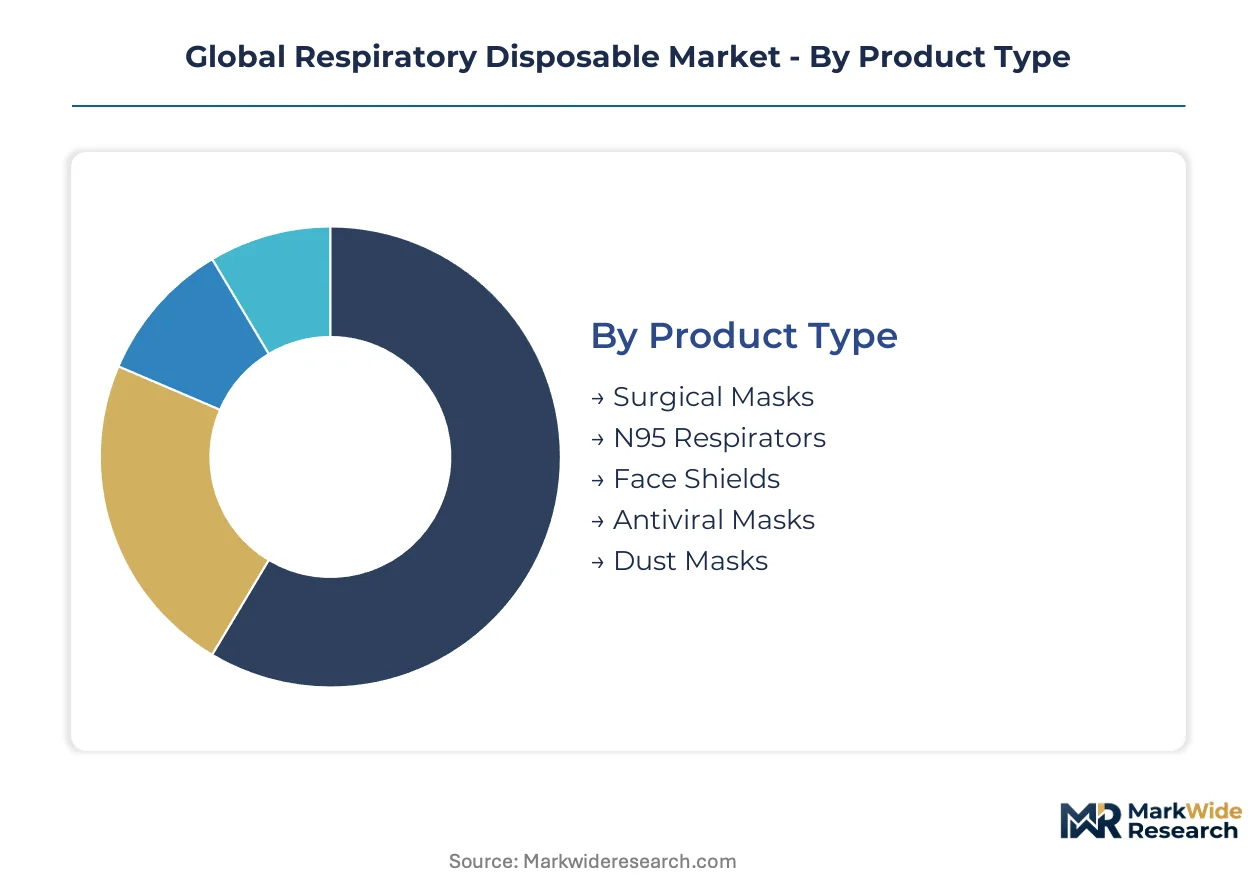
Respiratory disposables fragment across four intersecting dimensions that determine pricing power, regulatory burden, and channel economics. Product specifications diverge sharply between clinical-grade and industrial variants, while end-user procurement authority increasingly consolidates through specialized distributors rather than open markets.
Product Type:
Domestic production clusters in Germany, the United States, and Japan supply premium clinical segments, while export-led manufacturing in Southeast Asia feeds cost-optimized industrial and consumer channels.
- N95 Respirators:These tight-fitting filtration devices incorporate electrostatically charged meltblown polypropylene layers meeting OSHA 42 CFR 84 standards. Hospital networks in the United States sustain volume commitments through fit-testing mandates and pandemic stockpiling programs, though industrial substitution toward elastomeric alternatives constrains pricing flexibility.
- Surgical Masks:Loose-fitting barriers of three-ply non-woven construction provide droplet protection in procedural settings. German hospital procurement coalitions drive specification standardization toward Type IIR EN 14683 certification, compressing margin pools for uncertified imports.
- Face Shields:Clear polyethylene terephthalate visors with foam forehead bands extend protection against splash exposure.
- Antiviral Masks:Surface-treated variants integrate copper-ion or quaternary ammonium compounds for enhanced pathogen inactivation.
- Dust Masks:Unvalved filtering facepieces serve construction and mining sectors under simplified regulatory pathways.
N95 Respirators command the established base. The steepest expansion runs through Antiviral Masks.
Application:
Cost stratification separates acute-care premium tiers from price-sensitive occupational and consumer segments, with reimbursement availability determining effective demand elasticity.
- Hospital Settings:Inpatient mechanical ventilation and surgical suites require sterile single-use circuits, masks, and filters meeting ISO 18562 biocompatibility standards. United States health systems absorb elevated per-unit costs through diagnosis-related group reimbursement, while European facilities face tighter procurement caps under national health service frameworks.
- Home Care:Post-acute oxygen therapy and sleep apnea management shift volume toward humidification interfaces and nasal cannulas designed for patient self-administration. Medicare competitive bidding in Florida and Texas has compressed margins through standardized single-source contracts.
- Industrial Safety:OSHA-mandated respiratory protection programs sustain N95 deployment across manufacturing and energy sectors.
- Public Spaces:Voluntary masking in transit and retail environments exhibits demand volatility tied to infection surveillance thresholds.
- Emergency Response:Strategic national stockpiles and disaster preparedness frameworks generate lumpy tender volumes with extended fulfillment timelines.
Hospital Settings absorb the majority of current volume. Home Care is climbing the fastest as payors enforce shorter inpatient stays.
End User:
Customer scale concentrates purchasing leverage, with large integrated networks extracting tiered pricing unavailable to fragmented independent operators.
- Medical Facilities:Hospital systems and outpatient clinics command volume discounts through multi-year supply agreements. Kaiser Permanente and Mayo Clinic networks in the United States negotiate direct manufacturer relationships that bypass distributor markups.
- Emergency Medical Services:Municipal and private ambulance operators prioritize ruggedized packaging and rapid-deployment configurations for field use.
- Manufacturing Units:Automotive and chemical plants deploy fit-tested respirator programs under OSHA compliance documentation requirements.
- Commercial Offices:Corporate wellness initiatives drive sporadic bulk purchases with limited recurrence predictability.
- Educational Institutions:K-12 districts and university systems exhibit procurement fragmentation across decentralized purchasing authorities.
Medical Facilities anchor current revenue concentration. Emergency Medical Services is gaining share fastest through municipal fleet standardization.
Distribution Channel:
Channel selection determines margin capture, with direct and wholesale pathways preserving manufacturer pricing power against price-transparent retail alternatives.
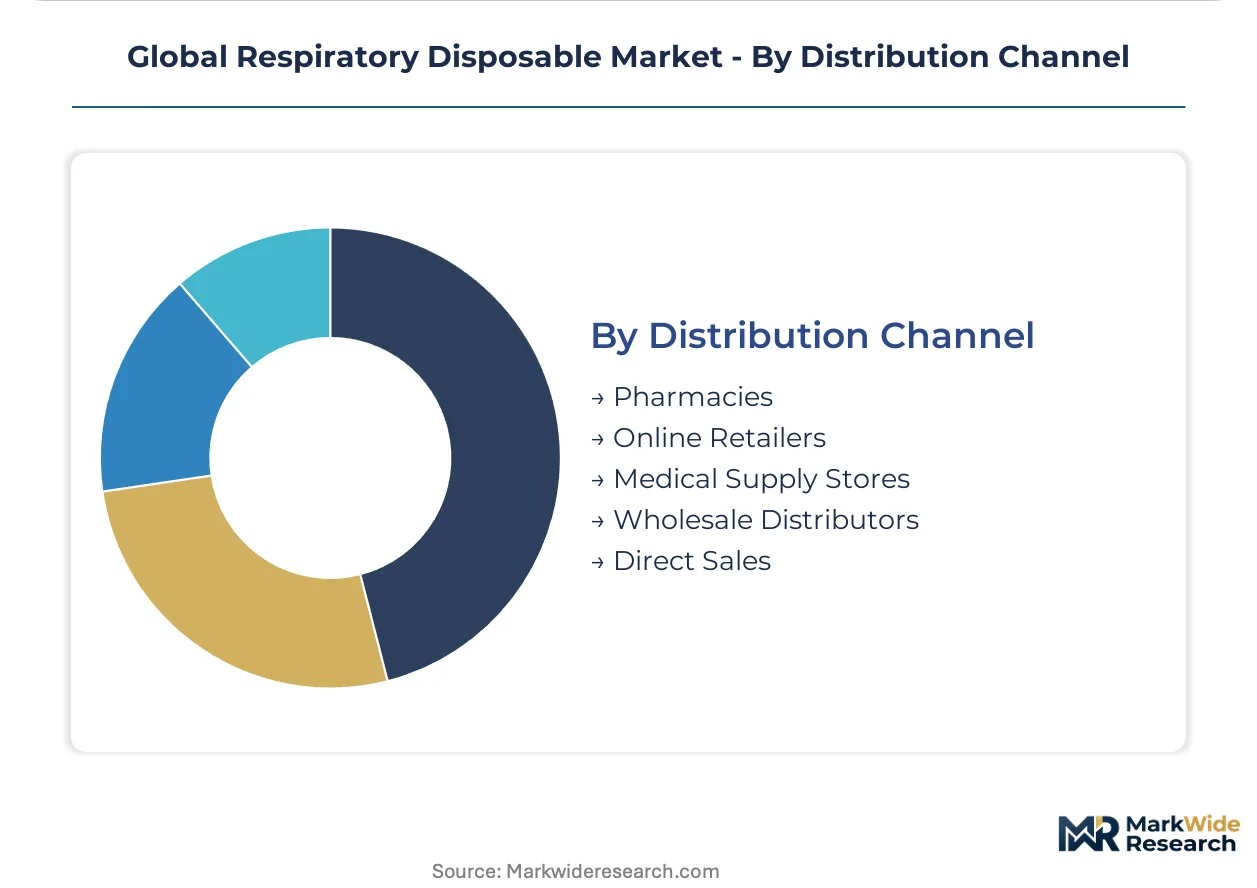
- Wholesale Distributors:Medline and Cardinal Health in the United States consolidate hospital procurement through integrated logistics platforms offering inventory management and consignment arrangements. These intermediaries extract 15-25% margins while providing compliance documentation and recall management services.
- Direct Sales:Manufacturers including Medtronic and Fisher & Paykel Healthcare maintain dedicated field forces for high-volume accounts requiring clinical training and technical support. This channel preserves pricing integrity but carries elevated customer acquisition costs.
- Medical Supply Stores:Independent dealers serve smaller clinics and home care patients with immediate availability.
- Pharmacies:Retail chains stock consumer-grade masks with limited clinical differentiation.
- Online Retailers:Amazon and specialized medical marketplaces expose price-sensitive buyers to commodity import competition.
Wholesale Distributors control the established volume base. Direct Sales is expanding most quickly as manufacturers seek margin recovery from distributor compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export meltblown polypropylene filtration media to United States hospital networks, establishing the primary trade-flow corridor in respiratory disposables.
United States
Hospital networks in Texas and Florida sustain bulk procurement through Medicare competitive bidding programs. OSHA's respiratory protection standards mandate fit-testing documentation for workplace N95 deployment. The Minneapolis-St. Paul corridor concentrates distributor logistics for Midwest health systems.
Germany
Industrial safety mandates in automotive and chemical plants sustain elastomeric respirator demand alongside disposable alternatives. REACH chemical disclosure requirements force material transparency down to 0.1% weight thresholds. The Rhine-Ruhr manufacturing belt hosts specialty thermoplastic elastomer compounders serving mask seal producers.
China
Domestic hospital procurement is expanding under national health infrastructure programs in second-tier cities. NMPA governs 510(k)-equivalent clearance pathways for novel mask designs. The Yangtze River Delta cluster exports cost-optimized non-woven polypropylene to Southeast Asian distributors.
India
Government diagnostic center proliferation under national health mission programs is creating first-time institutional demand for humidification circuits. CDSCO regulates medical device imports and domestic manufacturing licensure. The Mumbai-Pune corridor concentrates contract manufacturing for export-oriented mask producers.
Japan
Aging demographics are expanding home oxygen therapy and sleep apnea management volumes. PMDA maintains stringent biocompatibility evaluation timelines for respiratory gas pathway devices. The Osaka-Kobe industrial zone specializes in medical-grade silicone compounding for high-performance mask skirts.
Global Respiratory Disposable Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities, creating a tiered structure where scale-driven conglomerates and focused mid-caps coexist. The vendor base fragments across three strategic archetypes: integrated critical care conglomerates, specialized humidification interface developers, and industrial safety certification holders. Consolidation pressure operates through M&A activity targeting regional distribution networks and portfolio diversification into adjacent airway management categories.
Among integrated critical care conglomerates, Medtronic and Fisher & Paykel Healthcare exemplify archetype differentiation through direct channel relationships with outpatient respiratory clinics. Drägerwerk AG & Co. KGaA occupies a distinct position bridging clinical and industrial safety segments through specialized certification portfolios.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| Medtronic |
| Teleflex |
| Philips Respironics |
| Drägerwerk AG & Co. KGaA |
| Smiths Medical |
| Hamilton Medical |
| Getinge |
| Becton Dickinson |
| Others |
Supply & Pricing Matrix
Capacity utilization at German meltblown polypropylene facilities anchors cost floors for clinical-grade filtration media, concentrating supply-side pricing power among legacy European compounders while Asian export-oriented producers compete on volume-scale economies for industrial and consumer tiers.
Pricing Analysis
Electrospun nanofiber respiratory protection commands substantial premiums over conventional meltblown alternatives, while legacy three-ply surgical masks face commodity compression. Pricing stratifies across premium clinical-grade, standard institutional, and economy industrial tiers, with ISO 18562 biocompatibility certification and OSHA fit-testing documentation driving price differentiation. Cost compression in standard surgical mask tiers is intensifying because REACH chemical disclosure compliance forces reformulation expenses onto legacy product lines. Industrial safety buyers exhibit highest price sensitivity, while United States hospital networks absorbing diagnosis-related group reimbursement show lowest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for Southeast Asian non-woven polypropylene exporters serving European distributors. Supply concentrates in Germany, the United States, and China for meltblown filtration media, with medical-grade silicone compounding anchored in Japan and Germany for high-performance mask seals. Raw material dependencies draw from petroleum-derived polypropylene, thermoplastic elastomers, and copper-ion additives for antiviral surface treatments. Single-source vulnerability clusters around specialty elastomer production in the Rhine-Ruhr and Osaka-Kobe industrial zones. Distribution runs through wholesale distributor consignment arrangements for hospital networks and direct-to-patient subscription platforms for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-acute care decentralization fragments procurement authority across distributed home care networks, creating structural white-space for specialized entrants targeting humidification interfaces and oxygen delivery accessories outside hospital supply chain consolidation.
For Market Incumbents: Consolidate distribution control through exclusive consignment arrangements with United States group purchasing organizations, offsetting margin compression from Medicare competitive bidding in Florida and Texas. Deepen backward integration into medical-grade silicone compounding to reduce exposure to Japanese and German supply concentration. Prioritize ISO 18562 certification investment to defend premium positioning against electrospun nanofiber substitutes. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for novel mask designs offer regulatory arbitrage against entrenched European competitors facing extended EU MDR biocompatibility timelines. Target India outpatient respiratory clinic expansion under national health mission programs, where first-time institutional demand for humidification circuits lacks established supplier relationships. Deploy direct-to-patient subscription channels bypassing durable medical equipment intermediaries in United States sleep apnea and COPD home therapy segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among home care providers with automated resupply platforms, offering superior cash-flow predictability against transactional hospital procurement. Long-term viability over the next decade hinges on antiviral coating convergence with nanofiber substrates serving immunocompromised patient settings. Acquisition target archetype: specialized humidification interface developers with established outpatient respiratory clinic relationships. The signal to watch is CDSCO domestic manufacturing licensure acceleration in India as import substitution policy tightens.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | REACH chemical disclosure compliance accelerates product differentiation for European hospital procurement coalitions. |
| Hospital System Partnership | Direct channel relationships with Kaiser Permanente and Mayo Clinic networks bypass distributor margin extraction. |
| Backward Integration into Meltblown Media | In-house polypropylene filtration production reduces exposure to German export pricing volatility. |
| Software Companion Development | Automated resupply platforms for sleep apnea therapy consolidate patient adherence data for payor contracting leverage. |
| Reimbursement Strategy | Medicare competitive bidding alignment in Texas and Florida secures standardized contract access for home care volume. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, GPO contracts managers, biomedical engineers, and outpatient respiratory clinic administrators and secondary validation against FDA 510(k) filings, CMS Medicare competitive bidding data, hospital procurement databases, and EU MDR notified body disclosure records anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the respiratory disposable value chain.
Sensitivity analysis around OSHA mandate enforcement intensity and REACH chemical disclosure timeline assumptions tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, application setting, end-user scale, and distribution channel, with regional regulatory cluster differentiation for United States, European, and Asia-Pacific markets. CAGRs derive from volume-weighted average growth trajectories calibrated to inpatient stay duration trends and home care reimbursement policy shifts.
Decision-makers should treat outputs as directional under base assumptions of sustained Medicare competitive bidding expansion and stable OSHA respiratory protection mandate enforcement; material deviation in either policy lever would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Emphysema Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Lung Injury Market