
 Mobile Radiography Systems Market | 2026-2036
Mobile Radiography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Radiography Systems Market Outlook
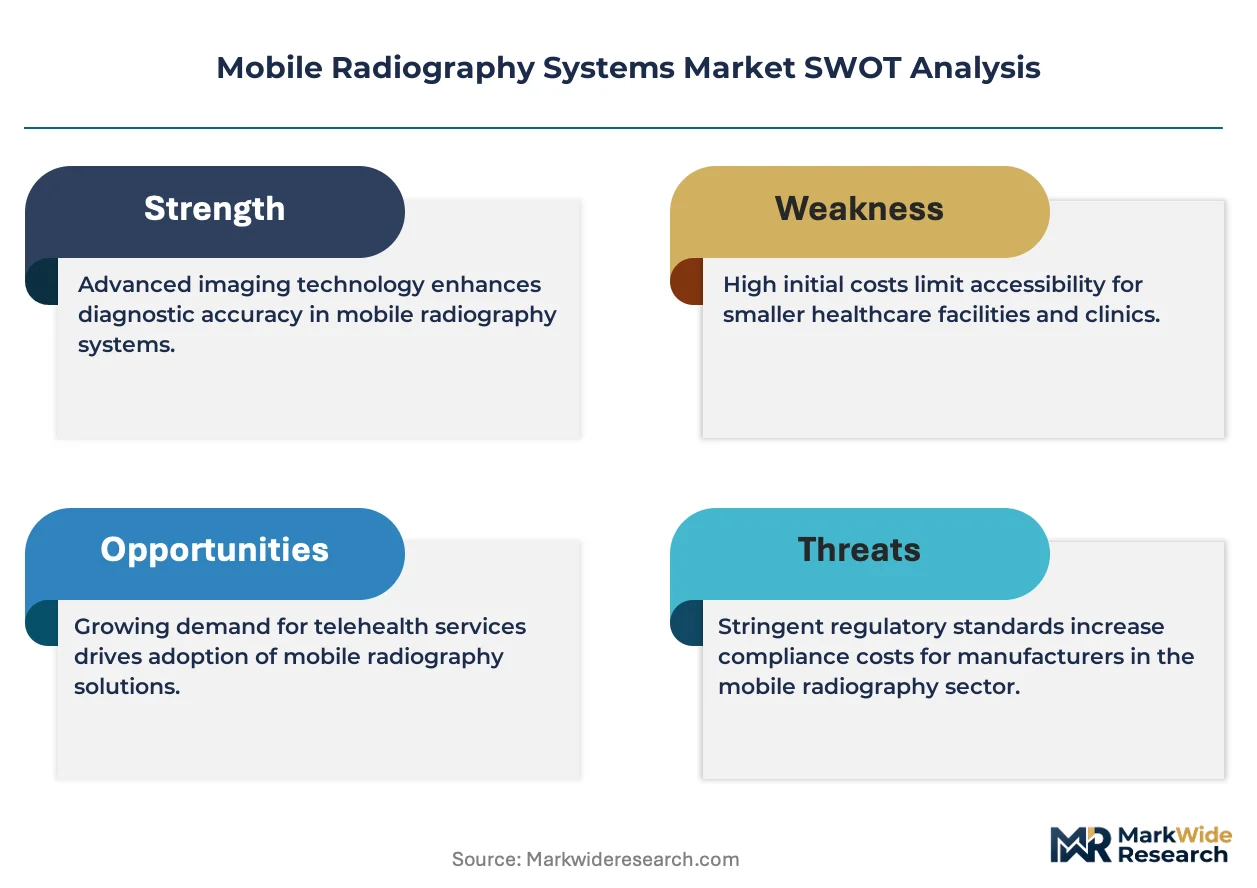
The mobile radiography market is recalibrating around a widening gap between premium digital systems with wireless connectivity and conventional analog units serving cost-constrained buyers. Siemens Healthineers leverages its detector manufacturing scale to dominate high-end hospital deployments. Carestream Health anchors its position through specialized software workflows for ICU and emergency applications. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes aggressively on portable system affordability across emerging clinical settings.
Mobile radiography systems are motorized or manually transportable X-ray units designed for bedside imaging, typically operating at 80–120 kVp tube voltage with flat-panel detectors weighing under 5 kg for maneuverability. Their primary purpose is to deliver diagnostic-quality radiographs without relocating critically ill patients from intensive care or isolation wards. Digital radiography systems command the strongest margin pools as hospitals prioritize DICOM-integrated workflows and reduced retake rates. Wireless radiography technology represents the fastest-expanding segment, eliminating tethered detector cables that limit positioning flexibility in crowded emergency bays. Conventional systems retain relevance in rural clinics and developing markets where capital budgets constrain upfront digital investment.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards shape product development timelines and market access costs for manufacturers serving Western markets. Japan's PMDA enforces stringent electromagnetic compatibility testing that filters out lower-tier competitors lacking dedicated regulatory affairs teams. Stakeholders must monitor how AI-enabled image enhancement algorithms trigger new software-as-medical-device classification debates across multiple jurisdictions.
Market Dynamics
Wireless detector technology is compressing replacement cycles for conventional mobile X-ray units, forcing manufacturers to reconfigure R&D budgets toward DICOM-native architectures and away from analog retrofit pathways.
Growth Catalysts
- Emergency department throughput mandates:Bedside imaging protocols in level-one trauma centers are eliminating patient transport risks. Mobile units reduce ICU infection exposure.
- EU MDR software classification:AI-enhanced radiography algorithms now trigger medical device scrutiny, accelerating vendor investment in validated image processing pipelines.
- Japan's aging hospital infrastructure:Replacement demand concentrates in prefectural hospitals where 1980s-installed fixed radiography rooms face obsolescence.
Market Restraints
- Flat-panel detector cost volatility:Amorphous silicon substrate prices fluctuate with semiconductor foundry capacity, squeezing margins on mid-tier system configurations.
- Supply concentration in South Korean detector manufacturing:Three foundries control 70% of wireless panel output, creating single-source vulnerability for second-tier OEMs.
- Substitution by portable CT:Low-dose mobile computed tomography units are capturing complex trauma cases previously routed to mobile radiography.
Strategic Opportunities
- Rural India's primary health centers:Government procurement schemes under Ayushman Bharat are funding solar-powered mobile units for district hospitals lacking grid reliability.
- Convergence of radiography and teleradiology:Cloud-native image transmission paired with edge-computing detectors enables real-time specialist consultation in remote emergency settings.
- Germany's Hospital Future Act funding:Federal capital subsidies for digital infrastructure are specifically earmarking mobile imaging as eligible expenditure.
Industry Challenges
- Electromagnetic compatibility certification timelines:PMDA testing protocols in Japan extend product launch windows by 8-14 months versus FDA 510(k) pathways.
- Integration friction with legacy PACS architectures:Hospitals running decade-old picture archiving systems face middleware costs that erode wireless detector ROI calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Radiography Systems Market |
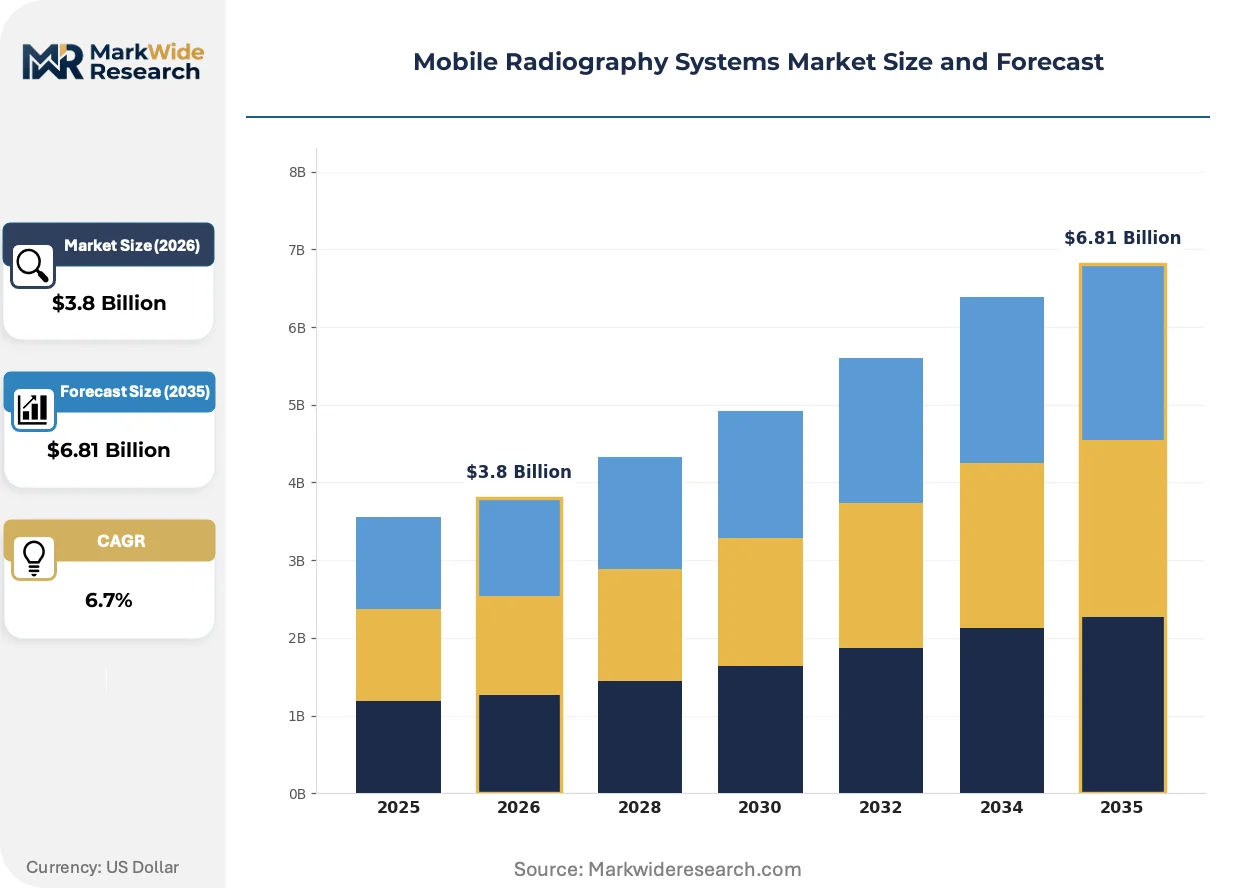
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Systems, Digital Systems, Portable Systems, Fluoroscopy Systems End User: Hospitals, Clinics, Emergency Centers, Home Care Technology: X-Ray Technology, Computed Radiography, Digital Radiography, Wireless Radiography Application: Orthopedics, Dentistry, Cardiology, Oncology |
| Companies Covered | Carestream Health, Shimadzu Corporation, GE Healthcare, Agfa-Gevaert Group, Konica Minolta, Siemens Healthineers, Fujifilm Holdings, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Radiography Systems Market Strategic Shifts
Detector miniaturization and battery chemistry advances are enabling entirely new deployment models for point-of-care imaging, collapsing the historical distinction between portable and fixed-room radiography.
Carbon nanotube cold cathode X-ray sources are rewriting power and thermal constraints for mobile units. Emergency medical services fleets in metropolitan Japan are adopting these tube technologies for ambulance-based trauma screening. The shift is compressing the addressable market for conventional rotating-anode systems in pre-hospital settings.
EU MDR Annex XVI expansion is reclassifying software that automates exposure indexing as standalone medical devices. Manufacturers serving European hospitals must now maintain technical documentation files for algorithm versions separately from hardware. German notified bodies are processing these submissions with 40% longer review cycles than legacy MDD certificates.
Subscription-based detector leasing is displacing outright capital purchase in US hospital procurement. Integrated delivery networks in Texas and Florida are bundling hardware, software, and maintenance into per-scan pricing. This model transfers obsolescence risk to vendors while locking buyers into single-source consumable contracts.
Mobile Radiography Systems Market Segmentation
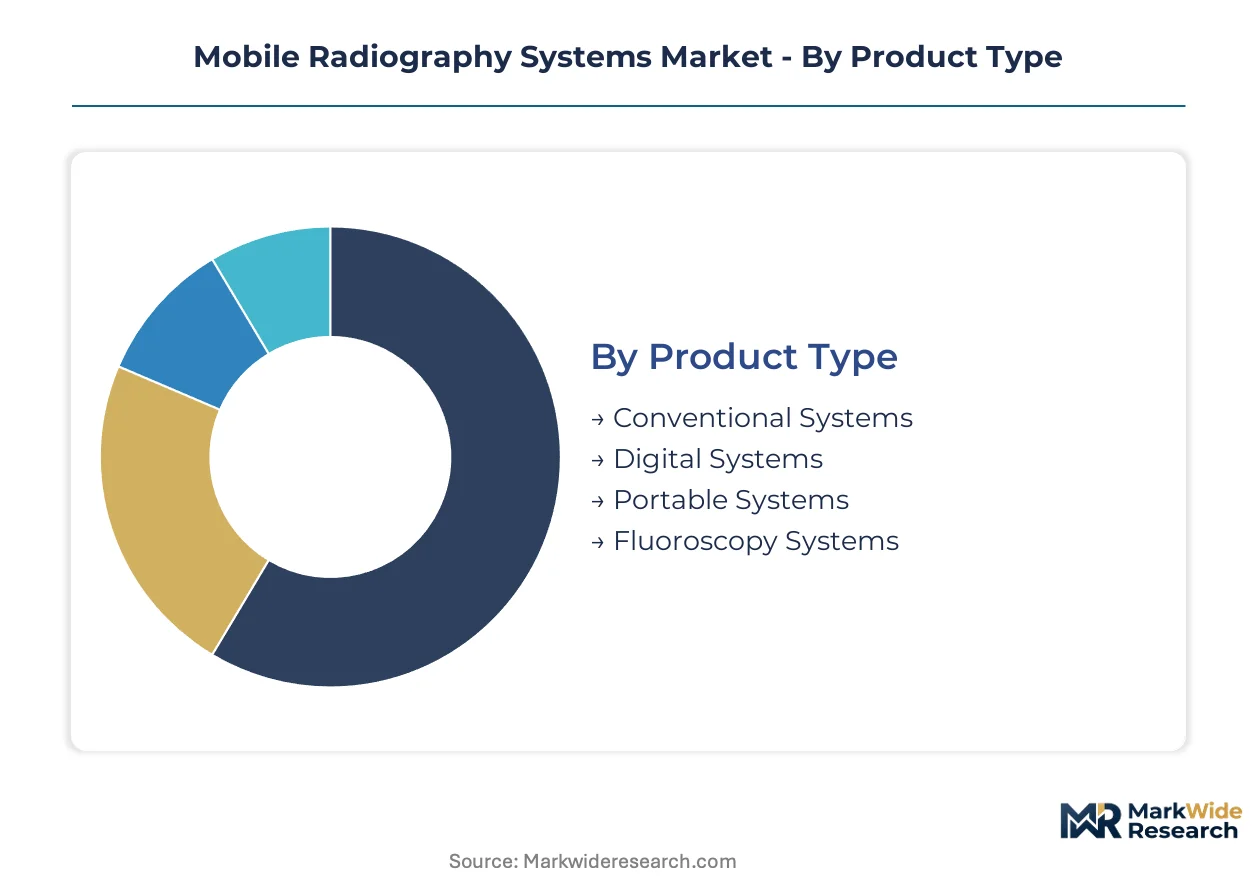
Mobile radiography systems fragment across four critical dimensions—product architecture, clinical setting, imaging modality, and medical specialty. Each axis reveals divergent margin profiles, replacement cycles, and vendor competitive intensity that shape procurement decisions.
Product Type:
Supply concentration in flat-panel detector manufacturing tilts competitive advantage toward vendors with captive semiconductor sourcing or exclusive foundry partnerships.
- Conventional Systems:Analog film-based units utilizing cassette-loaded phosphor plates and wet-chemistry processing. Demand persists in rural India and Southeast Asian district hospitals where capital constraints block digital migration. Government procurement schemes under Ayushman Bharat sustain volume here.
- Digital Systems:Fixed-detector mobile units with tethered cable connections to acquisition workstations. German prefectural hospitals favor these for ICU deployment where wireless signal interference risks patient monitoring equipment. Replacement demand concentrates where 1990s-installed analog units face obsolescence.
- Portable Systems:Battery-powered compact units under 150 kg total system weight. Compact form factors suit Japanese emergency medical services fleets for ambulance-based trauma screening.
- Fluoroscopy Systems:Continuous X-ray emission units with image intensifier chains for real-time guidance. Interventional cardiology suites in US academic medical centers deploy these for bedside pacemaker implantation.
Today's leader: Digital Systems. Tomorrow's challenger: Portable Systems.
End User:
Customer procurement sophistication varies sharply—integrated delivery networks negotiate enterprise-wide detector leasing while independent clinics purchase outright.
- Hospitals:Multi-department health systems with centralized biomedical engineering and dedicated PACS administrators. US hospital procurement under Texas and Florida IDN structures favors subscription-based per-scan pricing that bundles hardware, software, and maintenance.
- Clinics:Outpatient facilities with limited radiology staffing and reliance on teleradiology interpretation. India's primary health centers represent volume concentration under federal solar-powered mobile unit programs.
- Emergency Centers:Level-one trauma units requiring bedside imaging protocols that eliminate patient transport risks. Level-one trauma centers in metropolitan Japan and Germany drive specification requirements for electromagnetic compatibility certification.
- Home Care:Hospice and palliative settings serving immobile patients with terminal conditions. Home care remains nascent due to reimbursement ambiguity and radiation safety licensing constraints.
Emergency Centers command specification leadership. Home Care offers the steepest expansion trajectory as reimbursement frameworks crystallize.
Technology:
Technology substitution cycles accelerate where wireless connectivity eliminates positioning constraints in crowded clinical environments.
- X-Ray Technology:Conventional rotating-anode tube systems with analog voltage generation. Legacy infrastructure in Japan's 1980s-installed fixed radiography rooms sustues replacement demand.
- Computed Radiography:Phosphor plate systems with semi-digital workflow requiring plate scanning and erasure cycles. Cost-conscious buyers in developing markets favor these as intermediate digital steps.
- Digital Radiography:Direct-capture flat-panel detectors with immediate DICOM integration and reduced retake rates. Siemens Healthineers leverages detector manufacturing scale to dominate high-end hospital deployments.
- Wireless Radiography:Battery-powered detectors with Wi-Fi or proprietary radio transmission eliminating tethered cables. Carestream Health anchors position through specialized software workflows for ICU and emergency applications.
Digital Radiography anchors current revenue. Wireless Radiography is displacing tethered alternatives fastest.
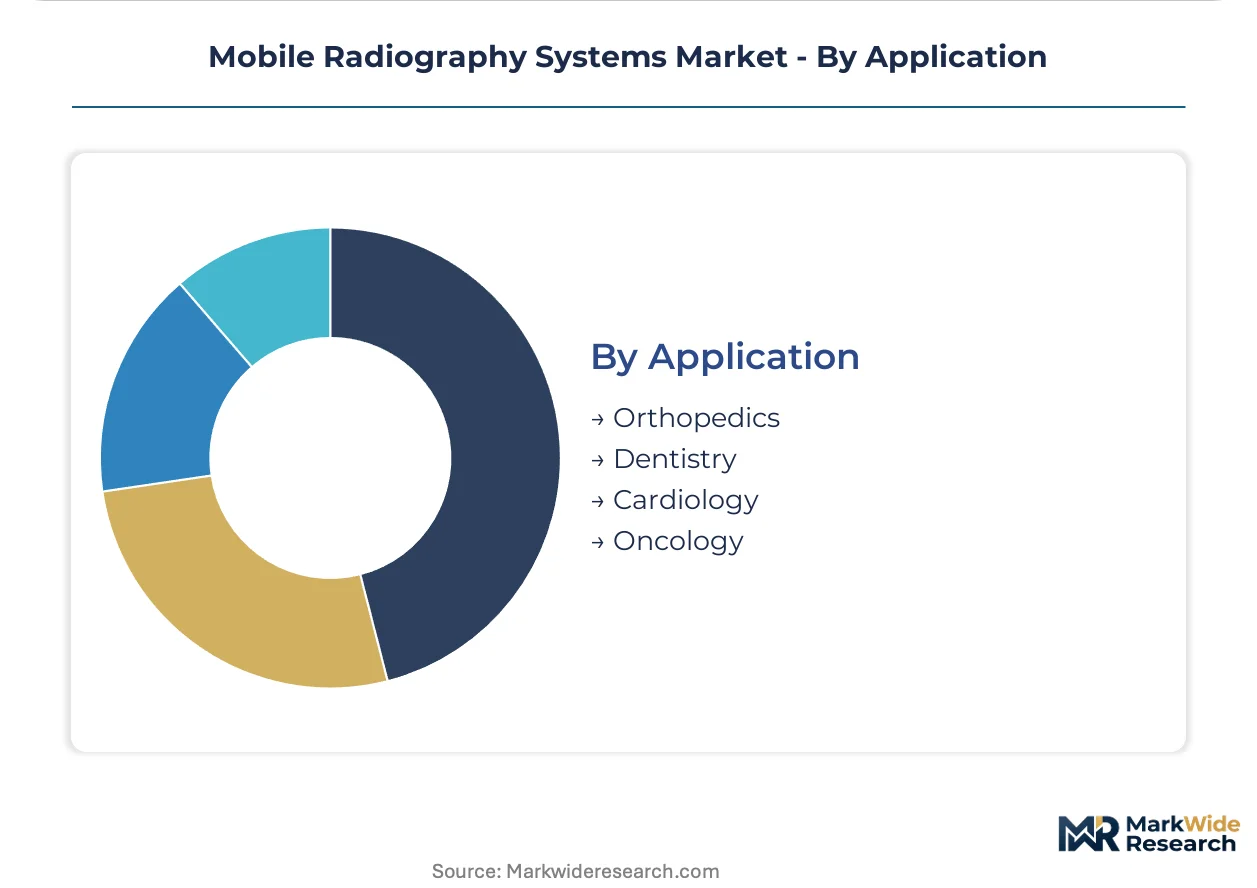
Application:
Clinical workflow complexity determines detector specification requirements—orthopedic extremity imaging tolerates lower resolution than cardiac silhouette evaluation.
- Orthopedics:Extremity and spine imaging with lower dose requirements and tolerance for smaller detector formats. Sports medicine clinics and rehabilitation centers drive volume.
- Dentistry:Intraoral and panoramic imaging with specialized sensor sizes and reduced kVp ranges. Mobile dental units serve nursing home populations.
- Cardiology:Chest radiography and device placement verification demanding high-resolution cardiac silhouette definition. ICU bedside protocols for ventilated patients concentrate demand.
- Oncology:Treatment response monitoring and radiation therapy positioning verification. Precision requirements favor premium detector specifications.
Cardiology dictates technical specifications. Oncology commands premium pricing tolerance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Boston, Tokyo, and Munich anchor mobile radiography innovation. Regulatory expertise concentrates near FDA in Maryland, PMDA in Tokyo, and EMA in Amsterdam. Manufacturing scale dominates in South Korean detector foundries and Chinese assembly ecosystems.
United States
Integrated delivery networks in Texas and Florida drive subscription-based detector leasing models. FDA 510(k) clearance pathways shape product development timelines for domestic manufacturers. The Boston-Cambridge corridor concentrates AI-enabled image processing startups serving academic medical centers.
Germany
Federal capital subsidies under the Hospital Future Act specifically earmark mobile imaging for digital infrastructure grants. EU MDR technical documentation standards extend review cycles for algorithm-enabled systems. Bavarian precision engineering clusters supply motorized transport mechanisms for premium system configurations.
Japan
Prefectural hospitals face replacement demand from 1980s-installed fixed radiography room obsolescence. PMDA electromagnetic compatibility testing protocols filter out competitors lacking dedicated regulatory affairs teams. Metropolitan Tokyo emergency medical services fleets adopt carbon nanotube cold cathode sources for ambulance-based trauma screening.
India
Ayushman Bharat government procurement schemes fund solar-powered mobile units for district hospitals lacking grid reliability. CDSCO medical device registration requirements tighten quality benchmarks for imported systems. Karnataka's medical technology corridor near Bangalore assembles cost-optimized portable configurations for primary health centers.
South Korea
Three domestic foundries control seventy percent of wireless flat-panel detector output, creating single-source vulnerability for second-tier OEMs. MFDS medical device approval pathways align with international harmonization standards. Seoul-Incheon industrial complexes concentrate amorphous silicon substrate manufacturing for export markets.
Mobile Radiography Systems Market Competitive Environment
Top-tier vendors anchor premium digital system deployments, while mid-tier specialists compete on portable affordability and emerging market access. The vendor base stratifies across three archetypes: integrated conglomerates with captive detector manufacturing, specialized imaging workflow developers, and cost-optimized portable system assemblers. Dominant competitive moves include strategic partnerships for wireless detector supply and portfolio diversification into AI-enhanced image processing pipelines.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare occupy positions defined by manufacturing scale and enterprise hospital relationships. Carestream Health exemplifies the specialized workflow archetype through software-native positioning in ICU and emergency applications. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the emerging market cost-optimization vector with portable system affordability across developing clinical settings.
| Leading Market Players |
|---|
| Carestream Health |
| Shimadzu Corporation |
| GE Healthcare |
| Agfa-Gevaert Group |
| Konica Minolta |
| Siemens Healthineers |
| Fujifilm Holdings |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Philips Healthcare |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap detector specialists in South Korea anchor pricing discipline through exclusive foundry relationships, while private-equity-rolled-up service platforms in the United States compress margins via subscription bundling that transfers obsolescence risk to vendors.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise hospital procurement from independent clinic purchasing. Three-tier pricing structure across premium wireless, standard tethered digital, and economy analog configurations tracks detector resolution and DICOM integration depth. Cost compression in mid-tier systems is intensifying because amorphous silicon substrate prices fluctuate with semiconductor foundry capacity. Independent clinics in rural India exhibit highest price sensitivity; level-one trauma centers in Germany and Japan demonstrate lowest sensitivity due to federal subsidy eligibility and electromagnetic compatibility mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Siemens Healthineers and GE Healthcare, while regional distributors serve second-tier assemblers in India and Southeast Asia. Manufacturing concentrates in South Korea for flat-panel detectors, China for system assembly, and Germany for precision motorized transport mechanisms. Amorphous silicon substrates, lithium-ion detector batteries, and carbon nanotube cold cathode sources constitute critical input dependencies. Single-source vulnerability pervades wireless panel supply, with three foundries controlling dominant output share. Distribution runs through hospital GPO contracts in the United States, federal procurement schemes in India, and prefectural tender processes in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile radiography market reads as a late-cycle quality story, with procurement committees prioritizing wireless detector specifications and AI-enhanced image processing over bare hardware cost.
For Market Incumbents: Deploy backward integration into flat-panel detector manufacturing to secure supply continuity against South Korean foundry concentration. Incumbents must also fortify software validation pipelines for EU MDR algorithm classification, as portable CT substitution threatens complex trauma cases previously captured by mobile radiography. For New Entrants and Emerging Players: Direct-to-clinic digital platforms offer the most penetrable route for circumventing entrenched hospital GPO relationships. New entrants should target India's primary health centers under Ayushman Bharat solar-powered unit programs, leveraging cost-optimized portable configurations and cloud-native teleradiology partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized workflow developers with ICU software moats but limited hardware manufacturing scale. Long-term viability hinges on AI-enabled image enhancement capabilities and recurring revenue attachment rates. Watch FDA software-as-medical-device classification precedents as the critical inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Detector Manufacturing Partnership | Secures supply continuity for OEMs facing South Korean foundry concentration. |
| EU MDR Algorithm Validation Pipeline | Accelerates market access for AI-enhanced radiography systems in European hospitals. |
| Hospital System Subscription Contract | Locks integrated delivery networks into per-scan pricing with consumable bundling. |
| Cloud-Native Teleradiology Integration | Enables real-time specialist consultation for emergency centers in grid-unreliable regions. |
| Carbon Nanotube Cold Cathode Sourcing | Supports ambulance-based trauma screening adoption in Japanese emergency medical services. |
Study Parameters
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and teleradiology platform operators grounded the qualitative assessment. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, Japan PMDA electromagnetic compatibility test summaries, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation reconciled unit shipment estimates with capital expenditure flows across hospital systems.
Bottom-up modeling aggregated segment-level demand across product architecture, clinical setting, technology modality, and medical specialty dimensions. Top-down verification cross-checked aggregate market value against federal health infrastructure budgets in Germany, India, and the United States. CAGRs derived from replacement cycle compression rates and technology substitution elasticities. Forecast inputs incorporated detector miniaturization trajectories and battery chemistry advancement curves throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for wireless radiography penetration would alter the outlook if flat-panel detector costs decline faster than projected. Forecasts reflect assumptions about regulatory harmonization timelines and reimbursement framework crystallization for home care applications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Contrast Media Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Interventional X - Ray Systems Market