
 Fluorescein Angiography Market | 2026-2036
Fluorescein Angiography Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescein Angiography Market Intelligence
Japanese optical equipment producers is rebalancing supply chains toward in-house production of high-resolution fundus camera components. Carl Zeiss Meditec AG leverages its surgical-ophthalmology ecosystem to cross-sell angiography systems into integrated practice workflows. Heidelberg Engineering GmbH anchors its position through proprietary SPECTRALIS platform technology that combines angiography with OCT. NIDEK CO., Ltd. competes aggressively on cost-optimized digital imaging configurations for mid-tier clinics.
Fluorescein angiography is a diagnostic imaging technique that uses intravenous fluorescein sodium dye to visualize retinal and choroidal vasculature through sequential fundus photography, typically capturing images at 10-30 second intervals over 5-10 minutes to assess blood flow dynamics and vascular leakage. The procedure requires excitation at 465-490 nm and emission detection at 520-530 nm, serving primarily to detect macular edema, neovascularization, and vascular occlusion in ophthalmic practice. Optical Coherence Tomography Angiography is displacing conventional dye-based methods in premium-tier settings by eliminating injection risks while delivering depth-resolved vascular maps. Retinal Disease Diagnosis occupies the largest application share as age-related macular degeneration and diabetic retinopathy screening protocols expand, while Diabetic Retinopathy Monitoring represents the fastest-growing segment due to rising diabetes prevalence and value-based care incentives for early detection.
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) impose clinical validation and post-market surveillance burdens that favor established manufacturers with regulatory infrastructure. The EPA and national health agencies in Germany and Japan additionally govern dye disposal protocols and contrast agent environmental handling standards. Stakeholders must monitor whether non-invasive OCT angiography advances trigger reimbursement code revisions that could accelerate technology substitution decisions across ophthalmology service lines.
Market Dynamics
Optical Coherence Tomography Angiography is compressing demand for dye-based diagnostics by eliminating injection protocols while delivering comparable vascular imaging, forcing incumbent equipment manufacturers to defend installed base positions through software upgrades and hybrid platform bundling.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:Streamlined CE marking pathways for ophthalmic diagnostics accelerate product introductions across German, French, and Italian hospital procurement frameworks.
- Diabetic retinopathy screening protocols:Value-based care incentives in United States Medicare Advantage plans expand reimbursement for early-stage vascular assessment in primary care ophthalmology settings.
- Wide-field imaging adoption:Ultra-widefield fundus camera installations at Japanese university hospitals drive replacement cycles for conventional narrow-angle systems.
Market Restraints
- Fluorescein sodium supply concentration:Three specialty chemical manufacturers control bulk dye production, exposing equipment vendors to input cost volatility and batch consistency risks.
- OCT angiography substitution:Non-invasive depth-resolved vascular mapping eliminates contrast agent handling requirements in premium-tier academic medical centers.
- FDA 510(k) clinical validation burdens:Post-market surveillance requirements for dye-based devices favor established manufacturers with regulatory infrastructure over new entrants.
Strategic Opportunities
- Rural ophthalmology networks in India:Mobile screening units equipped with portable fundus cameras address underpenetrated tier-2 and tier-3 city markets where diabetes prevalence outpaces diagnostic capacity.
- Artificial intelligence image analysis convergence:Automated leakage detection algorithms paired with angiography workflows reduce interpretation time and enable technician-operated screening models.
- United States IRA preventive care incentives:Medicare reimbursement expansion for chronic disease monitoring creates channel opportunities for integrated diagnostic-therapeutic platforms.
Industry Challenges
- Retinal imaging specialist workforce gaps:Qualified ophthalmic photographers capable of dye injection protocols and timing-sequence capture remain scarce outside major metropolitan hospital systems.
- Legacy PACS integration complexity:Proprietary image formats from angiography systems require costly middleware development to connect with hospital-wide electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescein Angiography Market |
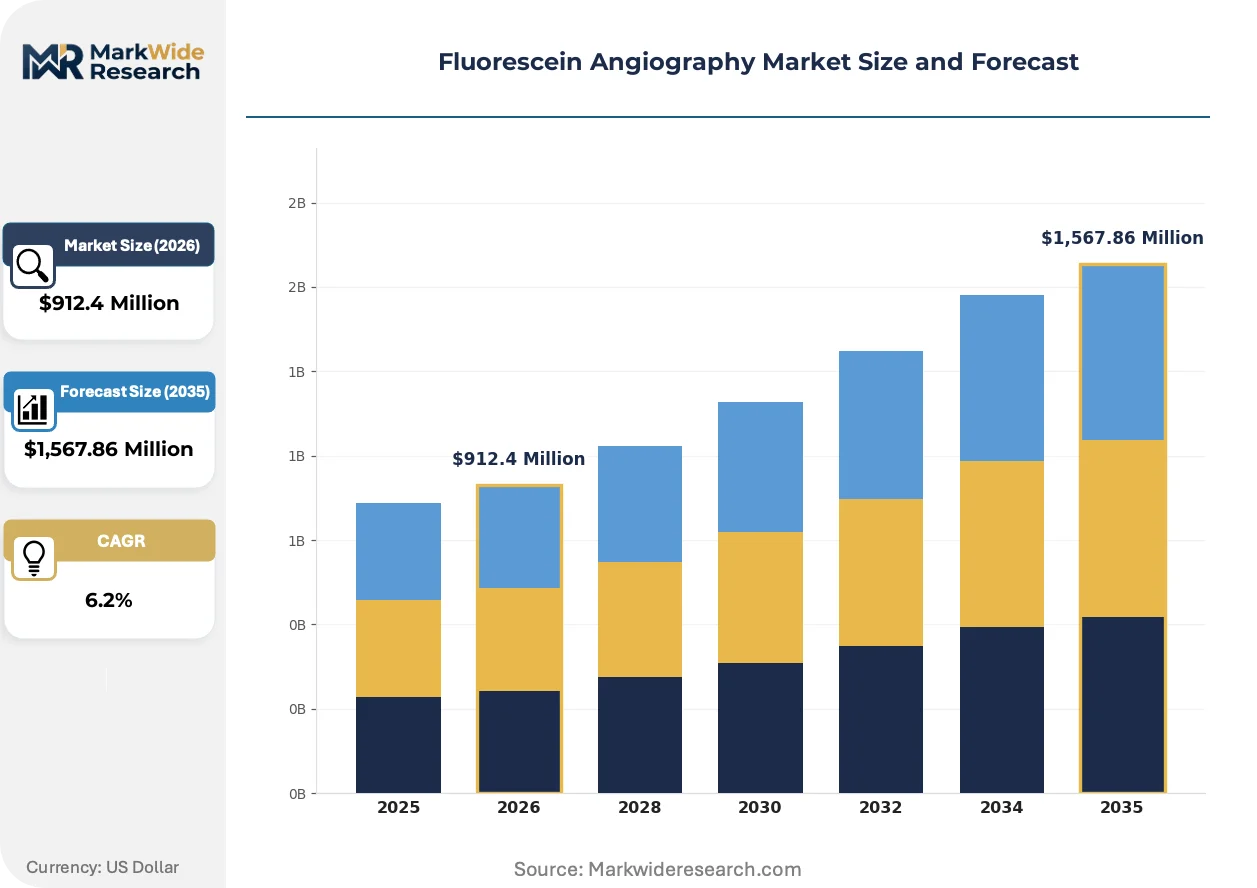
| Market Size in 2026 | $912.4 Million |
| Market Size in 2035 | $1,567.86 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescein Sodium, Indocyanine Green, Optical Coherence Tomography Angiography, Others Application: Retinal Disease Diagnosis, Vision Loss Assessment, Diabetic Retinopathy Monitoring, Choroidal Imaging End User: Hospitals, Ophthalmology Clinics, Diagnostic Laboratories, Academic Research Institutions Technology: Fundus Photography, Wide-field Imaging, Classic Angiography, Digital Imaging |
| Companies Covered | Kowa Company, Ltd., Optomed PLC, Canon, Inc., Heidelberg Engineering GmbH, Centervue SpA, Carl Zeiss Meditec AG, Topcon Medical Systems, Inc., Optos PLC, NIDEK CO., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescein Angiography Market Strategic Shifts & Innovations
Software-defined imaging platforms are displacing hardware-centric equipment sales models across ophthalmology diagnostics, with vendors bundling artificial intelligence modules and cloud-based image management to secure recurring revenue streams beyond initial system placement.
Adaptive optics technology is integrating high-resolution cellular imaging capabilities into conventional fundus camera architectures. Academic medical centers in Germany and Japan are piloting these hybrid systems for photoreceptor layer assessment. The technology is integrating research-grade visualization into clinical workflows previously requiring separate confocal scanning laser ophthalmoscopes.
EPA hazardous waste regulations governing fluorescein sodium disposal are tightening environmental handling requirements for outpatient clinics. United States ophthalmology practices face elevated compliance costs for contrast agent containment and documented disposal chain-of-custody. Smaller independent clinics are consolidating into hospital-affiliated networks to offload regulatory liability.
Equipment-as-a-service financing models are replacing capital purchase arrangements in mid-tier ophthalmology practices. Third-party lessors and manufacturer captive finance arms now dominate United States and German transactions between $150,000 and $400,000 system values. Japanese clinic chains are experimenting with per-procedure leasing structures tied to monthly imaging volumes.
Fluorescein Angiography Market Segmentation
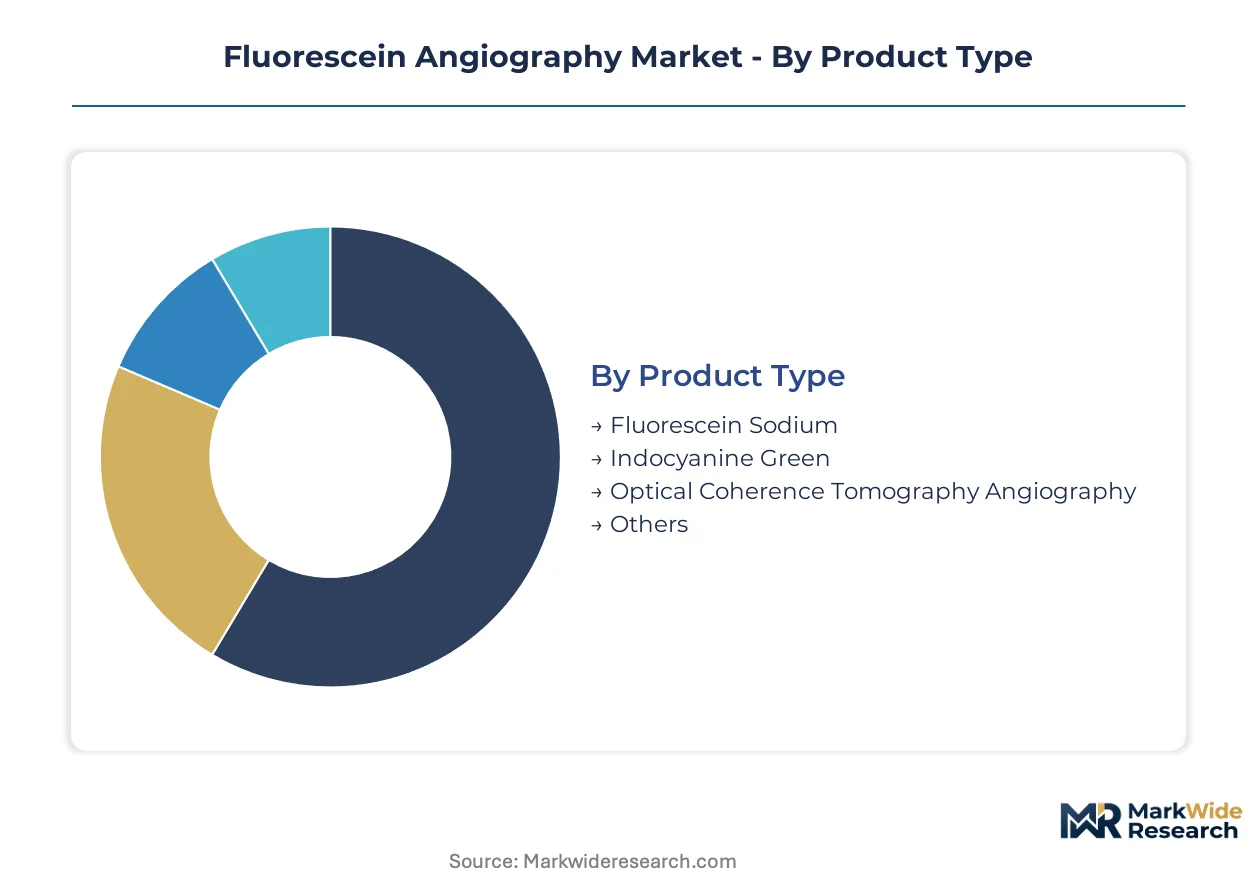
Fluorescein angiography equipment configurations vary sharply by diagnostic workflow requirements, dye compatibility, and integration depth with surgical platforms. Procurement decisions hinge on whether facilities prioritize traditional dye-based vascular mapping or non-invasive alternatives that eliminate contrast agent handling.
Product Type:
Technology specifications determine reimbursement pathways and capital allocation priorities across ophthalmology service lines.
- Fluorescein Sodium:Intravenous dye excitation at 465-490 nm remains the reference standard for macular edema detection. United States hospital outpatient departments concentrate procurement for Medicare-reimbursable procedures requiring documented leakage patterns.
- Indocyanine Green:Near-infrared excitation penetrates retinal pigment epithelium for choroidal neovascularization assessment. Japanese university hospitals drive adoption for polypoidal choroidal vasculopathy protocols where fluorescein yields insufficient contrast.
- Optical Coherence Tomography Angiography:Depth-resolved vascular mapping eliminates injection protocols entirely. Academic medical centers in Germany prioritize this modality for research-grade longitudinal studies.
- Others:Includes hybrid contrast agents and experimental fluorescent compounds under early-phase clinical investigation.
Mature deployment sits with Fluorescein Sodium. Newer deployment is concentrated in Optical Coherence Tomography Angiography.
Application:
Clinical indication severity shapes equipment specification requirements and imaging protocol complexity.
- Retinal Disease Diagnosis:Age-related macular degeneration screening protocols generate the highest imaging volume across United States Medicare Advantage networks. Wide-field systems capture peripheral pathology missed by standard-angle configurations.
- Diabetic Retinopathy Monitoring:Value-based care incentives accelerate early-stage vascular assessment in primary care ophthalmology settings. This segment is climbing the fastest as diabetes prevalence outpaces diagnostic capacity in tier-2 Indian cities.
- Vision Loss Assessment:Differential diagnosis protocols require sequential multimodal imaging combining angiography with structural OCT.
- Choroidal Imaging:Indocyanine green dependency limits adoption to specialized referral centers with dye handling infrastructure.
Established clinical workflows center on Retinal Disease Diagnosis. Emerging protocol expansion targets Diabetic Retinopathy Monitoring.
End User:
Capital intensity and regulatory liability distribution determine customer tier boundaries.
- Hospitals:Integrated health systems amortize equipment costs across high-throughput surgical-ophthalmology departments. United States hospital-affiliated networks absorb regulatory compliance burdens for dye disposal that independent practices cannot shoulder.
- Ophthalmology Clinics:Mid-tier independent practices in Germany consolidate into purchasing cooperatives to negotiate equipment-as-a-service financing structures.
- Diagnostic Laboratories:Centralized reading centers process outsourced angiography interpretation for rural networks lacking on-site specialists.
- Academic Research Institutions:Heidelberg and Tokyo medical schools drive adaptive optics integration for photoreceptor layer visualization protocols.
Volume concentration remains with Hospitals. Capability investment is accelerating fastest among Ophthalmology Clinics.
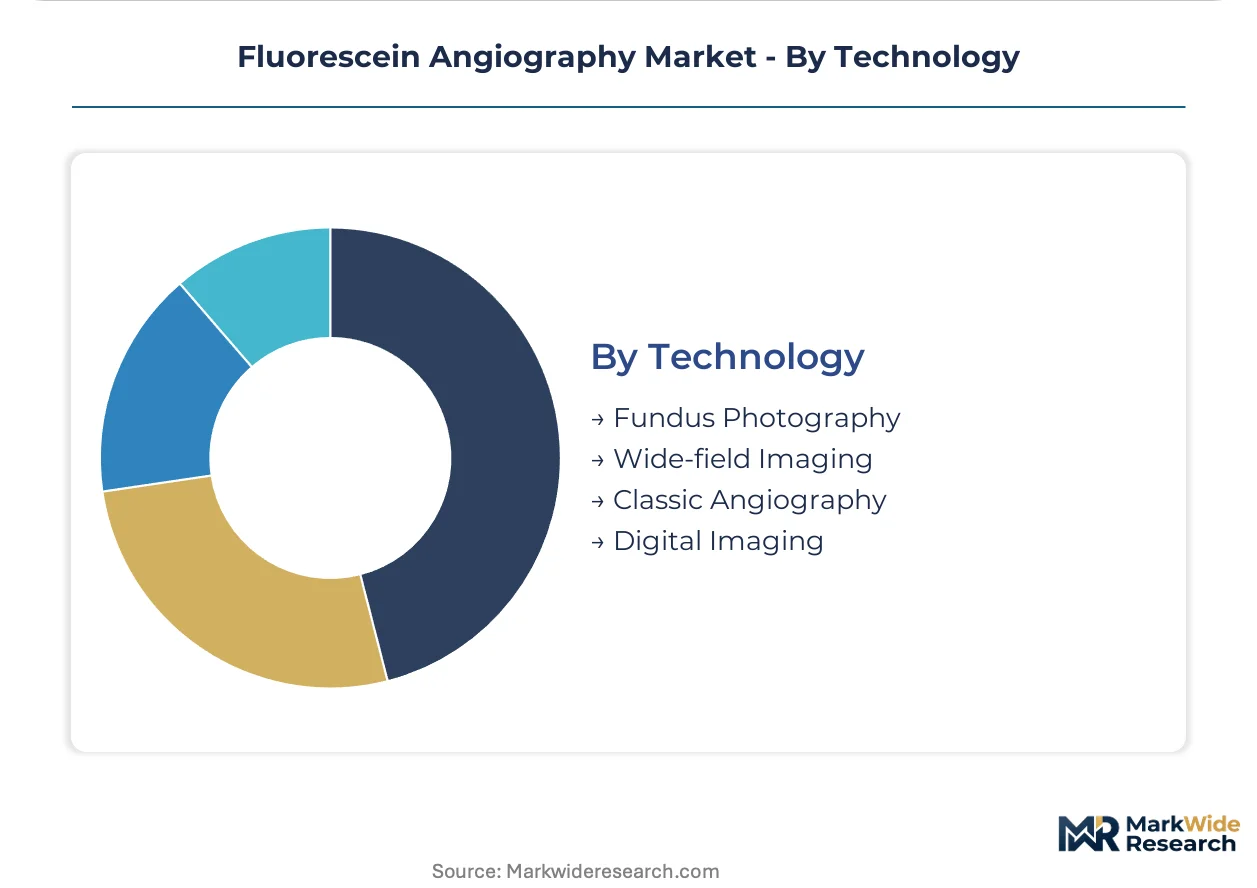
Technology:
Image acquisition architecture determines resolution limits, field of view, and interoperability with PACS infrastructure.
- Fundus Photography:Sequential narrow-angle capture at 30-50 degree fields dominates legacy installed bases. Japanese optical equipment producers are rebalancing supply chains toward in-house production of high-resolution camera components.
- Wide-field Imaging:Ultra-widefield systems spanning 200 degrees enable single-capture peripheral retinal assessment. University hospitals in Japan drive replacement cycles for conventional narrow-angle configurations.
- Classic Angiography:Film-based or early digital systems persist in budget-constrained settings with limited upgrade capital.
- Digital Imaging:Software-defined platforms with AI-assisted leakage detection reduce interpretation time and enable technician-operated screening models.
Installed base density favors Fundus Photography. Upgrade momentum is strongest for Wide-field Imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorescein sodium production concentrates among specialty chemical manufacturers in Germany and Japan, anchoring equipment supply chains for retinal diagnostic systems. Hospital procurement frameworks and aging demographics shape regional demand trajectories.
United States
Medicare Advantage value-based care incentives expand reimbursement for diabetic retinopathy screening in primary care ophthalmology settings. FDA 510(k) clearance pathways and EPA hazardous waste regulations govern dye disposal protocols for outpatient clinics. The Cleveland Clinic and Massachusetts Eye and Ear drive adoption of wide-field imaging systems for peripheral retinal assessment.
Germany
EU Medical Device Regulation harmonization accelerates CE marking for ophthalmic diagnostics across hospital procurement networks. Heidelberg and Munich university medical centers pilot adaptive optics integration for photoreceptor layer visualization. Carl Zeiss Meditec AG leverages its surgical-ophthalmology ecosystem for integrated practice workflows.
Japan
METI industrial policy supports domestic production of high-resolution fundus camera components by optical equipment producers. PMDA regulatory frameworks align with international standards for ophthalmic device approval. Tokyo and Osaka university hospitals drive replacement cycles for ultra-widefield systems capturing 200-degree peripheral fields.
India
Rising diabetes prevalence in tier-2 and tier-3 cities outpaces diagnostic capacity for retinal vascular assessment. CDSCO regulates medical device imports while domestic manufacturing incentives expand local production. Mobile screening units equipped with portable fundus cameras address underpenetrated markets in Maharashtra and Karnataka.
United Kingdom
NHS England screening programs for diabetic retinopathy generate sustained imaging volume across hospital eye services. MHRA post-market surveillance requirements align with EU MDR transition timelines. London and Manchester academic medical centers concentrate research-grade angiography platforms for longitudinal vascular studies.
Fluorescein Angiography Market Key Industry Players
Global majors compete with regional champions across regulatory compliance and integrated platform ecosystems. The vendor base stratifies between full-stack surgical-ophthalmology conglomerates and specialized diagnostic equipment fabricators. Three archetypes dominate: diversified medtech conglomerates with cross-selling ecosystems, precision optics specialists with captive component supply, and cost-optimized digital imaging vendors targeting mid-tier clinics. Incumbent manufacturers defend installed base positions through software upgrades and hybrid platform bundling while new entrants face FDA 510(k) clinical validation burdens.
Among German-based precision optics and medical technology groups, Heidelberg Engineering GmbH and Carl Zeiss Meditec AG exemplify the integrated platform archetype, anchoring positions through proprietary technology ecosystems that combine multiple diagnostic modalities. Japanese optical equipment specialists including NIDEK CO., Ltd. and Canon, Inc. occupy cost-optimized and imaging component tiers respectively, with Kowa Company, Ltd. representing regional champions focused on fundus camera specialization. These named entities illustrate competitive positioning across premium research-grade, mid-tier clinical, and portable screening market vectors without ascribing specific strategic actions or market share claims to individual firms.
| Leading Market Players |
|---|
| Kowa Company, Ltd. |
| Optomed PLC |
| Canon, Inc. |
| Heidelberg Engineering GmbH |
| Centervue SpA |
| Carl Zeiss Meditec AG |
| Topcon Medical Systems, Inc. |
| Optos PLC |
| NIDEK CO., Ltd. |
| Others |
Cost & Logistics Intelligence
Equipment-as-a-service financing arms at Carl Zeiss Meditec AG and Heidelberg Engineering GmbH anchor pricing discipline through captive leasing structures that bundle maintenance, software upgrades, and regulatory compliance support into multi-year contracts, insulating premium-tier vendors from spot-market volatility while compressing margins for independent distributors of unbundled hardware.
Pricing Analysis
Warranty and service bundling separates premium vendors from mid-tier competitors, with Heidelberg Engineering GmbH and Carl Zeiss Meditec AG including predictive maintenance and AI module updates in subscription pricing while NIDEK CO., Ltd. and regional champions compete on unbundled capital purchase models. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA 510(k) certification tiers and field-of-view specifications. Cost compression in the mid-tier is intensifying because OCT angiography substitution eliminates dye-handling revenue streams for conventional system vendors. Hospital-affiliated networks in the United States exhibit lowest price sensitivity due to integrated procurement frameworks, while independent ophthalmology clinics in India and tier-2 German cities face acute capital constraints.
Supply Chain Analysis
Single-source vulnerability sits with fluorescein sodium dye production concentrated among specialty chemical manufacturers in Germany and Japan, exposing equipment vendors to batch consistency risks and input cost volatility. High-resolution fundus camera optics draw from Japanese optical component fabricators, while excitation filter assemblies and digital sensor arrays source from German precision optics specialists and South Korean semiconductor foundries respectively. Tariff exposure on imported dye shipments and optical subassemblies threatens margin stability for vendors without captive chemical synthesis or backward integration into lens grinding. Distribution runs through manufacturer-direct sales forces for hospital systems and specialized ophthalmology distributors for mid-tier clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescein angiography equipment supply remains constrained by the scarcity of qualified ophthalmic photographers capable of dye injection protocols, propping pricing power for vendors who bundle training and technician certification into system sales.
For Market Incumbents: Deploy software-defined imaging platforms to defend installed base positions against OCT angiography substitution, bundling AI-assisted leakage detection and cloud-based image management to secure recurring revenue beyond initial hardware placement. Backward integration into fluorescein sodium synthesis or exclusive dye supply agreements mitigates input cost volatility from the three-manufacturer concentration. Channel control through equipment-as-a-service financing arms locks mid-tier clinics into multi-year contracts that raise switching costs. For New Entrants and Emerging Players: Enter via portable fundus camera configurations for mobile diabetic retinopathy screening units in India's tier-2 and tier-3 cities, where diabetes prevalence outpaces diagnostic capacity and CDSCO import regulations favor lightweight, lower-cost systems. Technician-operated screening models with automated image interpretation reduce dependency on scarce ophthalmic photographers. Partner with domestic Indian distributors who maintain relationships with Maharashtra and Karnataka state health departments. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized diagnostic equipment fabricators with FDA 510(k) clearance infrastructure and established GPO contracts in United States hospital systems, particularly those positioned for Medicare reimbursement expansion under IRA preventive care incentives. Long-term viability hinges on hybrid platform capabilities that bridge dye-based and OCT angiography modalities. Watch for reimbursement code revisions that accelerate technology substitution decisions across ophthalmology service lines.| Strategic Initiative | Industry Significance |
|---|---|
| AI Image Analysis Integration | Automated leakage detection algorithms reduce interpretation time and enable technician-operated screening in rural networks. |
| Wide-field Imaging System Launch | Ultra-widefield fundus cameras capture 200-degree peripheral fields that conventional narrow-angle systems miss. |
| CE Marking Pathway Acceleration | EU MDR harmonization streamlines product introductions across German, French, and Italian hospital procurement frameworks. |
| Hospital System Partnership | Integrated health systems amortize equipment costs across high-throughput surgical-ophthalmology departments. |
| Reimbursement Strategy Development | Medicare Advantage value-based care incentives expand coverage for diabetic retinopathy screening protocols. |
Research Approach
Independent corroboration across ophthalmic equipment procurement managers, biomedical engineers at academic medical centers, and GPO contracts specialists underwrites the qualitative findings, with secondary validation drawing from FDA 510(k) clearance databases, PMDA ophthalmic device registrations, and hospital capital expenditure disclosures. Bottom-up triangulation across installed base estimates and top-down cross-checks against Medicare reimbursement volume data anchor segmentation splits by product type, application, and end user.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon, with CAGRs derived from logistic diffusion curves modeling OCT angiography substitution rates and replacement cycles for legacy fundus photography systems. Segmentation dimensions include dye-based versus non-invasive technology, hospital versus clinic end-use, and geographic regulatory clusters spanning FDA, EU MDR, PMDA, and CDSCO jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated OCT angiography reimbursement code revisions or fluorescein sodium supply disruptions. Forecasts reflect assumptions about diabetic retinopathy screening protocol expansion, software upgrade attachment rates, and technician workforce development timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
Digital Pathology Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Perfusion Imaging Market