
 Global Refrigerated Display Cases and Chilled Rooms Market | 2026-2036
Global Refrigerated Display Cases and Chilled Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigerated Display Cases and Chilled Rooms Market Outlook
Remote monitoring and predictive maintenance subscriptions is rebalancing how buyers evaluate total cost of ownership across the equipment lifecycle. Hussmann Corporation leverages its service network density to anchor recurring revenue streams alongside hardware sales. Carrier Commercial Refrigeration sustains technology leadership through deep controls integration, while Epta S.p.A. specializes in natural refrigerant architectures for European retail chains.
Refrigerated display cases and chilled rooms are insulated enclosures employing vapor-compression or thermoelectric cooling to maintain temperatures between minus 25 degrees Celsius and plus 10 degrees Celsius for product preservation and visual merchandising. Glass door refrigerators dominate supermarket retrofit budgets where energy loss reduction justifies premium capital outlay, while open display merchandisers face structural pressure from sustainability audits despite superior impulse-purchase conversion. Blast chillers represent the fastest-growing product category as food service operators confront tightening food safety protocols.
The EPA SNAP program and EU F-Gas Regulation are phasing down hydrofluorocarbon refrigerants, forcing manufacturers to redesign compressor architectures and certify propane-based alternatives. ISO 23953 standards for refrigerated display cabinets shape export eligibility and thermal performance benchmarking across jurisdictions. Stakeholders must weigh natural refrigerant readiness against regional service infrastructure maturity when allocating R&D and manufacturing capacity.
Market Dynamics
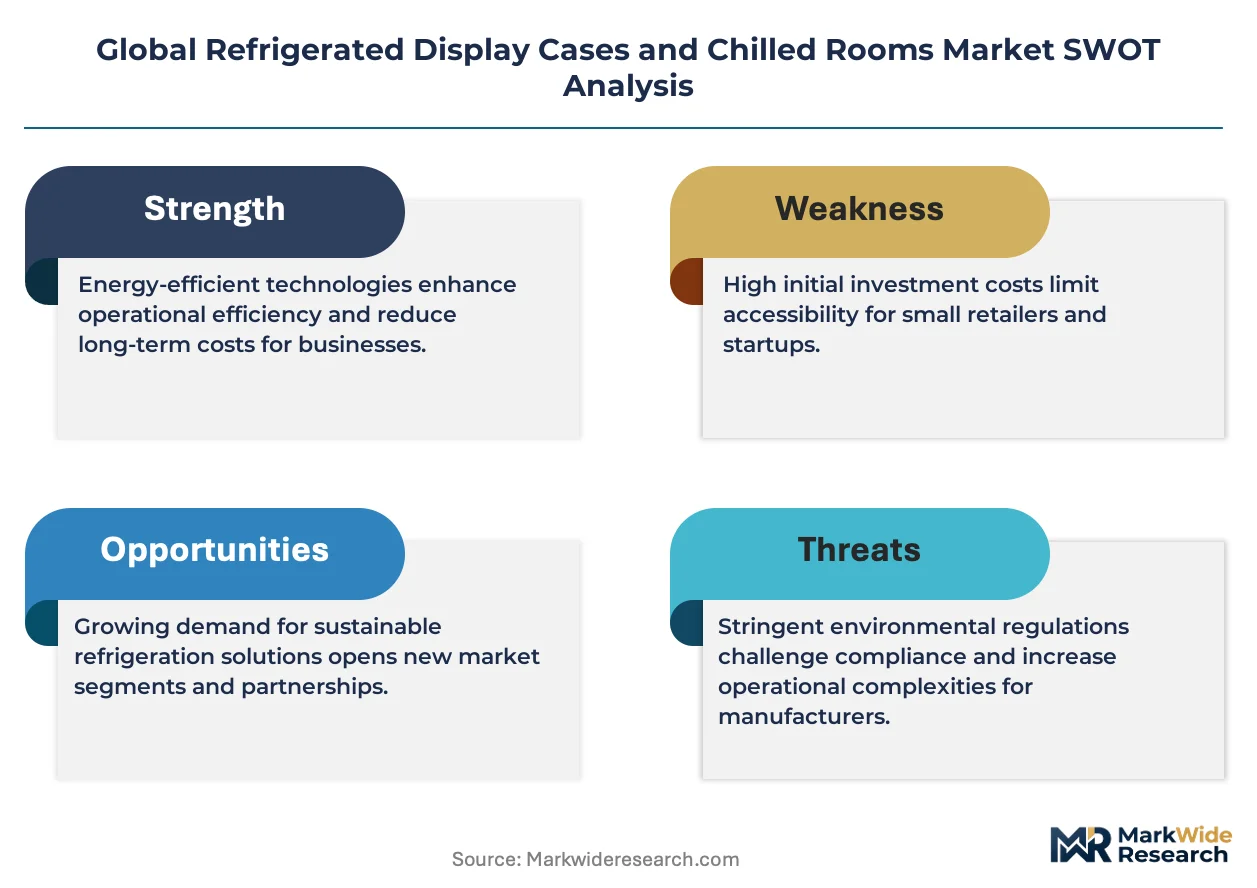
Equipment replacement cycles across food retail are compressing as the EU F-Gas Regulation and EPA SNAP program force simultaneous refrigerant transitions and energy-efficiency upgrades, creating a synchronized demand pulse that favors turnkey solution providers over component vendors.
Growth Catalysts
- Natural refrigerant mandates:The EU F-Gas Regulation's phasedown schedule accelerates retrofit demand as retailers face compliance deadlines for hydrofluorocarbon phaseout.
- Food safety protocol tightening:Food service operators in Germany and the United States are deploying blast chillers to meet HACCP-aligned temperature control requirements for prepared foods.
- Energy-efficiency retrofit programs:Utility-sponsored rebate schemes in China subsidize glass door retrofits that reduce cooling load and operating expenditure.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and coil fabrication costs fluctuate with commodity markets, compressing margin stability for equipment fabricators.
- Compressor supply concentration:European and Asian sourcing dependencies for variable-speed scroll compressors create lead time vulnerability during demand surges.
- Propane charge limits:IEC 60335-2-89 safety standards cap refrigerant quantities in self-contained cases, constraining unit capacity for large-format merchandisers.
Strategic Opportunities
- India cold-chain infrastructure gaps:Organized food retail penetration below 10 percent leaves substantial room for first-mover equipment deployment in tier-two cities.
- Predictive maintenance convergence:IoT sensor integration with refrigeration controls enables subscription revenue models that decouple service income from hardware shipment cycles.
- Carbon border adjustment alignment:EU CBAM implementation rewards low-global-warming-potential equipment imports, favoring natural refrigerant-ready manufacturers.
Industry Challenges
- Certified technician scarcity:Hydrocarbon refrigerant handling requires specialized training that outpaces vocational program output in North American and European markets.
- Legacy control system fragmentation:Proprietary communication protocols from incumbent building management systems complicate seamless integration of new refrigerated cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigerated Display Cases and Chilled Rooms Market |
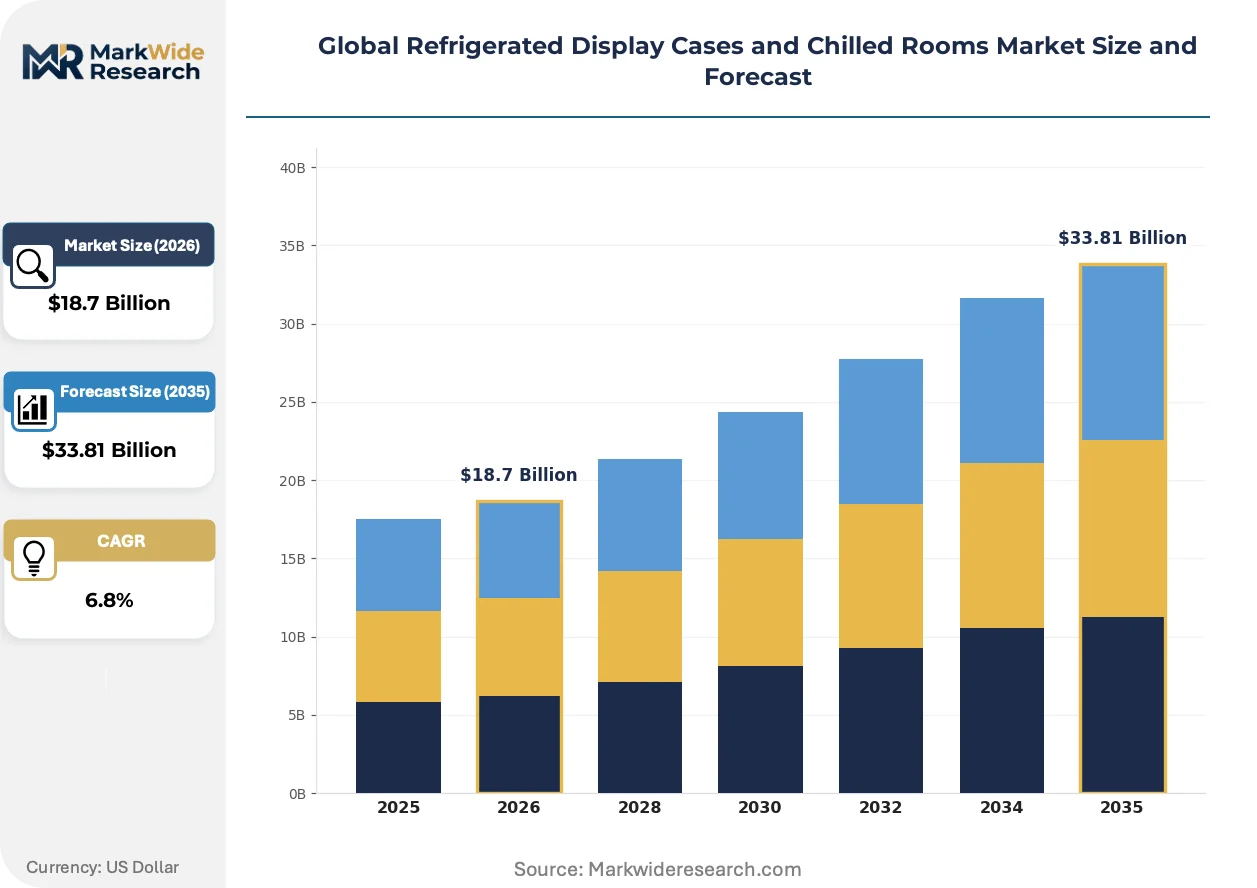
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Door Refrigerators, Open Display Merchandisers, Ice Cream Freezers, Blast Chillers End User: Retail Outlets, Food Service, Supermarkets, Convenience Stores Installation Type: Freestanding, Built-in, Modular, Portable Technology: Refrigeration System, Thermoelectric, Propane-Based, Air-Cooled |
| Companies Covered | Hussmann Corporation, Carrier Commercial Refrigeration, Illinois Tool Works Inc., Hoshizaki International, Epta S.p.A., AHT Cooling Systems GmbH, Lennox International, Dover Corporation, Metalfrio Solutions S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigerated Display Cases and Chilled Rooms Market Strategic Shifts
Refrigeration architecture is pivoting from hardware-centric sales toward integrated energy-service offerings, with digital controls and natural working fluids acting as the twin levers of competitive differentiation.
Transcritical CO₂ booster systems are electrifying supermarket refrigeration infrastructure by eliminating synthetic refrigerant dependency entirely. German and Nordic retailers are deploying these architectures at scale, with Danish and Swedish operators now specifying CO₂ as default for new-build stores. The technology is compressing the addressable market for traditional HFC-based distributed systems.
The EPA SNAP program's final rule on hydrofluorocarbon restrictions is forcing compressor OEMs to recalibrate product portfolios toward A3 safety group refrigerants. Equipment manufacturers must recertify entire model lines under UL 60335-2-89, extending new product introduction timelines by 12 to 18 months. California's Air Resources Board is mirroring this trajectory with accelerated phaseout schedules that pressure West Coast retrofit activity.
Buying committees now unbundle equipment procurement from long-term service agreements, reversing the bundled sale norm that dominated prior decades. Food retail chains in the United States and United Kingdom are awarding separate contracts for installation, commissioning, and multi-year maintenance, forcing manufacturers to defend recurring revenue through standalone service excellence. This pattern is most pronounced among top-ten grocery operators with centralized procurement functions.
Global Refrigerated Display Cases and Chilled Rooms Market Segmentation
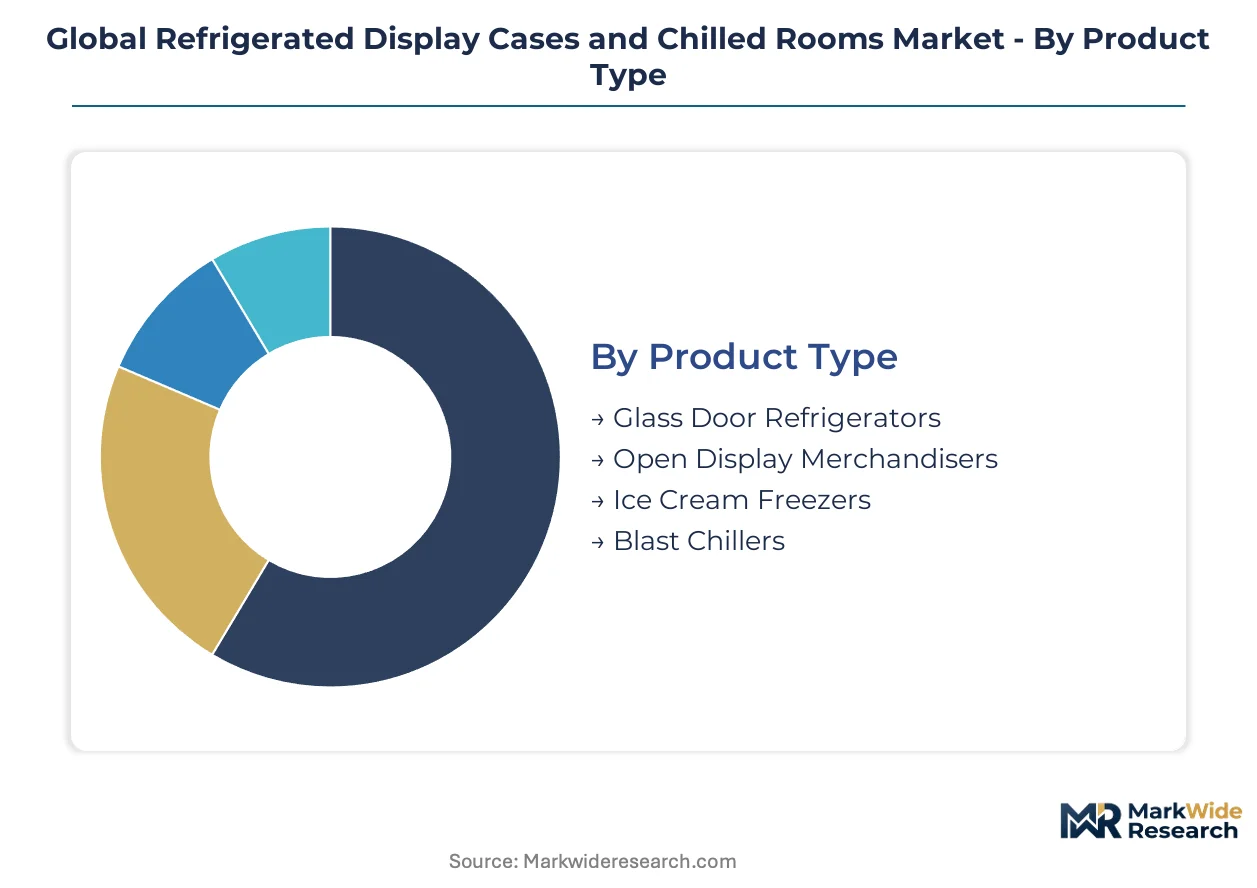
Equipment specification in refrigerated display cases and chilled rooms varies sharply by operational intensity and regulatory exposure. Buyers optimize capital allocation across product configurations, end-use environments, and installation constraints that determine lifecycle performance and compliance risk.
Product Type:
Standalone units dominate retrofit budgets where existing infrastructure limits integration flexibility, while embedded systems anchor new-build specifications requiring seamless architectural coordination.
- Glass Door Refrigerators:Insulated enclosures with transparent panels minimize thermal bridging and reduce cooling load in high-traffic retail environments. German supermarket operators prioritize these units under national energy-efficiency rebate schemes that reward door retrofits with operating expenditure reductions.
- Open Display Merchandisers:Unenclosed vertical cases maximize product visibility and impulse conversion through unobstructed customer access. Sustainability audits in California and New York are constraining deployment of these units as regulators target refrigerant leakage and energy intensity in open-architecture designs.
- Ice Cream Freezers:Low-temperature cabinets maintain minus 18 degrees Celsius for frozen dessert preservation in convenience store formats.
- Blast Chillers:Rapid-cooling systems reduce food core temperatures from cooking ranges to safe storage thresholds within regulatory time limits.
Glass door refrigerators lead volumes today; blast chillers are gaining share fastest.
End User:
Procurement sophistication varies by buyer scale, with centralized food retail chains demanding predictive maintenance integration that fragmented food service operators rarely specify.
- Retail Outlets:Department stores and specialty merchandisers deploy compact refrigerated cases for premium product categories including cosmetics and confectionery. Chinese luxury retail expansion in Shanghai and Shenzhen is driving specification of glass-door units with integrated digital controls.
- Food Service:Restaurants, hotels, and catering operations require HACCP-aligned temperature documentation and rapid recovery performance. Blast chiller demand concentrates in the United States where FDA Food Code updates tighten cooling protocol compliance for prepared foods.
- Supermarkets:Large-format grocers operate extensive cold-chain footprints with centralized refrigeration plants and distributed display case networks.
- Convenience Stores:Limited floor area forces compact freestanding configurations with reduced refrigerant charge requirements.
Supermarkets anchor current procurement volumes; food service is expanding most quickly.
Installation Type:
Site constraints and lease structures determine whether buyers favor permanent infrastructure or flexible repositionable assets.
- Freestanding:Self-contained units with integrated compressors require no remote piping and permit rapid deployment. Convenience store operators in India favor these configurations for tier-two city expansion where technical service infrastructure remains underdeveloped.
- Built-in:Flush-mounted cases integrate with architectural millwork and finish specifications in premium retail environments. European supermarket redesigns specify these units to optimize aisle width and customer flow in constrained urban locations.
- Modular:Prefabricated panel systems enable rapid assembly of walk-in chilled rooms with standardized dimensions.
- Portable:Castor-mounted units support temporary promotional displays and event catering requirements.
Freestanding configurations dominate shipment volumes; modular systems show the steepest expansion trajectory.
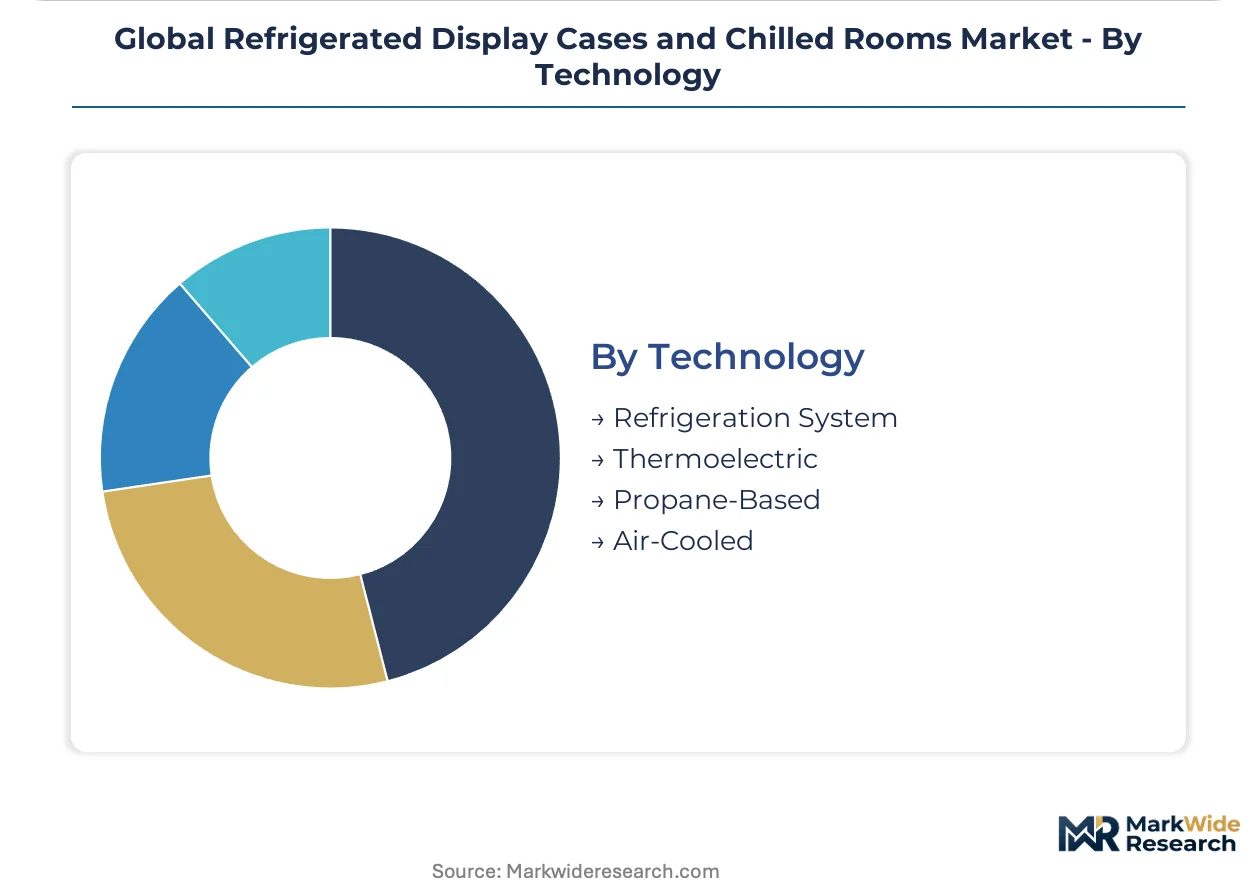
Technology:
Refrigerant selection and heat rejection architecture determine regulatory compliance eligibility and operating cost structure across climate zones.
- Refrigeration System:Vapor-compression architectures using synthetic or natural working fluids remain the baseline for commercial cooling capacity. EPA SNAP program phaseout schedules are forcing compressor OEMs to recalibrate portfolios toward hydrocarbon alternatives.
- Thermoelectric:Solid-state cooling eliminates moving parts and refrigerant charge in small-capacity applications. Japanese convenience store operators deploy these units for beverage merchandising where noise reduction and maintenance minimization justify premium capital outlay.
- Propane-Based:Hydrocarbon refrigerant systems achieve low global warming potential with charge limits under IEC 60335-2-89.
- Air-Cooled:Condenser configurations rejecting heat to ambient air simplify installation in water-scarce regions.
Conventional refrigeration systems retain volume leadership; propane-based architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retrofit intensity exceeds China's new-build velocity, while the United States navigates the most complex regulatory layering of refrigerant phaseout and state-level energy codes.
Germany
Supermarket operators prioritize transcritical CO₂ retrofits ahead of EU F-Gas Regulation deadlines. The national energy-efficiency rebate scheme subsidizes glass door replacements in Berlin and Hamburg metropolitan clusters. Bavarian equipment fabricators concentrate production capacity for propane-ready compressor architectures.
United States
West Coast retrofit demand surges under California Air Resources Board accelerated phaseout schedules. EPA SNAP program restrictions force simultaneous refrigerant and control system upgrades. Texas and Florida convenience store chains expand cold-chain footprints in Dallas-Fort Worth and Miami corridors.
China
Utility-sponsored rebate programs in Shanghai and Shenzhen subsidize energy-efficient display case deployments. SAMR enforcement of GB standards tightens thermal performance benchmarking for import eligibility. Yangtze River Delta supermarket operators modernize chilled room infrastructure in Nanjing and Hangzhou logistics hubs.
India
Organized food retail penetration below ten percent creates first-mover deployment opportunities in tier-two cities. FSSAI food safety protocol tightening drives blast chiller specification among food service operators. Maharashtra and Gujarat convenience store chains expand freestanding unit networks in Pune and Ahmedabad.
Japan
Convenience store operators deploy thermoelectric units for beverage merchandising under METI efficiency guidelines. JIS standards shape domestic procurement specifications that limit import competition. Tokyo and Osaka metropolitan clusters concentrate demand for compact, low-noise refrigeration architectures.
Global Refrigerated Display Cases and Chilled Rooms Market Competitive Environment
Top-tier vendors anchor integrated energy-service offerings, while mid-tier fabricators compete on natural refrigerant readiness and regional service density. The vendor base stratifies across turnkey solution providers, component specialists, and controls-integrated platforms. Strategic archetypes include service-network aggregators, hydrocarbon-system pioneers, and predictive maintenance platform builders. Competitive moves concentrate on M&A for service network expansion and technology licensing for natural refrigerant architectures.
Within the European specialist tier, Epta S.p.A. and AHT Cooling Systems GmbH exemplify hydrocarbon-ready fabrication capabilities. Hussmann Corporation and Carrier Commercial Refrigeration occupy positions among North American service-network aggregators. Illinois Tool Works Inc. represents the diversified industrial conglomerate archetype with refrigeration exposure.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Carrier Commercial Refrigeration |
| Illinois Tool Works Inc. |
| Hoshizaki International |
| Epta S.p.A. |
| AHT Cooling Systems GmbH |
| Lennox International |
| Dover Corporation |
| Metalfrio Solutions S.A. |
| Others |
Value Chain & Pricing Dynamics
Captive compressor production in Germany and China anchors margin control for tier-one manufacturers while locking in pricing power against commodity-exposed competitors. This backward integration into scroll compressor manufacturing insulates Hussmann and Carrier from copper and aluminum volatility that compresses margins for fabricators sourcing coils externally.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard glass door refrigerators as domestic OEMs expand export eligibility under SAMR-enforced GB standards. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified natural refrigerant units from legacy HFC architectures and basic freestanding imports. Pricing pressure stems from utility rebate arbitrage in Shanghai and Shenzhen that subsidizes energy-efficient retrofits. Convenience store operators in India exhibit highest price sensitivity, while German supermarket chains prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Container freight volatility from Asia to Europe and North America compresses margin stability for equipment fabricators dependent on Chinese coil and compressor imports. Manufacturing gravity centers on Germany, China, and the United States, with Bavarian fabricators concentrating propane-ready compressor production. Heat exchanger fabrication draws from copper and aluminum suppliers facing commodity price swings. Single-source vulnerability concentrates in variable-speed scroll compressor sourcing from European and Asian OEMs. Distribution runs through authorized service networks that anchor recurring revenue streams for incumbent vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's phasedown schedule compounds replacement demand into synchronized retrofit pulses that favor turnkey providers with natural refrigerant certification. This regulatory compounding accelerates equipment turnover beyond traditional depreciation cycles.
For Market Incumbents: Hedge margin erosion by securing captive compressor supply agreements with Bavarian and Yangtze River Delta manufacturers before IEC 60335-2-89 recertification deadlines tighten. Invest in predictive maintenance platform integration to defend recurring revenue as buying committees unbundle hardware from service contracts. Compressor supply concentration and technician certification scarcity represent the primary threats to service network density.
For New Entrants and Emerging Players: Begin with modular chilled room deployments in Indian tier-two cities where organized food retail penetration remains below ten percent and FSSAI protocol tightening drives first-mover specification. Target blast chiller segments in United States food service where FDA Food Code updates accelerate HACCP-aligned procurement. Lead with thermoelectric beverage merchandising for Japanese convenience store operators under METI efficiency guidelines.
For Investors and Strategic Acquirers: Roll-up economics work for regional service-network aggregators because certified hydrocarbon technician scarcity creates defensive moats around maintenance revenue pools. Five-to-ten year viability hinges on natural refrigerant readiness rather than legacy HFC portfolio scale. Monitor California Air Resources Board enforcement velocity as the inflection signal for West Coast retrofit acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Certification Investment | UL 60335-2-89 recertification extends product eligibility under EPA SNAP program restrictions. |
| Predictive Maintenance Platform Development | IoT sensor integration enables subscription revenue decoupled from hardware shipment cycles. |
| Service Network Geographic Expansion | Density in tier-two Indian cities captures FSSAI-driven blast chiller specification growth. |
| Backward Integration into Compressor Manufacturing | Captive production insulates margin from copper and aluminum commodity volatility. |
| Transcritical CO₂ System Deployment | German rebate schemes subsidize retrofit architectures eliminating synthetic refrigerant dependency. |
Study Parameters
Bottom-up food retail and food service modeling reconciled against top-down equipment shipment tracking forms the analytical core. Primary interviews with supermarket procurement directors, convenience store operations managers, refrigeration contractor service heads, and compressor OEM technical directors combined with secondary validation from EPA SNAP program filings, EU F-Gas Regulation implementation reports, SAMR GB standard enforcement notices, and utility rebate scheme disclosures. Trade flow analysis and customs data triangulate against manufacturer production disclosures.
Input-output matrices map refrigerant transition timelines against replacement cycle compression across product type, end-use, installation configuration, and technology archetype segments. CAGRs derive from equipment unit economics modeled against energy-efficiency retrofit program budgets and regulatory compliance deadline clustering. Forecast inputs include F-Gas Regulation phasedown schedules, EPA SNAP rule implementation velocity, and SAMR thermal performance benchmarking enforcement intensity.
Several conditions sit outside the modeled scope, including unannounced refrigerant safety standard revisions, abrupt commodity price shocks beyond historical volatility bands, and geopolitical trade restrictions affecting compressor cross-border movement. Forecasts reflect documented assumptions about regulatory enforcement consistency and rebate program continuity. Stakeholders should weight assumptions against their own operating context and regional service infrastructure maturity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Food Display Cabinet Market