
 Commercial Refrigerator Market | 2026-2036
Commercial Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Refrigerator Market Intelligence
The substitution of hydrofluorocarbons (HFCs) with natural refrigerants like CO2 and propane is broadening the range of available cooling technologies for end users. Carrier Global Corporation leverages its extensive distribution network to supply these advanced systems to retailers. Danfoss A/S specializes in component manufacturing, including compressors and valves optimized for new refrigerants. Hussmann Corporation focuses on display cases and systems for the grocery sector.
Commercial refrigerators are engineered cooling systems designed for non-residential environments. These units typically utilize a vapor-compression cycle to maintain precise internal temperatures, often between -18°C and 4°C, for the preservation of perishable items. Reach-in refrigerators constitute the largest product type segment by volume, primarily serving the food service industry. In contrast, walk-in coolers and blast chillers for pharmaceutical storage and food processing centers represent higher-value applications.
Regulations such as the US EPA's SNAP program and the EU's F-Gas Regulation are phasing out high-GWP refrigerants. Concurrently, energy efficiency mandates like China's GB standards and ENERGY STAR certification in the United States push manufacturers toward more efficient designs. Navigating the total cost of ownership, which balances initial investment with energy savings and compliance, remains the central challenge for end users.
Market Dynamics
The mandatory global transition away from high-GWP refrigerants, enforced by frameworks like the EU F-Gas Regulation and the US EPA's SNAP program, is the central structural force shaping the market. This shift necessitates fundamental redesigns of cooling systems and components.
Growth Catalysts
- Organized Retail Expansion:The proliferation of supermarkets, hypermarkets, and food processing centers in India, driven by policies supporting the cold chain, is creating sustained demand for commercial-grade refrigeration equipment.
- Regulatory Mandates:The EU F-Gas Regulation is actively compelling the replacement of HFCs, accelerating the adoption of systems that use natural refrigerants like CO2 and propane across the food service and retail sectors.
- Energy Efficiency Gains:The development of advanced components, including variable-speed compressors and electronically commutated motors, lowers the total cost of ownership, making new equipment purchases more attractive for end users focused on operational savings.
Market Restraints
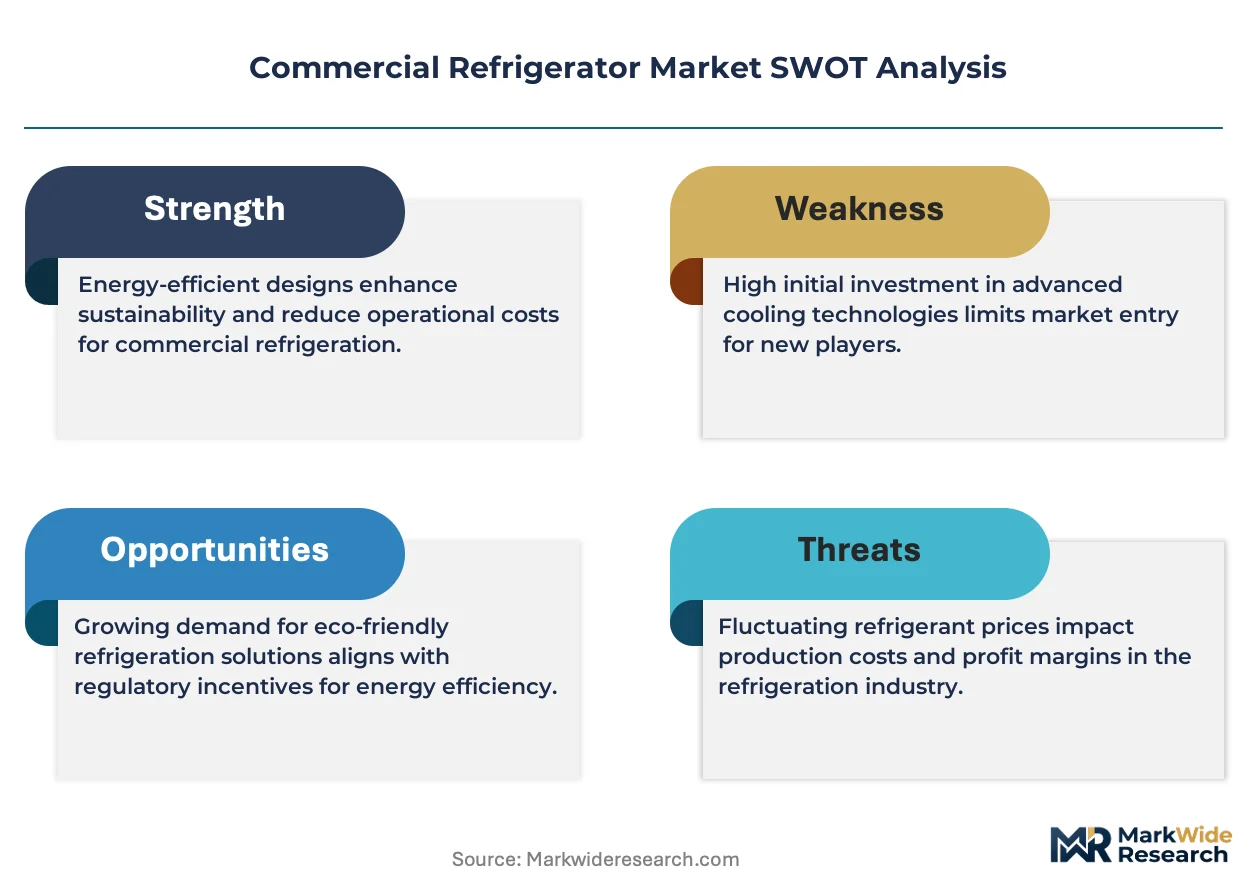
- High Initial Investment:Natural refrigerant systems, particularly transcritical CO2 installations, often carry a higher upfront capital cost compared to traditional HFC-based equipment, acting as a barrier for smaller businesses.
- Refrigerant Handling Risks:The flammability of hydrocarbon refrigerants like propane (R290) requires specialized technician training and adherence to strict safety codes, limiting deployment in certain environments.
- Component Sourcing:The supply of critical components optimized for new refrigerants, such as high-pressure valves and controls for CO2 systems, is concentrated among a few specialized manufacturers, creating potential supply chain vulnerabilities.
Strategic Opportunities
- Pharmaceutical Cold Chain:The growing market for biologics, vaccines, and cell therapies requires precise, reliable, and documented temperature control, opening a high-value application segment for specialized blast chillers and pharmacy-grade refrigerators.
- IoT-Enabled Services:Integrating IoT sensors for remote temperature monitoring, predictive maintenance alerts, and energy usage analytics provides manufacturers an opportunity to offer value-added service contracts beyond the initial equipment sale.
- Emerging Market Modernization:The modernization of food retail and hospitality sectors in Southeast Asia and Latin America presents a significant opportunity for walk-in coolers and display cases as local businesses upgrade from less efficient or smaller-scale solutions.
Industry Challenges
- Technician Skill Gap:A persistent shortage of service technicians trained to safely install, maintain, and repair systems using CO2 and flammable hydrocarbon refrigerants is a primary operational bottleneck for end users.
- Regulatory Fragmentation:Manufacturers must navigate a complex and often inconsistent patchwork of national and regional energy efficiency standards, such as ENERGY STAR in the US and GB standards in China, increasing compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Refrigerator Market |
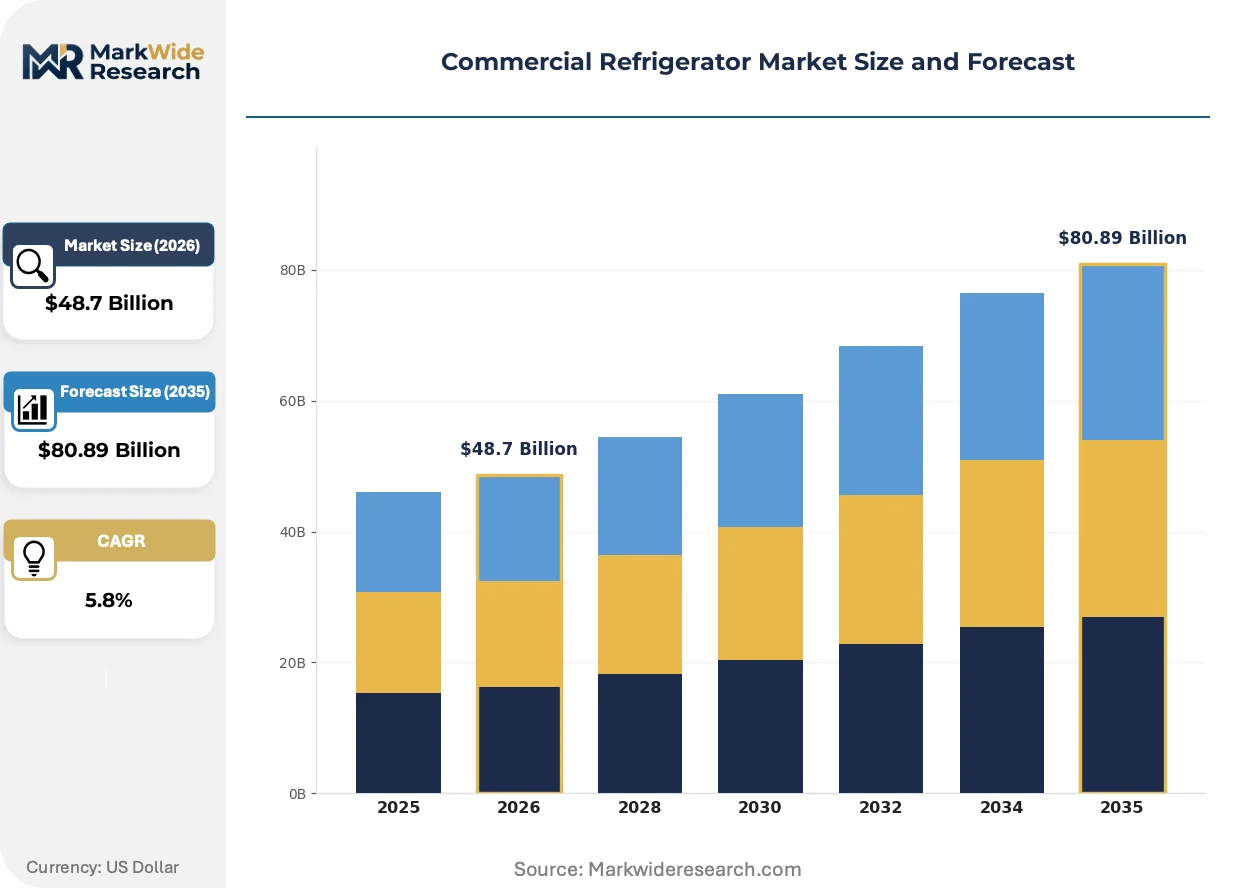
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reach-In Refrigerators, Display Freezers, Undercounter Refrigerators, Walk-In Coolers, Blast Chillers Technology: Compression, Absorption, Thermoelectric, Magnetic, Cryogenic Application: Food Service, Beverage Cooling, Pharmaceutical Storage, Laboratory Preservation, Floriculture End User: Restaurants, Hotels, Catering Companies, Retailers, Food Processing Centers |
| Companies Covered | Daikin Industries Ltd., Johnson Controls, Hussmann Corporation, Danfoss A/S, Dover Corporation, Haier Inc., AB Electrolux, Carrier Global Corporation, EPTA Corporate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Refrigerator Market Strategic Shifts & Innovations
Sustainability mandates and digital connectivity are converging to redefine commercial refrigeration. This is pushing innovation beyond mere cooling efficiency toward intelligent, networked systems that actively manage energy consumption and operational data across fleets of equipment.
Natural refrigerants like CO2 and propane provide cooling with a near-zero global warming potential. Supermarkets and food service chains are leading adoption, driven by regulatory compliance and corporate sustainability targets. The use of these alternatives is unifying system design principles around safety and high-pressure componentry, standardizing service protocols that were previously fragmented.
China's GB standards for energy efficiency in commercial equipment are among the most stringent globally. These regulations compel manufacturers to innovate on product designs, incorporating features like advanced insulation and variable-speed drives to meet market access requirements. Display cases and reach-in units are the most affected segments, with successful designs often becoming benchmarks for other markets.
A clear shift in buying behavior toward evaluating the total cost of ownership (TCO) is evident. This model, which prioritizes long-term energy savings and maintenance costs over low upfront price, is displacing traditional purchasing decisions. The trend is most visible among large grocery and quick-service restaurant chains in North America and Europe, where high energy costs make TCO a critical metric.
Commercial Refrigerator Market Segmentation
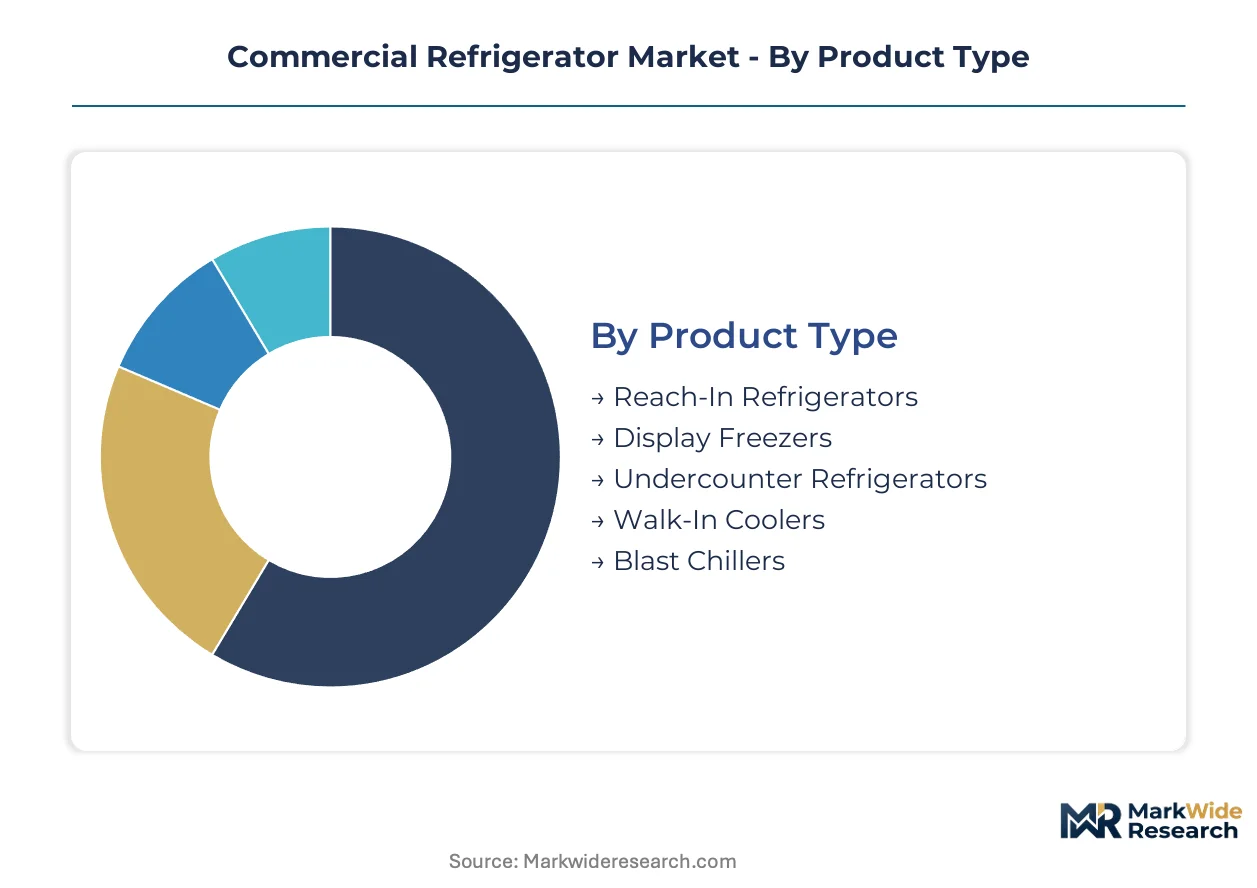
The segmentation analysis provides a granular view of the commercial refrigerator market's diverse offerings and demand patterns. Understanding these distinct segments helps manufacturers tailor product development and target specific end-user requirements. This detailed breakdown highlights areas of volume concentration and specialized high-value applications across the industry.
Product Type:
The product type segmentation reveals a clear distinction between high-volume, standardized units and specialized, higher-value equipment. Each category addresses specific operational needs within the commercial sector.
- Reach-In Refrigerators:These self-contained units feature hinged or sliding doors, providing accessible storage and maintaining temperatures typically between 0°C and 4°C for prepared foods. Demand concentration is notable in the food service industry, where they support daily operational efficiency for restaurants and cafes.
- Walk-In Coolers:Large, insulated rooms with refrigeration systems, walk-in coolers offer extensive storage capacity for bulk ingredients and pre-packaged goods, often operating at 0°C to 7°C. These units represent higher-value applications for food processing centers and large-scale retail operations requiring significant cold storage.
- Display Freezers:These units are designed with transparent doors or open tops to showcase frozen products, maintaining temperatures below -18°C.
- Undercounter Refrigerators:Compact, space-saving units installed beneath countertops, providing convenient cold storage in kitchens or bars.
- Blast Chillers:Specialized equipment rapidly reducing food temperatures from cooking to safe storage levels, crucial for food safety compliance.
Mature deployment sits with Reach-In Refrigerators. Newer deployment is concentrated in Blast Chillers.
Technology:
The technological landscape of commercial refrigeration is evolving, driven by efficiency mandates and refrigerant transitions. System design choices reflect a balance between performance, cost, and environmental impact.
- Compression:This dominant technology utilizes a vapor-compression cycle, where a refrigerant is compressed, condensed, expanded, and evaporated to transfer heat, maintaining precise temperature control. The widespread adoption of variable-speed compressors in Europe demonstrates a focus on energy efficiency for long-term operational savings.
- Absorption:These systems use a heat source to drive a refrigeration cycle, employing a refrigerant and an absorbent, often ammonia and water, with fewer moving parts than compression systems. Demand for absorption technology is emerging in niche applications where waste heat is readily available, such as industrial facilities seeking to reduce energy costs.
- Thermoelectric:Solid-state devices that use the Peltier effect to create a temperature difference, offering compact and vibration-free cooling for small-scale or specialized uses.
- Magnetic:An emerging technology that uses a magnetocaloric effect, where certain materials heat up when magnetized and cool down when demagnetized, offering potential for high efficiency.
- Cryogenic:Utilizes extremely low temperatures, often achieved with liquid nitrogen or helium, for specialized applications like ultra-low temperature storage in research.
Efficiency considerations drive investment in Compression systems, while Absorption addresses niche requirements.
Application:
Commercial refrigeration applications span a wide spectrum, each demanding specific temperature ranges, storage volumes, and regulatory compliance. The diversity in use cases influences equipment design and feature sets.
- Food Service:This broad segment includes restaurants, cafes, and institutional kitchens, relying on commercial refrigerators to store perishable ingredients and prepared meals safely. The expansion of organized retail in India creates sustained demand for food service refrigeration equipment.
- Pharmaceutical Storage:Requires precise temperature control and often validated systems to preserve sensitive biologics, vaccines, and medications within strict regulatory guidelines. The growing market for biologics creates a high-value application segment for specialized pharmacy-grade refrigerators.
- Beverage Cooling:Encompasses chillers and display units for soft drinks, alcoholic beverages, and juices in retail, hospitality, and vending environments.
- Laboratory Preservation:Involves specialized refrigerators and freezers for storing samples, reagents, and cultures, often with stringent temperature stability requirements.
- Floriculture:Utilizes controlled refrigeration to extend the shelf life of cut flowers and plants, maintaining freshness during transport and display.
The broadest market penetration occurs in Food Service, with Pharmaceutical Storage representing a high-growth segment.
End User:
The end-user landscape for commercial refrigerators reflects varied operational scales, storage needs, and purchasing power. Each end-user type has distinct requirements influencing equipment selection and service expectations.
- Restaurants:These establishments require a mix of reach-in refrigerators, undercounter units, and sometimes walk-in coolers to manage daily inventory of fresh and prepared ingredients. Restaurants prioritize reliability and space efficiency to support high-volume kitchen operations.
- Food Processing Centers:These large-scale facilities demand extensive cold storage, blast chillers, and specialized refrigeration systems for processing, packaging, and preserving food products before distribution. The modernization of food processing infrastructure in Southeast Asia presents a significant opportunity for walk-in coolers and blast chillers.
- Hotels:Utilize commercial refrigerators in kitchens, bars, and for guest room minibars, focusing on durability and aesthetic integration.
- Catering Companies:Rely on portable and robust refrigeration solutions to transport and store food safely at various event locations.
- Retailers:Include supermarkets, convenience stores, and hypermarkets, requiring display cases, walk-in coolers, and freezers for product merchandising and bulk storage.
Volume demand originates from Restaurants, whereas Food Processing Centers require highly customized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policies supporting the cold chain in India are driving significant demand for commercial refrigeration equipment, particularly in organized retail and food processing sectors. This focus on infrastructure development positions India as a central growth hub, influencing regional investment patterns. Other key countries also exhibit distinct demand drivers and regulatory landscapes.
India
Organized retail expansion and a growing food processing industry are primary demand drivers for commercial refrigeration in India. Government policies actively support cold chain development, encouraging investment in modern storage solutions. The Delhi-NCR region, with its dense population and growing food service sector, represents a significant concentration of new installations.
China
Energy efficiency gains and the modernization of retail infrastructure drive demand for commercial refrigeration in China. The country's stringent GB standards compel manufacturers to innovate product designs. The Yangtze River Delta region, a major industrial and commercial hub, sees high adoption of advanced refrigeration technologies.
United States
The extensive food service industry and the expanding pharmaceutical cold chain are key demand drivers in the United States. The US EPA's SNAP program and ENERGY STAR certifications influence product design and purchasing decisions. California, a leader in both food production and technological adoption, exhibits strong demand for energy-efficient units.
Germany
Adoption of natural refrigerants and corporate sustainability targets are major demand drivers for commercial refrigerators in Germany. The EU F-Gas Regulation actively compels the replacement of high-GWP refrigerants across various sectors. Bavaria, with its strong manufacturing base and focus on environmental technologies, is a hub for advanced cooling system development.
Brazil
Modernization of the food retail and hospitality sectors creates sustained demand for commercial refrigeration equipment in Brazil. Local energy efficiency standards encourage the procurement of more advanced units. The São Paulo metropolitan area, a major economic center, sees significant investment in both food service and large-scale retail refrigeration.
Commercial Refrigerator Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the commercial refrigerator market. The market exhibits a fragmented structure, with global integrators, component specialists, and regional fabricators representing distinct strategic archetypes. Competitive moves often involve strategic partnerships to develop new refrigerant technologies and vertical integration to secure component supply chains.
Specialists in specific components or end-user segments, such as Danfoss A/S, occupy a significant position by optimizing parts for new refrigerants. Hussmann Corporation exemplifies a focus on display cases and systems tailored for the grocery sector. Carrier Global Corporation represents a global integrator, leveraging its extensive distribution network to supply advanced systems to diverse retailers worldwide.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Johnson Controls |
| Hussmann Corporation |
| Danfoss A/S |
| Dover Corporation |
| Haier Inc. |
| AB Electrolux |
| Carrier Global Corporation |
| EPTA Corporate |
| Others |
Cost & Logistics Intelligence
Energy consumption, a significant operational cost component for commercial refrigerators, directly influences end-user purchasing decisions and subsequently impacts equipment pricing across all tiers. This cost pressure drives demand for more efficient units, reflecting in their market value.
Pricing Analysis
Premium pricing for short lead times often applies to specialized commercial refrigeration units, while standard models may see discounts for longer procurement cycles. The market primarily operates on a hybrid project-based and transactional pricing model. Price differentiation stems from energy efficiency certifications like ENERGY STAR and the level of integrated IoT services. Small restaurants exhibit the highest price sensitivity, whereas pharmaceutical storage applications prioritize reliability and compliance over initial cost.
Supply Chain Analysis
Logistics and freight costs significantly influence the final delivered price of commercial refrigeration equipment, especially for large, bulky units. Manufacturing of core components, such as compressors and specialized valves, concentrates in China and parts of Europe. The supply chain draws from a limited number of specialized manufacturers for advanced natural refrigerant components, creating a single-source vulnerability. Distribution runs through extensive global networks for integrated systems and specialized channels for niche components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial refrigerator market is undergoing a significant technology-transition phase, driven by the replacement of hydrofluorocarbon (HFC) refrigerants with natural alternatives like CO2 and propane. This shift necessitates fundamental system redesigns and new operational paradigms.
For Market Incumbents: Hedge against the regulatory shift phasing out HFCs by accelerating R&D into CO2 and propane-based refrigeration systems. Incumbents should strategically acquire smaller firms specializing in high-pressure componentry for natural refrigerants to secure supply and expertise. Invest in technician training programs to address the skill gap in handling flammable refrigerants, mitigating operational bottlenecks for end users. This proactive approach protects market share from emerging entrants focused on sustainable solutions.
For New Entrants and Emerging Players: A price-point gap exists between high-end, IoT-integrated systems and basic economy models, offering an entry point for value-added solutions. New entrants should target the modernization of food retail in Southeast Asia with energy-efficient display cases and walk-in coolers. Focus on offering bundled IoT-enabled services for remote monitoring and predictive maintenance, emphasizing long-term total cost of ownership savings. Specialized blast chillers for the pharmaceutical cold chain also represent a high-value, less saturated application.
For Investors and Strategic Acquirers: Increased adoption of natural refrigerant systems in new supermarket construction is the leading indicator that the market is firmly shifting towards sustainable technologies. Long-term viability for this market hinges on continued regulatory enforcement and the pursuit of energy efficiency gains. Investors should target component specialists optimized for CO2 and propane, or IoT platform providers offering integrated cold chain management solutions. Watch for government incentives for green technologies as a further accelerator for market transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Natural Refrigerants | Develop advanced CO2 and propane systems to meet EU F-Gas Regulation and US SNAP program mandates. |
| Acquisition of Component Specialist | Secure supply chains for high-pressure valves and compressors critical to new refrigerant technologies. |
| IoT Integration for Predictive Maintenance | Offer value-added service contracts and reduce total cost of ownership for end users. |
| Expansion into Emerging Markets | Capitalize on modernization of food retail and hospitality sectors in Southeast Asia and Latin America. |
| Technician Training Programs | Address the skill gap for safe installation and maintenance of flammable hydrocarbon refrigerants like R290. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis of the commercial refrigerator market. Primary insights stemmed from interviews with food service operators, procurement managers at food processing centers, and refrigeration technicians. This approach combined top-down market sizing with bottom-up validation, triangulating data from sources like EU F-Gas reports and ENERGY STAR certification databases.
Reconciliation of disparate data streams formed the basis of the forecast framework, projecting market evolution across the analysis window. The model integrated segmentation across product type, technology, application, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends, projected technology adoption, and future regulatory mandates. Key forecast inputs included food service sector expansion rates and refrigerant transition timelines.
Inputs from global trade statistics and corporate financial reports were available through the study window; gaps in specific component availability introduce uncertainty. Forecasts reflect assumptions concerning regulatory stability and economic growth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Autonomous One-Pot Cooking System Market