
 Global QSR Food Service Equipment Market | 2026-2036
Global QSR Food Service Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global QSR Food Service Equipment Market Intelligence
The modularization of kitchen equipment, enabling customized station configurations, is expanding buyer choice for global quick service chains. The Middleby Corporation leverages its diverse brand portfolio to provide complete, integrated kitchen packages for new franchise rollouts. Rational AG differentiates through its advanced combi-oven technology, a critical component in high-efficiency kitchen designs. ITW Food Equipment Group sustains a strong position through its specialized Hobart and Vulcan brands, particularly in warewashing.
QSR food service equipment encompasses commercial-grade appliances engineered for high-volume, rapid-turnaround food preparation, cooking, and storage. These systems are built for continuous duty cycles, often with stainless steel construction, and must meet stringent food safety standards. While cooking equipment and refrigeration units constitute the largest product segments, energy-efficient systems represent the fastest-growing technology category. Demand from large Quick Service Chains for standardized, network-connected appliances for remote monitoring continues to shape product development priorities.
Product compliance is governed by a matrix of standards, including NSF/ANSI for sanitation in the United States and CE marking for safety in Europe. Energy efficiency regulations, such as the EPA's Energy Star program and the EU's Ecodesign Directive, directly impact equipment specifications and total cost of ownership. Vendor selection will increasingly hinge on the ability to deliver equipment that optimizes both kitchen workflow efficiency and long-term energy consumption.
Market Dynamics
The central structural force shaping the market is the industrialization of food service, driven by global QSR chains demanding standardized, network-connected equipment. This push for operational uniformity and remote management capability dictates design priorities, favoring modular and energy-efficient systems.
Growth Catalysts
- Franchise Expansion in Emerging Economies:The rapid rollout of QSR franchises across urban centers in India and China necessitates large-scale procurement of standardized kitchen equipment, creating significant volume demand for cooking, holding, and refrigeration units.
- Energy Efficiency Mandates:Regulations like the US EPA's Energy Star program and the EU's Ecodesign Directive provide incentives and create replacement demand for equipment that lowers operational energy costs, a key metric for large chains.
- Modular Kitchen Designs:The adoption of modular equipment allows for customized, flexible station configurations. This trend enables QSRs to optimize workflow for specific menu items and adapt layouts for smaller real estate footprints, accelerating new store openings.
Market Restraints
- High Capital Investment:The significant upfront cost of advanced, automated, and energy-efficient food service equipment can be a substantial barrier for independent operators and smaller chains, slowing technology adoption outside of major franchises.
- Complex Regulatory Compliance:Manufacturers face a fragmented regulatory landscape, requiring adherence to different standards such as NSF/ANSI for sanitation in the United States and CE marking for safety in Europe, which increases design and testing costs.
- Stainless Steel Price Volatility:As the primary construction material for durability and sanitation, equipment pricing is highly sensitive to fluctuations in the cost of stainless steel, creating margin pressure for manufacturers and budget uncertainty for buyers.
Strategic Opportunities
- Equipment-as-a-Service Models:Developing subscription-based offerings that bundle equipment with ongoing maintenance, software updates, and remote monitoring can lower the initial capital barrier for operators and create recurring revenue streams for vendors.
- Plant-Based Menu Equipment:Designing specialized cooking and holding equipment optimized for the unique properties of plant-based meat and dairy alternatives addresses a fast-growing menu category within major QSR chains.
- Penetration of Secondary Cities:Targeting expansion in developing economies' secondary and tertiary cities, where organized food service is nascent, offers a significant long-term growth channel for standardized, durable equipment packages.
Industry Challenges
- Skilled Technician Shortage:A deficit of service technicians trained to diagnose and repair IoT-connected, software-driven kitchen appliances poses a risk to equipment uptime, a critical operational metric for high-volume QSRs.
- Data Interoperability:Achieving seamless communication and data sharing between equipment from different manufacturers within a single, integrated smart kitchen ecosystem remains a major technical and operational hurdle for QSR operators.
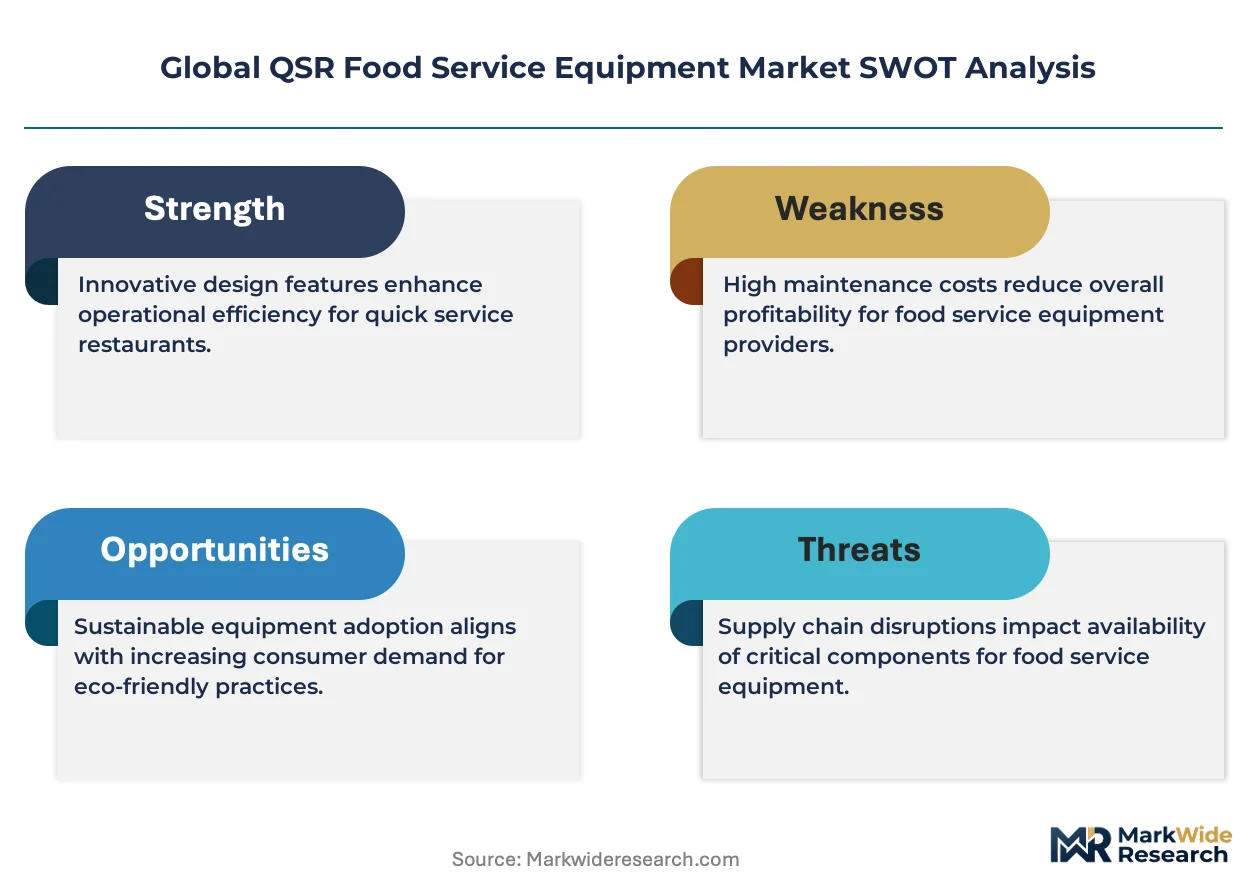
- Electronic Component Supply Chain:Production schedules are vulnerable to disruptions in the supply of essential electronic components, such as microcontrollers and sensors, which are critical for the functionality of modern, automated equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global QSR Food Service Equipment Market |
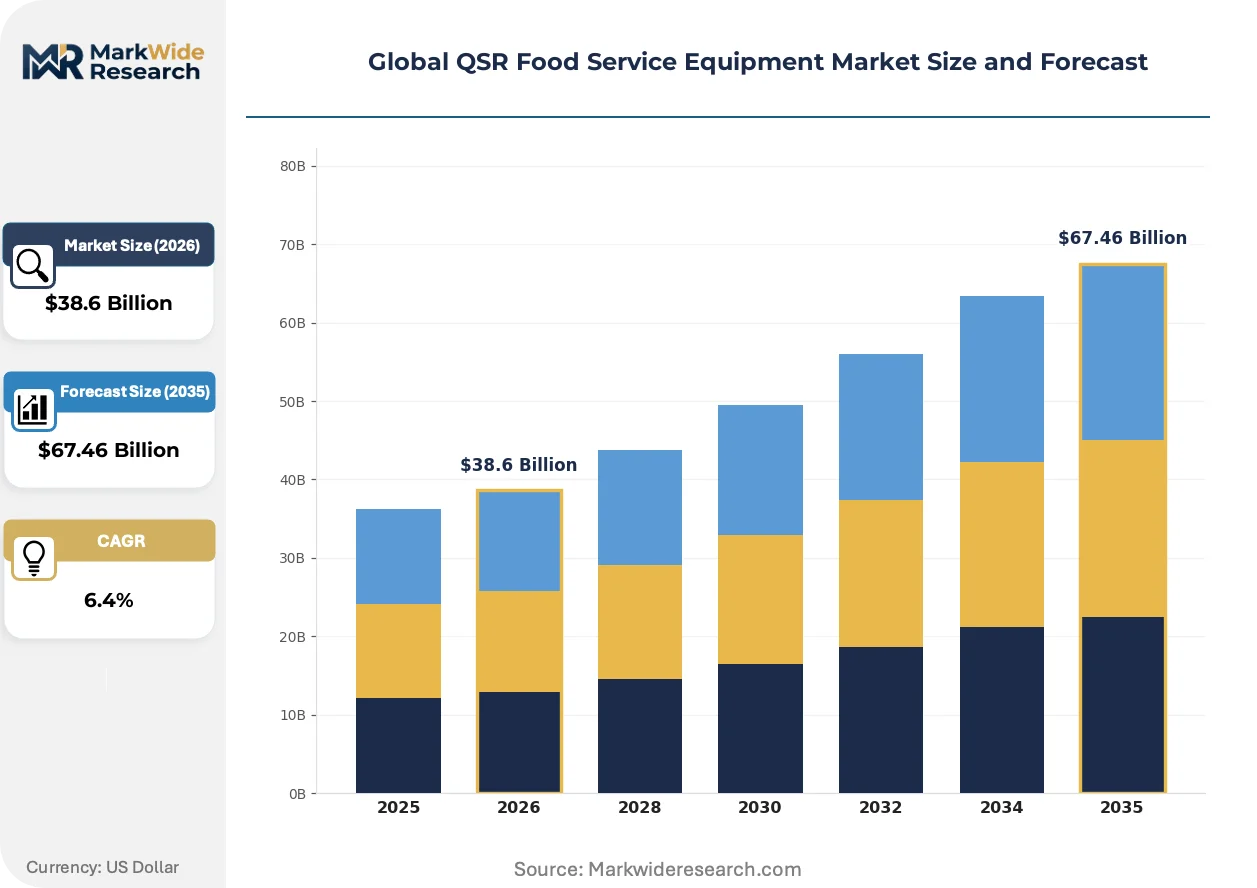
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooking Equipment, Refrigeration Units, Beverage Dispensers, Food Preparation Tools, Ventilation Systems Technology: Electric Heating, Gas-Powered, Induction Cooking, Automated Dispensing, Energy Efficient Systems Application: Drive-Thru Outlets, Counter Service, Mobile Kitchens, Delivery Preparation, Food Staging End User: Quick Service Chains, Catering Services, Food Trucks, Snack Bars, Concession Stands |
| Companies Covered | Hobart Corporation, Rational AG, Middleby Corporation, Hoshizaki America, Inc., Alto-Shaam, Inc., Ali Group, Welbilt, Taylor Commercial Foodservice, Inc., ITW Food Equipment Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global QSR Food Service Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from standalone mechanical appliances to integrated, data-driven kitchen platforms. This pivot emphasizes total ecosystem efficiency, where smart equipment optimizes energy usage, labor deployment, and food consistency across a distributed network of stores.
Advanced combi-ovens integrate steam, convection, and microwave functions into a single unit. Major QSR chains and institutional food service operators are adopting this technology to increase menu versatility and reduce kitchen footprint. This multi-function cooking platform is absorbing the roles of separate steamers, proofers, and convection ovens, consolidating kitchen workflows and simplifying equipment inventories.
The EU's F-Gas Regulation mandates a phase-down of hydrofluorocarbons (HFCs) used as refrigerants. This policy forces a significant technological shift in commercial refrigeration design toward natural refrigerants like propane (R290) and carbon dioxide (CO2). The refrigerated and frozen equipment segment is most impacted, with manufacturers redesigning entire product lines to ensure compliance for continued access to the European market.
Lifecycle management is displacing simple transactional equipment sales. QSR chains increasingly favor procurement models that bundle hardware with long-term service agreements, including predictive maintenance enabled by IoT sensors and remote diagnostics. This behavior is most visible among large franchise operators in the United States and Germany who prioritize standardized performance and maximum uptime across their extensive store networks.
Global QSR Food Service Equipment Market Segmentation
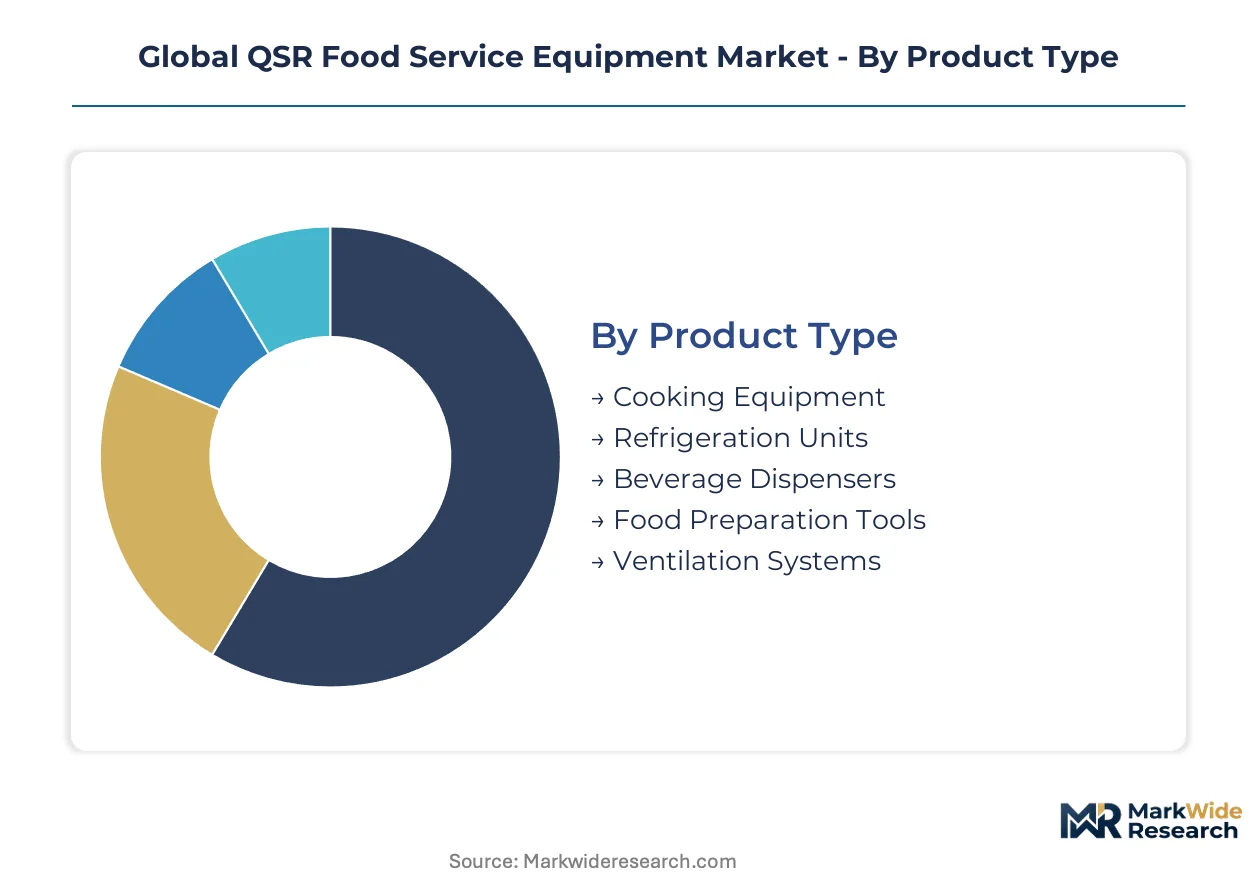
The global QSR food service equipment market segments based on the diverse operational requirements and strategic investments of quick service chains. Understanding these distinctions helps manufacturers align product development with specific end-user needs and capital expenditure patterns.
Product Type:
The capital intensity of kitchen outfitting often dictates initial procurement decisions for new QSR locations.
- Cooking Equipment:This segment includes fryers, griddles, ovens, and charbroilers, engineered for high-volume, continuous operation in QSR environments. Demand concentrates in emerging economies like India and China, where new franchise rollouts require complete kitchen installations.
- Refrigeration Units:Commercial refrigerators, freezers, and cold holding units maintain precise temperatures for food safety and ingredient preservation. Large QSR chains in the United States prioritize energy-efficient models to reduce long-term operational costs and comply with EPA Energy Star standards.
- Beverage Dispensers:These units dispense soft drinks, coffee, and other beverages, often with integrated ice makers. Quick service restaurants with high customer traffic volumes require robust, easy-to-maintain dispensing systems.
- Food Preparation Tools:This category encompasses mixers, slicers, choppers, and other tools used for ingredient processing. Automation in food preparation tools supports labor efficiency in busy kitchens.
- Ventilation Systems:Commercial hoods, exhaust fans, and air purification units manage smoke, grease, and odors from cooking operations. Health and safety regulations in Europe, such as those governed by national labor laws, drive specifications for these systems.
Cooking Equipment absorbs the bulk of installed capacity; Refrigeration Units are expanding most quickly.
Technology:
Technology advancements influence equipment performance and operational expenditure, with QSRs balancing upfront costs against long-term savings.
- Energy Efficient Systems:These technologies minimize power consumption through advanced insulation, smart controls, and optimized heating/cooling cycles. Global QSR chains in Germany and Japan increasingly adopt these systems to meet sustainability targets and reduce utility expenses.
- Induction Cooking:Induction cooktops use electromagnetic fields to heat cookware directly, offering precise temperature control and faster cooking times than traditional methods. Their integration into new restaurant designs in urban centers improves kitchen safety and reduces ambient heat.
- Electric Heating:Electric resistance elements provide consistent heat for various cooking and holding applications. This technology offers simpler installation in locations without natural gas infrastructure.
- Gas-Powered:Equipment using natural gas or propane provides powerful and responsive heating for many traditional cooking methods. Gas-powered units remain prevalent in markets with established gas line infrastructure.
- Automated Dispensing:These systems precisely measure and dispense ingredients or finished products, ensuring consistency and reducing labor for repetitive tasks. Automated beverage and condiment dispensers are common in high-volume QSR settings.
Energy Efficient Systems drive innovation in the QSR equipment sector; Induction Cooking is gaining share fastest.
Application:
The specific operational context of a QSR outlet shapes the type and configuration of equipment required.
- Drive-Thru Outlets:These applications demand highly specialized equipment for rapid order fulfillment, including dedicated fryers, holding cabinets, and beverage systems. The emphasis on speed and order accuracy drives equipment design for these high-volume channels in the United States.
- Delivery Preparation:Equipment for delivery-focused operations prioritizes efficiency in packaging, staging, and temperature maintenance for food items. This segment is growing rapidly in major metropolitan areas globally, influencing the design of holding and finishing stations.
- Counter Service:Traditional counter service operations utilize a broad range of equipment for front-of-house and back-of-house functions. These venues prioritize equipment that supports diverse menu offerings and efficient customer interaction.
- Mobile Kitchens:Food trucks and pop-up concepts require compact, durable, and often multi-functional equipment that can operate in confined spaces. Portability and power efficiency are critical considerations for mobile kitchen operators.
- Food Staging:This involves equipment for holding prepared food at optimal temperatures before serving or packaging. Staging equipment ensures food quality and expedites service during peak hours.
Drive-Thru Outlets command significant equipment investment; Delivery Preparation exhibits the steepest expansion trajectory.
End User:
Different types of food service operators have distinct purchasing power, operational scale, and equipment needs.
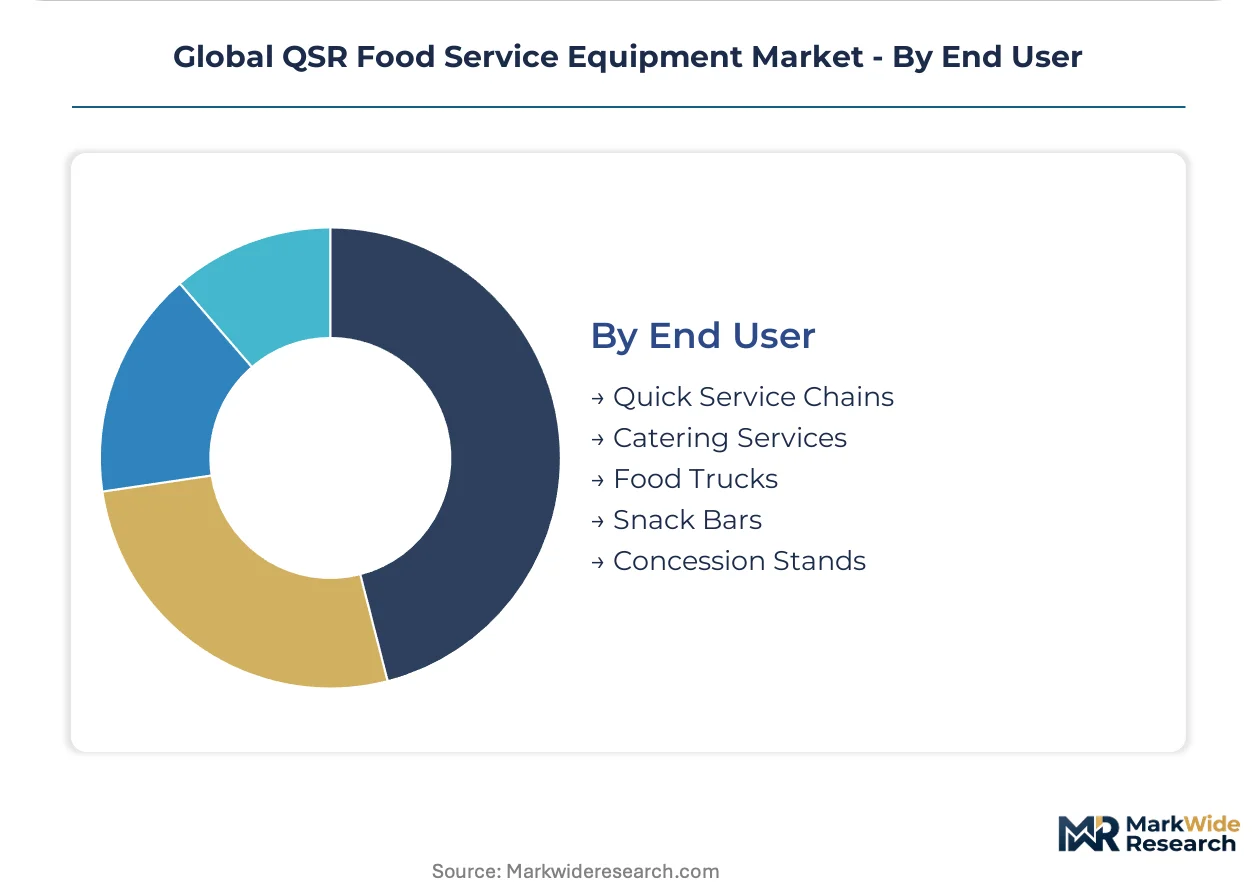
- Quick Service Chains:These large, multi-location operators demand standardized, durable, and often network-connected equipment for operational uniformity and remote management. Major QSR brands like McDonald's and Yum! Brands drive significant volume procurement globally.
- Food Trucks:Mobile food vendors require compact, robust, and often custom-fitted equipment to maximize limited space and ensure operational flexibility. The growth of independent food truck businesses in urban centers creates a niche demand for specialized appliances.
- Catering Services:Catering operations use portable and high-capacity equipment for off-site food preparation and serving. Versatility and ease of transport are key equipment attributes for these businesses.
- Snack Bars:These smaller venues typically require basic cooking, holding, and beverage dispensing equipment. Simplicity of operation and compact footprints are important for snack bar setups.
- Concession Stands:Often found in entertainment venues, concession stands utilize specialized equipment for high-volume, limited-menu items like popcorn, hot dogs, and soft drinks. Durability and speed of service are paramount in these environments.
Quick Service Chains represent the largest purchasing segment; Food Trucks are rapidly expanding their equipment footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global QSR food service equipment demand primarily originates from rapid franchise expansion, while manufacturing capabilities are distributed across established and emerging economies. This creates a dynamic where production centers often supply diverse consumption hubs. Energy efficiency mandates and operational standardization influence regional market characteristics.
United States
Large QSR chains in the United States prioritize energy-efficient refrigeration units to reduce long-term operational costs. The US EPA's Energy Star program influences equipment specifications for new installations. Drive-thru outlets in major metropolitan areas like Los Angeles command significant equipment investment. Standardized network-connected appliances are a priority.
China
China's rapid rollout of QSR franchises across urban centers necessitates large-scale procurement of standardized cooking and refrigeration units. Adherence to GB standards for food safety is mandatory for market entry. Cities such as Shanghai and Beijing are experiencing high volume demand for complete kitchen installations. Expansion into secondary cities drives equipment sales.
India
India's burgeoning QSR market, particularly in urban centers, fuels demand for complete kitchen installations and robust cooking equipment. FSSAI food safety regulations dictate specific material and design requirements for commercial appliances. Major cities like Mumbai and Delhi see significant volume demand from new franchise rollouts. This expansion prioritizes durable, continuous-operation equipment.
Germany
German QSR chains increasingly adopt energy-efficient systems to meet sustainability targets and reduce utility expenses. The EU's Ecodesign Directive directly impacts equipment specifications for commercial refrigeration. CE marking is essential for market access throughout the country. Industrial regions around Munich prioritize advanced, network-connected appliances.
Japan
Japanese QSR operators prioritize energy-efficient systems and compact equipment designs for smaller real estate footprints. METI's energy efficiency standards influence the development of advanced refrigeration technologies. Precise temperature control and automation are critical for maintaining food quality. Tokyo's high-density urban environment drives demand for space-saving units.
Global QSR Food Service Equipment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the global QSR food service equipment market. The market exhibits a tiered structure, with a few large players offering comprehensive solutions alongside numerous niche providers. Strategic archetypes include integrated solution providers, technology innovators, and regional specialists. Companies pursue geographic expansion, portfolio diversification, and strategic partnerships to enhance their market presence and optimize supply chain efficiencies.
Integrated solution providers, such as Middleby Corporation, leverage extensive brand portfolios to offer complete kitchen packages for global quick service chains. Rational AG exemplifies a technology innovator, specializing in advanced combi-oven technology critical for high-efficiency kitchen designs. ITW Food Equipment Group occupies a strong position as a specialist in warewashing and other heavy-duty equipment through its Hobart and Vulcan brands. These entities anchor different segments of the market, reflecting varied approaches to serving the QSR sector.
| Leading Market Players |
|---|
| Hobart Corporation |
| Rational AG |
| Middleby Corporation |
| Hoshizaki America, Inc. |
| Alto-Shaam, Inc. |
| Ali Group |
| Welbilt |
| Taylor Commercial Foodservice, Inc. |
| ITW Food Equipment Group |
Cost & Logistics Intelligence
Skilled technician concentrations in key manufacturing hubs influence equipment pricing, creating differentiation across advanced and standard product tiers. These labor-cost differentials directly impact the final cost of specialized QSR equipment packages.
Pricing Analysis
Cost-down pressure on standard and economy equipment tiers intensifies as independent operators seek lower upfront capital investments. The dominant pricing structure involves per-unit transactional sales for smaller purchases, transitioning to contract-based long-term agreements for large quick service chains. Price differentiation stems from factors like energy efficiency certifications (e.g., EPA Energy Star, EU Ecodesign Directive compliance) and bundled after-sales service contracts. Independent operators and smaller chains exhibit the highest price sensitivity, while large QSR chains prioritize total cost of ownership over initial purchase price.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by large QSR chains to mitigate supply risks. Geographic supply concentrates in China for general manufacturing, Germany for advanced refrigeration and combi-oven technology, and the United States for specialized heavy-duty equipment. The market's production heavily relies on stainless steel for construction and electronic components for smart functionalities. Electronic component supply chain disruptions pose a significant structural risk. Distribution runs through direct sales channels for major chains and extensive dealer networks for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global QSR food service equipment market is undergoing a technology-transition phase, with integrated, data-driven kitchen platforms displacing standalone mechanical appliances.
For Market Incumbents: Deploy portfolio diversification strategies to offer complete, integrated kitchen packages tailored for global quick service chains. Invest heavily in R&D for energy-efficient systems and IoT connectivity to counter the threat of evolving energy efficiency mandates. Bundling hardware with long-term service agreements strengthens customer retention against emerging tech-focused competitors.
For New Entrants and Emerging Players: Independent operators and food trucks represent an underserved buyer archetype seeking flexible, compact, and affordable solutions. Target the development of specialized plant-based menu equipment and modular designs for smaller real estate footprints. An effective go-to-market angle involves offering Equipment-as-a-Service models to lower the initial capital barrier for these operators.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized technology innovators given the market's shift towards integrated kitchen ecosystems. The long-term viability of the sector is anchored in the industrialization of food service and expansion into emerging economies. Acquisition targets should include companies with strong intellectual property in advanced combi-ovens or smart refrigeration. The successful scaling of Equipment-as-a-Service models serves as a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Emerging Economies | Increases equipment availability for new QSR franchise rollouts in high-growth markets like India and China. |
| Green Manufacturing Transition for Refrigerants | Ensures compliance with regulations like the EU's F-Gas Regulation, maintaining market access in Europe. |
| Product Launch of Plant-Based Menu Equipment | Addresses the fast-growing demand for specialized cooking solutions for alternative protein categories. |
| Strategic Partnership for IoT Software Integration | Enhances data interoperability and remote monitoring capabilities across diverse kitchen equipment. |
| Geographic Expansion into Secondary Cities | Captures nascent demand for organized food service equipment in previously untapped urban centers. |
Research Approach
Multi-period observation of QSR franchise expansion rates, equipment procurement trends, and regulatory compliance shifts anchored the trend analysis, supplemented by interviews. Primary research involved discussions with QSR procurement managers, equipment manufacturers' R&D leads, food service consultants, and supply chain logistics specialists. Secondary validation drew from industry association reports, government energy efficiency databases (EPA, EU Ecodesign), company financial disclosures, and trade publications, ensuring triangulation of bottom-up market sizing and top-down validation.
The analytical framework employed an input-output matrix to model market dynamics across the analysis window. Segmentation dimensions included product type, technology, application, end user, and regional regulatory environments. Compound annual growth rates were derived from historical growth rates, projected market drivers, and expert consensus over the projection horizon. Forecast inputs specifically incorporated new QSR store opening forecasts and energy efficiency investment trends.
Revisions become necessary when significant macroeconomic shifts or unforeseen regulatory changes materialize. Forecasts reflect assumptions regarding stable commodity prices and consistent technological evolution. Deviation in global economic stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Hospital Foodservice Equipment Market