
 Mobile Food Warmer Market | 2026-2036
Mobile Food Warmer Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Food Warmer Market Foresight
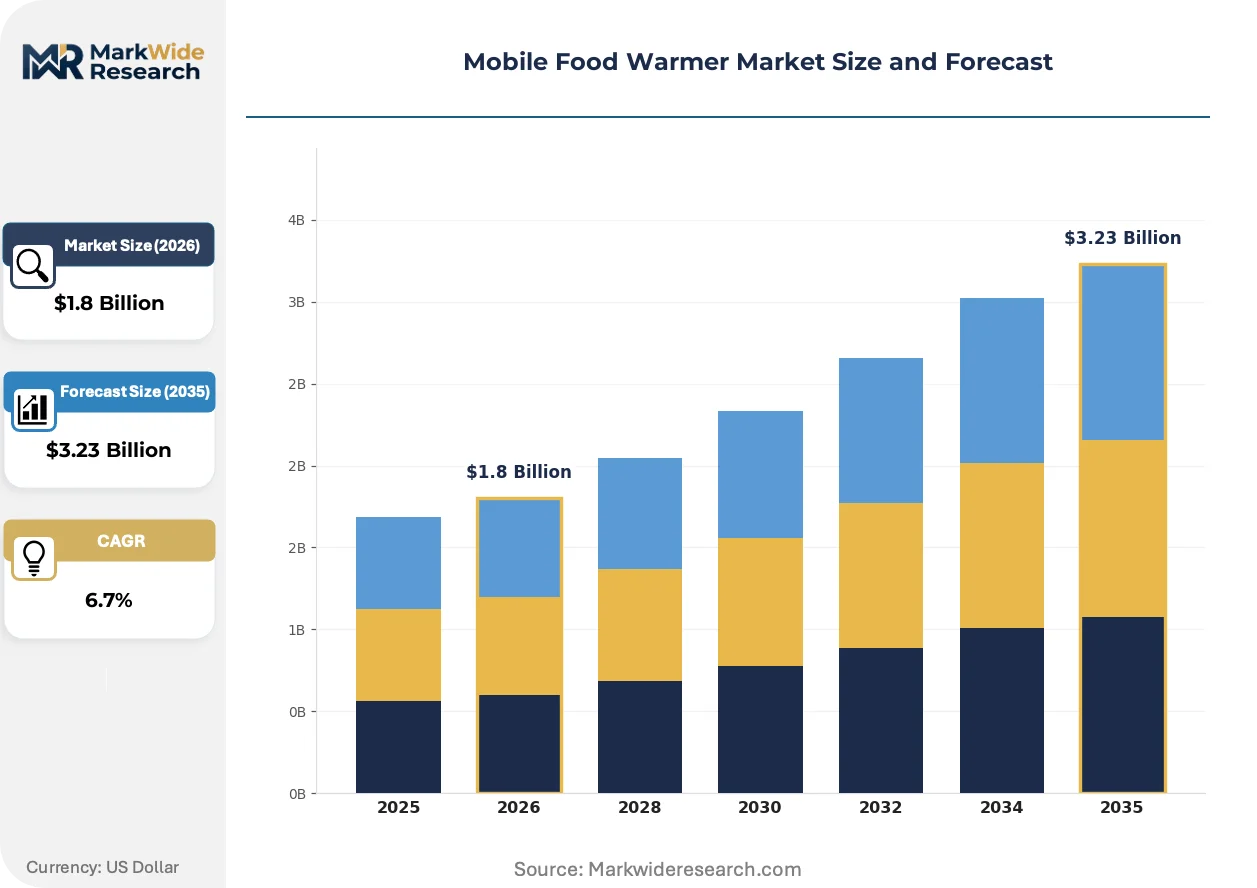
US FDA Food Code temperature-control mandates are broadening the cost-of-entry calculus for commercial kitchen operators seeking compliant mobile equipment. True Manufacturing leverages captive manufacturing of refrigeration and warming platforms to sustain pricing power across institutional channels. Alto-Shaam competes through precision humidity-management technology that extends hold times without quality degradation. Vollrath anchors its position via deep distribution into K-12 and healthcare segments where procurement specifications favor NSF-certified thermal solutions.
A mobile food warmer is an electrically or gas-powered insulated cabinet, drawer, or bag engineered to maintain prepared food within the HACCP-mandated 135°F to 165°F safe zone during transport or staging away from fixed kitchen infrastructure. Electric warmers incorporating convection airflow and digital thermostatic controls dominate commercial procurement due to energy efficiency and precise temperature management, while insulated carriers and food delivery bags represent the fastest-growing category as third-party delivery platforms expand hot-hold requirements. Induction warming technology leads margin pools in premium catering and banquet applications where rapid recovery and zone-specific heating justify higher equipment spend.
NSF International certification, UL safety standards, and US FDA Food Code provisions collectively shape product design, testing protocols, and market access for equipment sold into commercial foodservice. The US Department of Energy appliance efficiency regulations are tightening standby power allowances, forcing redesigns of electric warmer control systems and insulation packages. Stakeholders must monitor how state-level health department adoptions of FDA Food Code revisions accelerate replacement cycles for non-compliant legacy equipment already in field service.
Market Dynamics
US FDA Food Code temperature mandates are compressing replacement cycles for legacy hot-holding equipment as state health departments accelerate adoption of stricter HACCP enforcement protocols. This regulatory tightening is redrawing capital allocation priorities across commercial foodservice procurement.
Growth Catalysts
- Third-party delivery expansion:Platform operators are mandating carrier-grade thermal compliance for restaurant partners, pulling insulated bag demand upward across urban logistics networks.
- Outdoor event volume concentration:Texas, Florida, and California are issuing record food truck permits and temporary event licenses, forcing mobile fleet operators to scale compliant warming capacity.
- Induction warming maturation:Precision zone-control technology is penetrating premium catering segments where rapid thermal recovery justifies equipment upgrade spend.
Market Restraints
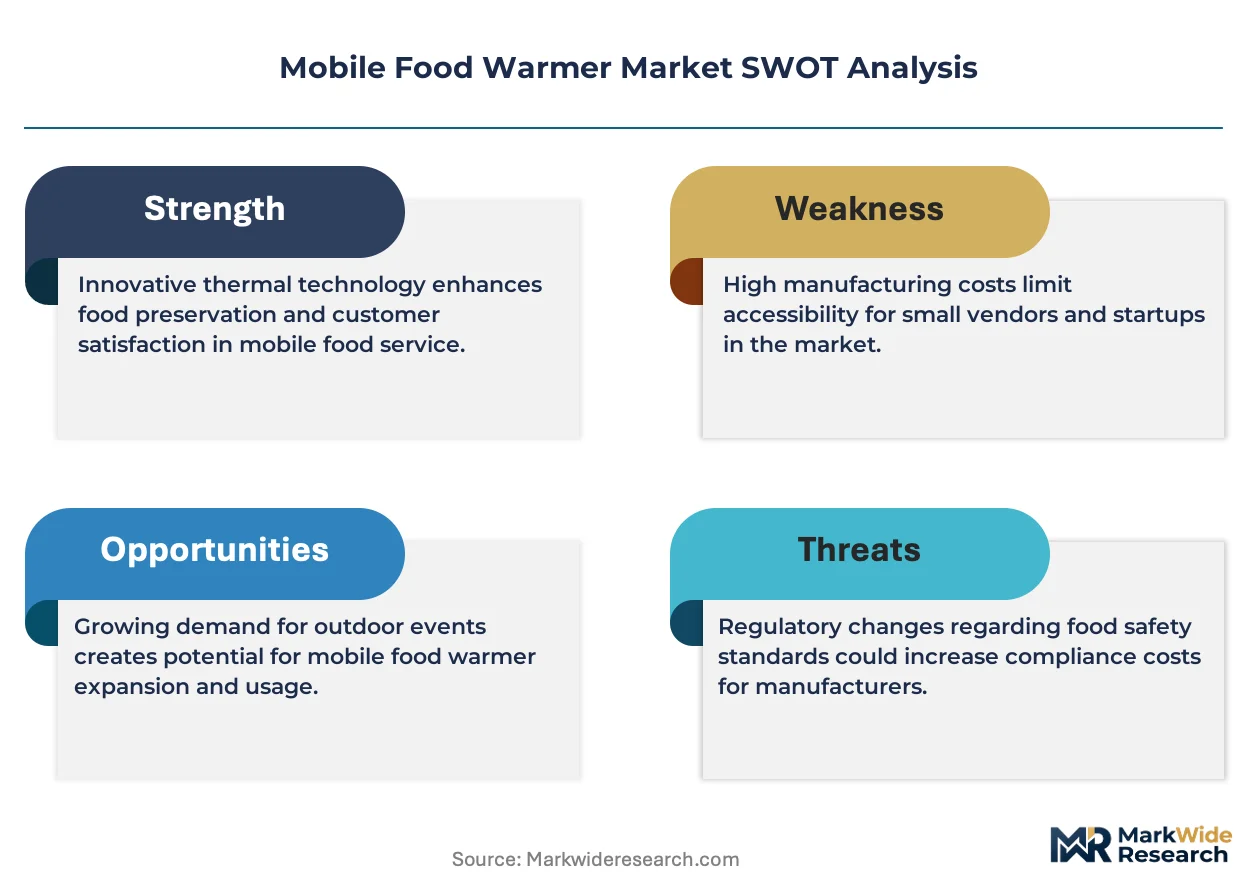
- Stainless steel input volatility:Commodity price swings for 304-grade sheet metal are compressing margin stability for cabinet and drawer manufacturers.
- Certification timeline friction:NSF International testing protocols and UL safety validations are extending new product introduction cycles by four to six months.
- Electric infrastructure dependency:Site power availability constraints at remote event locations are limiting deployment flexibility for plug-dependent warming platforms.
Strategic Opportunities
- Battery-powered thermal autonomy:Lithium-ion integrated warming cabinets are opening off-grid catering applications where generator noise restrictions apply.
- K-12 nutrition program modernization:USDA-backed school meal infrastructure grants are creating specification-driven replacement demand for NSF-certified transport solutions.
- Healthcare meal delivery unbundling:Hospital foodservice outsourcing is fragmenting procurement toward specialized thermal logistics providers with HACCP documentation capabilities.
Industry Challenges
- Control systems integration complexity:Digital thermostatic platforms must interface with legacy kitchen management software, stretching OEM engineering resources.
- Field service technician scarcity:Specialized refrigeration and warming equipment repair skills are concentrating among aging technician pools in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Food Warmer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Warmers, Gas Warmers, Insulated Carriers, Food Delivery Bags End User: Restaurants, Catering Services, Food Trucks, Events Capacity: Small Size, Medium Size, Large Size, Custom Size Technology: Infrared, Convection, Induction, Thermal |
| Companies Covered | True Manufacturing, VEVOR, Alto-Shaam, FWE, HeatMax Food Warmers, Hatco, Vollrath, Nemco, Cres Cor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Food Warmer Market Shifts & Advancements
Active thermal management architectures are displacing passive insulation as the dominant engineering priority. Equipment designers are prioritizing sensor-driven feedback loops and adaptive heating elements over static thermal mass.
Convection-assisted electric warming platforms are consolidating market share across mid-tier commercial procurement. Restaurant chains and institutional buyers are specifying these units for their energy efficiency and hold-time consistency. The technology is consolidating supplier margins by compressing demand for basic resistive-heating alternatives.
US Department of Energy standby power regulations are forcing control system redesigns across electric warmer portfolios. Manufacturers must reduce phantom load consumption while maintaining rapid thermal recovery performance. The compliance burden falls heaviest on budget-tier producers lacking captive electronics engineering.
Ghost kitchen operators are unbundling thermal equipment from full kitchen buildouts, renting mobile warming capacity by event or production cycle. This fractional-asset model is displacing capital purchase norms among emerging virtual brands. California and New York metro markets are exhibiting the fastest adoption of warming-as-a-service arrangements.
Mobile Food Warmer Market Segmentation
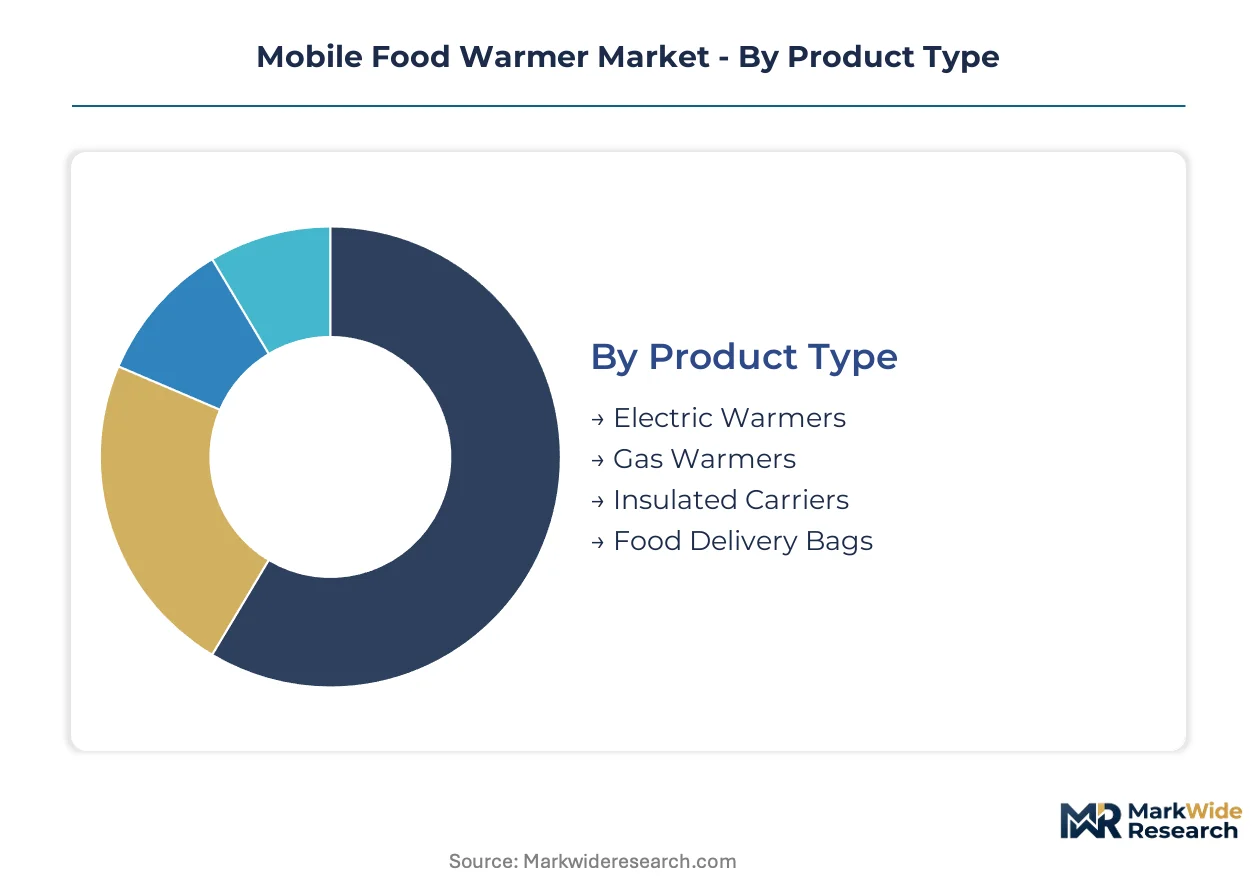
Mobile food warmer procurement decisions hinge on power availability at deployment sites, regulatory compliance tier, and thermal performance specifications. Equipment buyers across commercial foodservice weigh capital expenditure against operational flexibility, creating distinct preference clusters that reshape supplier positioning.
Product Type:
Capital constraints and site infrastructure availability dominate buyer calculus across warming equipment categories.
- Electric Warmers:Convection-assisted cabinets with digital thermostatic controls dominate institutional procurement. Restaurant chains and K-12 nutrition programs specify these units for energy efficiency and NSF certification alignment with HACCP mandates.
- Insulated Carriers:Passive thermal bags with phase-change inserts are expanding most quickly across third-party delivery networks. Platform operators in Texas, Florida, and California mandate carrier-grade thermal compliance for restaurant partner certification.
- Gas Warmers:Propane-powered cabinets serve off-grid catering applications where generator noise restrictions or electrical infrastructure gaps limit plug-dependent alternatives.
- Food Delivery Bags:Lightweight polyester carriers with reflective lining address last-mile logistics where volume throughput and driver mobility override hold-time duration requirements.
Volume sits with Electric Warmers; growth tilts toward Insulated Carriers.
End User:
Application environment determines specification stringency, with regulatory exposure and event scale driving equipment tier selection.
- Catering Services:Full-service operators deploy induction warming platforms for premium banquet applications. Rapid thermal recovery and zone-specific heating justify elevated equipment spend in corporate and wedding segments.
- Food Trucks:Mobile fleet operators in Texas, Florida, and California scale compliant warming capacity as temporary event license issuance accelerates. Space constraints favor compact electric drawer configurations.
- Restaurants:Ghost kitchen operators unbundle thermal equipment from full buildouts, renting mobile warming capacity by production cycle. Fractional-asset models displace capital purchase norms among virtual brands.
- Events:Stadium and festival concessionaires prioritize rapid throughput over hold-time precision, specifying high-capacity cabinets for peak-demand windows.
Procurement volume clusters with Catering Services; steepest expansion trajectory belongs to Food Trucks.
Capacity:
Production batch size and transportation logistics dictate dimensional requirements across buyer segments.
- Medium Size:Two-thirds sheet pan capacity balances mobility and throughput for independent caterers and mid-scale food trucks. This tier captures the broadest cross-segment demand.
- Large Size:Full-sheet and multi-pan configurations serve institutional feeding programs and stadium concessions. USDA-backed school meal infrastructure grants specification-driven replacement demand for NSF-certified transport solutions.
- Small Size:Single-pan and countertop units address healthcare meal delivery unbundling, where hospital foodservice outsourcing fragments procurement toward specialized thermal logistics providers.
- Custom Size:Built-to-specification cabinets serve premium catering operations with non-standard pan configurations or branded aesthetic requirements.
Medium Size holds installed base dominance; Large Size gains share fastest through institutional modernization programs.
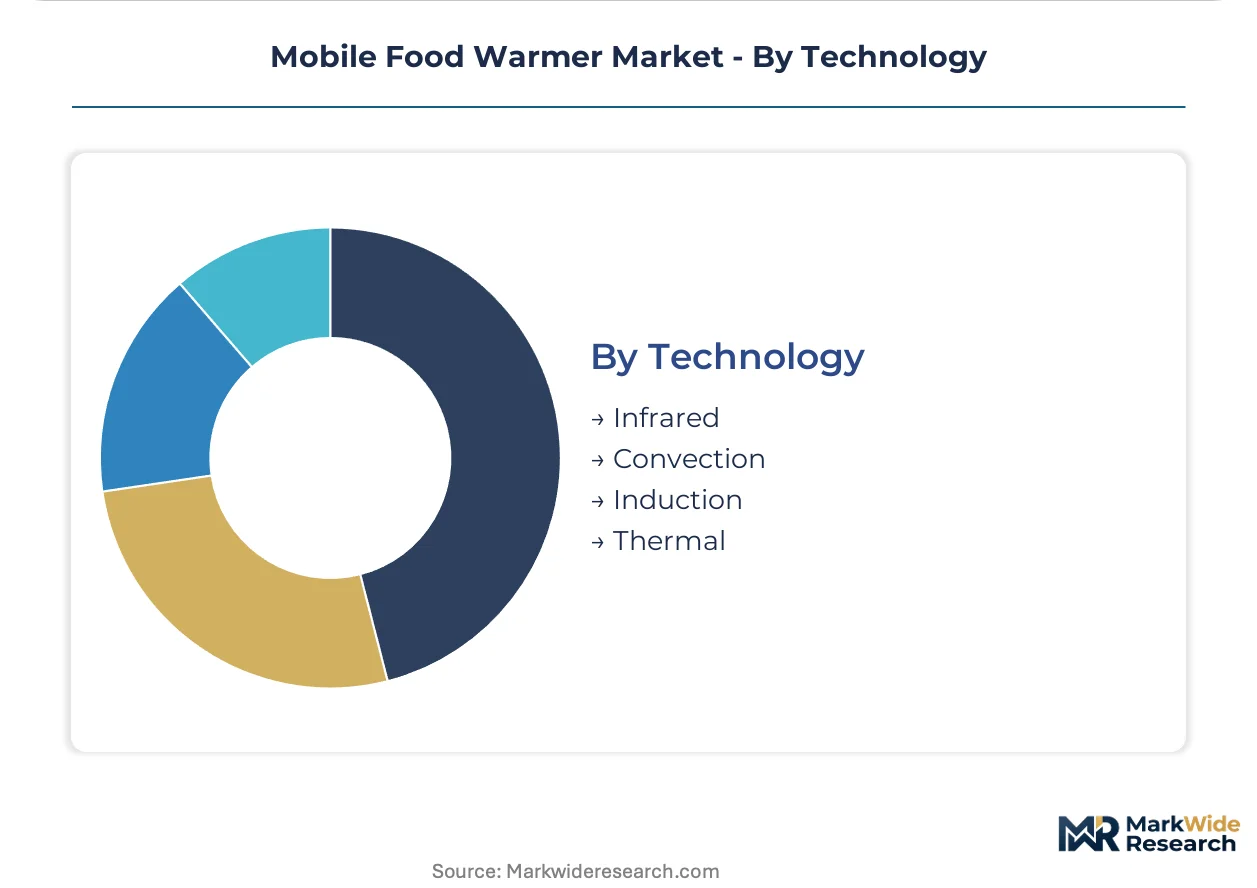
Technology:
Precision requirements and energy cost exposure separate premium technology adoption from baseline thermal performance acceptance.
- Convection:Fan-assisted airflow systems consolidate market share across mid-tier commercial procurement. Energy efficiency and hold-time consistency compress demand for basic resistive-heating alternatives.
- Induction:Electromagnetic heating with precision zone-control penetrates premium catering segments. Rapid thermal recovery justifies equipment upgrade spend where quality degradation risks escalate client attrition.
- Infrared:Radiant heat lamps serve front-of-house display applications where visual presentation and immediate serving temperature override extended hold requirements.
- Thermal:Passive mass-based systems with minimal active components address budget-constrained operations in secondary markets where technician scarcity elevates maintenance cost concerns.
Convection anchors current revenue; Induction climbs the fastest as precision catering expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Enterprise Zone Program incentives are concentrating mobile foodservice equipment manufacturing in the Dallas-Fort Worth corridor. State-level tax abatements for capital-intensive production facilities are reshaping supplier location decisions across North America.
United States
Third-party delivery platform mandates for carrier-grade thermal compliance are pulling insulated bag demand upward across urban logistics networks. FDA Food Code temperature-control updates are tightening equipment compliance standards for commercial kitchen operators. Texas, Florida, and California are issuing record food truck permits and temporary event licenses, forcing mobile fleet operators to scale compliant warming capacity.
Germany
Precision catering segments are driving specification-driven procurement for rapid thermal recovery equipment across corporate banquet operations. EU energy efficiency directives under the Ecodesign framework are forcing redesigns of electric warmer control systems and insulation packages. Bavaria's Munich-Stuttgart industrial corridor hosts specialized thermal equipment fabricators serving Central European institutional foodservice markets.
China
Mass-market manufacturing scale is compressing production costs for insulated carriers and passive thermal bags serving export markets. GB standards for commercial kitchen equipment safety are converging with international certification protocols to streamline market access. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces are consolidating supply for global foodservice equipment distributors.
United Kingdom
Ghost kitchen operators are unbundling thermal equipment from full kitchen buildouts, renting mobile warming capacity by production cycle. Food Standards Agency HACCP enforcement protocols are accelerating replacement cycles for non-compliant legacy equipment already in field service. London's dense urban logistics networks are exhibiting the fastest adoption of warming-as-a-service arrangements among virtual brands.
Japan
Compact urban foodservice formats are favoring space-constrained electric drawer configurations for mobile fleet operators. METI appliance efficiency regulations are tightening standby power allowances for commercial warming equipment. Osaka-Kobe industrial districts maintain specialized production capacity for precision thermal management components serving domestic and export markets.
Mobile Food Warmer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct price-performance tiers. The vendor base organizes around three strategic archetypes: captive manufacturers controlling upstream component supply, technology specialists differentiating through precision humidity and induction systems, and distribution-anchored players with deep institutional channel penetration. Competitive moves concentrate on NSF certification acceleration and battery-powered thermal autonomy development.
Within the captive manufacturing tier, True Manufacturing exemplifies backward integration into refrigeration and warming platforms. Among precision technology specialists, Alto-Shaam occupies a position representing humidity-management engineering capabilities. On the distribution-anchored vector, Vollrath sits within the institutional channel penetration archetype serving K-12 and healthcare procurement specifications.
| Leading Market Players |
|---|
| True Manufacturing |
| VEVOR |
| Alto-Shaam |
| FWE |
| HeatMax Food Warmers |
| Hatco |
| Vollrath |
| Nemco |
| Cres Cor |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists with multi-decade institutional channel relationships anchor supply-side discipline, translating captive manufacturing scale into pricing power against commodity-tier competitors while insulating premium NSF-certified tiers from stainless steel input volatility.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, while spot inventory liquidations clear excess capacity at discounted rates. Three-tier pricing structure across premium induction platforms, standard convection cabinets, and economy passive carriers separates buyers by certification grade and thermal performance requirements. Cost compression in budget electric warmers is intensifying because US Department of Energy standby power regulations force control system redesigns that commodity producers cannot absorb. K-12 nutrition programs exhibit highest price sensitivity due to USDA grant dependency, whereas premium catering services prioritize hold-time precision over capital expenditure.
Supply Chain Analysis
304-grade stainless steel sheet metal supply rests on Chinese, German, and South Korean mill capacity, with Yangtze River Delta fabricators consolidating passive thermal bag production for export markets. Lithium-ion battery cells, precision thermostatic sensors, and NSF-certified insulation composites constitute critical component dependencies. Single-source vulnerability concentrates in specialized induction coil winding and humidity-management sensor modules sourced from Osaka-Kobe industrial districts. Distribution runs through foodservice equipment dealers, GPO contracts, and direct OEM relationships with institutional chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Food Warmer Market operates as a cost-of-compliance arena where US FDA Food Code temperature mandates erect barrier-to-entry moats favoring NSF-certified incumbents with established state health department relationships.
For Market Incumbents: Deploy certification acceleration as the primary lever, compressing NSF International and UL validation timelines through pre-submission engineering consultation to outpace emerging competitors. Deepen backward integration into thermostatic control electronics and lithium-ion battery management systems to capture margin pools in battery-powered thermal autonomy segments. Counter ghost kitchen rental-model disruption by bundling warming-as-a-service offerings with HACCP documentation capabilities.
For New Entrants and Emerging Players: US FDA Food Code adoption waves across Texas, Florida, and California state health departments open a window for specification-compliant insulated carrier specialists to penetrate third-party delivery platform vendor lists. Target food truck fleet operators in Dallas-Fort Worth and Houston metro corridors where Enterprise Zone Program incentives concentrate mobile foodservice infrastructure buildouts. Pursue ghost kitchen operator partnerships with fractional-asset rental models that displace capital purchase norms among virtual brands.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision humidity-management technology specialists with captive induction engineering capabilities in Bavaria's Munich-Stuttgart corridor or Osaka-Kobe districts. Long-term viability hinges on battery-powered thermal autonomy patent portfolios and state-level health department specification capture. Watch FDA Food Code revision adoption velocity across secondary state markets as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Acceleration | Compresses validation timelines by four to six months against competitors lacking pre-submission engineering relationships. |
| Battery-Powered Thermal Autonomy Development | Opens off-grid catering applications where generator noise restrictions limit plug-dependent warming platform deployment. |
| Backward Integration into Control Electronics | Captures margin pools in digital thermostatic platforms while meeting US Department of Energy standby power regulations. |
| Ghost Kitchen Rental-Model Launch | Displaces capital purchase norms among virtual brands in California and New York metro markets. |
| State Health Department Specification Capture | Locks in replacement demand as FDA Food Code revisions accelerate non-compliant legacy equipment retirement. |
Research Methodology
SEC 10-K filings, foodservice equipment customs records, and state health department procurement databases formed the secondary backbone, cross-referenced with primary interviews involving commercial kitchen operators, NSF International certification engineers, K-12 nutrition program directors, and third-party delivery platform logistics managers. Bottom-up equipment shipment data triangulated against top-down institutional spending patterns to validate market sizing across the analysis window.
Historical trendline analysis of electric warmer, insulated carrier, and induction platform shipment volumes established baseline growth trajectories across product type, end user, capacity tier, and technology segmentation dimensions. CAGRs were derived through regression modeling of replacement cycle compression, regulatory adoption velocity, and third-party delivery network expansion inputs.
The model assumes a particular technology adoption path; alternative pathways for battery-powered thermal autonomy would alter the outlook if lithium-ion cost curves flatten or generator noise restrictions fail to propagate across municipal jurisdictions. Forecasts reflect assumptions regarding FDA Food Code revision adoption schedules, stainless steel commodity stability, and technician pool replenishment rates. A small set of named triggers—state-level HACCP enforcement intensity, food truck permit issuance velocity, and ghost kitchen platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Commercial Panini Grills Market