
 Industrial Dishwasher Market | 2026-2036
Industrial Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Dishwasher Market Foresight
Equipment leasing and pay-per-wash service contracts is fragmenting the competitive landscape for capital-intensive warewashing systems. ITW Hobart leverages its direct-service network to bundle chemicals, parts, and labor into multi-year agreements that lock out independent distributors. Meiko anchors its position through in-house production of heat-recovery modules and wastewater heat exchangers that reduce operating costs for large institutional buyers. Electrolux competes by offering modular rack-conveyor configurations that let mid-scale restaurants scale capacity without full replacement.
An industrial dishwasher is a commercial-grade warewashing machine engineered to sanitize foodservice equipment through high-temperature water jets, typically operating at rinse temperatures exceeding 82 degrees Celsius to achieve thermally validated pathogen elimination. These systems employ stainless-steel wash chambers, pumped detergent injection, and forced-air drying to process hundreds of racks per hour in continuous-use environments. Conveyor systems dominate installed base value due to their throughput economics in centralized kitchens and banquet operations, while energy-efficient technology variants are capturing replacement demand as operators face escalating utility tariffs. Door-type units sustain steady volume in independent restaurants where floor space constraints and lower peak loads limit conveyor feasibility.
The U.S. Department of Energy sets minimum efficiency standards that manufacturers must certify through standardized test procedures, directly influencing product development priorities and factory line allocations. In Europe, the Ecodesign Directive and CE marking requirements enforce water-consumption limits and noise thresholds that shape which models gain market access across EU member states. NSF International standards govern material safety and cleanability in North American foodservice installations, creating a compliance baseline that filters out lower-specification imports. Stakeholders must monitor how tightening carbon-border adjustments and embodied-carbon disclosure rules will reshape sourcing decisions for stainless-steel chassis and electronic control assemblies.
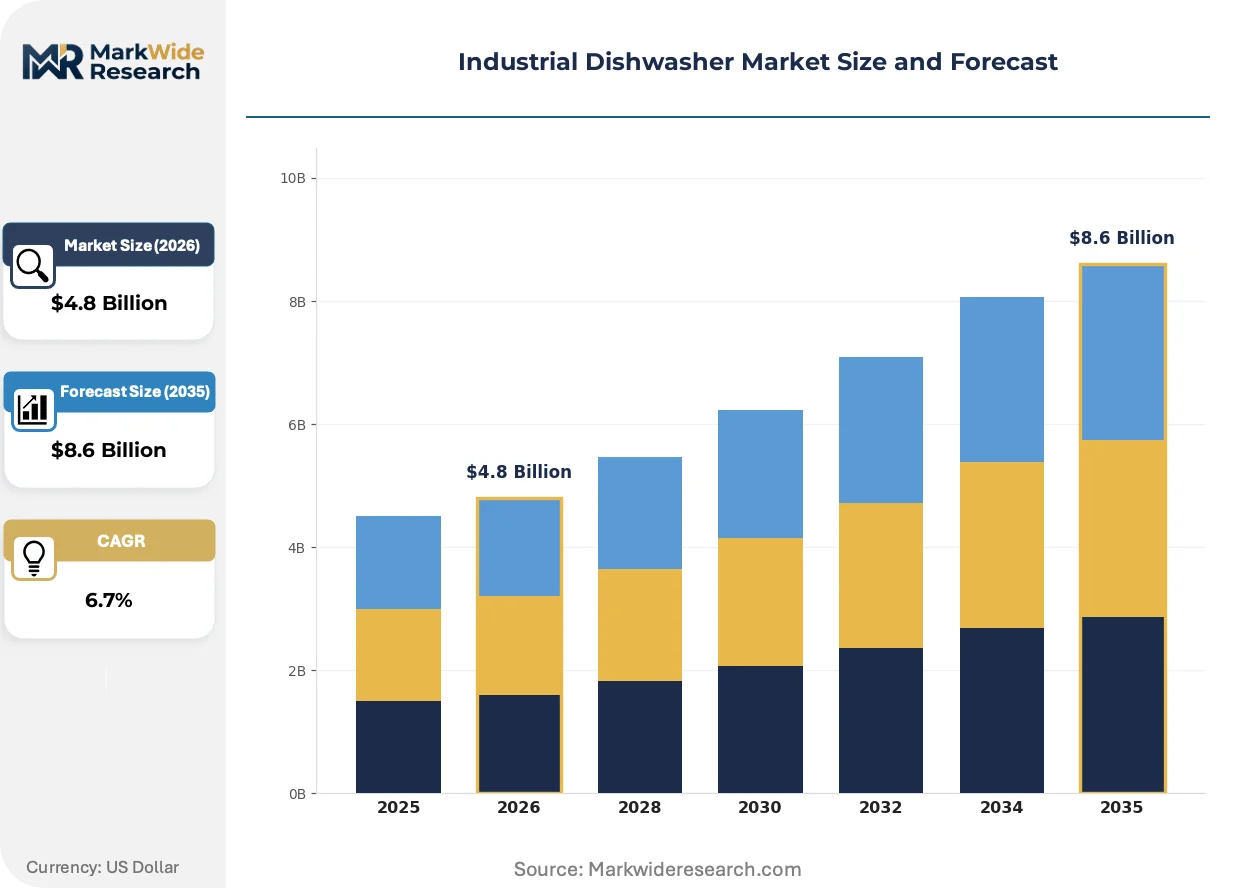
Market Dynamics
Equipment leasing and pay-per-wash service contracts are fragmenting competitive positioning for capital-intensive warewashing systems, forcing manufacturers to restructure from product sales to recurring revenue architectures.
Growth Catalysts
- DOE Efficiency Standards:The U.S. Department of Energy's tightening water and thermal energy thresholds are accelerating replacement cycles in institutional kitchens across North America.
- Healthcare Foodservice Expansion:Hospital cafeterias and healthcare operations are expanding procurement of automated warewashing systems to meet stringent hygiene protocols.
- German Hygiene Codes:Centralized kitchen infrastructure and stringent local regulations in Germany are driving concentrated replacement demand for certified equipment.
Market Restraints
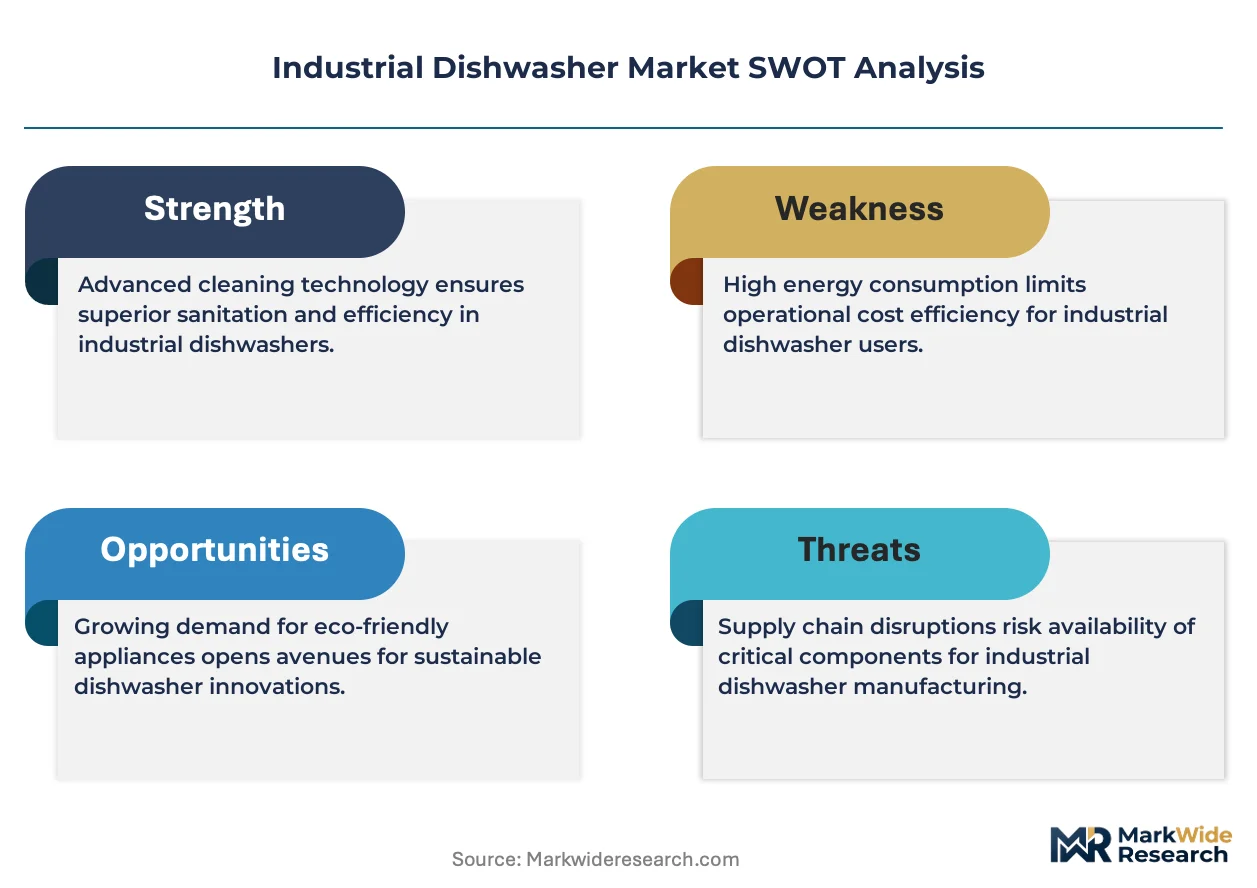
- Stainless Steel Input Volatility:Fluctuations in nickel and chromium prices compress margin predictability for chassis fabricators.
- Supply Concentration in Heat-Recovery Components:Captive production of heat exchangers by dominant European manufacturers limits sourcing flexibility for mid-tier assemblers.
- Technical Ceiling on Water Recovery:Current membrane and filtration technologies face throughput limits in high-solids institutional environments.
Strategic Opportunities
- Underpenetrated Central Kitchens in India:Food Safety and Standards Authority of India compliance mandates are opening institutional procurement channels previously served by manual washing.
- IoT-Enabled Predictive Maintenance:Convergence of sensor telemetry and cloud analytics is collapsing downtime costs for multi-site foodservice operators.
- EU Ecodesign Directive Expansion:Upcoming water-consumption limits and noise thresholds will create first-mover advantage for pre-certified product lines.
Industry Challenges
- Field Service Technician Scarcity:Specialized electromechanical repair skills for heat-recovery modules and control systems outpace vocational training pipelines.
- NSF Certification Timelines:Material safety and cleanability validation procedures create six-to-nine-month launch delays for new stainless-steel chamber designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Dishwasher Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swing-Type, Conveyor, Door-Type, Undercounter Technology: Steam, Automatic, Manual, Energy-Efficient End User: Restaurants, Hotels, Cafeterias, Hospitals Installation: Built-in, Portable, Integrated, Standalone |
| Companies Covered | Winterhalter, CMA Dishmachine, ITW Hobart, Washtech, Insinger Machine, Miele, Jackson, Electrolux, Meiko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Dishwasher Market Shifts & Advancements
Heat-recovery engineering and connected service architectures are actively compressing operating economics and ownership models across institutional foodservice operations.
Heat-recovery modules with wastewater heat exchangers are collapsing thermal energy consumption for large institutional buyers. Centralized kitchen operators in Germany and the Netherlands are retrofitting existing conveyor lines with these systems to preempt utility tariff escalations. The technology is collapsing the payback period justification for full equipment replacement.
The U.S. Department of Energy's appliance efficiency standards are mandating lower water consumption per rack across certified commercial dishwashing equipment. Manufacturers must redesign pump systems and spray arm geometries to maintain pathogen elimination performance at reduced flow rates. Door-type units serving independent restaurants face the steepest engineering adaptation costs.
Multi-year service contracts bundling chemicals, parts, and labor are displacing capital purchase decisions in healthcare and education verticals. Foodservice management companies operating hospital cafeterias are consolidating vendor relationships to reduce procurement administrative burden. This pattern is most visible in the United States and Germany where centralized procurement functions dominate institutional buying.
Industrial Dishwasher Market Segmentation
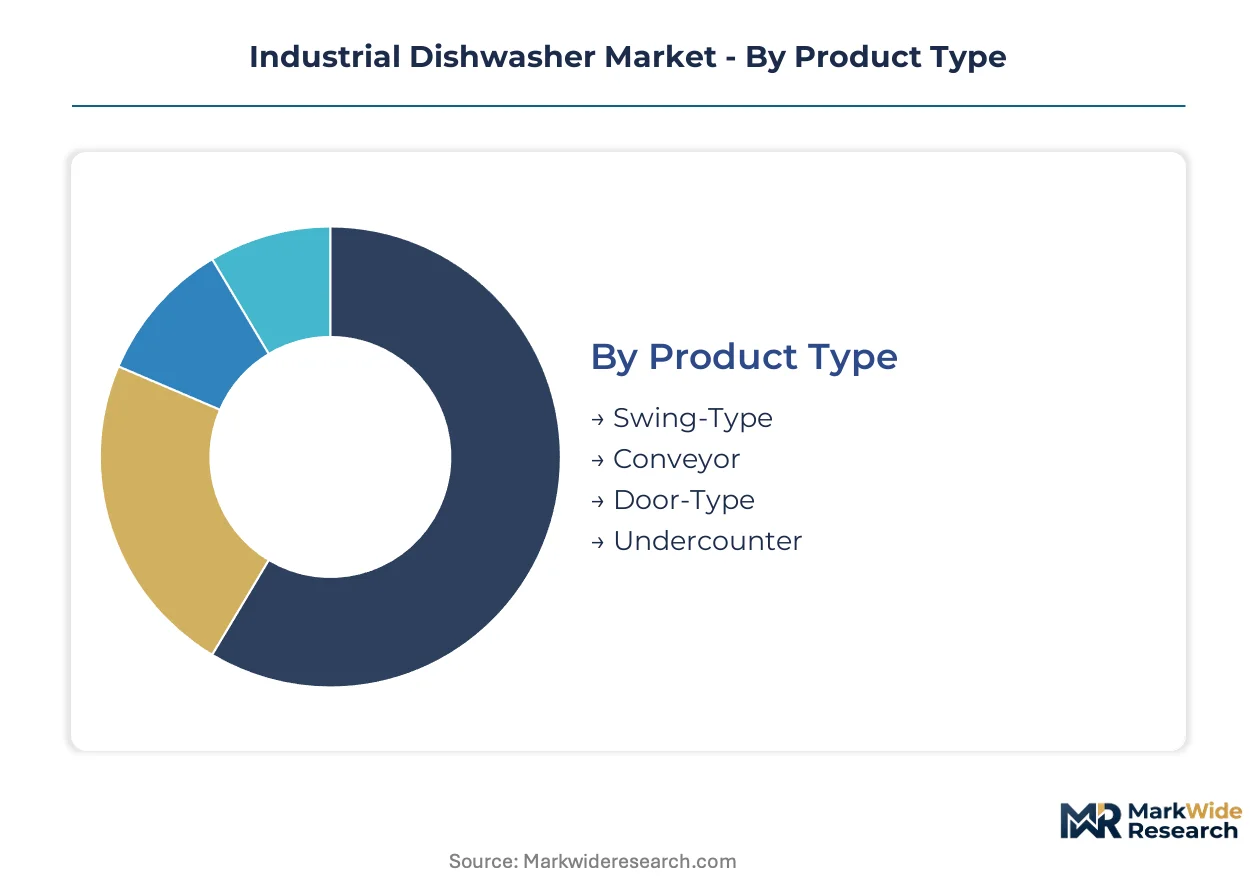
Segmentation in industrial dishwashing equipment determines service contract structures and replacement cycle timing. Product architecture dictates maintenance intensity, while installation mode shapes distributor relationships and chemical supply bundling.
Product Type:
After-sales-service intensity varies sharply across mechanical configurations, with conveyor systems demanding dedicated technician networks and swing-type units requiring minimal field intervention.
- Conveyor:Continuous-belt systems process hundreds of racks hourly through multi-stage wash zones with pumped detergent injection and forced-air drying. Hospital cafeterias and centralized kitchen operations in Germany specify these units for throughput economics, though heat-recovery module maintenance creates recurring service dependencies.
- Door-Type:Single-chamber units with vertical lifting doors accommodate lower peak loads in space-constrained environments. Independent restaurants across the United States favor this format where floor space limits conveyor feasibility, though DOE efficiency standards are forcing pump and spray arm redesigns.
- Swing-Type:Compact front-loading designs suit small commercial kitchens with intermittent washing needs.
- Undercounter:Low-profile units integrate beneath existing countertops for front-of-house or bar applications.
By volume, Conveyor leads. By growth pace, Door-Type is ahead.
Technology:
Capital deployment patterns diverge across technology tiers, with energy-efficient variants commanding premium pricing and automatic systems enabling chemical bundling strategies.
- Energy-Efficient:Heat-recovery modules with wastewater heat exchangers reduce thermal energy consumption. Large institutional buyers in the Netherlands retrofit existing lines to preempt utility tariff escalations, collapsing payback periods for full replacement decisions.
- Automatic:Sensor-driven detergent injection and programmable cycle controls minimize labor supervision. Healthcare foodservice operators specify these systems to meet stringent hygiene protocols with reduced staffing.
- Steam:High-temperature vapor sanitization achieves pathogen elimination without chemical residuals.
- Manual:Operator-dependent wash cycles persist in underpenetrated markets with limited capital availability.
By installed base value, Automatic dominates. By expansion trajectory, Energy-Efficient is climbing the fastest.
End User:
Procurement authority concentration shapes vendor access, with hospital systems and hotel chains centralizing decisions while independent restaurants fragment purchasing.
- Hospitals:Healthcare foodservice operations face stringent hygiene codes and audit requirements. German hospital cafeterias are expanding automated warewashing procurement to satisfy centralized kitchen infrastructure mandates and replacement cycle regulations.
- Hotels:Banquet and room service operations demand scalable capacity for variable event loads. Multi-year service contracts bundling chemicals, parts, and labor are displacing capital purchases in this vertical.
- Restaurants:Independent operators prioritize floor space efficiency and lower capital outlays.
- Cafeterias:Institutional feeding operations in education and corporate settings balance throughput against utility costs.
By contract value, Hospitals lead. By volume growth, Cafeterias are gaining share fastest.
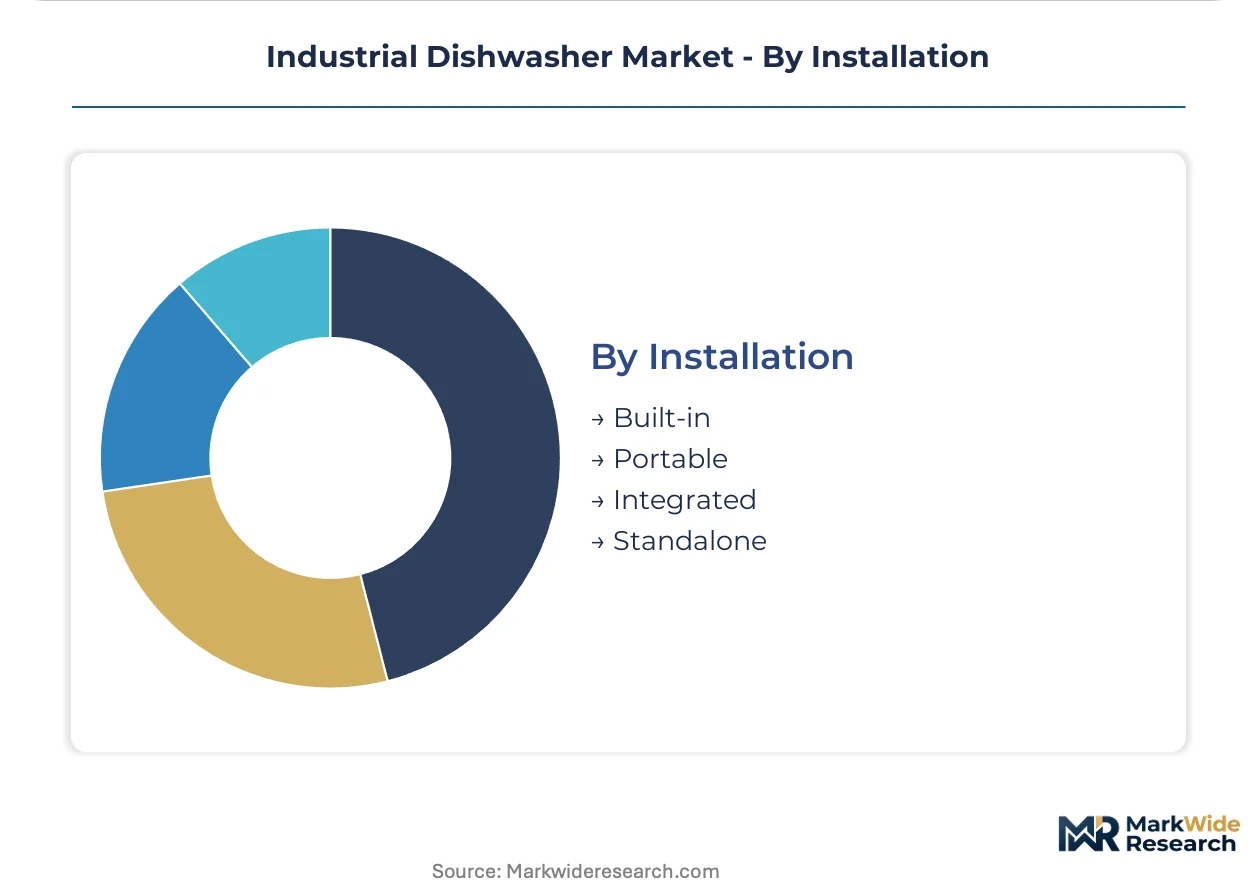
Installation:
Supply chain configuration determines margin capture, with built-in and integrated formats capturing chassis fabrication value while portable units fragment through distributor networks.
- Built-in:Fixed installations with custom stainless-steel enclosures anchor centralized kitchen designs. These configurations require NSF certification timelines that create six-to-nine-month launch delays for new chamber designs.
- Integrated:Systems engineered into complete kitchen workflows with pre-plumbed utility connections. Foodservice management companies specify these packages to reduce procurement administrative burden across multi-site operations.
- Portable:Self-contained units with casters and temporary utility hookups serve temporary or seasonal operations.
- Standalone:Freestanding equipment with minimal site preparation requirements suits retrofit installations.
By project value, Built-in leads. By shipment velocity, Standalone is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany posts the strongest trade surplus in industrial dishwashing equipment, exporting heat-recovery systems throughout the EU while importing minimal finished goods. The United States runs a structural deficit, sourcing stainless-steel chassis from European fabricators and Asian electronics assemblies. China's export volumes concentrate in door-type units for emerging markets.
United States
Hospital cafeterias and healthcare foodservice operations are expanding procurement of automated warewashing systems to meet stringent hygiene protocols. The U.S. Department of Energy's tightening water and thermal energy thresholds are accelerating replacement cycles in institutional kitchens across the country. Foodservice management companies in Chicago and New York Metro are consolidating vendor relationships to reduce procurement administrative burden.
Germany
Centralized kitchen infrastructure and stringent local hygiene codes are driving concentrated replacement demand for certified equipment. The Ecodesign Directive and CE marking requirements enforce water-consumption limits and noise thresholds that shape which models gain market access across EU member states. Manufacturers in Baden-Württemberg and Bavaria anchor in-house production of heat-recovery modules and wastewater heat exchangers.
Netherlands
Large institutional buyers are retrofitting existing conveyor lines with heat-recovery systems to preempt utility tariff escalations. The EU Ecodesign Directive's upcoming water-consumption limits create first-mover advantage for pre-certified product lines in Dutch centralized kitchens. Rotterdam and Amsterdam foodservice operators are collapsing payback periods for full replacement decisions through energy-efficient retrofits.
India
Food Safety and Standards Authority of India compliance mandates are opening institutional procurement channels previously served by manual washing. The country's national food safety regulator is tightening hygiene codes for hospital and education sector foodservice operations. Maharashtra and Karnataka are seeing accelerated adoption as centralized kitchen infrastructure expands in Mumbai and Bangalore.
Japan
Sensor-driven detergent injection and programmable cycle controls are minimizing labor supervision in healthcare foodservice operations. METI efficiency standards and JIS certification requirements shape product development priorities for domestic and imported equipment. Tokyo and Osaka metropolitan areas concentrate demand for compact, high-throughput systems in space-constrained institutional environments.
Industrial Dishwasher Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in heat-exchanger and control module fabrication. The vendor base stratifies across three tiers: multinational kitchen equipment conglomerates with direct-service networks, mid-scale regional fabricators with captive chemical bundling, and specialized heat-recovery engineering houses. Consolidation pressure is accelerating as leasing models and pay-per-wash contracts favor scale. Dominant competitive moves include backward integration into stainless-steel chassis production and multi-year service contract anchoring.
Among German-based manufacturers, Winterhalter and Meiko occupy positions anchored by in-house heat-recovery engineering and direct-service infrastructure. ITW Hobart represents the multinational platform integrator archetype with bundled chemical, parts, and labor agreements. These three companies exemplify the shift from capital sales toward recurring revenue architectures in institutional foodservice verticals.
| Leading Market Players |
|---|
| Winterhalter |
| CMA Dishmachine |
| ITW Hobart |
| Washtech |
| Insinger Machine |
| Miele |
| Jackson |
| Electrolux |
| Meiko |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's captive heat-recovery module production shapes downstream pricing power for European manufacturers serving institutional buyers. Stainless-steel chassis fabrication costs and NSF certification timelines feed directly into contract structures across North American procurement channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term service agreements that bundle chemicals, parts, and labor into recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates heat-recovery equipped conveyors from basic door-type units and manual swing-type configurations. Cost compression in mid-tier automatic systems is intensifying because DOE efficiency standards force pump and spray arm redesigns. Independent restaurants exhibit highest price sensitivity due to capital constraints, while hospital systems prioritize hygiene certification over upfront outlay.
Supply Chain Analysis
EU dual-use export controls on advanced heat-exchanger technology limit cross-border flows of energy-efficient components to Asian assemblers. Manufacturing gravity centers on Germany, Italy, and China, with stainless-steel sheet drawing from Finnish and Swedish mills and electronic control assemblies sourcing from South Korean and Taiwanese fabricators. Single-source vulnerability concentrates in heat-recovery module production held by Meiko and Winterhalter captive operations. Distribution runs through direct-service networks for institutional accounts and independent distributor channels for portable and standalone units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption as IoT-enabled predictive maintenance architectures collapse downtime economics for multi-site foodservice operators. Regulatory tightening on water consumption and thermal efficiency across DOE and EU Ecodesign frameworks accelerates replacement cycles beyond historical patterns.
For Market Incumbents: Build switching-cost moats through multi-year chemical and parts bundling that locks out independent service providers. Deepen backward integration into stainless-steel chassis production to preempt nickel price volatility margin compression. Expand direct-service technician networks in Germany and the Netherlands where heat-recovery retrofit demand concentrates.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's underpenetrated hospital and education sector centralized kitchens where FSSAI compliance mandates displace manual washing. Target modular rack-conveyor configurations that let mid-scale restaurants scale capacity without full replacement. Lead with pay-per-wash service contracts to bypass capital purchase friction in credit-constrained markets.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because service contract bundling displaces transactional equipment sales across healthcare and education verticals. Acquisition targets should display captive heat-recovery engineering capabilities and established direct-service footprints. Watch for DOE efficiency standard acceleration or EU carbon-border adjustment implementation as signals of replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Recovery Module Production | Captive supply of wastewater heat exchangers locks in margin capture for institutional conveyor lines. |
| Multi-Year Service Contract Anchoring | Bundled chemical, parts, and labor agreements displace capital purchases in hospital cafeterias and hotel chains. |
| IoT-Enabled Predictive Maintenance Platform | Sensor telemetry convergence collapses downtime costs for foodservice management companies operating multi-site networks. |
| Geographic Expansion into Indian Central Kitchens | FSSAI compliance mandates open institutional procurement channels previously served by manual washing operations. |
| Energy-Efficient Product Line Pre-Certification | Early EU Ecodesign Directive compliance creates first-mover advantage as water-consumption limits tighten. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with maintenance directors at hospital systems, plant engineers at centralized kitchen operators, OEM procurement teams at foodservice management companies, and aftermarket service heads at distributor networks; alongside secondary validation through DOE appliance efficiency filings, NSF certification databases, EU Ecodesign Directive implementation reports, and customs trade data on stainless-steel equipment imports. Bottom-up installation tracking across product types and end-use verticals was triangulated against top-down market sizing from regulatory disclosure patterns.
Forecast inputs span product type segmentation across conveyor, door-type, swing-type, and undercounter configurations; technology tiers including energy-efficient, automatic, steam, and manual systems; end-use verticals spanning hospitals, hotels, restaurants, and cafeterias; and installation modes from built-in to portable formats. CAGRs were derived from replacement cycle modeling against regulatory compliance deadlines and utility tariff escalation trajectories. Heat-recovery retrofit economics and IoT service contract penetration curves shaped the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian cost-focused assemblers or European heat-recovery engineering houses would shift outcomes. Material shifts in nickel and chromium input costs, DOE efficiency standard acceleration timelines, or EU carbon-border adjustment scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Countertop Ice Dispensers Market