
 Warewashing Equipment Market | 2026-2036
Warewashing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Warewashing Equipment Market Analysis
European stainless steel fabrication capacity is broadening as warewashing OEMs expand output to serve rebounding hospitality capital expenditure. Meiko Maschinenbau anchors its position through captive pump and conveyor manufacturing in Offenburg, while Electrolux Professional leverages its Italian burner technology center to differentiate on energy recovery systems. Hobart sustains North American channel control through its exclusive distributor network spanning institutional foodservice accounts.
Warewashing equipment comprises automated and semi-automated machines that clean dishware, glassware, and cooking utensils using heated water, alkaline detergents, and rinse aids, with cycle temperatures typically ranging from 150°F to 180°F for sanitization compliance. The primary commercial purpose is eliminating manual scrubbing labor while ensuring health code-compliant thermal or chemical disinfection in high-volume foodservice environments. Dishwashers occupy the dominant revenue position within product type segments, though high-efficiency technology variants are capturing disproportionate margin pools as utility rebate programs expand. Energy Star rated equipment leads technology segment growth as operators face escalating water and natural gas tariffs across deregulated utility markets.
The U.S. Department of Energy sets minimum efficiency standards under 10 CFR 431 for commercial dishwashers, while the EU Ecodesign Directive mandates progressive water and energy consumption limits through delegated regulations. NSF International certification requirements in North America and CE marking under the EU Machinery Directive create dual compliance pathways that shape product development roadmaps and market access timelines. Stakeholders must monitor evolving state-level building electrification mandates that could displace natural gas booster heaters in major metropolitan equipment specifications.
Market Dynamics
Full-service restaurant chains are accelerating automated warewashing deployment to offset persistent kitchen labor shortages, while dual regulatory pressure from DOE appliance standards and EU Ecodesign mandates compress replacement cycles toward high-efficiency equipment platforms.
Growth Catalysts
- DOE 10 CFR 431 Efficiency Mandates:U.S. federal minimums for commercial dishwasher energy and water consumption are forcing institutional foodservice accounts into equipment refresh cycles ahead of natural depreciation schedules.
- Natural Gas Tariff Escalation:Deregulated utility markets in Texas, California, and New York are amplifying payback calculations for heat-recovery and electric booster configurations.
- German Stainless Steel Fabrication:OEM captive capacity expansion in Baden-Württemberg is shortening lead times for conveyor and pump subassemblies serving rebounding European hospitality capex.
Market Restraints
- Electrical Infrastructure Retrofit Costs:Building electrification mandates in New York City and Seattle require panel upgrades and three-phase service extensions that add 15-25% to installed equipment economics.
- NSF/ANSI 3 Certification Timelines:North American market access requires 6-9 month validation cycles for novel heat exchanger geometries, delaying product launches versus CE-marked equivalents.
- Alkaline Detergent Price Volatility:Caustic soda and chlorine compound input costs fluctuate with chlor-alkali plant operating rates, compressing operator chemical budget predictability.
Strategic Opportunities
- India FSSAI Commercial Kitchen Standards:Emerging hospitality infrastructure in Mumbai and Bangalore lacks automated warewashing penetration, creating first-mover positioning for NSF-compliant equipment platforms.
- Heat Pump Drying Convergence:Integration of refrigeration cycle dehumidification with conventional rinse systems enables natural gas elimination and utility rebate stacking.
- Cloud-Connected Predictive Maintenance:IoT-enabled wash cycle analytics allow OEMs to unbundle service contracts from equipment sales, capturing recurring revenue from multi-unit restaurant operators.
Industry Challenges
- Booster Heater Electrification Skill Gap:Commercial kitchen technician training lags behind heat pump and induction booster deployment, extending commissioning timelines and warranty claim rates.
- Legacy Rack Dimension Fragmentation:Non-standard dish rack specifications across institutional, casual dining, and healthcare segments prevent modular equipment standardization, inflating SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warewashing Equipment Market |
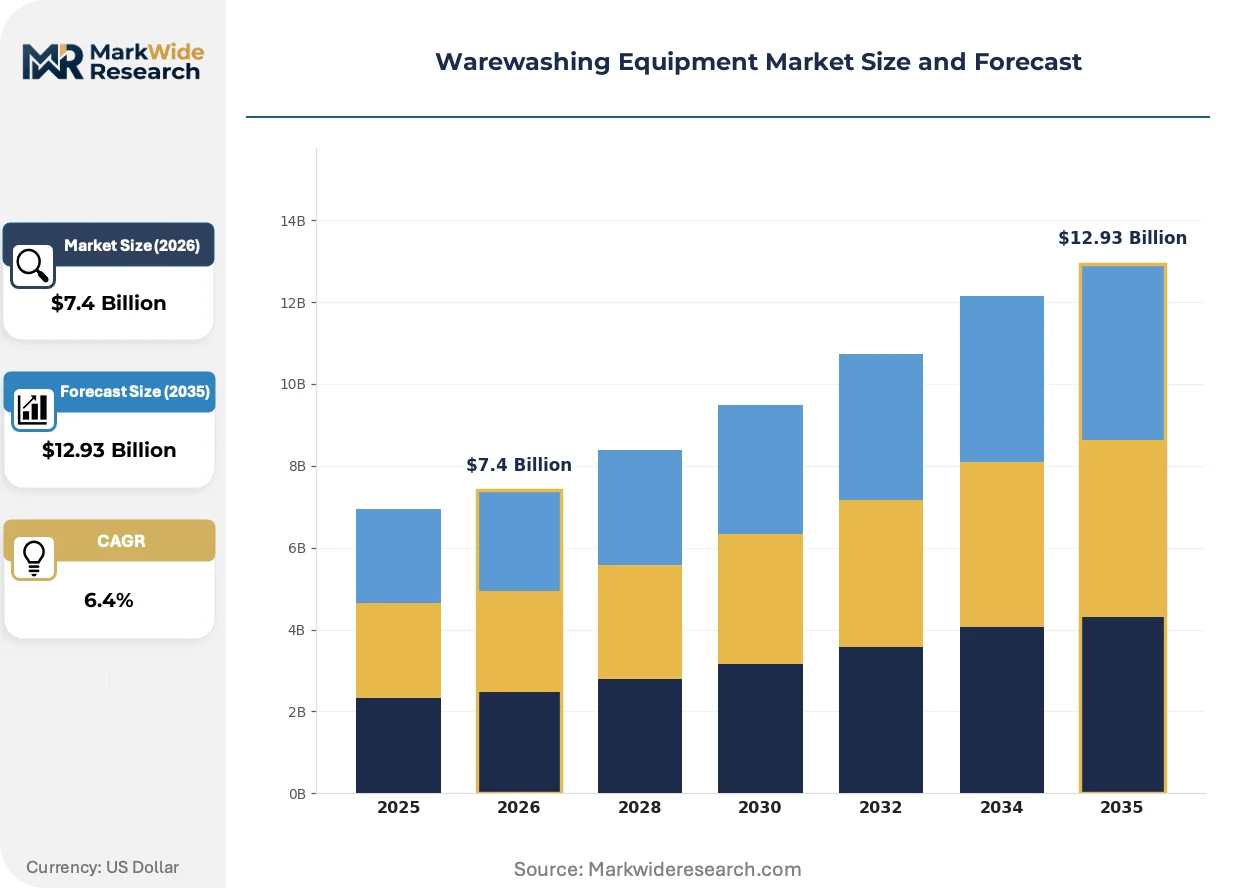
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dishwashers, Glass Washers, Pot Washers, Undercounter Washers End User: Restaurants, Hotels, Cafes, Catering Technology: Conventional, High Efficiency, Energy Star Rated, Manual Installation: Standalone, Built-in, Portable, Mobile |
| Companies Covered | Ali Group, Meiko Maschinenbau, The Middleby Corporation, Illinois Food Equipment, Winterhalter Gastronom, Hobart, Electrolux Professional, Champion Industries, Jackson Warewashing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warewashing Equipment Market Emerging Trajectories
Warewashing equipment architecture is pivoting from standalone mechanical systems to integrated thermal and data platforms, with regulatory compliance and labor substitution operating as simultaneous design constraints rather than sequential priorities.
Heat recovery exchangers are capturing waste energy from final rinse cycles to pre-heat incoming fresh water, cutting natural gas consumption by 30-40% in high-volume operations. Casino and hotel kitchen operators in Nevada and Florida are specifying these configurations to qualify for utility demand-response rebates. The technology is integrating with building management systems to enable automated load shifting during peak tariff windows.
EU Ecodesign Directive delegated regulations are mandating progressive water consumption limits for commercial dishwashers through 2027, with draft measures targeting 1.8 liters per rack for undercounter units. German and Italian OEMs are accelerating spray arm optimization and filtered wash tank designs to maintain throughput under constrained water budgets. Full-service restaurant chains with cross-border European footprints are consolidating procurement around compliant platforms to avoid fragmented national inventory.
Multi-unit operators are consolidating vendor relationships around full-lifecycle cost contracts that bundle equipment, chemicals, and preventive maintenance into per-rack pricing. Casual dining groups with 50-plus locations are displacing transactional equipment purchases with performance-guaranteed service agreements. This model concentrates most visibly in the U.S. Sun Belt, where private equity-backed restaurant rollups prioritize capital-light expansion structures.
Warewashing Equipment Market Segmentation
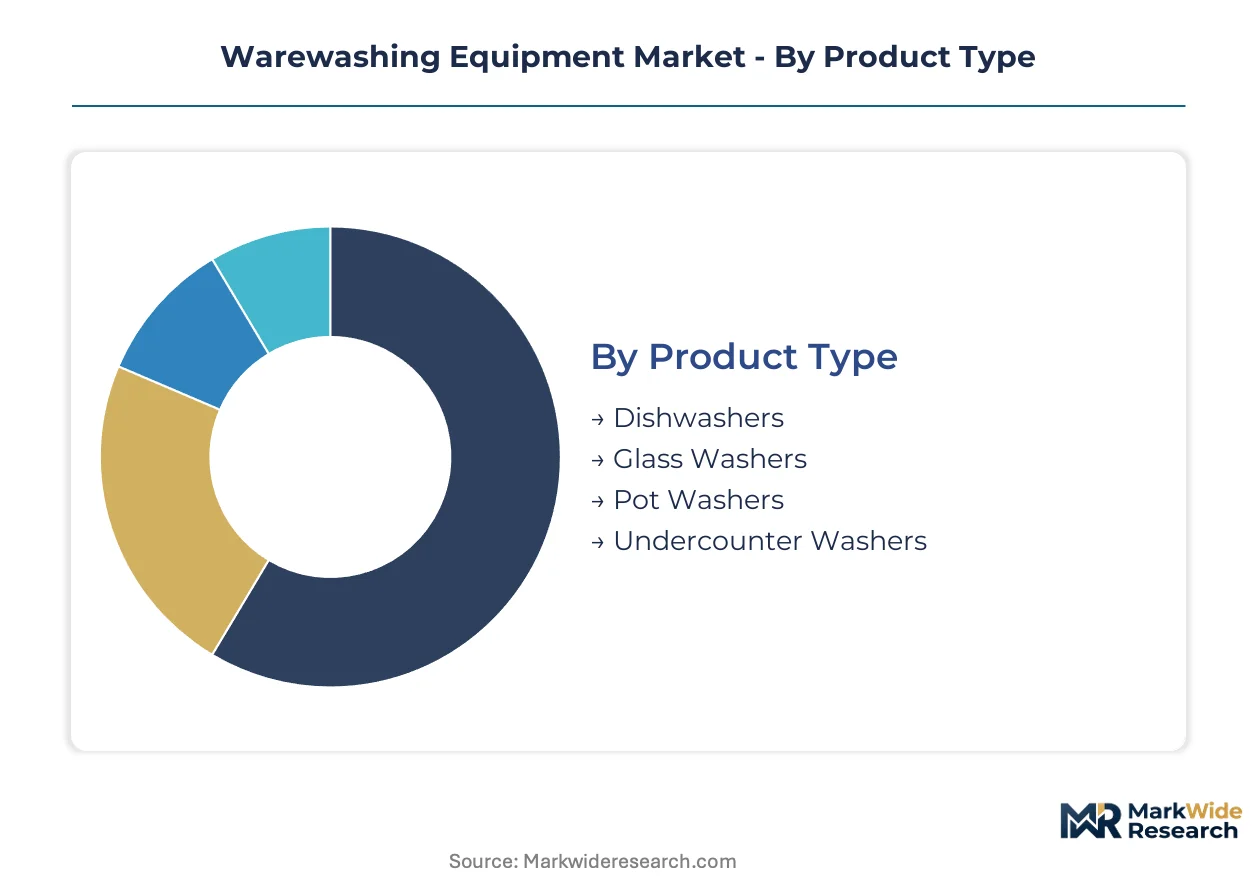
Warewashing equipment segmentation reflects divergent capital intensity and operational integration models across foodservice verticals. Equipment specification varies sharply between standalone front-of-house installations and back-of-house systems embedded within kitchen workflow architecture.
Product Type:
Integration depth separates standalone conveyor systems from compact units embedded under counters or within service lines.
- Dishwashers:Conveyor and door-type machines process 200-400 racks hourly using 150°F-180°F sanitization cycles. Full-service restaurant chains in Germany and the United States specify these for centralized dish rooms with dedicated ventilation infrastructure.
- Glass Washers:Low-temperature rotary brush systems with dedicated rinse chemistry prevent etching on stemware. Boutique hotels in France and Italy embed these directly behind bar counters to eliminate glass transport labor.
- Pot Washers:High-clearance door machines accommodate 140-liter mixing bowls and sheet pans using aggressive alkaline detergents.
- Undercounter Washers:Compact front-loading units integrate beneath prep lines in space-constrained cafes.
Dishwashers lead volumes today; undercounter washers are gaining share fastest in urban micro-kitchen deployments.
End User:
Cost tier stratification distinguishes capital-heavy institutional buyers from lease-oriented operators seeking per-rack service contracts.
- Restaurants:Full-service chains deploy automated conveyor systems to offset kitchen labor shortages, while independent operators favor undercounter units with chemical-inclusive leasing. Chains across Texas and Florida are consolidating procurement around heat-recovery configurations to capture utility rebates.
- Hotels:Casino resorts in Nevada specify heat-recovery dishwashers integrated with building management systems for demand-response participation.
- Cafes:Limited kitchen footprints drive specification of compact undercounter glass washers with reverse-osmosis rinse systems.
- Catering:Mobile operations require portable pot washers with onboard water heating for off-premise event coverage.
Restaurants dominate installed base; hotels are expanding fastest through resort development corridors.
Technology:
Application context determines whether conventional thermal systems suffice or efficiency mandates force platform migration.
- Conventional:Natural gas booster heaters with single-pass water consumption remain prevalent in legacy institutional accounts with stable utility tariffs.
- High Efficiency:Heat recovery exchangers and filtered wash tanks cut consumption by 30-40%, qualifying operators for California and New York utility rebates.
- Energy Star Rated:DOE 10 CFR 431-compliant platforms are displacing conventional equipment in U.S. federal and state procurement.
- Manual:Three-compartment sink systems persist in low-volume catering and temporary foodservice permits.
Conventional technology retains largest installed base; Energy Star rated equipment is climbing the fastest on regulatory replacement cycles.
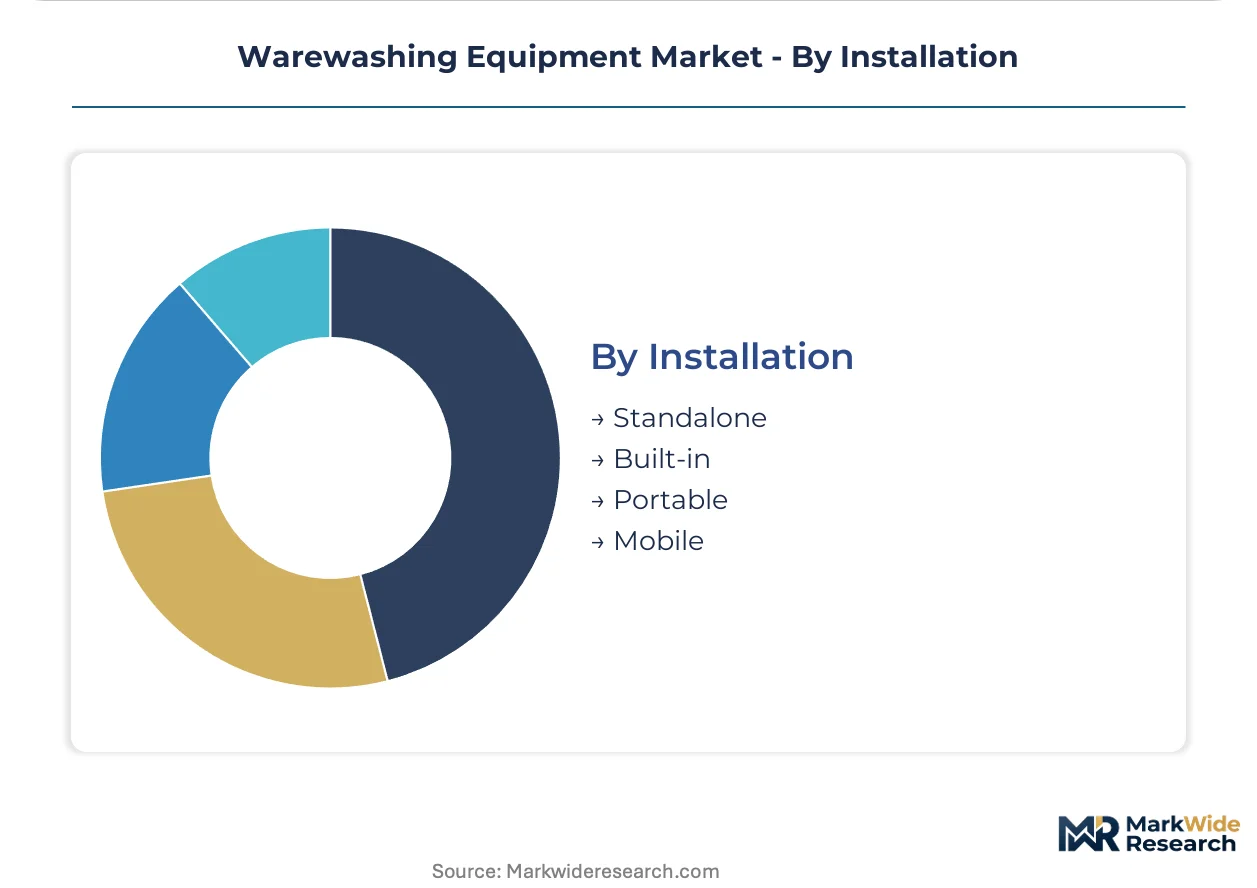
Installation:
Customer type and mobility requirements dictate whether fixed infrastructure or flexible deployment models prevail.
- Standalone:Conveyor and door-type machines occupy dedicated dish rooms with floor drainage and ventilation infrastructure. Hospital and university foodservice accounts in the United States specify these for centralized operations with 10-15 year depreciation schedules.
- Built-in:Undercounter and glass washer units integrate within millwork for front-of-house bar and service line deployment.
- Portable:Castor-mounted pot washers with quick-connect utilities serve catering and ghost kitchen operations requiring equipment relocation.
- Mobile:Self-contained units with onboard water tanks and propane heating support outdoor event and disaster relief foodservice.
Standalone installations anchor revenue today; portable configurations are expanding most quickly in flexible foodservice real estate models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as OEMs relocate fabrication to jurisdictions with lower compliance costs while maintaining access to high-standard markets through modular design platforms.
United States
Full-service restaurant chains across Texas and Florida are accelerating automated conveyor deployments to offset kitchen labor shortages. The U.S. Department of Energy's 10 CFR 431 efficiency mandates are compressing replacement cycles toward high-efficiency platforms. The Sun Belt hospitality corridor from Phoenix to Orlando concentrates procurement activity for heat-recovery configurations qualifying for utility demand-response rebates.
Germany
Baden-Württemberg's stainless steel fabrication cluster anchors European OEM supply chains through captive pump and conveyor manufacturing. The EU Ecodesign Directive's progressive water consumption limits through 2027 are forcing spray arm optimization investments. Offenburg and Stuttgart industrial zones are expanding output to serve rebounding hospitality capital expenditure across the continent.
Italy
Boutique hotel operators in Milan and Florence are embedding front-of-house glass washers to eliminate stemware transport labor. CE marking under the EU Machinery Directive shapes product development roadmaps for export-oriented manufacturers. The Veneto and Emilia-Romagna regions host burner technology centers differentiating on energy recovery system integration.
India
Emerging hospitality infrastructure in Mumbai and Bangalore lacks automated warewashing penetration, creating positioning opportunities for NSF-compliant equipment platforms. The Food Safety and Standards Authority of India's commercial kitchen standards are elevating hygiene compliance requirements. Maharashtra and Karnataka state governments are channeling hospitality investment toward organized sector foodservice with centralized dish room specifications.
France
Casino resort operators in the Côte d'Azur corridor are specifying heat-recovery dishwashers integrated with building management systems. ANSM and CNIL oversight creates dual compliance pathways for connected equipment platforms. The Île-de-France region concentrates procurement from multi-unit operators consolidating vendor relationships around full-lifecycle cost contracts.
Warewashing Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue heat-pump drying convergence and cloud-connected predictive maintenance as differentiation vectors. The market exhibits moderate concentration with tiered positioning across captive fabrication specialists and diversified commercial kitchen equipment portfolios. Strategic archetypes include stainless steel fabricators with vertical control over pump subassemblies, burner technology licensors, and full-lifecycle service contract bundlers. Dominant competitive moves center on capacity expansion in German manufacturing corridors and exclusive distributor network consolidation for North American institutional accounts.
Among German-based fabricators, Meiko Maschinenbau exemplifies the captive-component archetype through its Offenburg manufacturing footprint, while Winterhalter Gastronom occupies a position within the premium-tier service contract segment. Illinois Food Equipment represents the North American institutional channel specialist archetype. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Ali Group |
| Meiko Maschinenbau |
| The Middleby Corporation |
| Illinois Food Equipment |
| Winterhalter Gastronom |
| Hobart |
| Electrolux Professional |
| Champion Industries |
| Jackson Warewashing Systems |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign Directive water consumption mandates gate qualified supply access and premium-tier pricing power, compressing equipment refresh cycles toward certified platforms while OEMs with captive stainless steel fabrication in Baden-Württemberg capture margin expansion unavailable to import-dependent competitors.
Pricing Analysis
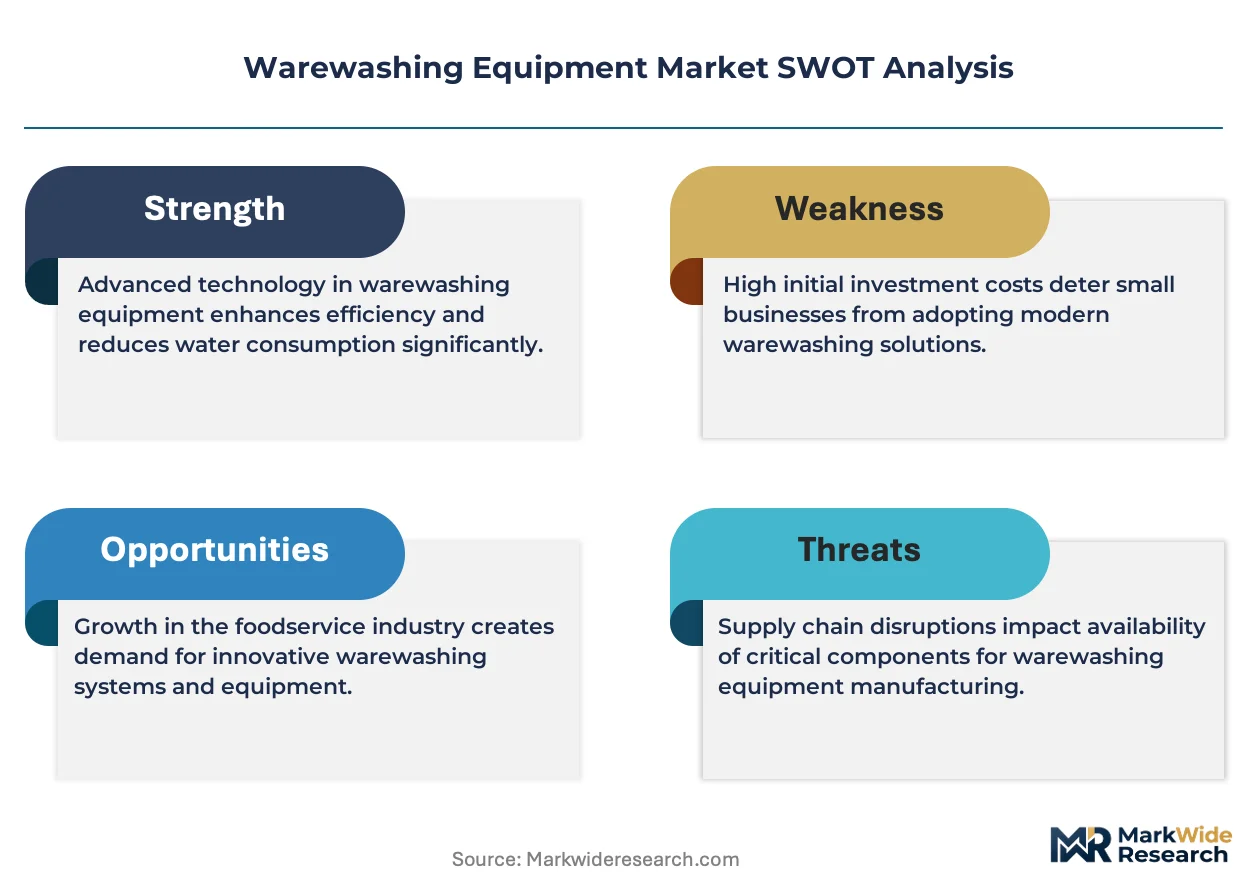
Distributor margins in the 18-25% range dominate channel economics for institutional foodservice accounts, while direct-to-OEM volume discounts compress transactional pricing for multi-unit restaurant chains. Three-tier pricing structure across premium heat-recovery configurations, standard Energy Star-rated platforms, and economy conventional units separates buyers by certification grade and utility rebate eligibility. Price differentiation hinges on NSF/ANSI 3 certification status and heat exchanger geometry complexity, with California and New York operators least sensitive due to rebate stacking. Cost compression in the economy tier is intensifying as Chinese stainless steel imports pressure European fabrication margins.
Supply Chain Analysis
Refurbishment flows for conveyor subassemblies and pump modules are emerging from casino resort operators in Nevada and Florida seeking to extend depreciation schedules. Manufacturing gravity centers on Germany, Italy, and the United States, with Baden-Württemberg's stainless steel cluster anchoring European pump and conveyor supply. Raw material dependencies rest on nickel-alloy sheet stock, caustic soda for detergent chemistry, and precision burner castings from Emilia-Romagna. Single-source vulnerability concentrates in German captive pump manufacturing, where MEKO Maschinenbau's vertical control limits second-source availability. Distribution runs through exclusive distributor networks for North American institutional accounts and direct OEM relationships for European full-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The warewashing equipment market represents a late-cycle quality story as full-service restaurant chains consolidate procurement around heat-recovery configurations that satisfy both DOE 10 CFR 431 mandates and utility rebate qualification thresholds.
For Market Incumbents: Lock in channel control through exclusive distributor network consolidation across the U.S. Sun Belt hospitality corridor, while deepening backward integration into stainless steel fabrication to defend margin position against Chinese import pressure. Prioritize captive supply of heat exchanger subassemblies to offset emerging entrant competition from heat-pump drying convergence specialists. For New Entrants and Emerging Players: Launch via equipment-as-a-service contracts targeting India's Mumbai and Bangalore hospitality infrastructure, where FSSAI commercial kitchen standards are elevating hygiene compliance requirements without established vendor relationships. Penetrate the portable equipment segment serving ghost kitchen and catering operators with castor-mounted pot washers, leveraging quick-connect utility specifications as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional stainless steel fabricators with NSF-compliant welding certification because fragmented North American institutional channel access creates consolidation value through distributor network aggregation. Monitor state-level building electrification mandate acceleration as the inflection signal for heat pump booster heater technology viability.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Drying Convergence | Integration with refrigeration cycle dehumidification eliminates natural gas dependency for California operators. |
| Cloud-Connected Predictive Maintenance | IoT-enabled wash cycle analytics allow OEMs to unbundle service contracts from equipment sales revenue. |
| NSF-Compliant Platform Entry | Certification investment opens India FSSAI-regulated hospitality infrastructure in Maharashtra and Karnataka. |
| Exclusive Distributor Consolidation | Channel control across Texas and Florida institutional accounts defends position against import competition. |
| Spray Arm Optimization R&D | EU Ecodesign Directive water limits through 2027 force throughput maintenance under constrained consumption budgets. |
Methodological Framework
Direct dialogue with commercial kitchen equipment procurement directors, foodservice facility maintenance managers, OEM product development engineers, and utility demand-response program administrators grounded qualitative findings in operational reality. Secondary validation drew from DOE 10 CFR 431 regulatory filings, EU Ecodesign Directive delegated regulations, NSF International certification databases, and trade data from German mechanical engineering associations. Bottom-up equipment shipment tallies by product type and installation configuration were cross-referenced against top-down hospitality capital expenditure surveys to establish triangulated market sizing.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, technology tier, end-user vertical, and geographic regulatory cluster. The analytical framework incorporated dishwasher rack throughput specifications, utility tariff escalation curves, and state-level electrification mandate adoption rates as industry-specific forecast inputs. CAGRs were derived from equipment replacement cycle compression analysis and hospitality sector employment elasticity to automation investment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated building electrification mandates or chlor-alkali plant disruption affecting alkaline detergent input costs. Practitioners should monitor FSSAI enforcement intensity in India and utility rebate program renewal schedules in deregulated U.S. markets for early signals of demand trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Commercial Bar Equipment Market