
 Restaurant Fryers Market | 2026-2036
Restaurant Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Fryers Market Analytics
EPA grease-management mandates for commercial kitchens is recalibrating the cost-of-entry calculus for new fryer installations across the United States. Middleby Corporation leverages its vertical manufacturing footprint to control component sourcing for automated filtration systems. Henny Penny anchors the pressure-fryer segment through specialized designs targeting chicken-centric quick-service chains. Ali Group competes across multiple price tiers through its portfolio of European and North American equipment brands.
A restaurant fryer is a thermostatically controlled cooking appliance that heats oil or fat to temperatures between 325°F and 375°F for submerging and cooking food products, constructed from stainless steel with immersion heating elements or gas burner tubes and incorporating sediment zones, filtration loops, and interlock safety mechanisms. Electric fryers now lead unit shipments in urban locations with strict ventilation codes, while gas fryers sustain margin pools in high-volume operations where energy costs favor hydrocarbon fuels. Pressure fryers represent the fastest-growing product type as fast-casual chains expand fried-chicken menus requiring faster cook cycles and reduced oil absorption.
FDA food-code provisions on cooking-oil temperature monitoring and OSHA kitchen-safety standards on burn and fire hazards shape equipment specifications and installation protocols across commercial foodservice operations. The EU Ecodesign Directive and accompanying energy-labeling requirements for professional kitchen equipment restrict standby power consumption and mandate efficiency disclosures, redirecting procurement toward certified models. Stakeholders must weigh total cost of ownership against upfront capital outlay as regulatory compliance layers compound with labor-automation requirements.
Market Dynamics
Automated oil-filtration systems are compressing labor requirements and recalibrating capital-deployment timelines for quick-service operators across North America and Europe. Equipment buyers now prioritize total cost of ownership over upfront unit price as regulatory compliance layers compound with automation mandates.
Growth Catalysts
- EPA grease-management mandates:Commercial kitchens in the United States face stricter discharge protocols, forcing upgrades to integrated filtration loops and sediment-zone designs.
- Pressure-fryer technology:Fast-casual chains expanding fried-chicken menus demand faster cook cycles with reduced oil absorption, pulling specialized equipment into mainstream procurement.
- EU F-Gas Regulation:European operators are retiring gas-fired models in favor of electric units with lower-GWP refrigerants, creating replacement demand across Germany, France, and Italy.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin pools for fabrication-heavy manufacturers dependent on commodity markets.
- Ventilation-code stringency:Urban jurisdictions in California and New York impose hood-system requirements that disqualify gas fryers from dense-location installations.
- Induction cooking substitution:Oil-free alternatives for specific menu categories threaten fryer unit economics in health-positioned concepts.
Strategic Opportunities
- Self-cleaning automation:Labor shortages across the United States are accelerating capital investment in fryers with automated wash cycles and filtration.
- India quick-service expansion:Western fast-food chains entering tier-2 cities create first-mover positioning for ventless electric models suited to constrained kitchen footprints.
- ISO 22000 certification convergence:Food-safety management standards are becoming procurement gatekeepers, favoring suppliers with documented hazard controls.
Industry Challenges
- Certification timeline compression:UL and NSF approval cycles for new filtration mechanisms lag product-development schedules, delaying commercialization.
- Legacy control-system integration:IoT-enabled fryers must interface with existing kitchen-display and inventory-management infrastructure, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Fryers Market |
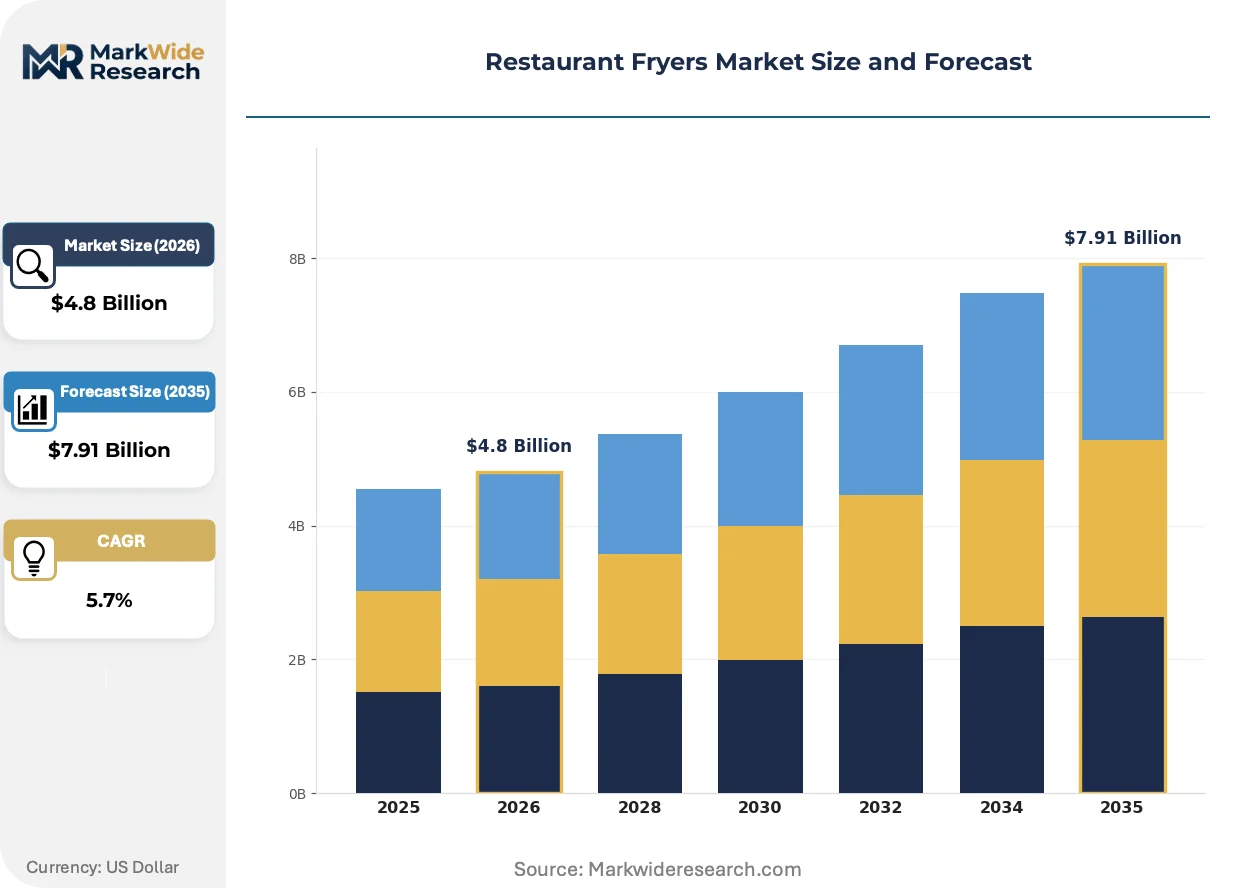
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fryers, Gas Fryers, Pressure Fryers, Conveyor Fryers End User: Fast Casual Restaurants, Fine Dining, Cafés, Food Trucks Installation Type: Countertop, Floor-standing, Indoor, Outdoor Maintenance Type: Preventive, Corrective, Routine, Emergency |
| Companies Covered | Middleby Corporation, Ali Group, Henny Penny, Electrolux Professional, Frymaster, Pitco, Vulcan, Welbilt, ITW Food Equipment Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Fryers Market Evolving Landscape
Equipment intelligence and energy-transition mandates are rewriting procurement criteria across commercial foodservice. Fryer manufacturers must now engineer for connectivity, efficiency disclosure, and labor substitution simultaneously.
Sensor-embedded fryers with real-time oil-quality monitoring are converging with cloud-based kitchen-management platforms. Large franchise operators in the United States are piloting these systems to optimize filtration scheduling and extend oil life. The technology is converging with predictive-maintenance service models that unbundle after-sales revenue from equipment margin.
The EU Ecodesign Directive now caps standby power consumption for professional kitchen equipment and mandates efficiency labeling. Manufacturers must redesign heating-element controls and insulation packages to meet disclosure thresholds. Full-service restaurants and institutional caterers across Germany, France, and the Netherlands are prioritizing certified models in competitive tenders.
Equipment-as-a-service contracts are displacing outright purchase for mid-scale operators with constrained capex budgets. Distributors in the United Kingdom and Ireland are bundling fryer leases with oil-management and maintenance subscriptions. Fast-casual chains with rapid expansion timelines favor this structure to preserve liquidity for real estate and build-out costs.
Restaurant Fryers Market Segmentation
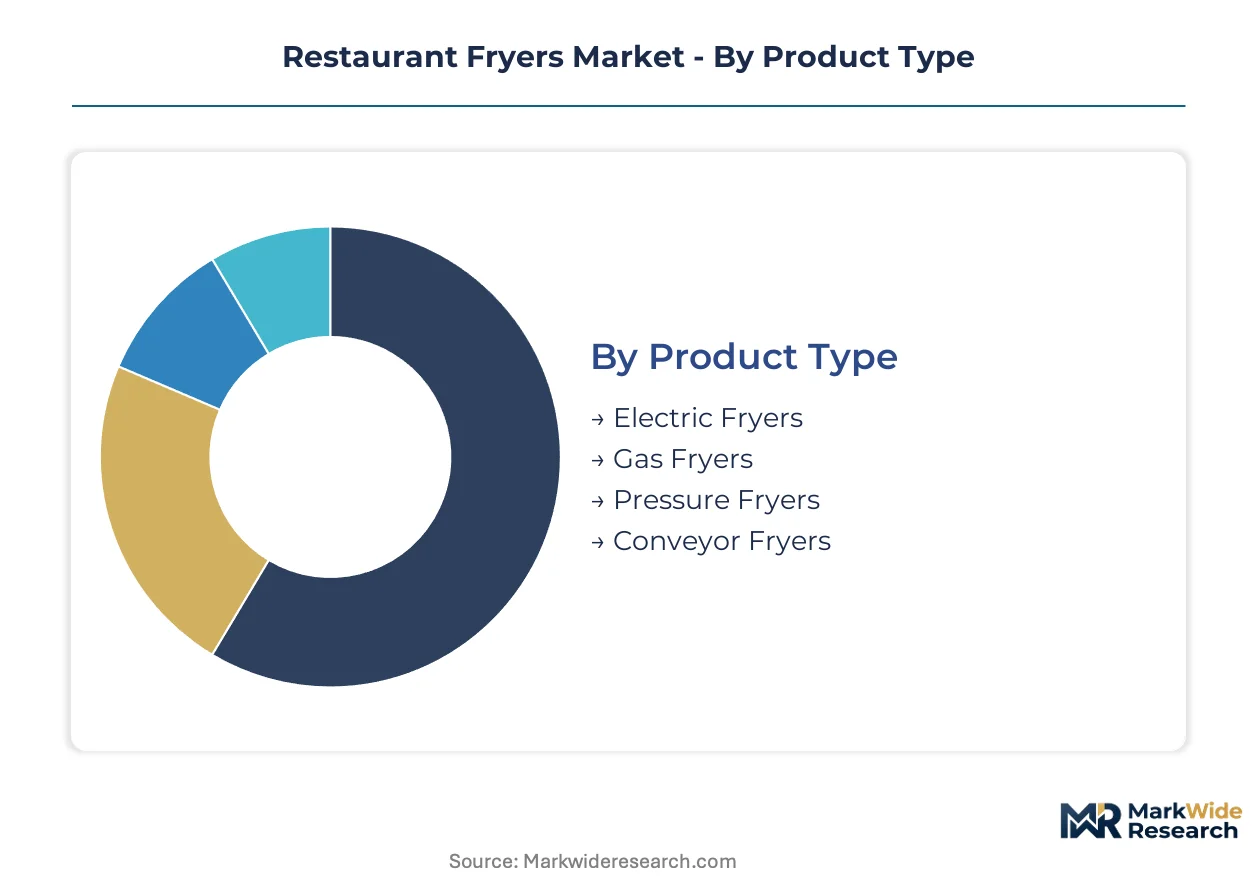
Equipment specification choices in the restaurant fryers market cascade through energy costs, labor deployment, and regulatory compliance. Procurement teams segment options across thermal technology, operational setting, and service intensity to match capital constraints against throughput requirements.
Product Type:
Heating mechanism and pressure architecture define thermal efficiency, cook speed, and oil degradation curves across commercial deployments.
- Electric Fryers:Immersion heating elements deliver precise temperature control without combustion ventilation requirements. Urban operators in California and New York specify these models to satisfy strict municipal emissions codes while avoiding hood-system capital expenditure.
- Pressure Fryers:Sealed cooking chambers elevate internal pressure above atmospheric levels, accelerating protein cook cycles by 30-40% while reducing oil absorption. Fast-casual chains expanding fried-chicken menus in the United States are standardizing on these units to compress ticket times and extend oil life.
- Gas Fryers:Atmospheric or infrared burner configurations deliver faster recovery rates for high-volume batch frying. Operators in Texas and Florida with lower natural gas tariffs favor these units for margin preservation at peak throughput.
- Conveyor Fryers:Continuous belt systems automate product movement through fixed-temperature oil zones for standardized output. High-volume quick-service chains with limited skilled labor deploy these for menu consistency across multiple locations.
Electric fryers lead on scale; pressure fryers lead on momentum.
End User:
Service model and price positioning dictate fryer specification priorities from throughput volume to aesthetic integration.
- Fast Casual Restaurants:Hybrid service formats demand rapid cook cycles with visible equipment profiles. Chains in the United States prioritize automated filtration and compact footprints to balance speed with kitchen labor constraints.
- Fine Dining:Smaller batch requirements and open-kitchen visibility drive specification toward precision temperature control and premium stainless finishes. Operators accept higher unit costs for equipment that supports menu storytelling.
- Cafés:Limited kitchen footprints and diversified daypart menus favor countertop electric models with rapid recovery. Operators in dense urban districts specify ventless configurations to circumvent hood installation timelines.
- Food Trucks:Mobile power constraints and space compression require compact electric or propane-fired units with simplified maintenance access. Operators prioritize reliability over feature depth given remote service challenges.
Fast casual commands the largest installed base; food trucks are climbing the fastest.
Installation Type:
Physical deployment constraints shape ventilation pathways, mobility requirements, and structural load calculations.
- Countertop:Compact electric units with direct electrical connection and minimal clearance requirements. Cafés and ghost kitchens in Manhattan and San Francisco deploy these to maximize production density per square foot.
- Floor-standing:High-capacity vessels with caster mobility or fixed anchoring for stability during filtration cycles. Full-service restaurants and institutional kitchens specify these for volume flexibility and integrated oil management.
- Indoor:Standard configurations with hood integration or ventless certification for enclosed kitchen environments. The majority of commercial fryer deployments fall within this category across all end-user segments.
- Outdoor:Weather-sealed housings with enhanced insulation and corrosion-resistant finishes for patio kitchens and event catering. Resorts in Florida and California specify these for seasonal revenue extension.
Indoor installations dominate absolute volume; outdoor configurations show the steepest expansion trajectory.
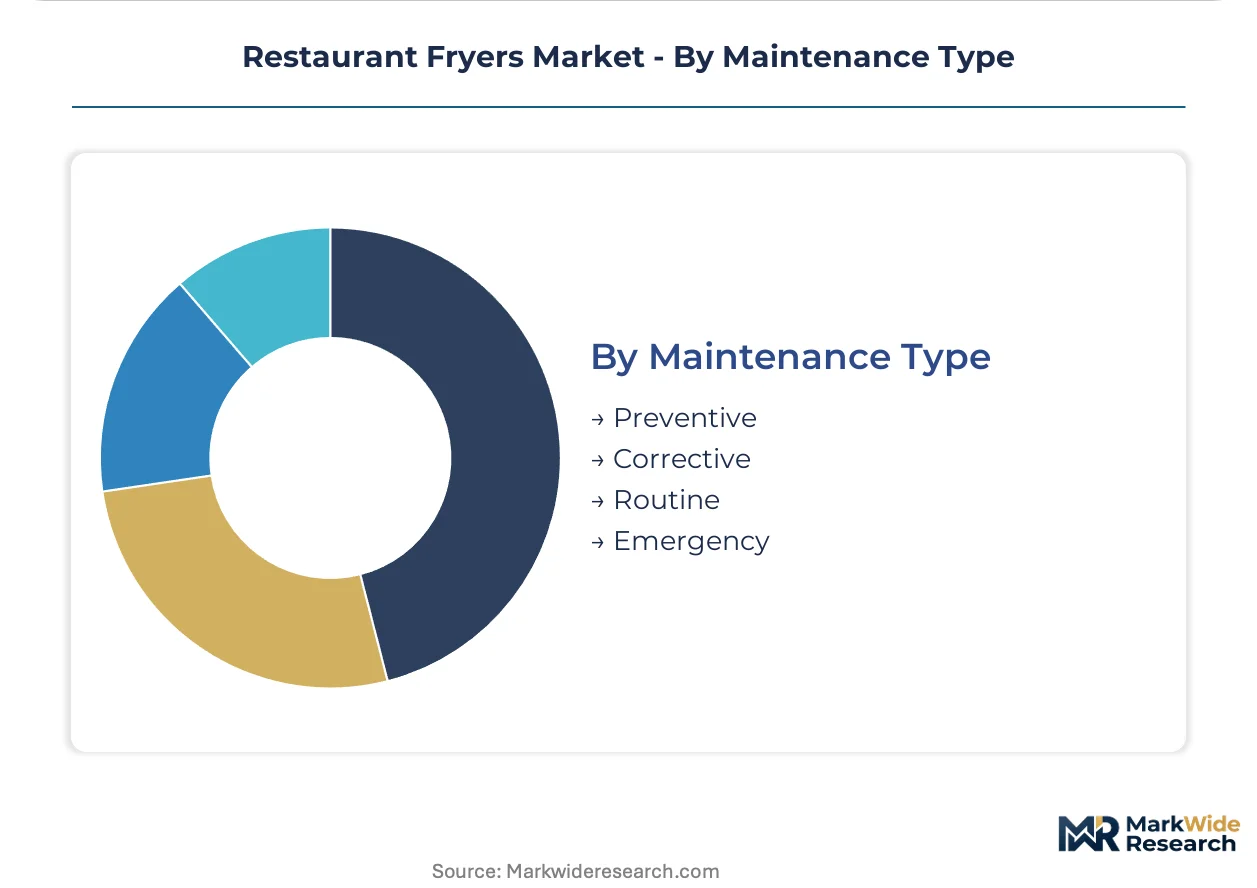
Maintenance Type:
Service intervention timing and scope determine total cost of ownership and operational continuity risk.
- Preventive:Scheduled component inspection, calibration, and replacement before failure occurrence. Large franchise operators in the United States contract OEM service networks to minimize unplanned downtime.
- Corrective:Reactive repair following equipment malfunction or performance degradation. Independent operators with limited service budgets often defer to this model despite higher per-incident costs.
- Routine:Daily or weekly operator-performed tasks including filtration, boil-out, and sediment removal. Automated systems are compressing labor hours in this category across quick-service deployments.
- Emergency:Unscheduled intervention for critical failures threatening food safety or operational continuity. 24/7 service coverage commands premium pricing in dense metropolitan markets.
Preventive contracts capture the highest service revenue; routine maintenance is gaining share fastest as automation displaces manual labor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled kitchen-equipment technicians and commercial foodservice engineers concentrate in industrial corridors across five countries where restaurant fryer procurement accelerates.
United States
Quick-service chains in Texas and Florida favor gas-fired models for energy-cost preservation, while California and New York operators specify electric units to satisfy municipal ventilation codes. EPA grease-management mandates compel integrated filtration upgrades across commercial kitchens. Dallas-Fort Worth anchors high-volume equipment distribution to Sun Belt restaurant clusters.
Germany
Full-service restaurants and institutional caterers prioritize EU Ecodesign-certified models with capped standby power consumption. The EU F-Gas Regulation redirects procurement toward electric fryers with lower-GWP refrigerants. Industrial equipment fabricators in North Rhine-Westphalia supply certified units across the Rhine-Ruhr metropolitan corridor.
China
Western fast-food chains expanding into tier-2 cities generate demand for compact ventless electric configurations. National efficiency standards for commercial kitchen equipment tighten import requirements for foreign manufacturers. Shanghai-based distributors channel equipment to Yangtze River Delta restaurant developments.
India
Quick-service expansion in Maharashtra and Karnataka creates first-mover positioning for countertop electric models suited to constrained kitchen footprints. FSSAI food-safety protocols elevate certification requirements for imported equipment. Mumbai-Pune industrial belt hosts emerging fabrication capacity for localized production.
United Kingdom
Mid-scale operators favor equipment-as-a-service contracts to preserve capex liquidity for real estate costs. Energy-labeling disclosure mandates reshape competitive tender evaluation criteria. London distributors bundle fryer leases with oil-management subscriptions across Greater Southeast restaurant networks.
Restaurant Fryers Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive component sourcing and specialized pressure-fryer engineering houses. Market concentration reflects consolidation among foodservice equipment portfolios spanning multiple price tiers and thermal technologies. Three archetypes dominate: vertically integrated manufacturers controlling filtration-system supply chains, pressure-fryer specialists serving chicken-centric quick-service chains, and multi-brand holding companies competing across premium and economy segments. Dominant competitive moves include backward integration into heating-element fabrication and geographic expansion through distributor network acquisition.
Among North American-based diversified manufacturers, Middleby Corporation, Henny Penny, and Ali Group exemplify contrasting strategic positions. Middleby Corporation occupies a position as a vertically integrated fabricator with captive supply of automated filtration components. Henny Penny anchors the pressure-fryer specialization archetype through engineered designs targeting protein-focused fast-casual concepts. Ali Group sits within the multi-brand portfolio tier, competing across European and North American price segments through distinct equipment marques.
| Leading Market Players |
|---|
| Middleby Corporation |
| Ali Group |
| Henny Penny |
| Electrolux Professional |
| Frymaster |
| Pitco |
| Vulcan |
| Welbilt |
| ITW Food Equipment Group |
| Others |
Value Network & Pricing Analysis
Quick-service chains consolidating procurement around automated filtration specifications are forcing fabricators to reconfigure component sourcing and absorb upfront engineering costs into longer-term service contracts. This demand-side specification tightening compresses margin pools for manufacturers lacking captive supply of filtration hardware or predictive maintenance platforms.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning across the restaurant fryers market. Equipment-as-a-service contracts with integrated oil-management subscriptions command premium positioning against transactional unit sales, particularly among mid-scale operators preserving capex liquidity. Price differentiation rests on UL/NSF certification tier and automation depth, with self-cleaning models capturing wider spreads over baseline electric units. Cost compression in standard gas-fired configurations is intensifying because stainless steel input volatility and ventilation-code stringency in California and New York disqualify these units from dense urban deployments. Fast-casual chains with rapid expansion timelines exhibit highest price sensitivity, while institutional caterers with multi-year procurement cycles prioritize total cost of ownership over upfront outlay.
Supply Chain Analysis
Workforce availability constraints in North Rhine-Westphalia, Ohio, and Guangdong industrial corridors are lengthening lead times for precision fabrication of heating elements and filtration housings. Supply concentration centers on Germany, the United States, and China for stainless steel vessel forming, with India emerging for localized assembly serving South Asian quick-service expansion. Raw material dependencies draw from Grade 304 and 316 stainless steel, immersion heating coils, and electronic control modules. Single-source vulnerability in semiconductor-based temperature controllers creates exposure for IoT-enabled product lines. Distribution runs through authorized dealer networks with OEM-direct service contracts for large franchise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
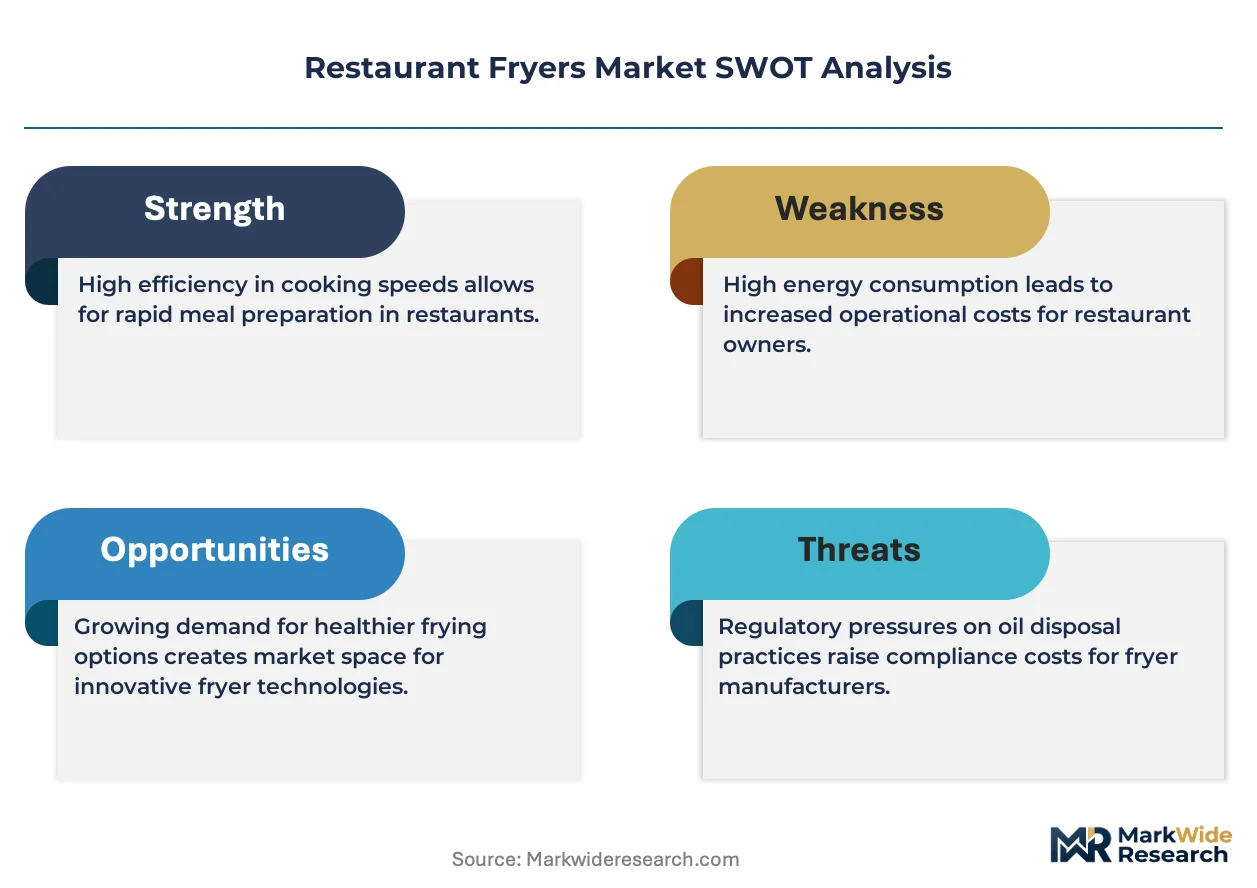
The restaurant fryers market functions as a stable compounder, with regulatory mandates on grease management and oil-disposal protocols ensuring replacement demand cycles regardless of macroeconomic volatility.
For Market Incumbents: Extend predictive maintenance service platforms to capture recurring revenue streams and deepen customer switching costs. Defend against induction cooking substitution in health-positioned concepts by accelerating R&D into oil-quality sensor integration. Backward integration into heating-element fabrication secures margin control against commodity volatility.
For New Entrants and Emerging Players: Capture white-space positioning in India's tier-2 city quick-service expansion, where Western fast-food chains require compact ventless electric models suited to constrained kitchen footprints. Target food truck operators with propane-fired reliability-focused units addressing mobile power constraints. Pursue FSSAI certification early to establish procurement eligibility before localized fabrication capacity matures.
For Investors and Strategic Acquirers: Asymmetric upside sits with pressure-fryer specialists possessing proprietary sealed-chamber designs and established relationships with chicken-centric fast-casual chains. The five-to-ten-year viability window favors manufacturers with documented ISO 22000 hazard controls and installed base density enabling predictive maintenance monetization. Watch for EPA enforcement acceleration on grease-management mandates as the inflection indicator for filtration-system upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filtration Component Manufacturing | Middleby Corporation's captive supply of automated filtration hardware protects margin pools against commodity volatility. |
| Pressure-Fryer Specialization for Protein-Focused Chains | Henny Penny's sealed-chamber designs target fast-casual fried-chicken expansion with 30-40% cook cycle compression. |
| Equipment-as-a-Service Contract Expansion | UK distributors bundling fryer leases with oil-management subscriptions preserve operator liquidity for real estate costs. |
| Ventless Electric Model Development | Urban operators in California and New York specify these configurations to circumvent hood installation timelines and emissions codes. |
| ISO 22000 Certification Investment | Food-safety management standards are becoming procurement gatekeepers across institutional catering and quick-service tenders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with quick-service chain procurement directors, commercial kitchen equipment distributors, OEM aftermarket service heads, and restaurant facility engineers with secondary validation. Primary fieldwork drew from equipment specification reviews, competitive tender documentation, and operator deployment case studies. Secondary sources included EPA regulatory filings, EU Ecodesign Directive compliance databases, NSF certification registries, and customs trade data on stainless steel equipment imports. Bottom-up unit shipment modeling and top-down value triangulation cross-validated segment-level estimates.
Historical reference periods anchored the forecast window through verified installation data and replacement cycle documentation across quick-service, fast-casual, and institutional end-use segments. The analytical framework modeled thermal technology, operational setting, service intensity, and geographic regulatory cluster across the projection horizon. CAGRs derived from regression analysis against macroeconomic indicators and regulatory enforcement timelines. Industry-specific forecast inputs incorporated oil-price sensitivity for gas-fired units and labor-cost trajectories for automation adoption curves.
Stainless steel commodity volatility, EPA enforcement acceleration, and induction cooking substitution momentum are the dominant revision risks for installed base and replacement demand assumptions. Forecasts reflect documented regulatory timelines and operator capex intention surveys. Material deviation in named triggers warrants pause and re-evaluation of segment-level penetration assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market