
 Popcorn Machine Market | 2026-2036
Popcorn Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Popcorn Machine Market Analytics
Modular concession bundles pairing popcorn machines with warming cabinets and dispensing stations is hardening as the dominant procurement pattern for theater operators. Gold Medal Products Co. anchors the commercial segment through deep specialization in high-volume kettle systems for stadium and cinema deployments. Hamilton Beach Brands competes aggressively in the home appliance tier with compact countertop units distributed through mass retail channels. Nostalgia Products leverages retro-styled designs to differentiate within the gift and specialty segments.
A popcorn machine is an electromechanical or gas-powered appliance engineered to heat kernels to approximately 180°C via conduction or hot-air circulation, expanding internal moisture into edible foam. Commercial units employ stainless steel kettles with motorized stirring mechanisms and output capacities ranging from 4 to 32 ounces per batch. The commercial machines segment dominates value generation through durable equipment sales to theater chains and concession operators. Home appliances represent the fastest-expanding category as residential snacking habits shift toward experiential food preparation. Kettle popcorn machines retain strong margin pools in specialty retail and festival catering due to their theatrical visual appeal and premium positioning.
The US FDA governs food-contact surfaces under 21 CFR regulations, compelling manufacturers toward stainless steel and certified non-stick coatings. China's SAMR enforces GB standards for electrical safety and energy efficiency in small appliances exported or sold domestically. Germany's LFGB framework shapes material migration limits that influence European procurement specifications. Stakeholders must monitor evolving energy-efficiency mandates and food-safety certifications as baseline requirements for market access across major economies.
Market Dynamics
Theatrical concession operators are consolidating procurement around integrated equipment bundles that combine popping, warming, and dispensing functions into single-source vendor relationships.
Growth Catalysts
- Self-Serve Concession Formats:Cinema chains in the United States are retrofitting lobby spaces with customer-operated stations that reduce labor costs during peak attendance windows.
- 21 CFR Food-Contact Compliance:The US FDA's tightening material standards are accelerating replacement cycles for aging aluminum-kettle units in commercial kitchens.
- Hot-Air Circulation Technology:Oil-free popping systems are capturing health-conscious segments in Germany's cinema market where LFGB migration limits already favor stainless-steel construction.
Market Restraints
- Stainless Steel Input Volatility:Kettle manufacturers face margin pressure from commodity-grade 304 stainless price swings tied to nickel supply concentration in Indonesia.
- Specialized Maintenance Labor:Commercial units require certified technicians for kettle calibration and agitator repair, creating service deserts outside major metropolitan zones.
- Home Air-Popper Substitution:Compact countertop alternatives at mass retail price points divert low-volume residential buyers from premium kettle-style machines.
Strategic Opportunities
- India's Multiplex Expansion:PVR-Inox and Cinepolis India are adding screens in Tier-2 cities where concession infrastructure remains underdeveloped.
- Event Catering Applications:Kettle-style units with theatrical visual appeal are penetrating festival circuits and mobile food operations beyond traditional theater settings.
- EU Energy Efficiency Mandates:The Ecodesign Directive is creating procurement preference for induction-heating kettles that outperform legacy gas systems in carbon accounting.
Industry Challenges
- GB Standard Certification Timelines:China's SAMR electrical safety approvals for imported commercial equipment extend lead times by four to six months.
- Legacy POS Integration:Theater operators require API compatibility between new dispensing stations and existing ticketing platforms, complicating vendor selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popcorn Machine Market |
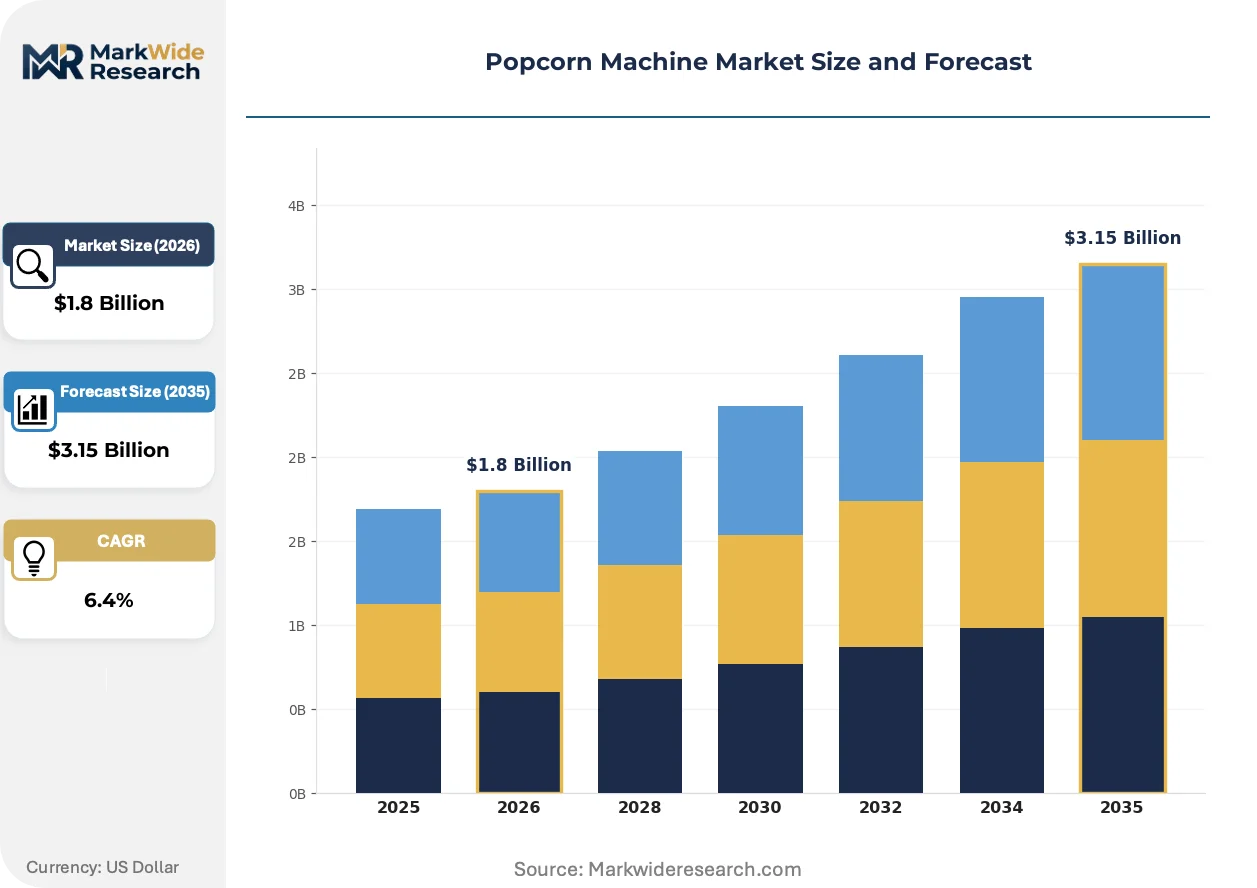
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Machines, Home Appliances, Kettle Popcorn Machines, Microwave Popcorn Makers End User: Theaters, Restaurants, Households, Concession Stands Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales Application: Snacking, Events, Catering, Festivals |
| Companies Covered | Conair Corporation, Hamilton Beach Brands, Gold Medal Products Co., The Legacy Companies, Wabash Valley Farms, National Presto Industries, Nostalgia Products, Nordic Ware, Great Northern Popcorn Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popcorn Machine Market Evolving Landscape
Equipment functionality is converging around automation and data capture as operators seek labor substitution and real-time consumption analytics.
Induction-heating kettle systems are unifying temperature precision with energy metering capabilities. Major theater chains in Germany and the United States are specifying these units for new-build locations. This technology is unifying operational reporting with equipment performance data, compressing the traditional separation between kitchen hardware and facility management software.
REACH substance restrictions are reshaping coating specifications for food-contact surfaces across European procurement. Manufacturers are reformulating non-stick formulations to eliminate perfluorinated compounds ahead of sunset dates. Commercial-grade popcorn equipment sold into France, Germany, and Italy now carries expanded material documentation to satisfy ECHA compliance verification.
Concession bundling is consolidating vendor relationships as theater operators reduce supplier counts. Single-source contracts covering machines, warming cabinets, and dispensing stations are displacing component-by-component purchasing. This pattern is most visible in the United States where AMC, Cinemark, and Regal have standardized around integrated equipment packages.
Popcorn Machine Market Segmentation
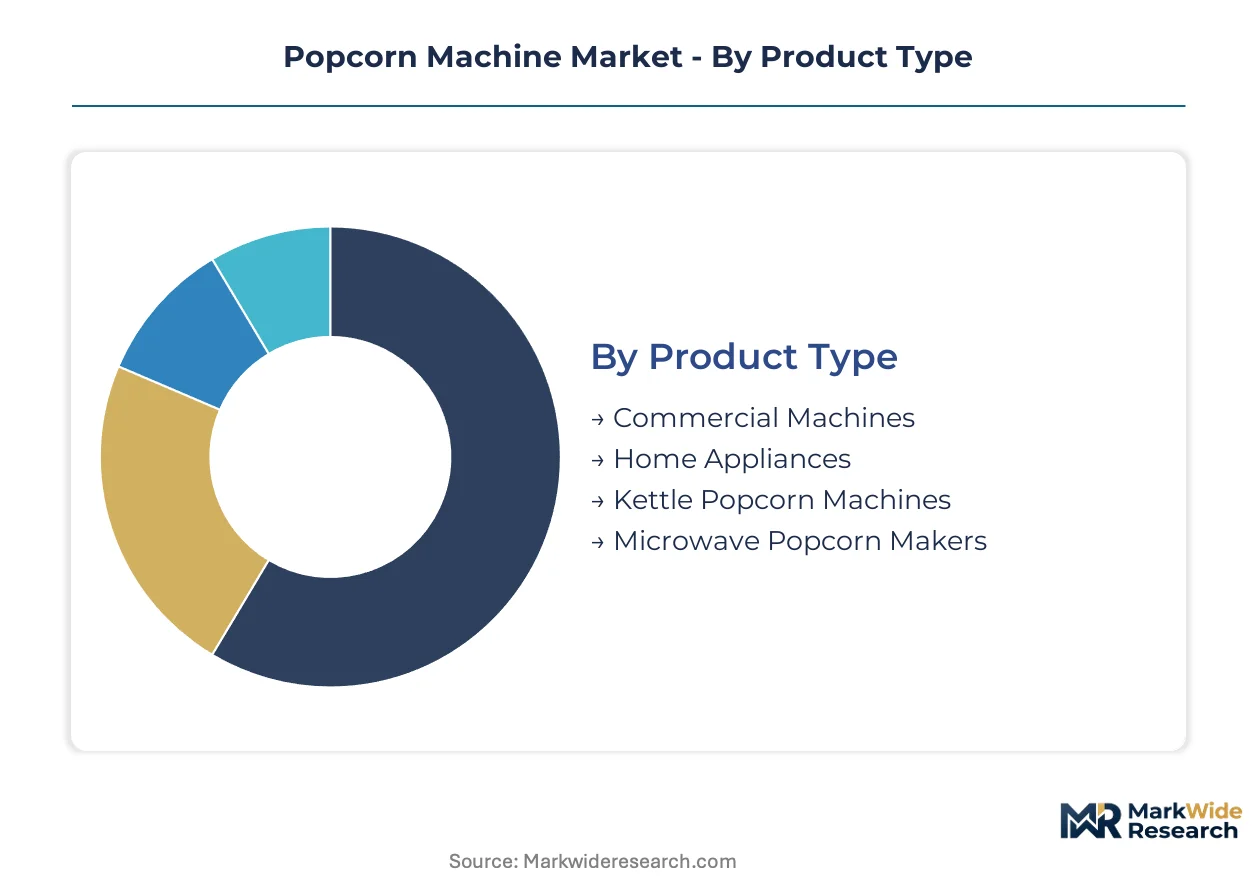
Popcorn machine procurement patterns diverge sharply between high-volume commercial operators and experiential residential buyers. Equipment specifications, distribution pathways, and application contexts create distinct margin pools that manufacturers must navigate separately.
Product Type:
Volume throughput and durability requirements drive buyer selection across installation contexts.
- Commercial Machines:Stainless steel kettles with motorized stirring mechanisms process 4 to 32 ounce batches for cinema chains and stadium concessionaires. Theater operators in the United States specify these units for lobby retrofit projects that consolidate vendor relationships around integrated equipment bundles.
- Home Appliances:Compact countertop units distribute through mass retail channels to residential buyers seeking experiential food preparation. Germany's LFGB migration limits favor stainless-steel construction in premium residential tiers where health-conscious positioning commands price premiums.
- Kettle Popcorn Machines:Theatrical visual appeal supports specialty retail and festival catering deployments with premium positioning.
- Microwave Popcorn Makers:Convenience-focused residential buyers favor these units for minimal cleanup and storage footprint.
Commercial machines lead on scale; home appliances lead on momentum.
End User:
Operational intensity and labor availability shape equipment specifications across buyer categories.
- Theaters:Cinema chains deploy self-serve concession formats that reduce labor costs during peak attendance windows. AMC, Cinemark, and Regal in the United States have standardized around integrated equipment packages covering popping, warming, and dispensing functions.
- Households:Residential snacking habits shift toward experiential food preparation, expanding demand for countertop units with retro styling and compact footprints.
- Restaurants:Casual dining operators incorporate kettle-style units for tableside or lobby theater experiences that differentiate service offerings.
- Concession Stands:Mobile food operations and seasonal venues prioritize portability and rapid batch cycling over permanent installation durability.
Theaters dominate installed base; households drive expansion velocity.
Distribution Channel:
Buyer sophistication and purchase frequency determine channel economics for equipment vendors.
- Direct Sales:Theater chains and stadium operators negotiate single-source contracts covering machines, warming cabinets, and dispensing stations. This channel captures the highest-value transactions through consolidated procurement relationships.
- Online Retailers:Residential buyers research specifications and compare countertop alternatives through e-commerce platforms with rapid delivery expectations.
- Specialty Stores:Gift and specialty segments leverage retro-styled designs for differentiated merchandising in physical retail environments.
- Supermarkets:Mass retail placement reaches price-sensitive residential buyers seeking immediate availability without shipping delays.
Direct sales anchor revenue concentration; online retailers capture volume growth.
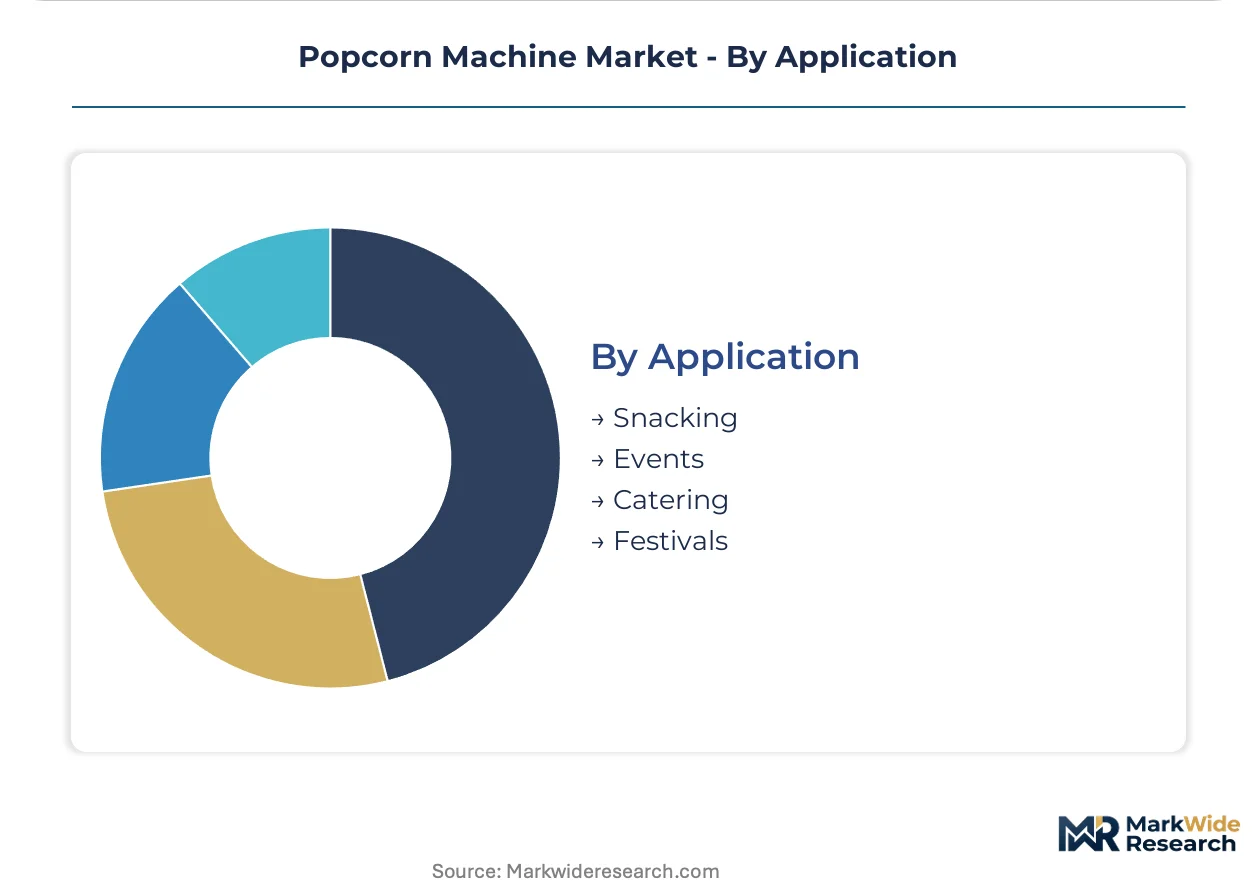
Application:
Usage context determines equipment mobility requirements and batch frequency specifications.
- Snacking:Daily consumption in residential and commercial settings demands reliable temperature control and consistent output quality.
- Events:Temporary installations require rapid setup and breakdown capabilities with minimal utility connections.
- Catering:Mobile food operations deploy kettle-style units for theatrical visual appeal that supports premium pricing at private functions.
- Festivals:Outdoor venues specify gas-powered or high-capacity electric units for continuous operation without grid dependency.
Snacking applications dominate unit economics; festival deployments expand addressable occasions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The popcorn machine industry traces its commercial origins to early 20th-century American street vendors and cinema concessions, with manufacturing expertise later dispersing to Germany and China as theater infrastructure globalized. Equipment specifications now diverge sharply across regulatory environments and concession formats.
United States
AMC, Cinemark, and Regal operate over 20,000 combined screens and are retrofitting lobbies with self-serve concession stations that integrate popping, warming, and dispensing functions. The FDA's 21 CFR food-contact surface regulations are accelerating replacement cycles for aging aluminum-kettle units in commercial kitchens. Chicago and Los Angeles anchor the domestic manufacturing base where Gold Medal Products Co. maintains deep specialization in high-volume kettle systems.
Germany
Cineplex Deutschland and other operators are specifying induction-heating kettles for new-build locations to satisfy Ecodesign Directive energy-efficiency mandates. The LFGB framework enforces strict material migration limits that favor stainless-steel construction across both commercial and premium residential tiers. Bavaria's industrial machinery cluster hosts precision fabricators serving theater equipment supply chains.
China
PVR-Inox and Cinepolis India source equipment from Chinese manufacturers as multiplex expansion accelerates in Tier-2 cities with underdeveloped concession infrastructure. SAMR enforces GB standards for electrical safety and energy efficiency that extend certification lead times for imported commercial equipment. The Yangtze River Delta concentrates domestic production capacity for small appliance exports.
India
PVR-Inox and Cinepolis India are adding screens in Tier-2 cities where concession infrastructure remains underdeveloped and labor costs favor semi-automated equipment over full self-serve formats. The FSSAI regulates food-contact materials for commercial kitchen equipment with increasing stringency. Mumbai and Delhi-NCR cluster the domestic cinema exhibition headquarters that drive procurement specifications.
Japan
Toho Cinemas and other operators emphasize compact, high-efficiency units for dense urban theater locations where space constraints dominate equipment selection. METI energy-efficiency standards shape domestic appliance specifications and influence export-oriented manufacturing. The Kanto region around Tokyo concentrates precision engineering capabilities for specialized concession equipment.
Popcorn Machine Market Competitive Landscape
The competitive structure tilts toward specialization-driven differentiation rather than scale consolidation. Equipment vendors cluster into three tiers: high-volume commercial specialists serving theater chains, mass-market residential appliance manufacturers, and niche retro-styled gift segment players. Strategic moves center on concession bundling contracts and induction-heating technology licensing rather than horizontal mergers.
Among North American equipment specialists, Gold Medal Products Co. exemplifies the commercial-segment archetype through deep kettle-system expertise, while Hamilton Beach Brands occupies the mass-market residential tier with compact countertop distribution. Nostalgia Products represents the specialty-gift positioning vector with retro-styled differentiation. These three anchors illustrate how vendor strategies diverge across procurement contexts rather than converging on common capabilities.
| Leading Market Players |
|---|
| Conair Corporation |
| Hamilton Beach Brands |
| Gold Medal Products Co. |
| The Legacy Companies |
| Wabash Valley Farms |
| National Presto Industries |
| Nostalgia Products |
| Nordic Ware |
| Great Northern Popcorn Company |
| Others |
Value Network & Pricing Analysis
Captive stainless steel sourcing from Indonesian nickel processors anchors both supply security and margin stability for kettle manufacturers serving theater chains. This backward integration into raw material streams insulates high-volume producers from commodity volatility while compressing procurement costs for 304-grade alloy inputs essential to FDA-compliant food-contact surfaces.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates induction-heating commercial units from legacy gas systems and entry-level home appliances. Price differentiation rests on certification tier—UL-listed commercial equipment commands substantial premiums over uncertified residential imports—and volume scale, with theater chain bundling contracts securing double-digit discounts. Cost compression in the home appliance tier is intensifying because mass retail channels are prioritizing private-label air poppers. Household buyers exhibit highest price sensitivity, while cinema operators prioritize total cost of ownership over upfront equipment spend.
Supply Chain Analysis
Ocean freight volatility between Yangtze River Delta ports and Los Angeles/Long Beach corridors is reshaping inventory strategies for commercial equipment distributors. Manufacturing concentrates in China, Germany, and the United States, with precision kettle fabrication anchored in Bavaria's industrial machinery cluster. Supply chains draw from Indonesian nickel, Taiwanese electrical components, and domestic stainless steel from Chicago-area mills. Single-source vulnerability concentrates in nickel sulfate processing, where Indonesian refining capacity dominates global supply. Distribution runs through direct sales teams for theater chains, mass retail for residential units, and specialty distributors for festival catering deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through induction-heating technology adoption, where energy efficiency certifications unlock premium positioning and reduce operating costs for theater operators.
For Market Incumbents: Deepen concession bundling relationships by integrating dispensing station APIs with legacy POS platforms at AMC, Cinemark, and Regal locations. Invest in captive stainless steel sourcing through Indonesian nickel partnerships to defend against commodity volatility threatening kettle margins. Certification investment in Ecodesign Directive compliance for European theater deployments represents a critical defensive lever against emerging induction-heating specialists. For New Entrants and Emerging Players: Tier-2 city multiplex operators in India present an underserved buyer archetype with underdeveloped concession infrastructure and preference for semi-automated equipment over full self-serve formats. Festival catering circuits and mobile food operations offer penetrable white-space with theatrical kettle-style units priced below commercial theater specifications. A go-to-market angle emphasizing rapid deployment and minimal utility connections differentiates against established theater equipment vendors. For Investors and Strategic Acquirers: Roll-up economics work for precision kettle fabricators because the vendor base fragments across regional machinery clusters with limited scale advantages. Mid-cap specialists with captive stainless steel sourcing and Ecodesign-ready induction technology represent priority acquisition targets. The signal to watch is theater chain standardization announcements—consolidated procurement decisions around single-source vendors indicate inflection toward bundled equipment contracts that favor scaled suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Induction-Heating Technology Licensing | German theater operators specify these units for Ecodesign Directive compliance. |
| Concession Bundling Contracts | AMC and Regal consolidate vendor relationships around integrated equipment packages. |
| Backward Integration into Nickel Sourcing | Indonesian refining partnerships insulate margins from stainless steel volatility. |
| API Integration with Legacy POS Systems | Theater operators require compatibility between dispensing stations and ticketing platforms. |
| Festival Catering Channel Expansion | Kettle-style units penetrate mobile food operations beyond traditional theater settings. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market's theater operators and equipment distributors. Primary interviews with cinema concession directors, commercial kitchen procurement managers, festival catering operators, and stainless steel kettle fabricators were combined with secondary validation from FDA 21 CFR filings, SAMR GB standard documentation, and LFGB material migration test reports. Bottom-up equipment shipment data triangulated against top-down theater construction permits and multiplex expansion announcements.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects and technology substitution patterns. Segmentation dimensions modeled include product type, end user category, distribution channel, and application context, with additional granularity on heating technology—induction versus gas versus conventional electric. CAGRs were derived from installed base replacement cycles, new screen additions, and residential penetration trends. Industry-specific forecast inputs incorporated energy-efficiency mandate timelines and REACH substance restriction sunset dates.
Inputs from theater chain procurement directors and equipment distributor sales teams were available through the study window; gaps in Tier-2 city multiplex construction timelines introduce uncertainty bands around India demand projections. Forecasts reflect assumptions regarding concession format adoption rates and regulatory enforcement consistency across jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Food Thermos Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Food Display Cabinet Market