
 Exterior Wall System Market | 2026-2036
Exterior Wall System Market Size, Share, and Industry Trends Forecast 2026-2036
Exterior Wall System Market Analysis
LEED v4.1 and BREEAM certification cycles is bifurcating the competitive landscape into qualified premium suppliers and commodity-grade vendors. Saint-Gobain leverages its integrated glass and insulation portfolio to control specification channels across European commercial projects. Owens Corning anchors North American residential demand through fiberglass-backed siding systems and regional manufacturing density. Alcoa Corporation competes on lightweight aluminum composite solutions for high-rise applications where wind-load engineering dominates procurement criteria.
An exterior wall system comprises the integrated assembly of cladding, insulation, air barriers, and structural substrates that manage thermal transfer, moisture intrusion, and structural loads for buildings. Fiber cement panels incorporate cellulose fiber reinforcement with Portland cement matrices to achieve fire ratings and dimensional stability in humid climates. Brick and stone cladding retains specification share in institutional and heritage-sensitive projects where aesthetic permanence justifies higher installed cost. Panelized and prefabricated installation methods are gaining fastest in multi-family residential towers where labor scarcity on job sites compresses construction schedules. Vinyl siding dominates single-family replacement demand in cost-sensitive North American markets despite thermal expansion limitations.
The EU Green Deal's embodied carbon thresholds and the EPA's ENERGY STAR certification requirements are redirecting material procurement toward lower-carbon substrates and higher-performance insulation assemblies. BREEAM and LEED compliance costs are filtering smaller contractors from premium commercial bidding pools. China's MIIT building energy efficiency standards and the dual carbon policy framework are accelerating composite and recycled material sourcing mandates for new urban construction. Stakeholders must monitor how tightening carbon accounting rules reshape supplier qualification criteria and retrofit opportunity sizing across their served geographies.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing material substitution timelines, forcing specifiers to trade traditional masonry for lower-carbon composites and engineered panels across commercial construction portfolios.
Growth Catalysts
- MIIT building energy efficiency standards:China's dual carbon policy framework mandates composite and recycled material sourcing for new urban construction, accelerating prefabricated facade adoption in tier-one cities.
- Commercial high-rise construction:Asia-Pacific cladding demand concentrates in vertical towers where wind-load engineering and rapid assembly requirements favor panelized systems over traditional masonry.
- LEED v4.1 certification cycles:Premium commercial bidding pools now require qualified suppliers, bifurcating the competitive landscape and filtering commodity-grade vendors from specification channels.
Market Restraints
- Aluminum price volatility:Lightweight composite cladding systems face input cost pressure from energy-intensive smelting operations concentrated in high-electricity-cost jurisdictions.
- Portland cement carbon intensity:Fiber cement panels carry embodied carbon penalties that complicate compliance with tightening EU Green Deal thresholds for institutional projects.
- Vinyl thermal expansion:Single-family replacement demand in North American markets faces technical limitations that restrict specification in extreme climate zones despite cost advantages.
Strategic Opportunities
- Prefabricated installation methods:Labor scarcity on multi-family residential job sites creates white space for panelized systems that compress construction schedules in dense urban corridors.
- Retrofit opportunity sizing:Existing building stock across European commercial portfolios requires facade upgrades to meet ENERGY STAR and BREEAM compliance, opening specification windows for integrated insulation-cladding assemblies.
- Recycled content mandates:China's MIIT standards and EU circular economy frameworks create procurement pull for reclaimed aluminum and glass in composite panel manufacturing.
Industry Challenges
- Wind-load engineering talent scarcity:High-rise facade specification requires specialized structural calculation capabilities that concentrate among limited consultant pools in major metropolitan design centers.
- Certification timeline compression:LEED and BREEAM compliance documentation demands extend pre-construction phases, squeezing contractor cash conversion cycles on fixed-price commercial contracts.
- Legacy system integration:Panelized retrofits must interface with existing air barrier and moisture management substrates that lack standardized connection details across building vintages.
Report Scope
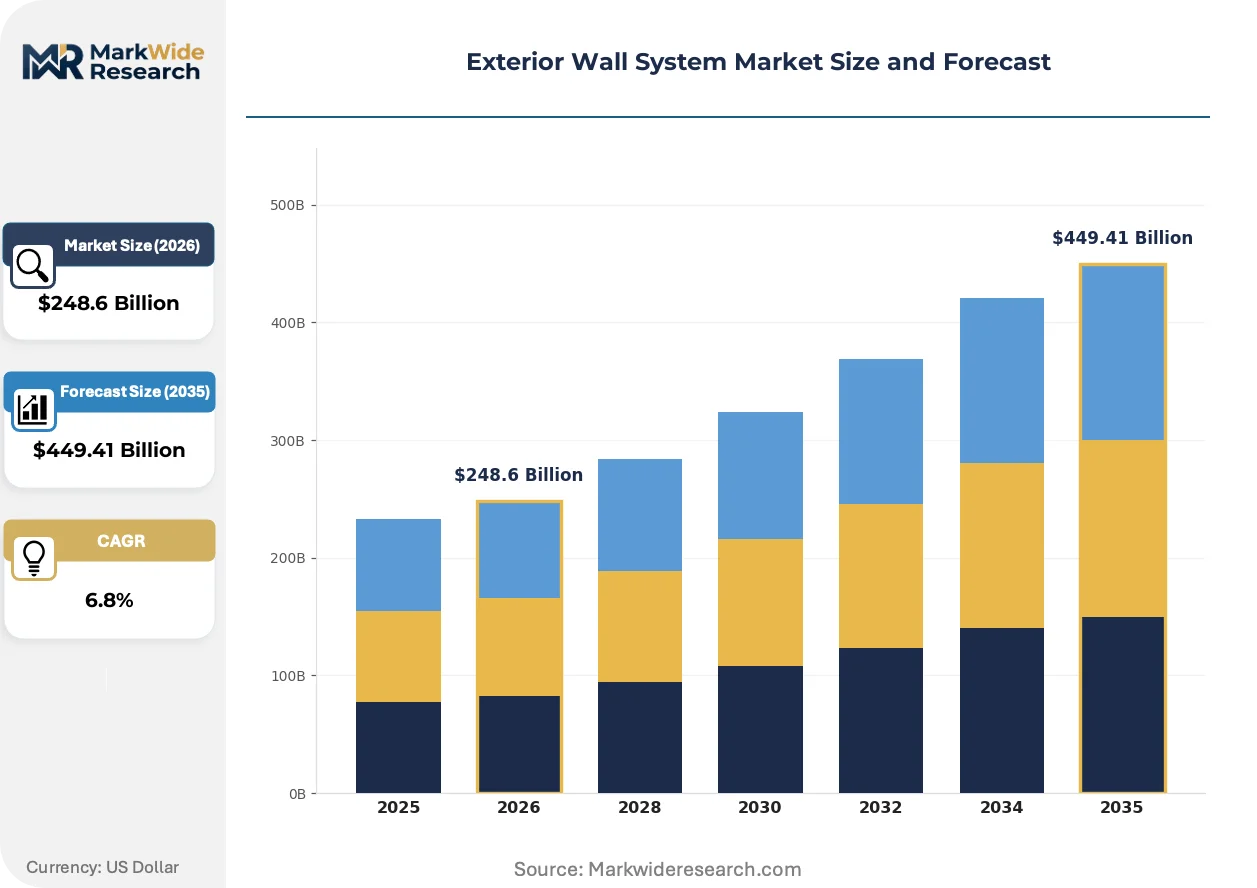
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exterior Wall System Market |
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $449.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brick, Stone, Vinyl Siding, Fiber Cement Installation Method: Retrofitting, New Construction, Panelized System, Prefabricated Material Source: Manufactured, Natural, Recycled, Composite End User: Residential, Commercial, Institutional, Industrial |
| Companies Covered | Etex Group, Alcoa Corporation, Saint-Gobain, Sika, 3A Composites, Asahi Glass (AGC), PPG Industries, Owens Corning, Nippon Sheet Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exterior Wall System Market Emerging Trajectories
Digital fabrication and material science advances are collapsing traditional trade boundaries between cladding manufacturers, insulation suppliers, and structural engineers. Specification power is migrating toward integrated system providers.
Cross-laminated timber facade panels with integrated cellulose fiber cement facing layers are decomposing the conventional separation between structural substrate and weather-resistant cladding. Multi-family residential developers in Scandinavian markets specify these hybrid assemblies for mid-rise projects where carbon accounting drives material selection. The technology is decomposing established procurement patterns that treated cladding and structure as discrete subcontractor scopes.
REACH chemical restriction expansions and the EU F-Gas Regulation phase-down are eliminating high-global-warming-potential blowing agents from rigid insulation cores used in composite panel manufacturing. European facade suppliers reformulate polyurethane and polystyrene formulations to maintain thermal performance under tightened environmental safety profiles. Commercial specification in Germany, France, and the Netherlands now requires third-party verified low-GWP insulation credentials as a baseline qualification threshold.
Developer procurement teams increasingly bundle cladding, insulation, and air barrier specification into single-source integrated system contracts rather than discrete material purchases. General contractors in China's tier-one cities favor this consolidation to reduce interface risk and accelerate envelope completion schedules. The shift is most visible in Shanghai and Shenzhen commercial tower projects where foreign design consultants specify European or North American integrated facade systems over fragmented local supply chains.
Exterior Wall System Market Segmentation
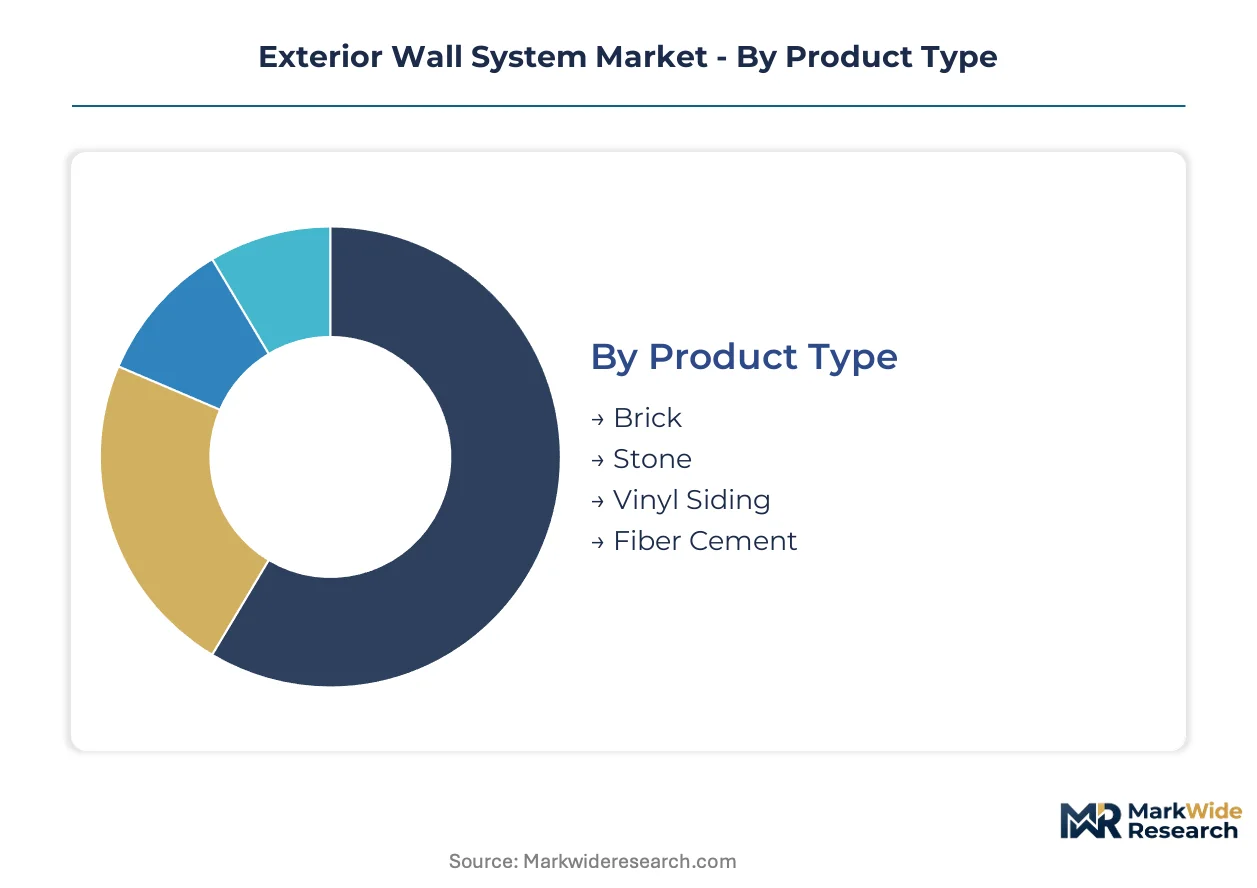
Exterior wall system procurement channels diverge sharply by segment. Residential replacement flows through distributor networks, while commercial towers demand direct manufacturer engagement for wind-load engineering support.
Product Type:
Channel mix varies dramatically: fiber cement and vinyl siding dominate big-box retail and regional distributor networks, while brick and stone specification travels through architect-led channels with masonry contractor fulfillment.
- Fiber Cement:Cellulose-reinforced Portland cement matrices achieve Class A fire ratings and dimensional stability in humid coastal zones. Specification concentrates in Southeast US residential construction where termite resistance and hurricane impact ratings drive substitution away from wood siding. Labor scarcity on job sites accelerates demand for lighter panel formats that reduce crew fatigue.
- Vinyl Siding:PVC resin formulations with UV stabilizers dominate single-family replacement demand through cost-sensitive retail channels. Thermal expansion coefficients restrict specification in extreme desert and northern climate zones despite installed cost advantages over fiber cement. Color fade warranties now extend to 50 years on premium product lines.
- Brick:Fired clay masonry retains institutional and heritage-sensitive specification where aesthetic permanence justifies premium installed costs. Clay sourcing regionalization affects embodied carbon calculations under tightening EU Green Deal thresholds.
- Stone:Natural granite, limestone, and sandstone cladding commands luxury residential and cultural institution budgets. Quarry proximity to project sites increasingly influences procurement decisions as transportation emissions enter carbon accounting frameworks.
By volume, vinyl siding leads. By growth pace, fiber cement is ahead.
Installation Method:
Cost tier stratification separates field-applied systems from factory-integrated solutions. Retrofitting and new construction occupy economy and standard tiers, while panelized and prefabricated methods command premium pricing for schedule compression value.
- Panelized System:Factory-assembled wall sections with integrated insulation and air barriers compress on-site envelope completion from weeks to days. Demand concentrates in multi-family residential towers across China's tier-one cities where labor scarcity and schedule penalties reshape procurement economics. General contractors in Shanghai and Shenzhen specify European-integrated systems over fragmented local supply chains.
- Prefabricated:Complete volumetric modules with finished cladding arrive site-ready for crane installation. Vertical tower projects in Singapore and Hong Kong adopt these systems where site logistics constraints and skilled labor shortages intersect. Quality control consistency reduces warranty callbacks compared to field-built alternatives.
- New Construction:Traditional stick-built or masonry installation remains standard for custom single-family and low-rise commercial projects. Trade coordination complexity extends schedules but preserves design flexibility for architect-driven projects.
- Retrofitting:Over-cladding existing substrates with insulated panel systems addresses energy upgrade mandates across European commercial building stock. Interface detailing with legacy air barriers creates technical risk that filters contractor bidding pools.
By project count, new construction leads. By margin expansion, prefabricated is climbing the fastest.
Material Source:
Customer type alignment maps material sourcing to project sustainability commitments. Natural materials serve heritage and luxury segments, while recycled and composite inputs satisfy institutional procurement policies and green building certification requirements.
- Composite:Engineered combinations of aluminum, glass fiber, and mineral fillers achieve strength-to-weight ratios critical for high-rise wind-load engineering. China's MIIT building energy efficiency standards mandate composite content in new urban construction, accelerating supplier qualification in tier-one cities. Aluminum price volatility from energy-intensive smelting operations compresses margin stability.
- Recycled:Reclaimed aluminum and glass content in panel manufacturing responds to EU circular economy frameworks and Chinese dual carbon policy requirements. Third-party verification chains add procurement documentation burden that smaller contractors struggle to satisfy.
- Manufactured:Industrial-processed materials including fiber cement and vinyl dominate volume production through scale economies and specification standardization. Quality consistency supports long warranty terms that reduce developer risk.
- Natural:Quarry-sourced stone and clay-fired brick serve aesthetic-driven segments where material authenticity commands price premiums. Regional sourcing radius constraints limit supply chain flexibility compared to manufactured alternatives.
By tonnage, manufactured materials lead. By procurement policy tailwinds, recycled inputs are gaining share fastest.
End User:
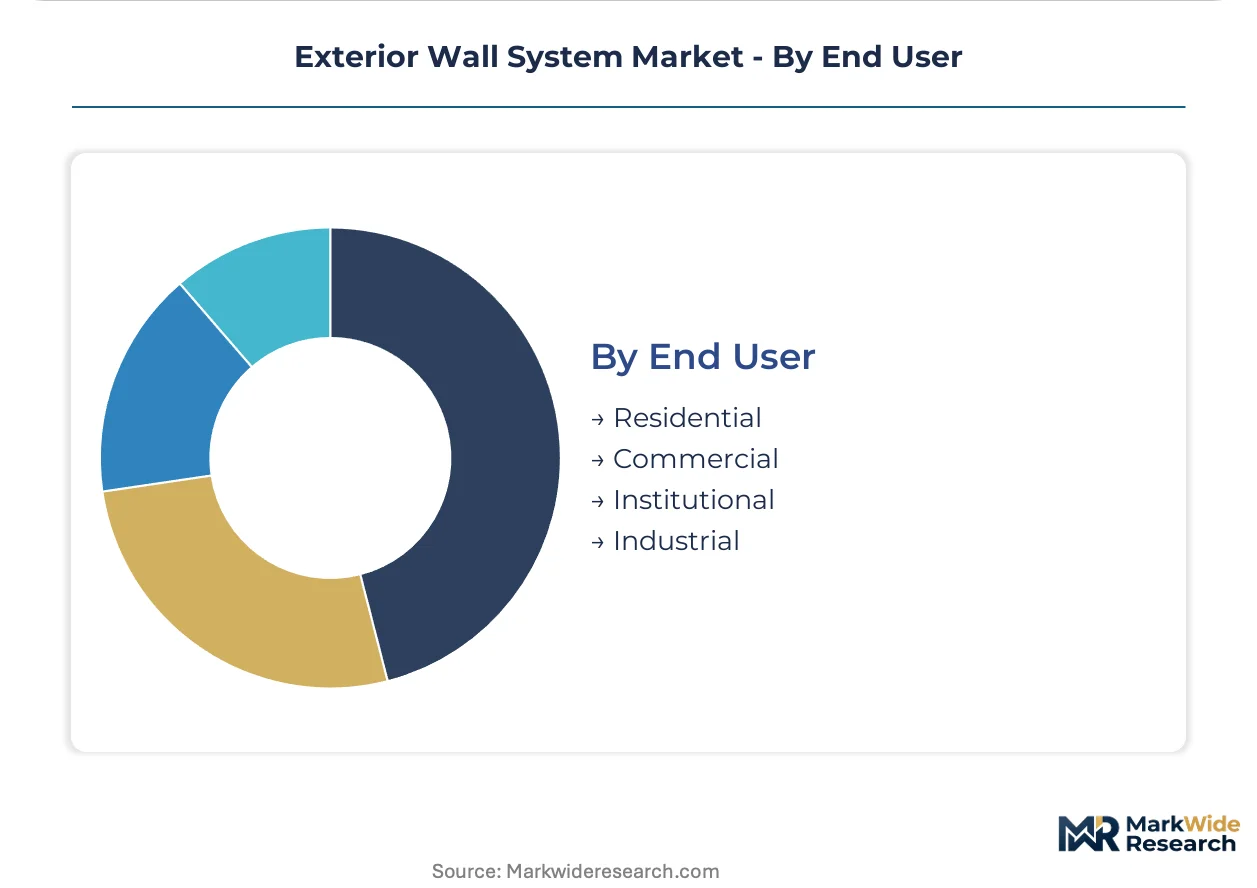
Application requirements reshape product mix and channel strategy. Residential and commercial segments drive volume, while institutional and industrial end users impose specialized performance specifications that filter supplier pools.
- Commercial:High-rise towers and office campuses demand integrated facade systems combining cladding, insulation, and air barriers under single-source contracts. LEED v4.1 and BREEAM certification requirements bifurcate bidding pools between qualified premium suppliers and excluded commodity vendors. Wind-load engineering and rapid assembly specifications favor panelized systems over traditional masonry in Asia-Pacific vertical construction.
- Residential:Single-family replacement and multi-family new construction split between cost-optimized vinyl siding and performance-upgraded fiber cement. Regional manufacturing density determines distributor availability and installed cost competitiveness.
- Institutional:Schools, hospitals, and government buildings combine extended durability requirements with heritage sensitivity that preserves brick and stone specification share. EU Green Deal embodied carbon thresholds complicate material selection for public procurement frameworks.
- Industrial:Warehousing and manufacturing facilities prioritize weather resistance and low maintenance over aesthetic considerations. Metal panel systems with reflective coatings address thermal performance requirements in climate-extreme zones.
By square footage, commercial leads. By specification complexity, institutional is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's embodied carbon thresholds and China's dual carbon policy framework are redirecting procurement toward lower-carbon substrates across major construction markets. National building codes and energy efficiency mandates reshape supplier qualification criteria and retrofit opportunity sizing.
China
Commercial high-rise construction in Shanghai and Shenzhen drives prefabricated facade adoption. MIIT building energy efficiency standards mandate composite and recycled material sourcing for new urban construction. Tier-one cities accelerate panelized system specification where labor scarcity compresses construction schedules.
United States
Single-family replacement demand concentrates in cost-sensitive markets through distributor networks. EPA ENERGY STAR certification requirements redirect material procurement toward higher-performance insulation assemblies. Southeast residential construction favors fiber cement specification where hurricane impact ratings drive substitution from wood siding.
Germany
REACH chemical restrictions and the EU F-Gas Regulation phase-down eliminate high-GWP blowing agents from rigid insulation cores. BREEAM compliance documentation filters smaller contractors from premium commercial bidding pools. Industrial clusters in North Rhine-Westphalia reformulate polyurethane formulations for low-credential thermal performance.
Japan
METI building energy standards accelerate composite panel adoption in urban commercial towers. Wind-load engineering requirements concentrate specification power among integrated system providers. Tokyo and Osaka metropolitan projects favor factory-assembled wall sections that reduce on-site envelope completion timelines.
United Arab Emirates
High-rise vertical construction in Dubai and Abu Dhabi demands lightweight aluminum composite solutions where wind-load engineering dominates procurement criteria. Extreme climate zones restrict specification of thermally limited materials despite cost advantages. Developer procurement teams increasingly bundle cladding and insulation into single-source contracts.
Exterior Wall System Market Vendor Landscape
Player mix skews toward integrated material conglomerates with cross-portfolio specification control. The vendor base concentrates among firms controlling glass, insulation, and cladding production simultaneously. Two strategic archetypes dominate: diversified building material conglomerates leveraging channel integration, and specialized composite panel fabricators competing on lightweight engineering. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure regional manufacturing density.
Within the conglomerate tier, Saint-Gobain and Owens Corning occupy positions anchored by integrated glass and insulation portfolios. Alcoa Corporation exemplifies the lightweight engineering specialist archetype, competing on aluminum composite solutions for high-rise applications. These three firms represent contrasting pathways to specification channel control across commercial and residential construction segments.
| Leading Market Players |
|---|
| Etex Group |
| Alcoa Corporation |
| Saint-Gobain |
| Sika |
| 3A Composites |
| Asahi Glass (AGC) |
| PPG Industries |
| Owens Corning |
| Nippon Sheet Glass |
| Others |
Supply Flow & Price Mechanics
Aluminum substitution for Portland cement in composite panel formulations simultaneously shifts supply geography toward energy-intensive smelting regions and compresses margin stability for facade manufacturers exposed to electricity price volatility.
Pricing Analysis
Certification level creates the primary spread across BREEAM and LEED qualification tiers, separating premium integrated system providers from commodity-grade vendors filtered from commercial bidding pools. Three-tier pricing structure across premium, standard, and economy levels reflects specification complexity, wind-load engineering support, and after-sales warranty bundling. Cost compression in standard-tier fiber cement runs through Portland cement carbon penalties under tightening EU Green Deal thresholds. Single-family replacement demand through North American distributor networks exhibits highest price sensitivity, while commercial high-rise procurement in Asia-Pacific prioritizes schedule compression value over unit cost.
Supply Chain Analysis
Bauxite refining capacity concentrated in Guinea and Australia anchors primary aluminum feedstock for lightweight composite cladding systems. Manufacturing draws from energy-intensive smelting operations in China, Russia, and Canada, with rigid insulation cores sourcing polyurethane formulations from German and Dutch chemical clusters. Single-source vulnerability concentrates in high-purity aluminum supply for wind-load-engineered high-rise applications. Distribution runs through specification-channel control by integrated material conglomerates holding glass, insulation, and cladding portfolios simultaneously.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefabricated facade adoption in China's tier-one cities signals early-cycle expansion, with labor scarcity on dense urban job sites accelerating penetration beyond traditional stick-built alternatives.
For Market Incumbents: Fortify specification-channel control through captive insulation production and direct architect engagement, countering emerging composite panel fabricators from South Korea and Japan. Backward integration into low-GWP blowing agent formulations addresses REACH chemical restriction phase-downs before compliance deadlines filter smaller competitors. Prioritize wind-load engineering talent acquisition in Shanghai and Tokyo design centers where consultant scarcity concentrates procurement power.
For New Entrants and Emerging Players: BREEAM certification fast-track through third-party verified low-credential insulation credentials opens specification windows in German and Dutch commercial markets where incumbent qualification filters create bidding pool gaps. Target retrofit opportunity sizing across European commercial building stock requiring facade upgrades for ENERGY STAR compliance. Pursue panelized system partnerships with multi-family residential developers in Shenzhen and Singapore where labor scarcity compresses construction schedules.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated system providers with cross-portfolio specification control over fragmented component suppliers. Long-term viability centers on facade-as-a-service business models bundling installation, energy performance guarantees, and circular material recovery. Monitor aluminum price volatility and EU carbon border adjustment implementation as inflection indicators for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Low-Carbon Aluminum | Secures feedstock for EU Green Deal-compliant composite panels amid smelting energy cost volatility. |
| Prefabricated Installation Method Partnership | Compresses envelope completion timelines for Shanghai and Shenzhen commercial tower developers facing labor scarcity. |
| Recycled Content Certification Program | Qualifies suppliers for China's MIIT mandates and EU circular economy procurement frameworks simultaneously. |
| Wind-Load Engineering Talent Acquisition | Concentrates specification power in Tokyo and Osaka where consultant scarcity dominates high-rise procurement. |
| Retrofit System Integration Platform | Addresses European commercial building stock upgrades for BREEAM compliance through over-cladding solutions. |
Methodological Framework
Cross-validation between primary interviews with facade system manufacturers, wind-load engineering consultants, and multi-family residential developers anchors the qualitative findings against secondary data from MIIT building energy efficiency standards, EU ETS carbon price registries, and BREEAM certification databases. Bottom-up triangulation aggregates project-level specification data across Shanghai, Shenzhen, and Singapore commercial towers, while top-down validation incorporates customs trade flows for aluminum composite panel imports.
Sensitivity analysis across the projection horizon tests demand elasticity to aluminum price shocks, labor cost inflation in China's tier-one cities, and embodied carbon threshold tightening under EU Green Deal implementation. Segmentation dimensions model product type, installation method, material source, and end-user application, with regional regulatory cluster effects layered across national building code variations. CAGRs derive from installed base growth in prefabricated systems and retrofit penetration rates in European commercial stock.
Underlying assumptions cover continued MIIT mandate enforcement, sustained EU carbon border adjustment trajectory, and stable wind-load engineering consultant supply, with deviation risk concentrated in aluminum smelting energy cost volatility and REACH chemical restriction expansion timelines. Practitioners should keep alternative scenarios live as dual carbon policy implementation pace and circular economy verification chain maturity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Masonry Sealers Market