

Residential Non-metal Electrical Conduit Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Non-metal Electrical Conduit Market Insights
UL 651 certification for Schedule 40 and Schedule 80 PVC conduit is bifurcating the competitive landscape into qualified incumbents and cost-challenged entrants. Atkore leverages its integrated PVC resin-to-conduit manufacturing footprint across the southeastern United States to sustain price competitiveness in standard rigid offerings. Champion Fiberglass differentiates through specialized fiberglass conduit formulations targeting coastal and corrosive environments where metallic alternatives fail prematurely.
Residential non-metal electrical conduit comprises thermoplastic and composite piping systems engineered to protect and route electrical wiring in dwelling units, with PVC formulations typically extruded to NEMA TC-2 wall thickness tolerances and HDPE variants meeting ASTM F2160 density specifications for direct-burial applications. PVC conduit occupies the mature volume core of the market, while flexible non-metallic conduit represents the fastest-expanding segment as electricians prioritize labor-saving installation in tight wall cavities and retrofit scenarios. Cable management applications within the application dimension command premium positioning as smart-home device proliferation requires dedicated low-voltage pathways separate from line-voltage circuits.
The National Electrical Code, enforced by local authorities having jurisdiction across U.S. municipalities, mandates wet-location ratings and sunlight-resistant jackets for outdoor residential conduit runs, directly shaping product specifications and inventory requirements. UL standards and NEMA performance protocols further constrain material formulations and dimensional consistency, creating compliance barriers that favor established testing investments. Stakeholders must monitor code cycle revisions and local amendment adoptions to anticipate shifts in permitted materials and installation methods before specification lock-in at the project design phase.
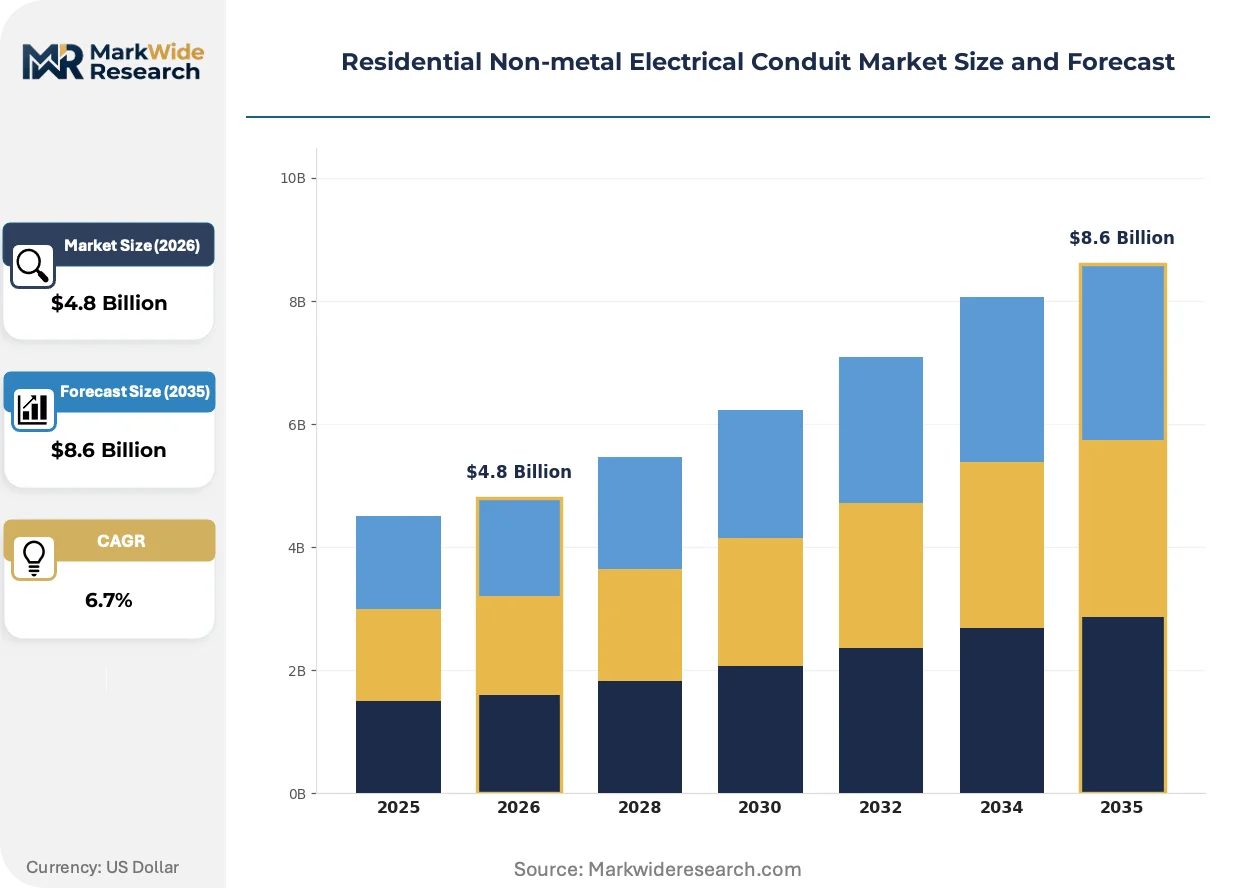
Market Dynamics
Single-family housing starts and smart-home retrofits are concentrating contractor procurement power, forcing conduit manufacturers to align inventory with volatile construction cycles and code-compliance deadlines rather than steady-state replacement demand.
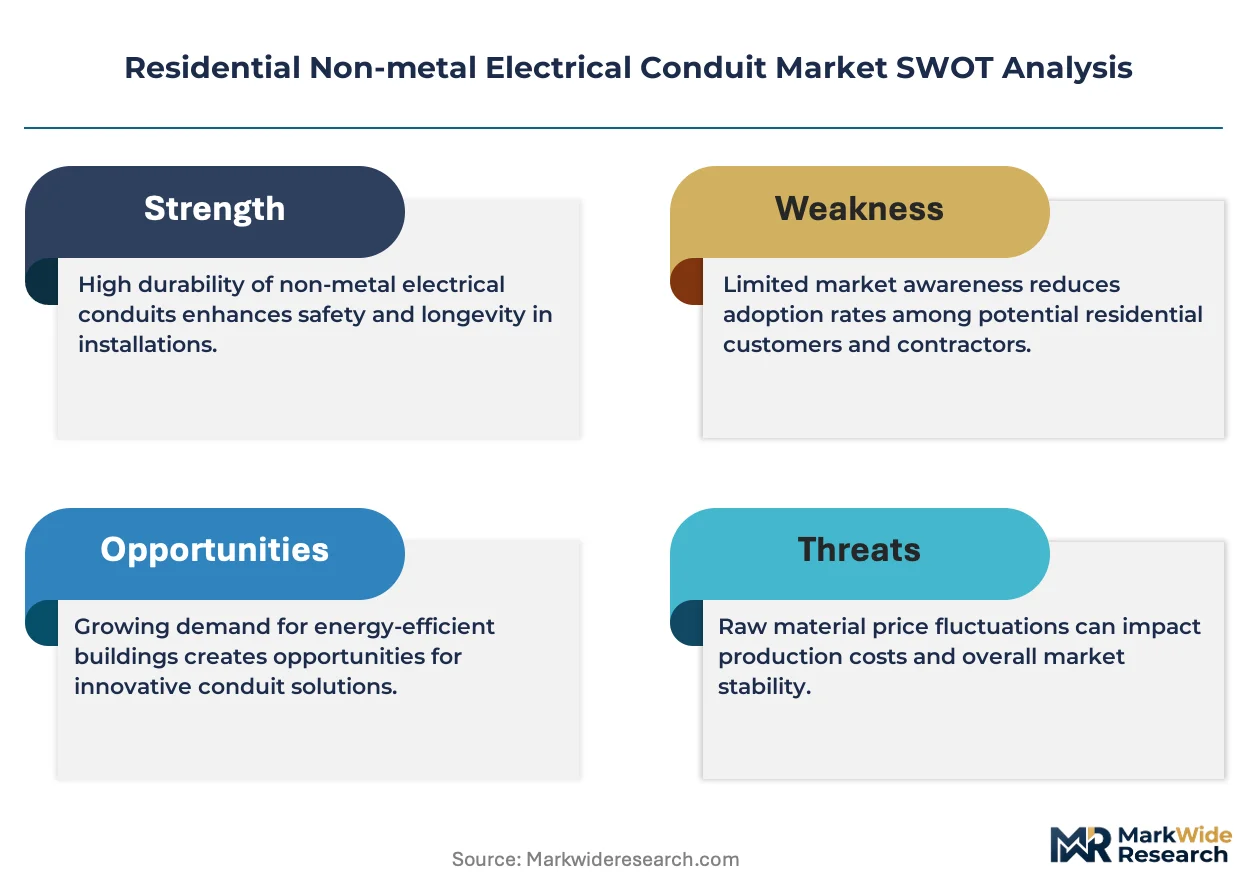
Growth Catalysts
- NEC wet-location mandates:Outdoor residential conduit runs now require sunlight-resistant jackets, expanding the addressable market for specialized PVC formulations.
- HDPE direct-burial adoption:Electricians in coastal subdivisions specify high-density polyethylene for underground feeder circuits to metallic corrosion.
- Smart-home device proliferation:Low-voltage pathway requirements separate from line-voltage circuits create dedicated cable management demand.
Market Restraints
- PVC resin price volatility:Feedstock cost swings compress margin stability for extrusion-dependent producers.
- Southeastern US supply concentration:Integrated resin-to-conduit manufacturing clusters create geographic risk exposure.
- Fiberglass substitution ceiling:Premium composite formulations face cost barriers in standard residential applications.
Strategic Opportunities
- Flexible conduit retrofit penetration:Tight wall cavity installations in aging housing stock favor labor-saving non-metallic solutions.
- NEMA TC-2 specification expansion:Thickness tolerance protocols for thermoplastic conduit create certification-based differentiation.
- Electrical contractor direct channels:Bypassing traditional distribution through jobsite delivery models captures specification influence.
Industry Challenges
- UL 651 certification timelines:Schedule 40 and Schedule 80 testing protocols delay new product introductions.
- Local authority jurisdiction fragmentation:Municipal code amendment adoptions create inventory complexity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Non-metal Electrical Conduit Market Trends and Innovations
Material science advances and installation efficiency pressures are restructuring competitive advantage around labor cost reduction and code-anticipating specification capture.
Cross-linked polyethylene formulations for high-temperature residential circuits is bifurcating the thermoplastic segment. Homebuilders in sun-belt states specify PEX-derived jacketing for attic runs. This technology is compressing standard PVC's share in premium thermal-stress applications.
ASTM F2160 density specifications for direct-burial HDPE are tightening across municipalities. Underground feeder installations now face stricter dimensional verification. Coastal electrical contractors are responding by stockpiling certified inventory ahead of enforcement windows.
Specification influence has migrated from distributor sales teams to jobsite electricians. Large residential contractors now mandate pre-approved conduit brands through master service agreements. This pattern is most visible in Arizona and Florida production homebuilding.
Residential Non-metal Electrical Conduit Market Segmentation
Segmentation in residential non-metal electrical conduit reveals how code compliance, installation labor economics, and end-user procurement power reshape competitive positioning. Manufacturers must align product portfolios with the divergent technical requirements of new construction versus retrofit applications.
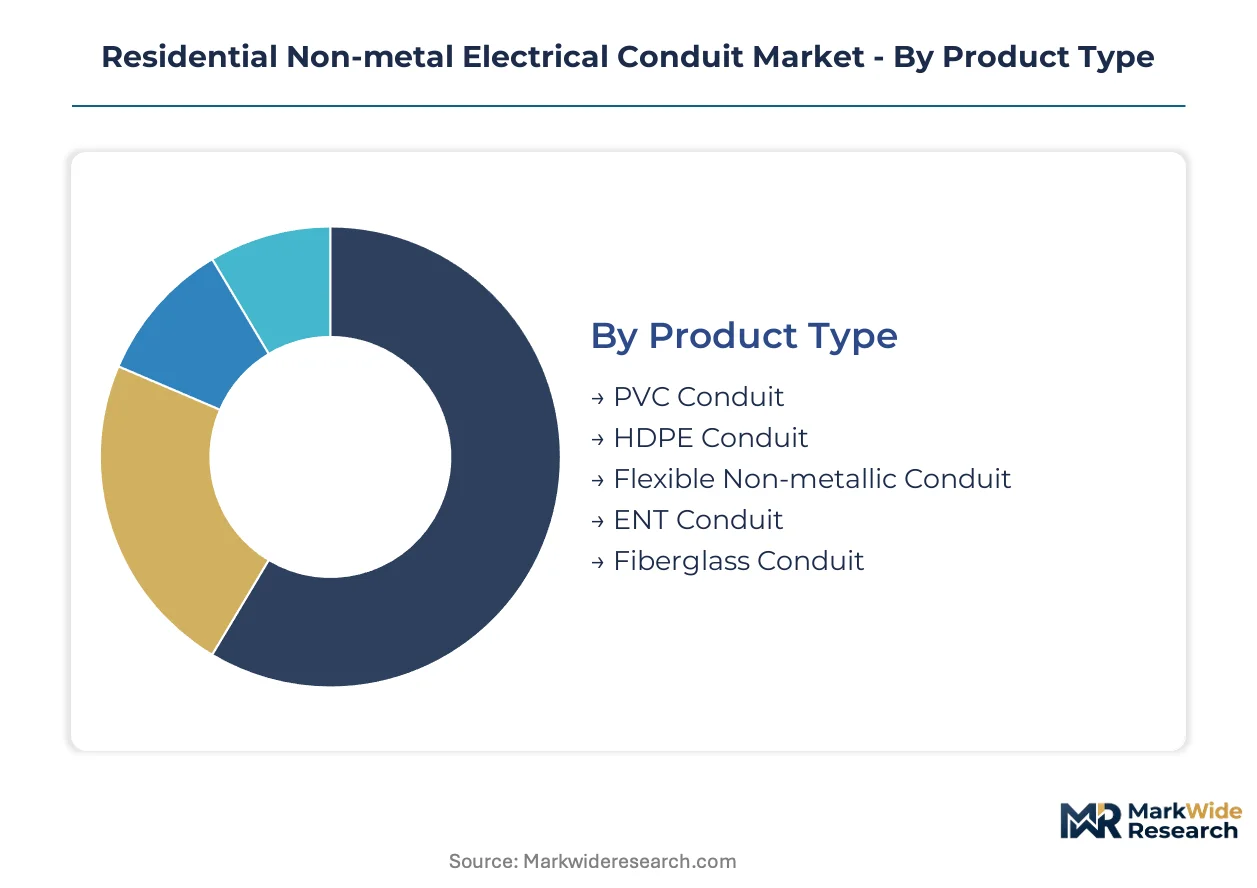
Product Type:
Premium margin pools concentrate in specialized formulations that solve corrosion or thermal-stress failures where standard PVC degrades.
- PVC Conduit:Extruded thermoplastic systems meeting UL 651 Schedule 40 and Schedule 80 specifications dominate volume procurement in standard residential wiring protection. Demand concentrates in southeastern U.S. production homebuilding where Atkore's integrated resin-to-conduit footprint sustains price competitiveness against cost-challenged entrants.
- Flexible Non-metallic Conduit:Corrugated thermoplastic jackets over helical wire reinforcement enable labor-saving pulls through tight wall cavities and existing structure retrofits. Electricians in Arizona and Florida production homebuilding specify this format through master service agreements that bypass traditional distribution channels.
- HDPE Conduit:High-density polyethylene formulations meeting ASTM F2160 density specifications for direct-burial feeder circuits in coastal subdivisions.
- ENT Conduit:Electrical non-metallic tubing with thin-wall construction for dry-location branch circuit protection in interior residential framing.
- Fiberglass Conduit:Champion Fiberglass specialized formulations targeting premium coastal and corrosive environments where metallic alternatives fail prematurely.
PVC Conduit holds installed capacity. Flexible Non-metallic Conduit is rotating up the share rankings.
Installation Method:
Application complexity and code inspection intensity determine where contractors accept material premiums for labor reduction.
- Underground:Direct-burial HDPE and PVC conduit systems require ASTM F2160 density verification and wet-location ratings per National Electrical Code mandates. Coastal electrical contractors stockpile certified inventory ahead of municipal enforcement windows in Florida and California subdivisions.
- Concealed:Wall cavity and ceiling plenum installations demand flexible non-metallic formats that reduce electrician labor hours in retrofit scenarios. Aging housing stock across the northeastern United States drives specification of corrugated jacketing through renovation contractor procurement channels.
- Surface Mounted:Exposed raceway applications in utility spaces and unfinished basements favor rigid PVC cost economics.
- Aerial:Weather-resistant jacketing for overhead service entrance and detached structure feeder runs.
- Embedded:Concrete-encased conduit for slab-on-grade and foundation wall penetrations in new construction.
Underground commands specification premiums. Concealed is climbing the fastest as retrofit activity accelerates.
End User:
Procurement consolidation through master service agreements and direct jobsite delivery models is compressing distributor margins.
- Electrical Contractors:Licensed installation professionals specifying conduit brands through pre-approved vendor lists and bulk procurement programs. Large residential contractors in sun-belt states mandate brand lock-in through master service agreements that capture specification influence from distributor sales teams.
- New Construction Developers:Production homebuilders procuring standard rigid PVC through volume contracts tied to housing start cycles. Single-family developers in Texas and North Carolina align inventory with volatile construction schedules rather than steady-state replacement demand.
- Homeowners:DIY and small-project purchasers through retail and contractor referral channels.
- Renovators:Specialty contractors focused on smart-home retrofits and aging-in-place electrical upgrades.
- Property Managers:Multi-family maintenance and capital improvement procurement for rental housing portfolios.
Electrical Contractors control specification authority. New Construction Developers are gaining procurement scale fastest.
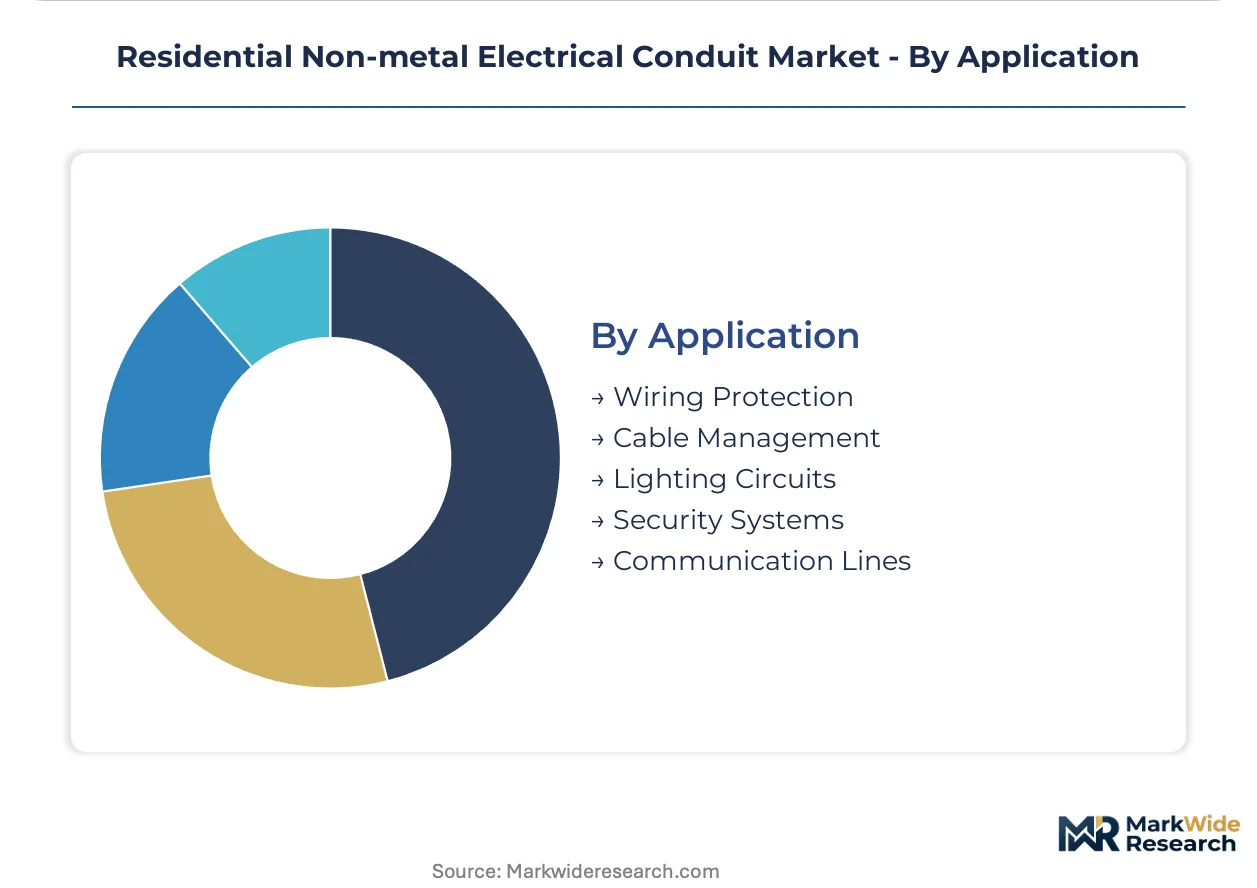
Application:
Low-voltage pathway separation from line-voltage circuits creates dedicated product requirements with distinct margin profiles.
- Cable Management:Dedicated routing systems for smart-home device networks, security systems, and communication lines requiring separation from power circuits. Smart-home proliferation in California and Washington state mandates dedicated low-voltage pathways that command premium positioning over standard wiring protection.
- Security Systems:Concealed conduit for alarm, surveillance, and access control wiring in residential installations.
- Wiring Protection:General-purpose raceway for branch circuit conductors in standard residential electrical distribution.
- Lighting Circuits:Circuit-specific conduit for interior and exterior luminaire connections.
- Communication Lines:Structured cabling pathways for data, voice, and media distribution networks.
Wiring Protection holds baseline volume. Cable Management is expanding most quickly on smart-home device density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level electrical code revisions across multiple jurisdictions are accelerating specification shifts toward corrosion-resistant conduit materials. The United States anchors regional demand through housing starts and retrofit activity. Canada and Mexico follow distinct regulatory trajectories that reshape cross-border procurement patterns.
United States
Single-family housing starts in Texas and Florida drive volume procurement of Schedule 40 PVC for new construction electrical distribution. The National Electrical Code mandates wet-location ratings and sunlight-resistant jackets for outdoor residential runs, enforced by local authorities having jurisdiction. Southeastern manufacturing clusters in Georgia and the Carolinas concentrate integrated resin-to-conduit production capacity.
Canada
Cold-climate construction in Ontario and Alberta elevates demand for flexible non-metallic conduit that withstands thermal cycling in exterior wall assemblies. Health Canada and provincial electrical safety authorities enforce CSA C22.1 standards that parallel but diverge from NEC requirements in material specifications. Toronto and Vancouver metropolitan areas concentrate contractor procurement power through large residential development consortia.
Mexico
Export-oriented manufacturing in Nuevo León and Baja California generates demand for conduit systems in worker housing and industrial park infrastructure. The national electrical utility CFE influences material specifications through procurement standards for grid-connected residential developments. Monterrey anchors northern Mexico's construction materials distribution network.
Residential Non-metal Electrical Conduit Market Competitive Landscape
Player mix skews toward diversified electrical infrastructure conglomerates with captive conduit divisions alongside specialized thermoplastic extruders. The market structure concentrates around integrated resin producers and independent fabricators competing on certification speed and jobsite delivery reliability. Three archetypes dominate: integrated chemical-electrical conglomerates, regional extrusion specialists, and fiberglass composite innovators. Competitive moves center on UL certification pre-positioning ahead of code cycles and direct contractor channel development bypassing traditional distribution.
Within the integrated infrastructure tier, ABB and Schneider Electric exemplify conglomerate positioning across electrical protection systems. Atkore anchors the North American specialist vector with southeastern U.S. manufacturing concentration. Champion Fiberglass occupies the premium composite niche targeting coastal corrosion environments where thermoplastic alternatives degrade.
| Leading Market Players |
|---|
| ABB |
| Atkore |
| Cantex |
| Astral |
| Anamet Electrical |
| Legrand |
| Schneider Electric |
| Hubbell |
| Champion Fiberglass |
| Others |
Pricing and Supply Chain Analysis
Long-term resin supply contracts with monthly PVC indexation lock in feedstock access for southeastern U.S. extruders while exposing cost-challenged entrants to spot market volatility. This contract structure concentrates procurement power among integrated producers who control captive resin production, compressing margins for independent fabricators forced to absorb ethylene price swings without volume leverage.
Pricing Analysis
Cost-plus contracts indexed to ethylene and chlorine spot benchmarks dominate PVC conduit procurement between integrated manufacturers and large electrical contractors. Price differentiation separates UL 651 Schedule 80 certified product from uncertified imports and economy-grade Schedule 40 offerings. Pricing pressure stems from PVC resin cost volatility that independent extruders cannot hedge effectively. New construction developers in Texas and Florida exhibit highest price sensitivity through volume tender processes, while coastal contractors specifying fiberglass alternatives show lowest sensitivity due to corrosion-failure costs.
Supply Chain Analysis
Strategic stockpiling of ASTM F2160-certified HDPE inventory ahead of municipal enforcement windows contrasts with just-in-time rigid PVC procurement tied to housing start cycles. Supply concentrates in the United States, China, and Germany for resin feedstocks and extrusion equipment. Raw material dependencies center on ethylene, chlorine, and high-density polyethylene resin. Single-source vulnerability runs through Gulf Coast petrochemical corridors exposed to hurricane disruption. Distribution runs through electrical wholesale distributors and direct jobsite delivery models bypassing traditional inventory holding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at an early-cycle expansion phase driven by NEC wet-location mandate adoption and smart-home retrofit penetration. Flexible conduit formats and cable management applications remain underpenetrated relative to mature rigid PVC baselines.
For Market Incumbents: Compound certification advantages by accelerating UL 651 pre-positioning ahead of code cycle revisions while securing long-term resin offtake to defend margin position against PVC price volatility. Threat from cross-linked polyethylene substitution in sun-belt attic applications demands R&D investment in thermal-stress formulations. Backward integration into captive resin production anchors cost competitiveness against Chinese import pressure. For New Entrants and Emerging Players: Differentiate on flexible conduit retrofit specialization targeting northeastern U.S. aging housing stock where labor-saving installation commands specification premiums. White-space concentrates in concealed wall-cavity applications and smart-home cable management pathways separate from line-voltage circuits. Go-to-market angle should prioritize direct electrical contractor channels through jobsite delivery models that bypass entrenched distributor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin-to-conduit specialists with southeastern U.S. manufacturing footprints. Long-term viability centers on code-anticipating specification capture and certification speed rather than commodity volume scale. Acquisition target archetype includes regional extrusion specialists with UL 651 testing investments and established contractor relationships. Signal to watch is municipal adoption velocity of ASTM F2160 density verification requirements that tighten inventory requirements and favor certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| UL Certification Pre-Positioning | Schedule 40 and Schedule 80 testing investments lock in specification authority before NEC code cycles finalize. |
| Resin Supply Integration | Captive PVC production in Georgia and the Carolinas insulates margin from ethylene spot volatility. |
| Flexible Conduit Capacity Expansion | Corrugated jacketing lines address labor-cost pressures in Arizona and Florida retrofit markets. |
| Direct Contractor Channel Development | Jobsite delivery models capture specification influence from distributor sales teams in production homebuilding. |
| Coastal Corrosion Formulation R&D | Fiberglass and HDPE innovations target Florida and California subdivisions where metallic alternatives fail. |
Research Methodology
Cross-validation between electrical contractor procurement interviews and NEC code revision documentation anchors the qualitative findings in this study. Primary research incorporated structured discussions with plant managers at southeastern U.S. extrusion facilities, procurement leads at national electrical distributors, licensed electricians in Texas and Florida production homebuilding, and regulatory affairs specialists tracking local authority jurisdiction amendments. Secondary validation drew from UL certification databases, NEMA technical standards publications, U.S. Census Bureau housing start data, and SEC filings from publicly traded infrastructure conglomerates. Bottom-up channel checks triangulate against top-down construction spending models.
Sensitivity analysis around housing start volatility and resin cost scenarios frames the projection methodology. Segmentation dimensions modeled include product type, installation method, end user procurement channel, and application voltage class across the analysis window. CAGRs derive from regression analysis correlating historical conduit demand with single-family construction permits and smart-home device installation rates. Industry-specific forecast inputs incorporate NEC adoption timelines and municipal enforcement window schedules.
Material uncertainties — PVC resin price spikes, hurricane disruption to Gulf Coast petrochemical supply, and municipal code amendment fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions about steady NEC wet-location mandate adoption and continued single-family construction recovery. Revision becomes warranted when housing start volatility or regulatory delay crosses thresholds that alter contractor procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.