
 Rail Coatings Market | 2026-2036
Rail Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Coatings Market Outlook
European coating formulators is realigning production footprints to serve cross-border rail refurbishment tenders. PPG Industries Inc. leverages its liquid coatings portfolio to anchor OEM supply relationships across North American freight builders. Akzo Nobel N.V. competes through powder coating technology leadership for European passenger coach programs.
Rail coatings are protective and decorative film-forming systems applied to rolling stock and trackside steel, typically comprising epoxy or polyurethane binders with corrosion-inhibiting pigments, designed to withstand cyclic thermal stress, UV exposure, and abrasive cargo contact. Epoxy formulations dominate freight car applications where chemical resistance and substrate adhesion outweigh gloss retention. Polyurethane coatings lead passenger coach specifications where UV stability and colorfastness command specification premiums.
EPA VOC rules and REACH Annex XVII restrict solvent-borne formulations, redirecting R&D toward waterborne and high-solids alternatives. ECHA substance evaluations further pressure isocyanate-containing polyurethane systems, accelerating hybrid technology development. Stakeholders must monitor regulatory divergence between European hazard-based restrictions and US performance-standard frameworks when configuring regional product pipelines.
Market Dynamics
Waterborne epoxy technology is consolidating specification control as freight operators in China, Germany, and the United States simultaneously phase out solvent-borne systems under tightening VOC frameworks. This convergence of regulatory pressure and performance validation is compressing formulation diversity while elevating coating procurement to strategic supply chain decisions.
Growth Catalysts
- China high-speed rail expansion:State railway procurement mandates for specification-grade polyurethane topcoats on new rolling stock are pulling advanced coating volumes into domestic supply chains.
- EPA VOC Phase II rules:The regulatory compression on solvent content is forcing North American freight operators into accelerated refurbishment cycles, opening coating specification windows.
- Hybrid polyurethane-epoxy binders:These formulations are capturing share in European passenger coach programs by bridging chemical resistance and UV stability requirements.
Market Restraints
- Isocyanate raw material concentration:European supply chains face ECHA substance evaluation pressures on diisocyanate precursors, constraining polyurethane production flexibility.
- Technical limitation in cure speed:Waterborne epoxies require extended ambient cure windows that conflict with freight yard throughput schedules in temperate climates.
- Substitution threat from thermal spray aluminum:Trackside steel protection in coastal China is partially displacing conventional coating systems for corrosion-critical infrastructure.
Strategic Opportunities
- Underpenetrated India freight modernization:Indian Railways' wagon refurbishment programs remain below specification-grade coating penetration thresholds, creating white space for epoxy primer suppliers.
- Regulatory tailwind from EU Green Deal:Carbon border adjustment mechanisms are incentivizing low-VOC coating adoption in cross-border rolling stock trade.
- Technology convergence of IoT-enabled coating monitoring:Embedded sensor layers in trackside steel coatings are emerging as value-add propositions for predictive maintenance contracts.
Industry Challenges
- Certification timeline compression:EMA and EPA parallel approval pathways for novel biocide-containing formulations are extending product launch cycles by 18-24 months.
- Skill gap in spray application robotics:Automated coating cell programming expertise lags behind capital deployment in Chinese and German OEM facilities.
- Legacy fleet color-matching complexity:Refurbishment programs struggle to replicate fading standards from 1990s-era polyurethane specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Coatings Market |
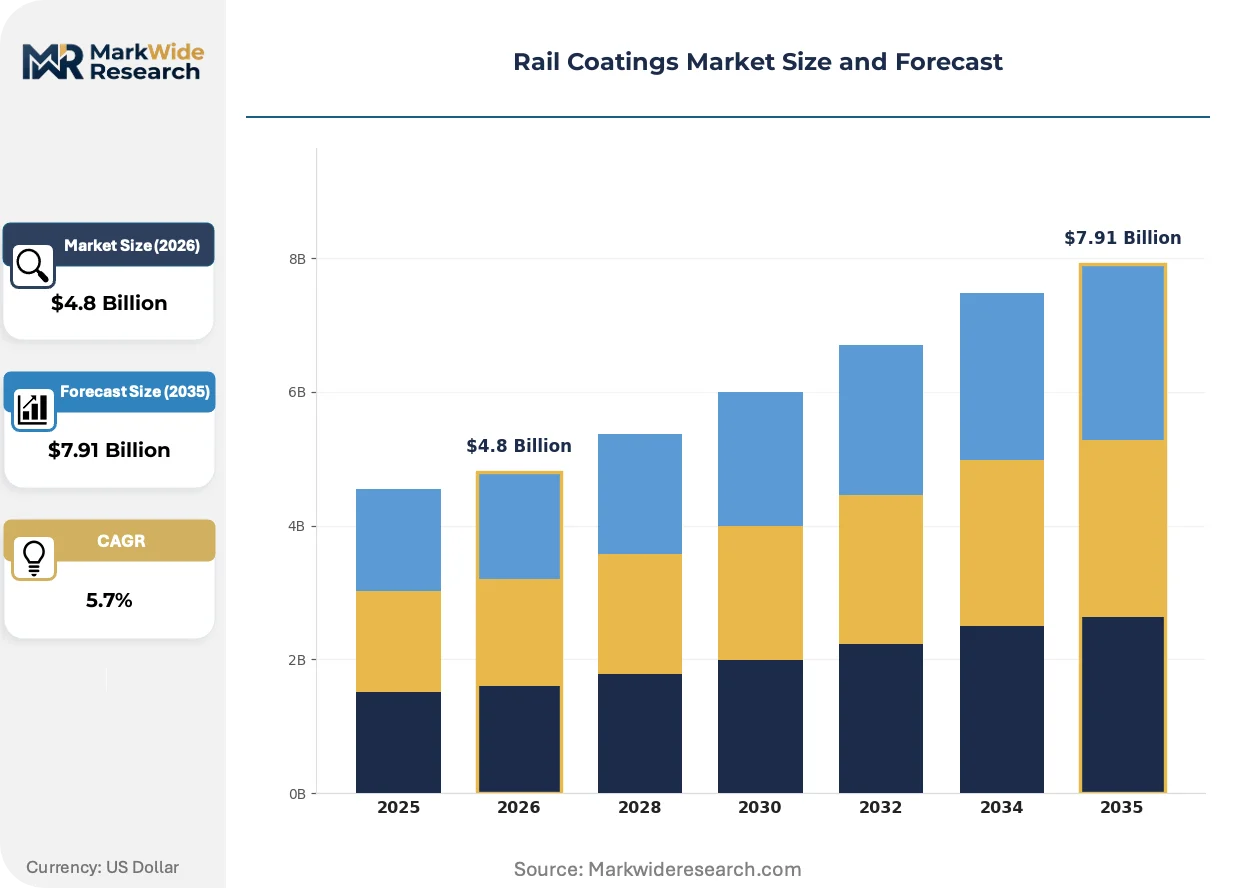
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, polyurethane, acrylic, alkyd Application: Freight Cars, Passenger Coaches, Locomotives, Infrastructure End User: Rail Operators, Maintenance Services, OEMs, Contractors Coating Technology: Liquid Coatings, Powder Coatings, Thermal Spray, Electrostatic |
| Companies Covered | The Sherwin-Williams Company, Nippon Paint Company Limited, PPG Industries Inc., RPM International Inc., Hempel A/S, Akzo Nobel N.V., Axalta Coating Systems LLC, Kansai Paint Co. Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Coatings Market Strategic Shifts
Coating formulators are compressing product pipelines around validated waterborne platforms while regulatory divergence between hazard-based and performance-standard frameworks forces regional specialization. This tension is accelerating R&D consolidation and reshaping competitive positioning.
High-solids epoxy technology is consolidating freight car specification control by delivering chemical resistance parity with legacy solvent systems at reduced VOC footprints. North American Class I railroads are adopting these platforms for hopper and tank car refurbishment programs. The technology is consolidating supplier relationships around fewer qualified formulators with validated track records.
REACH Annex XVII restrictions on diisocyanate content are forcing polyurethane formulators into hybrid binder development for European passenger coach applications. Industrial consequence includes accelerated substitution of conventional two-component systems with blocked isocyanate alternatives. Western European OEMs are responding by pre-qualifying waterborne polyurethane topcoats for premium livery specifications.
Specification-grade procurement is compressing coating selection cycles as Chinese state railway procurement centralizes around certified supplier lists. Direct tender relationships are displacing distributor-mediated transactions for high-speed rail rolling stock programs. This concentration is most visible in procurement patterns linking CRRC subsidiaries with pre-approved coating formulators.
Rail Coatings Market Segmentation
Rail coatings procurement stratifies sharply across specification tiers, with regulatory certification requirements varying by substrate, service environment, and operator procurement protocols. Understanding these segment boundaries enables suppliers to align R&D investments with approval pathways that gate commercial access.
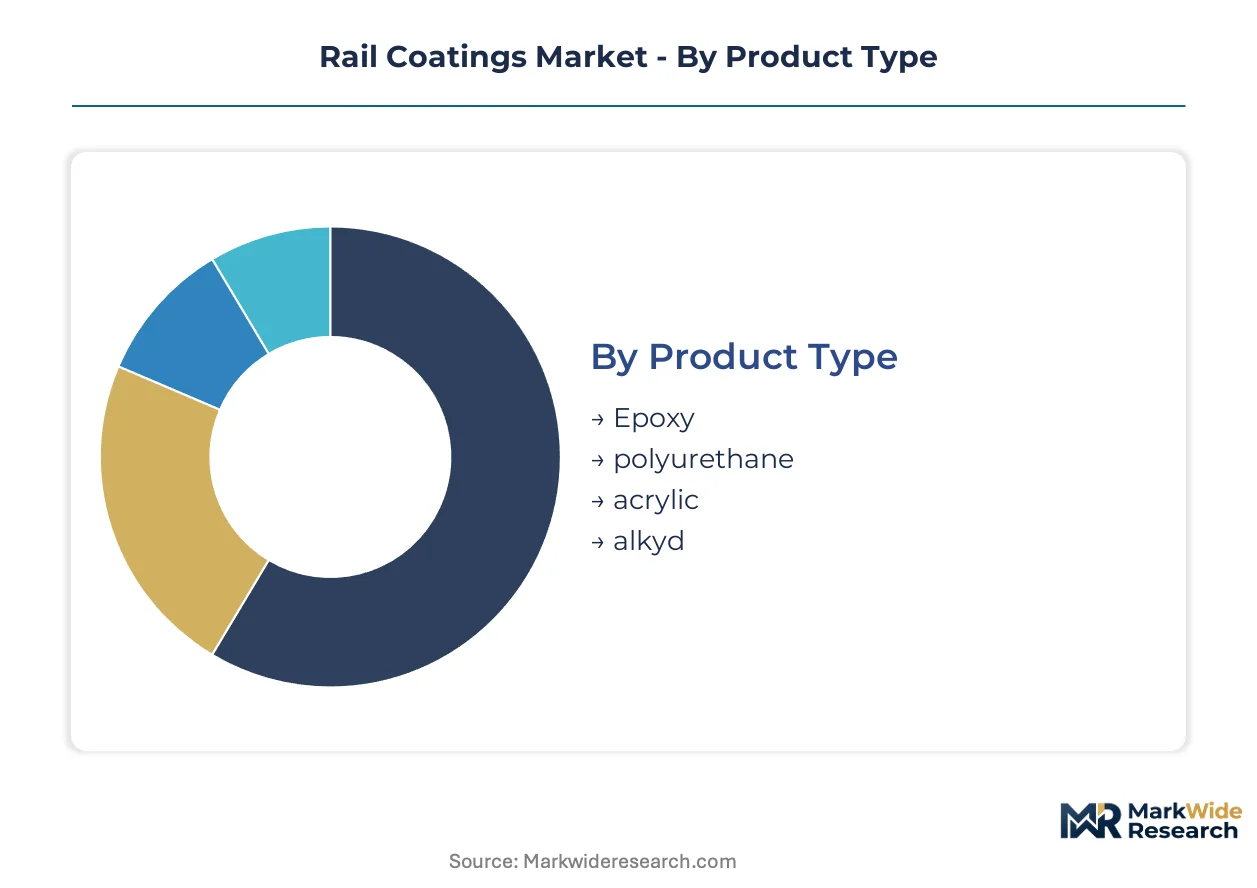
Product Type:
Certification burdens concentrate on polyurethane and epoxy systems, where REACH Annex XVII diisocyanate restrictions and EPA VOC Phase II rules impose parallel substance evaluation and performance validation requirements. Acrylic and alkyd formulations face lighter regulatory scrutiny but correspondingly narrower specification windows.
- Epoxy:Two-component amine-cured systems dominate freight car underframe and tank car interiors, delivering chemical resistance against corrosive cargoes. Chinese and North American freight operators specify these for hopper car refurbishment under tightening solvent-content frameworks. Demand concentrates in refurbishment yards serving coal and chemical transport fleets.
- Polyurethane:Aliphatic isocyanate-based topcoats command specification premiums on European and Chinese passenger coaches where UV stability and color retention define procurement scoring. ECHA substance evaluations on diisocyanate precursors are forcing reformulation toward blocked isocyanate hybrids, extending product launch timelines.
- Acrylic:Waterborne acrylic primers serve infrastructure applications with lower performance thresholds, particularly trackside steel in non-coastal environments.
- Alkyd:Solvent-borne alkyd maintenance enamels persist in legacy fleet touch-up applications where full system replacement is uneconomical.
Leading the category by volume: Epoxy. Growing fastest: Polyurethane.
Application:
Application segments diverge by capital cycle timing, with OEM new-build procurement running on multi-year state railway programs and refurbishment demand responding to regulatory compliance deadlines.
- Freight Cars:Hopper and tank car interiors require chemical-resistant epoxy systems certified for food-grade or hazardous cargo contact. North American Class I railroads are consolidating supplier relationships around high-solids platforms that satisfy EPA VOC rules without sacrificing throughput.
- Passenger Coaches:Exterior livery specifications demand polyurethane topcoats with 15-plus year color retention warranties. Chinese high-speed rail procurement centralizes around certified supplier lists, displacing distributor relationships for CRRC subsidiaries.
- Locomotives:Engine compartment coatings must balance thermal resistance with fire safety certification, narrowing qualified formulator pools.
- Infrastructure:Trackside steel protection faces substitution pressure from thermal spray aluminum in coastal China, though conventional coatings retain cost advantages for inland installations.
Dominant by procurement value: Passenger Coaches. Expanding most quickly: Freight Car refurbishment.
End User:
End user categories structure pricing power and contract duration, with OEMs extracting volume commitments and maintenance services prioritizing application speed over system specification.
- Rail Operators:State railway procurement in China and European incumbent operators specify certified coating systems through multi-year framework agreements, locking supplier capacity.
- Maintenance Services:Third-party refurbishment contractors in North America optimize for shop throughput, creating demand for fast-cure waterborne epoxies despite extended ambient cure windows.
- OEMs:Rolling stock manufacturers pre-qualify coating formulators during design phases, embedding specification decisions early in procurement cycles.
- Contractors:Infrastructure project contractors bid on trackside steel protection with price-driven coating selection, limiting premium system penetration.
Highest specification authority: Rail Operators. Fastest procurement cycle compression: Maintenance Services.
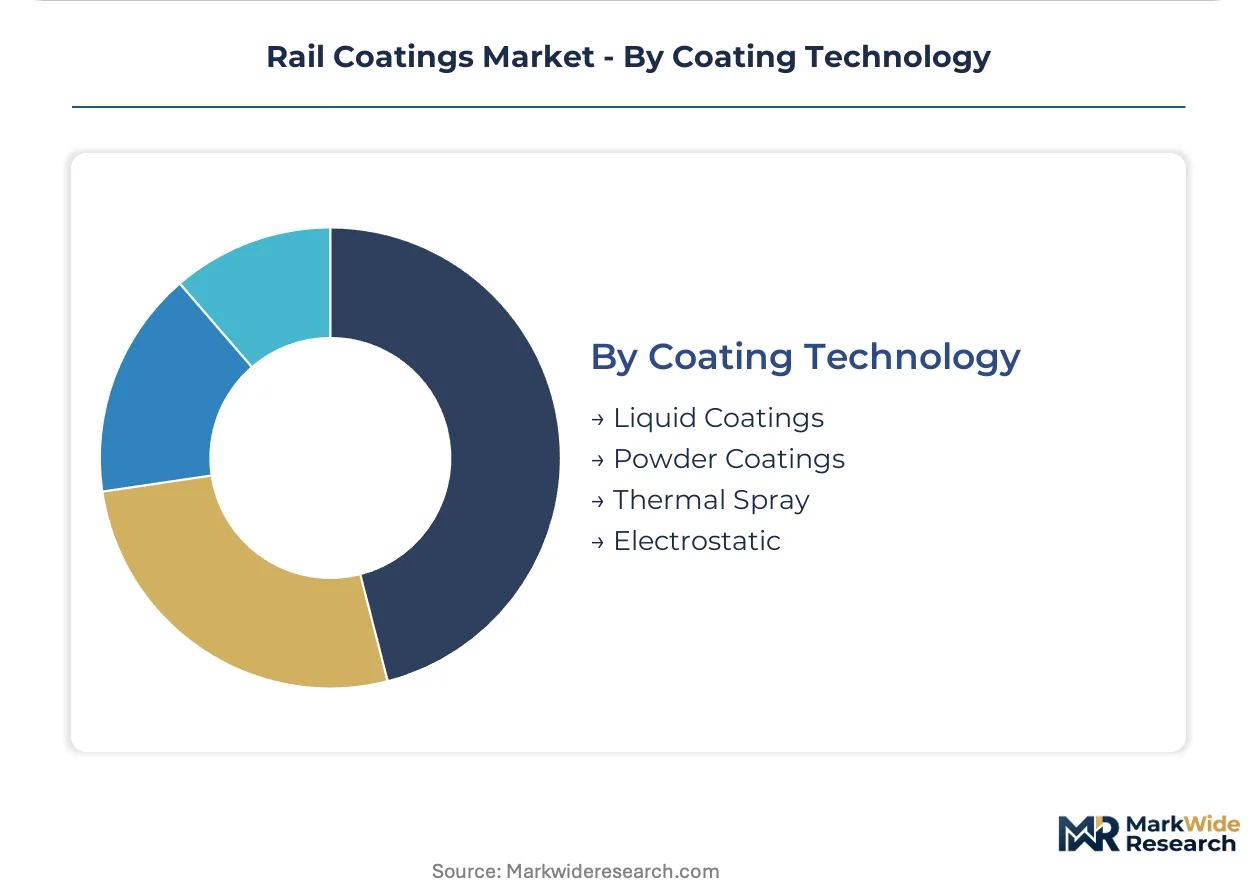
Coating Technology:
Technology segments map directly to capital intensity and regulatory compliance pathways, with powder coatings requiring electrostatic application infrastructure and liquid systems offering retrofit flexibility.
- Liquid Coatings:Solvent-borne and waterborne liquid systems retain dominance across all application segments, with waterborne epoxy technology consolidating freight car specification control in China, Germany, and the United States.
- Powder Coatings:Electrostatic powder application commands European passenger coach programs where zero-VOC profiles satisfy EU Green Deal procurement scoring. Akzo Nobel technology leadership anchors OEM supply relationships in this segment.
- Thermal Spray:Aluminum arc spray systems displace conventional coatings for coastal China trackside steel, offering superior corrosion protection at higher application cost.
- Electrostatic:Liquid electrostatic spray improves transfer efficiency in automated OEM coating cells, though programming expertise lags capital deployment in Chinese and German facilities.
Widest installed base: Liquid Coatings. Steepest expansion trajectory: Powder Coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's titanium dioxide and petrochemical feedstock clusters supply coating resin precursors to domestic formulators serving high-speed rail programs. German isocyanate production anchors European polyurethane supply chains for passenger coach specifications. North American epoxy resin manufacturing concentrates around Gulf Coast petrochemical infrastructure.
United States
Freight car refurbishment drives coating demand across Class I railroad networks spanning 140,000 route miles. EPA VOC Phase II rules compress solvent-borne formulation windows, redirecting procurement toward high-solids epoxy systems. Houston-Galveston petrochemical corridors supply bisphenol-A and amine curing agents to regional formulators.
Germany
Passenger coach OEM programs at Alstom and Siemens Mobility facilities sustain premium polyurethane topcoat specifications. ECHA substance evaluations on diisocyanate precursors force blocked isocyanate hybrid development. Ruhr industrial clusters host specialized coating application equipment manufacturers serving cross-border refurbishment tenders.
China
State Railway Group procurement mandates specification-grade polyurethane systems for CRRC new-build rolling stock. MIIT dual carbon goals accelerate waterborne epoxy adoption in freight car refurbishment yards. Yangtze River Delta coating formulators concentrate around Shanghai-Nanjing chemical industrial corridors.
Japan
Shinkansen fleet renewal programs sustain demand for UV-stable aliphatic polyurethane topcoats with 20-year color retention warranties. METI industrial standards govern fire-resistant coating specifications for tunnel-passing rolling stock. Kansai industrial belt formulators supply Osaka-based rail OEM final assembly facilities.
India
Indian Railways wagon modernization programs remain below specification-grade coating penetration thresholds across 300,000 freight car fleets. BIS certification requirements for protective coating systems are tightening for corrosion-critical applications. Gujarat industrial corridors host emerging domestic coating formulators targeting refurbishment contract opportunities.
Rail Coatings Market Competitive Environment
Global majors compete with regional champions across formulation technology and certification authority tiers. The vendor base stratifies around liquid coatings specialists, powder technology leaders, and integrated chemical conglomerates with captive resin supply. Three archetypes dominate: petrochemical-integrated multinationals with backward resin control; application-technology specialists with OEM pre-qualification depth; and regional formulators with regulatory certification agility. Competitive moves concentrate on hybrid binder R&D partnerships and automated coating cell integration contracts.
Among petrochemical-integrated multinationals, BASF SE and Axalta Coating Systems LLC exemplify archetypes combining captive epoxy and polyurethane precursor supply with specification-grade formulation expertise. Akzo Nobel N.V. occupies a distinct position within powder coating technology leadership for European passenger coach programs. PPG Industries Inc. anchors North American freight builder supply relationships through liquid coatings portfolio breadth. These three represent competitive positioning vectors spanning integrated supply chain control, application technology specialization, and regional OEM relationship depth.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Nippon Paint Company Limited |
| PPG Industries Inc. |
| RPM International Inc. |
| Hempel A/S |
| Akzo Nobel N.V. |
| Axalta Coating Systems LLC |
| Kansai Paint Co. Ltd. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
EPA VOC Phase II rules and REACH Annex XVII restrictions gate qualified supply and premium-tier pricing access by forcing reformulation investments that only capitalized formulators can absorb. Certification-grade polyurethane systems command 40-60% price premiums over standard epoxy platforms, with warranty bundling separating strategic suppliers from commodity competitors.
Pricing Analysis
Warranty and service bundling separates specification-grade suppliers from unbundled commodity competitors in this market. Three-tier pricing structure across premium, standard, and economy levels reflects certification authority, with EMA- and EPA-approved systems capturing premium positioning. Price differentiation hinges on 15-year color retention warranties and embedded technical service contracts. Cost compression in standard epoxy tiers is intensifying because freight operators prioritize throughput over performance specifications. Maintenance services exhibit highest price sensitivity, while Chinese state railway procurement demonstrates lowest sensitivity due to framework agreement structures.
Supply Chain Analysis
Freight logistics costs from German isocyanate production centers to European OEM facilities add 8-12% to landed polyurethane resin costs. Raw material concentration centers on China for titanium dioxide and epoxy precursors, Germany for aliphatic isocyanates, and the US Gulf Coast for bisphenol-A and amine curing agents. Formulation draws from petrochemical feedstocks with single-source vulnerability in specialized blocked isocyanate intermediates. Distribution runs through direct tender relationships for Chinese high-speed rail programs and distributor-mediated channels for North American refurbishment yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with backward integration into resin precursor production emerging as the decisive margin lever for specification-grade competitors.
For Market Incumbents: Anticipate ECHA substance evaluation outcomes by pre-qualifying blocked isocyanate hybrid formulations before regulatory deadlines compress. Secure captive supply of aliphatic isocyanate precursors through long-term offtake agreements with German and Japanese chemical producers. Thermal spray aluminum substitution in coastal China threatens conventional coating volumes for trackside steel applications. For New Entrants and Emerging Players: Begin with Indian Railways wagon refurbishment programs, where specification-grade coating penetration remains below 15% across 300,000 freight car fleets. Target BIS certification pathways for protective coating systems in corrosion-critical applications. Partner with Gujarat-based domestic formulators to leverage local regulatory agility and avoid established distributor relationships. For Investors and Strategic Acquirers: CRRC subsidiary procurement centralization around certified supplier lists is the leading indicator that direct tender relationships will displace distributor-mediated transactions across high-speed rail programs. Prioritize acquisition targets with EPA VOC Phase II and REACH Annex XVII pre-approval status. Watch for MIIT dual carbon goal acceleration as the signal for waterborne epoxy technology consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursors | Captive supply of bisphenol-A and isocyanates insulates margins from feedstock volatility. |
| Hybrid Binder R&D Partnerships | Blocked isocyanate development with German chemical producers accelerates ECHA compliance pathways. |
| Automated Coating Cell Integration | Programming contracts with Chinese and German OEM facilities embed specification decisions early. |
| Long-term Framework Agreements | Multi-year contracts with Chinese State Railway Group lock capacity and displace competitors. |
| IoT-Enabled Coating Monitoring | Embedded sensor layers create predictive maintenance revenue streams for trackside steel protection. |
Study Parameters
Trade databases, chemical industry association reports, and regulatory filing repositories formed the secondary backbone of this analysis. Primary fieldwork encompassed coating formulator technical directors, freight operator procurement leads, OEM specification engineers, and third-party refurbishment contractors. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and coating technology segments.
Historical trendline analysis of specification-grade procurement patterns informed the projection framework across the analysis window. Segmentation modeling incorporated coating chemistry tier, end-use application, regulatory certification cluster, and regional production hub dimensions. CAGRs derived from volume trajectory alignment with capital cycle timing for OEM new-build versus refurbishment demand. Forecast inputs included EPA VOC Phase II compliance deadlines and MIIT dual carbon policy implementation pacing.
Underlying measurement precision varies by segment; polyurethane topcoat specifications carry tighter precision than alkyd maintenance enamel volumes due to centralized procurement data availability. Forecasts reflect assumptions regarding regulatory timeline adherence and capital deployment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Wood Protection Coating Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Marine Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
2K Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Conductive Shielding Coatings for Battery Management Systems Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Gelcoat Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Coatings Raw Materials Market