
 Anti Fog Coatings Market | 2026-2036
Anti Fog Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Fog Coatings Market Intelligence
The automotive sector's demand for coatings on LiDAR sensors and interior displays is pivoting the market's focus from traditional safety eyewear. 3M Company leverages its extensive material science portfolio across multiple end-user segments. Mitsui Chemicals specializes in high-performance polymer solutions tailored for automotive clients in Japan. FSI Coating Technologies competes by offering customized, durable coatings for specialized industrial and medical applications.
Anti-fog coatings are hydrophilic surface treatments that prevent water vapor condensation by reducing surface tension and spreading moisture into a non-light-scattering film. These formulations are typically based on polyurethane or acrylic polymers applied in thin, transparent layers. Transparent product types dominate the market due to the critical need for optical clarity in most applications. While eyewear remains a core application, demand for coatings on healthcare face shields and automotive mirrors is expanding rapidly.
Regulatory frameworks significantly influence product development and market access. In the United States, the FDA sets standards for coatings used on medical devices like face shields, while Europe's CE marking is essential for personal protective equipment. Global ISO standards for optical quality and durability further define performance benchmarks. Coating manufacturers must balance investments in durable nano-coatings against cost-effective formulations for commoditized segments.
Market Dynamics
The market's center of gravity is shifting from commoditized safety eyewear towards high-performance automotive and electronics applications. This pivot is driven by the technical demands of ADAS sensors, heads-up displays, and advanced medical imaging equipment, which require superior optical clarity and durability.
Growth Catalysts
- Advanced Nano-Coatings:Durable nano-formulations extend product lifespans, meeting performance demands in high-wear industrial and automotive applications.
- Automotive Sector Integration:Demand from automotive hubs like Germany for coating ADAS sensors and displays provides a consistent, high-value revenue stream.
- PPE Regulations:Mandates like Europe's CE marking for personal protective equipment create baseline demand for certified anti-fog coatings on face shields.
Market Restraints
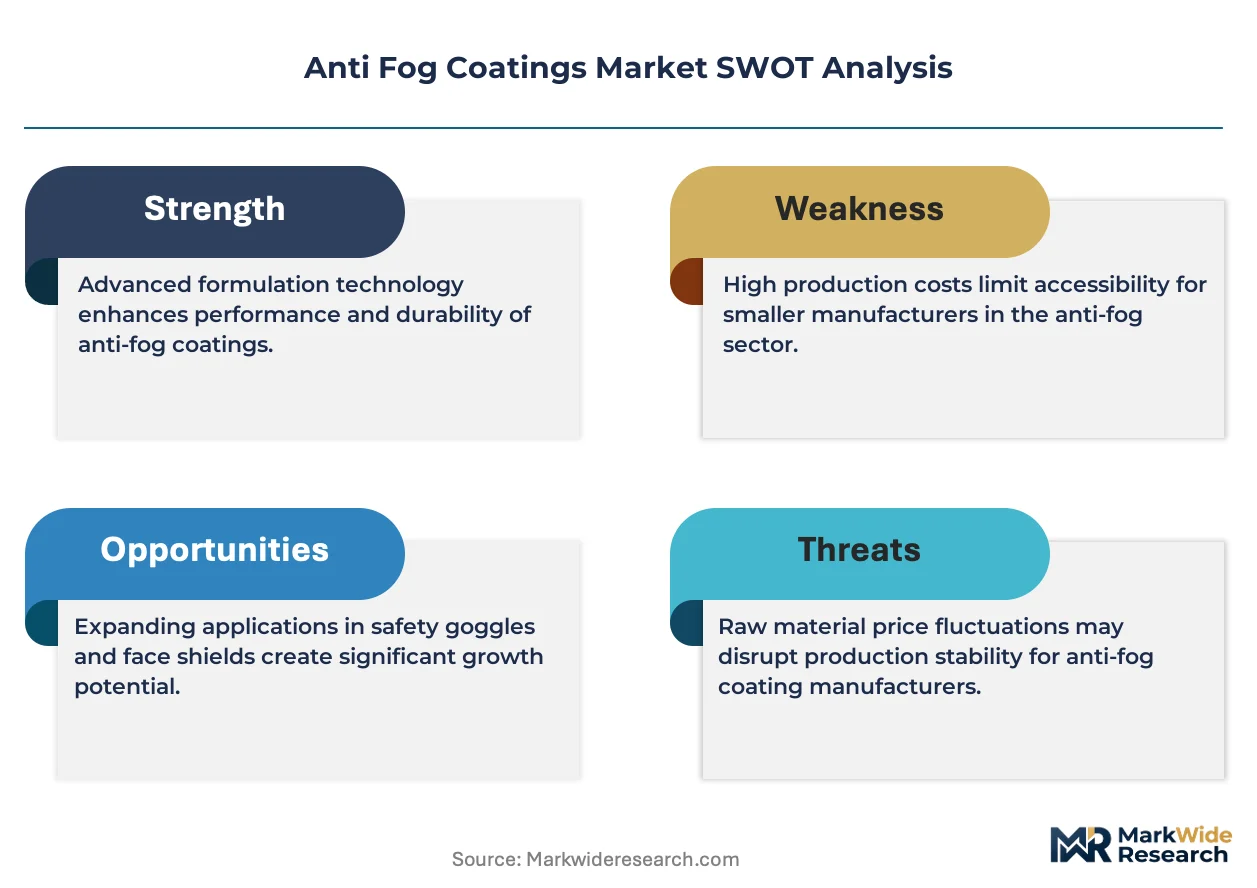
- Input Cost Volatility:Price fluctuations for polyurethane and acrylic precursors create margin pressure for manufacturers of high-volume, cost-sensitive eyewear coatings.
- Performance Trade-offs:Many hydrophilic coatings have limited abrasion resistance, requiring frequent reapplication and limiting use in rugged industrial environments.
- Regulatory Hurdles:The lengthy FDA approval process for coatings on medical devices in the United States deters market entry for smaller innovators.
Strategic Opportunities
- Emerging Display Technologies:The market for augmented and virtual reality headsets presents an opportunity for specialized anti-fog coatings on complex optical lenses.
- Geographic Expansion:India's expanding healthcare manufacturing sector offers growth potential for coatings on locally produced medical face shields and goggles.
- Self-Healing Formulations:Research into coatings that self-repair minor scratches while maintaining hydrophilic properties is a key area for future product differentiation.
Industry Challenges
- Application Complexity:Achieving uniform coating thickness and adhesion on complex, curved surfaces like wraparound safety glasses or automotive LiDAR covers remains a significant manufacturing challenge.
- Standardization Gaps:A lack of universally accepted ISO testing protocols across different industries complicates performance comparisons and supplier selection for end users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Fog Coatings Market |
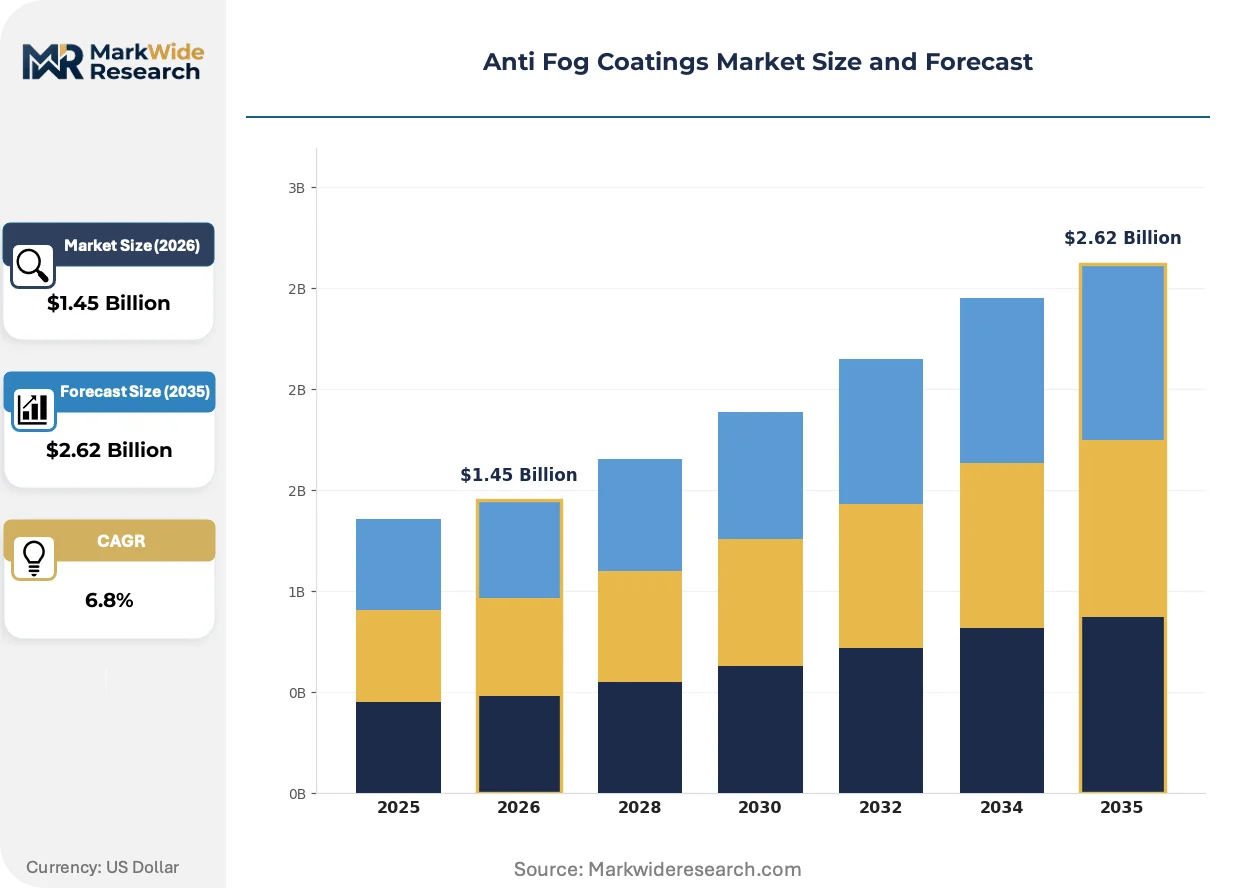
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Translucent, Pigmented, Self-Cleaning Application: Safety Goggles, Face Shields, Mirrors, Eyewear End User: Healthcare, Automotive, Consumer Electronics, Sports Technology: Nano-Coating, Chemical Coating, Physical Coating, Hybrid Coating |
| Companies Covered | 3M Company, FSI Coating Technologies, Peerless Plastics & Coatings, Mitsui Chemicals, Nippon Paint Holdings, Hydromer, NEI Corporation, WeeTect, Optical Coating Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Fog Coatings Market Strategic Shifts & Innovations
Material science advancements are enabling a new generation of application-specific coatings, moving the industry beyond generic formulations. The primary focus is on integrating multiple performance attributes into a single, durable layer tailored to specific end-use environments.
Multi-functional coatings combine anti-fog properties with other functionalities like anti-scratch, anti-static, or anti-reflective capabilities. The consumer electronics sector, particularly in South Korea, is rapidly adopting these for smartphone camera lenses and wearable device screens. This development is unifying previously separate performance criteria into a single, high-value coating application, simplifying manufacturing processes.
Europe's REACH regulation restricts certain chemicals, such as specific isocyanates used in some polyurethane-based anti-fog formulations. This is forcing a shift towards water-based and solvent-free acrylic systems to ensure compliance for products sold within the EU. Manufacturers of personal protective equipment are most affected, investing in R&D to reformulate products without compromising performance to retain CE marking.
Automotive OEMs are increasingly co-developing custom anti-fog solutions directly with coating specialists, bypassing traditional distribution channels. This collaborative model is displacing the standard procurement of off-the-shelf products, favoring long-term partnerships focused on specific performance outcomes. This trend is most visible in Germany's automotive industry, where precise coating performance is critical for the optical clarity of ADAS sensors.
Anti Fog Coatings Market Segmentation
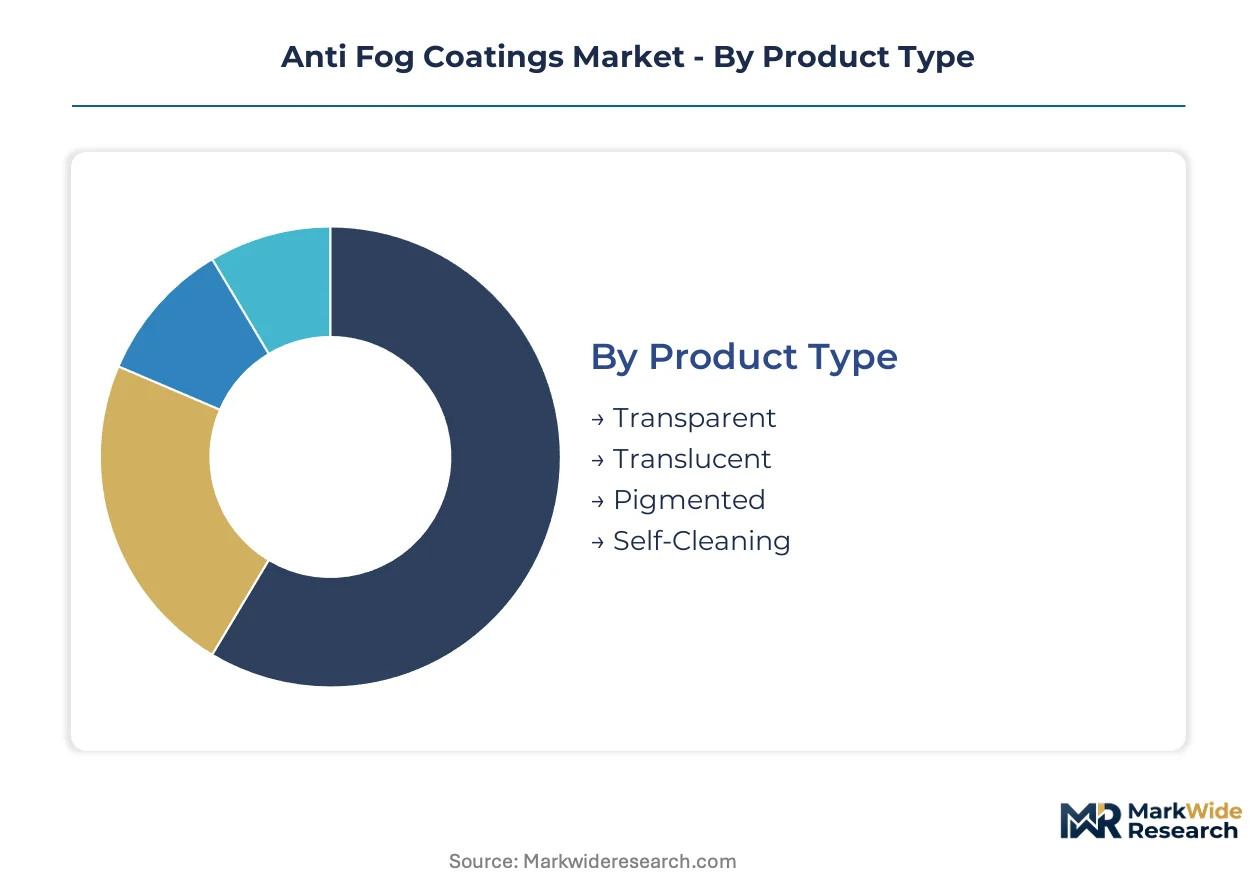
The anti-fog coatings market is highly segmented, reflecting the diverse performance requirements and end-use environments for these specialized surface treatments. Understanding these distinct segments is crucial for manufacturers to tailor product development and market strategies effectively.
Product Type:
The anti-fog coatings market differentiates products primarily based on their optical properties and functional characteristics.
- Transparent:These coatings allow maximum light transmission without distortion, crucial for optical clarity. Demand concentrates in automotive applications for ADAS sensors and heads-up displays, driven by stringent performance requirements.
- Translucent:These formulations permit light passage but scatter it, often used where diffused light is acceptable.
- Pigmented:Incorporating colorants, these coatings offer anti-fog benefits alongside aesthetic or signaling functions.
- Self-Cleaning:These advanced coatings integrate photocatalytic or superhydrophobic properties to repel dirt and maintain clarity over time. Demand is emerging in outdoor industrial equipment and specialized architectural glass, where reduced maintenance costs are a key advantage.
Transparent coatings lead on market scale; self-cleaning formulations lead on technological momentum.
Application:
Applications for anti-fog coatings span various end-use environments, each demanding specific performance profiles.
- Safety Goggles:These coatings are essential for maintaining clear vision in industrial and laboratory settings.
- Face Shields:Critical for healthcare and personal protection, these coatings ensure unobstructed vision for medical professionals. Demand is expanding rapidly in healthcare manufacturing hubs like India, driven by local production mandates and public health initiatives.
- Mirrors:Applied to automotive and bathroom mirrors, these coatings prevent condensation, improving visibility and safety. Demand is particularly strong in the automotive sector for exterior side mirrors, where regulatory safety standards are paramount.
- Eyewear:This segment includes prescription glasses and sunglasses, benefiting from enhanced clarity in diverse climatic conditions.
The market is observing a shift towards applications demanding higher durability and specialized performance characteristics.
End User:
End-user industries define coating requirements based on their operational environments and regulatory compliance needs.
- Healthcare:This sector utilizes anti-fog coatings on medical devices, face shields, and diagnostic equipment. Demand is influenced by FDA standards in the United States and CE marking in Europe for medical personal protective equipment.
- Automotive:Coatings are applied to ADAS sensors, interior displays, and external lighting for improved safety and functionality. Germany's automotive industry drives significant demand for custom solutions, ensuring optical clarity for critical vehicle systems.
- Consumer Electronics:This segment applies coatings to smartphone camera lenses and wearable device screens for enhanced user experience.
- Sports:Anti-fog solutions are critical for sports eyewear, ski goggles, and diving masks, preventing vision impairment during activities.
Industry-specific demands are driving innovation in tailored anti-fog coating solutions.
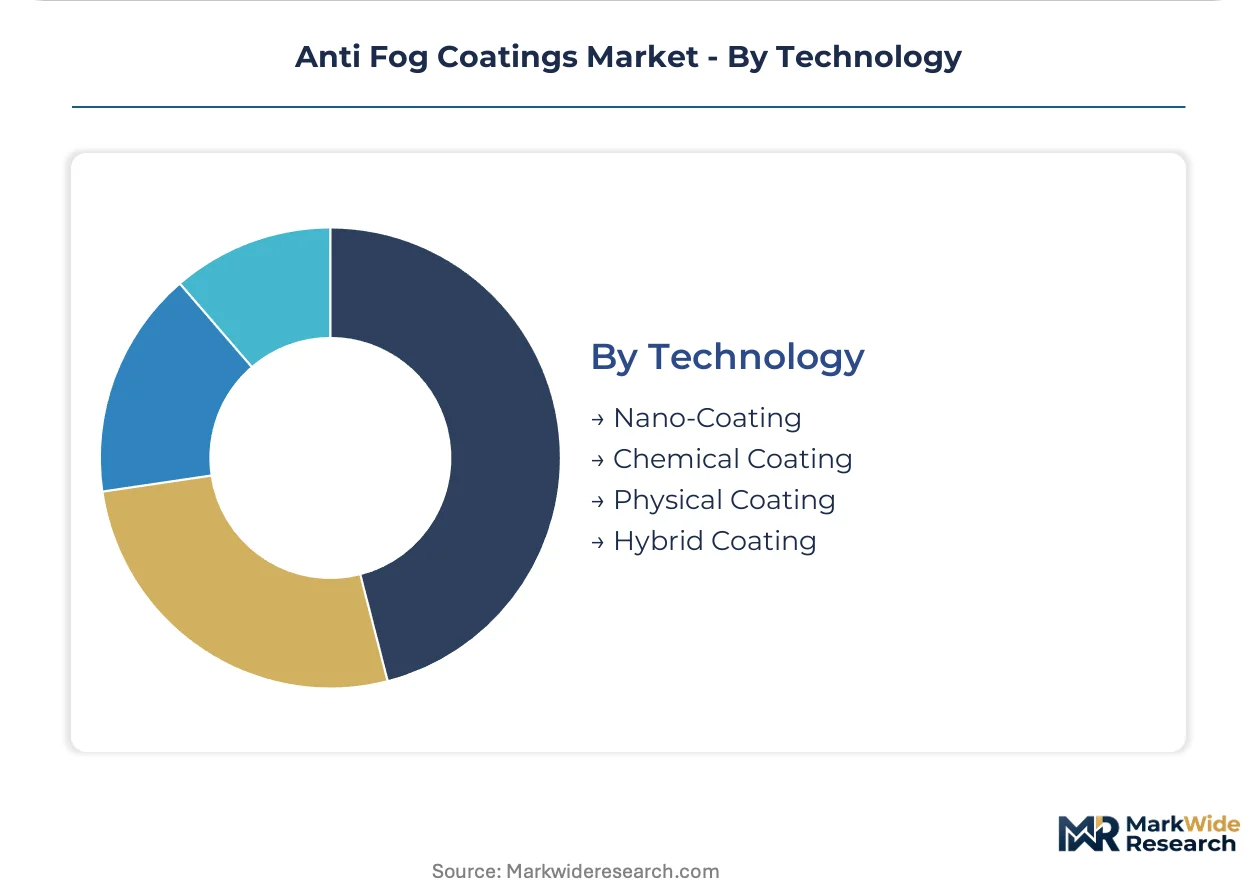
Technology:
Technological advancements in material science underpin the performance and durability of modern anti-fog coatings.
- Nano-Coating:These formulations utilize nanoscale structures to create highly durable and effective hydrophilic surfaces. Demand from automotive hubs like South Korea for advanced displays and sensors leverages these high-performance properties.
- Chemical Coating:These involve chemical reactions on the substrate surface to impart anti-fog properties.
- Physical Coating:Physical deposition methods are used to apply thin layers of anti-fog materials onto surfaces.
- Hybrid Coating:These combine multiple coating technologies, such as anti-fog with anti-scratch or anti-reflective properties, into a single layer. The consumer electronics sector in South Korea increasingly adopts these multi-functional coatings for smartphone camera lenses, simplifying manufacturing.
Innovation in coating technologies is focusing on multi-functional attributes and enhanced durability for diverse applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory disparities across regions create opportunities for manufacturing relocation in the anti-fog coatings market. Stringent chemical regulations in Europe, such as REACH, encourage a shift towards compliant formulations, influencing production investments. This dynamic drives manufacturers to optimize supply chains based on both cost-effectiveness and adherence to diverse environmental and product standards.
Germany
Germany's automotive sector generates significant demand for high-performance anti-fog coatings on ADAS sensors and heads-up displays. KBA regulations for vehicle components emphasize durability and optical clarity. Automotive clusters in Bavaria and Baden-Württemberg focus on custom anti-fog solutions co-developed with coating specialists.
South Korea
South Korea's consumer electronics industry drives demand for advanced anti-fog nano-coatings on displays and camera lenses. MFDS standards for medical devices and KCC for electronics influence product development. The Seoul Capital Area and Gyeonggi Province lead in multi-functional coating development for wearable technology.
United States
The United States healthcare sector requires anti-fog coatings for medical devices, face shields, and diagnostic equipment. The FDA sets rigorous standards for medical device coatings, impacting market entry for new formulations. Silicon Valley and Boston's biotech hubs drive demand for specialized optical coatings in advanced medical imaging.
India
India's expanding healthcare manufacturing sector offers growth potential for anti-fog coatings on locally produced medical face shields and goggles. BIS standards for industrial safety equipment and CDSCO for medical products influence local production. Manufacturing zones in Gujarat and Maharashtra expand local production of certified anti-fog PPE.
China
China's vast manufacturing base, particularly in electronics and automotive, drives substantial demand for anti-fog coatings. GB standards for product quality and safety guide local production and import requirements. The Yangtze River Delta and Pearl River Delta regions see high volume production of anti-fog components for diverse applications.
Anti Fog Coatings Market Key Industry Players
Strategic partnerships and R&D investment dominate the current landscape, as original equipment manufacturers co-develop custom solutions. The market exhibits a tiered structure, encompassing large material science conglomerates and highly specialized coating technology firms. Key archetypes include global chemical producers, niche industrial solution providers, and regional manufacturers focusing on specific application segments. Portfolio diversification into advanced multi-functional coatings and technology licensing agreements are primary competitive maneuvers.
Material science conglomerates like 3M Company leverage extensive portfolios across multiple end-user segments, representing broad market reach. Mitsui Chemicals, a Japanese-based corporation, occupies a position among high-performance polymer solution providers, often tailored for specific automotive clients. FSI Coating Technologies exemplifies specialized industrial and medical application providers, offering customized and durable coating solutions.
| Leading Market Players |
|---|
| 3M Company |
| FSI Coating Technologies |
| Peerless Plastics & Coatings |
| Mitsui Chemicals |
| Nippon Paint Holdings |
| Hydromer |
| NEI Corporation |
| WeeTect |
| Optical Coating Technologies |
| Others |
Cost & Logistics Intelligence
The global polyurethane price index directly influences the cost structure of anti-fog coatings, cascading into varied pricing tiers for commoditized eyewear versus high-performance automotive applications. This volatility for key chemical precursors creates margin pressure across the supply chain.
Pricing Analysis
Distributor margins for anti-fog eyewear are subject to intense competition, often leading to price compression. Pricing primarily follows a per-unit transactional model, differentiated by optical clarity grade and specific regulatory certifications like CE marking. Input cost volatility for acrylic precursors drives pricing pressure in high-volume, lower-margin segments. Healthcare face shield manufacturers are highly price-sensitive, unlike automotive OEMs seeking customized, long-term solutions with stringent performance requirements.
Supply Chain Analysis
Regional distribution centers facilitate the movement of coating formulations from manufacturing hubs to end-user markets. Supply concentrates in Germany, South Korea, and China, drawing heavily on polyurethane and acrylic precursors. Single-source vulnerability for specialized additives presents a structural risk to the supply chain. Distribution primarily occurs through direct-to-OEM channels for high-value applications and through specialized chemical distributors for broader industrial and consumer use.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-fog coatings market operates as a regulatory compounder, with Europe's CE marking for personal protective equipment driving consistent demand for certified products.
For Market Incumbents: Deepen material science R&D into multi-functional nano-coatings to counter commoditization from generic formulations. Invest in advanced manufacturing capacity in strategic regions like Germany to serve automotive OEMs directly. Secure long-term supply agreements for critical precursors to mitigate input cost volatility from external markets.
For New Entrants and Emerging Players: Underserved medical device manufacturers in emerging markets like India present a significant white-space opportunity. Focus on specialized anti-fog coatings for complex optical components in AR/VR headsets, leveraging advanced application techniques. A direct-to-developer go-to-market strategy for niche electronics can accelerate market penetration.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating technology firms offering proprietary, durable nano-formulations. The market demonstrates long-term viability driven by increasing regulatory mandates for safety and performance across industries. Watch for the adoption of new ISO testing protocols as a key inflection indicator for product differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Nano-Coating R&D | Enhances product durability and performance for high-value automotive and electronics applications. |
| Expand Manufacturing in India | Capitalizes on local production mandates and healthcare sector growth for PPE coatings. |
| Form Strategic OEM Partnerships | Secures long-term revenue streams and co-development opportunities with automotive clients. |
| Develop Multi-Functional Coatings | Addresses consumer electronics demand for combined anti-fog, anti-scratch, and anti-reflective properties. |
| Pursue Advanced Certification | Ensures market access and compliance with stringent medical and safety standards like FDA and CE. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. Interviews included R&D directors, procurement leads, regulatory specialists, and application engineers across the value chain. Secondary data sources comprised industry association reports, government standards documents, and patent databases. This was triangulated with bottom-up market sizing and top-down validation.
Rate-of-change decomposition informed the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, application, end-user industry, technology, and regional regulatory clusters. CAGRs were derived from historical growth trends and projected adoption rates. Key forecast inputs included ADAS sensor integration rates and PPE manufacturing capacity expansions.
Underlying measurement precision varies by segment; transparent coatings and automotive applications carry tighter precision than others. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Waterborne Automobile Coating Market
Coatings
Fluoropolymer Coating Market
Coatings
Global Anti Slip Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Compound Coating Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Marking Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Textile Coatings Market