
 Global Protective Fabrics Market | 2026-2036
Global Protective Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protective Fabrics Market Foresight
Chinese aramid fiber producers is restructuring capacity allocation toward domestic military and aerospace programs. DuPont leverages its Kevlar manufacturing heritage to sustain premium positioning in North American defense contracts. Teijin Limited anchors Asian supply chains through integrated Twaron production from polymer to finished textile. W. L. Gore & Associates differentiates via membrane-laminate technology that controls breathable waterproofing in hazmat ensembles.
Protective fabrics are engineered textile systems combining synthetic high-performance fibers with barrier coatings to achieve specified thermal, mechanical, or chemical resistance ratings, typically measured against ASTM F1506 or EN ISO 11612 protocols for flame exposure and heat transfer. Their primary purpose is to reduce occupational injury risk in environments where standard apparel would fail under thermal, cut, or permeation hazards. Aramid fiber workwear occupies the largest value pool due to entrenched specification in fire service and electrical utility procurement. Nanofiber textiles represent the fastest-expanding material technology segment as manufacturers seek lighter weight alternatives with equivalent particulate filtration efficiency. Military uniform applications concentrate margin pools where multi-threat performance requirements justify premium pricing over standard industrial workwear.
NFPA standards in the United States, EU PPE regulations with CE marking requirements, and China's GB national standards collectively shape product certification pathways and market access conditions for protective fabric manufacturers. OSHA enforcement of workplace hazard assessments in American manufacturing plants directly converts regulatory compliance into fabric procurement volume. Stakeholders must monitor evolving PFAS restrictions under REACH and state-level American legislation, as fluorinated chemistry bans threaten existing water-repellent finishing technologies and force material transitions.
Market Dynamics
PFAS chemistry restrictions under REACH and parallel US state legislation are forcing immediate reformulation of water-repellent finishing systems across the protective fabrics supply chain, compressing established margin structures while opening substitution pathways for bio-based alternatives.
Growth Catalysts
- NFPA 1971 revisions:Updated thermal performance benchmarks for firefighter turnout gear are accelerating specification upgrades across municipal procurement programs in the United States.
- China's GB 12014-2019 standard:Mandatory anti-static workwear requirements in petrochemical facilities are expanding aramid fiber volume through state-owned enterprise purchasing.
- Nanofiber membrane integration:Electrospun barrier layers are penetrating hazmat ensemble designs, offering lighter weight alternatives to traditional laminated constructions.
Market Restraints
- Meta-aramid fiber concentration:Three producers control over eighty percent of global para-aramid supply, creating vulnerability to geopolitical trade restrictions or capacity allocation shifts.
- Fluorinated chemistry phase-out:ECHA PFAS restriction proposals and US state-level bans threaten existing durable water-repellent finishing technologies without mature commercial replacements.
- Certification timeline compression:Extended third-party testing protocols for multi-threat fabrics extend product development cycles by twelve to eighteen months versus single-hazard alternatives.
Strategic Opportunities
- India's PLI scheme for technical textiles:Production-linked incentives for protective fabric manufacturing are attracting greenfield investment in Gujarat and Tamil Nadu industrial corridors.
- Wearable sensor convergence:Integration of biometric monitoring threads with thermal protective base layers addresses emerging demand from wildland fire management agencies.
- Direct-to-utility procurement platforms:Bypassing traditional industrial distribution channels allows fabric producers to capture margin previously allocated to intermediaries in electrical utility segments.
Industry Challenges
- Multi-hazard certification complexity:Simultaneous testing against EN ISO 11612 flame resistance, EN 388 cut protection, and EN 943 chemical permeation standards requires specialized laboratory capacity that remains scarce outside Western Europe.
- Legacy finishing equipment stranded:C6 fluorocarbon treatment lines face accelerated obsolescence as regulatory timelines compress, forcing capital redeployment toward plasma or sol-gel alternative systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protective Fabrics Market |
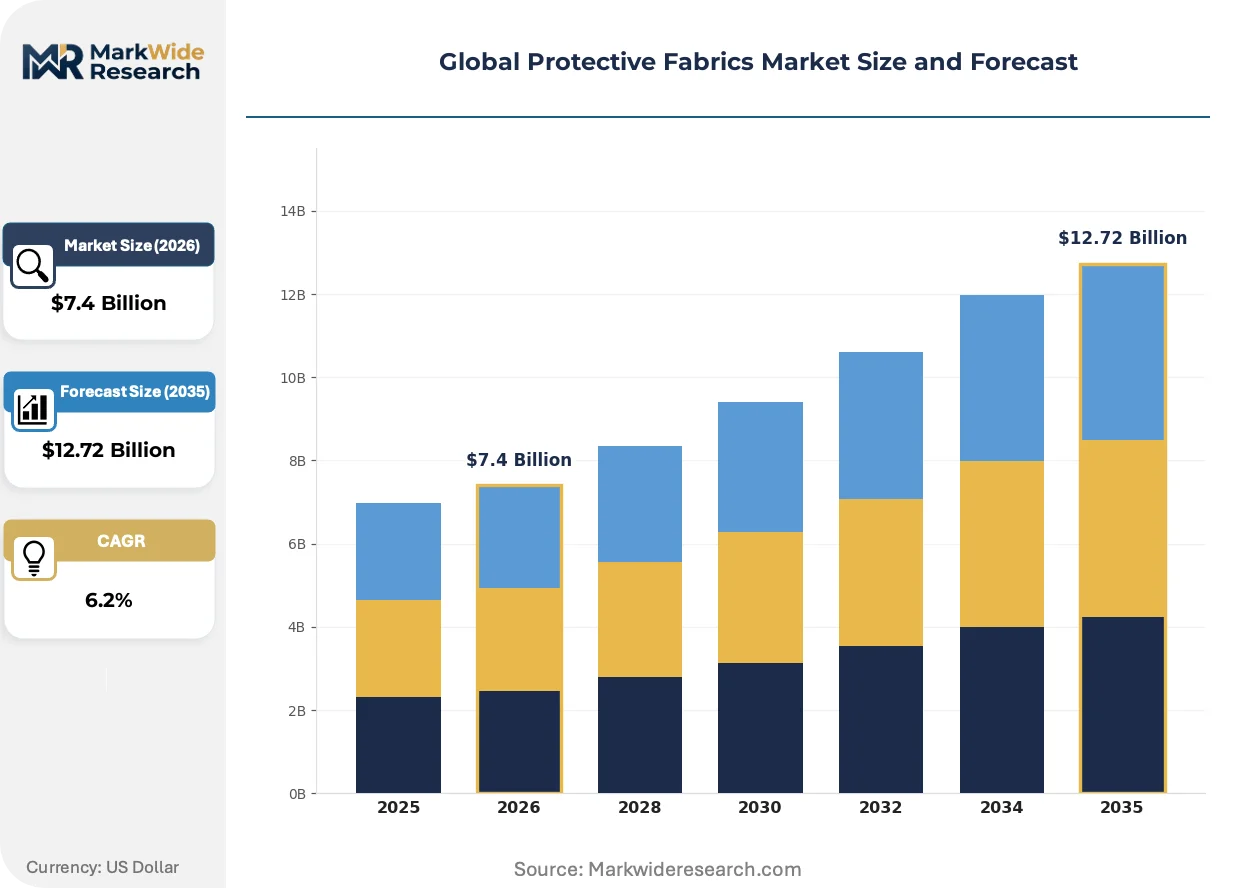
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Resistant Fabrics, Cut-Resistant Textiles, Waterproof Materials, Chemical-Resistant Cloths, Anti-Static Yarns End Use Industry: Construction, Oil & Gas Extraction, Emergency Services, Manufacturing Plants, Transportation Sector Application: Workwear, Protective Gear, Safety Equipment, Industrial Covers, Military Uniforms Material Technology: Aramid Fibers, High-Density Polyethylene, Basalt Fibers, Carbon Fiber Blends, Nanofiber Textiles |
| Companies Covered | DuPont, 3M, Honeywell, Milliken & Company, Teijin Limited, W. L. Gore & Associates, TenCate Protective Fabrics, Lakeland Industries, Klopman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protective Fabrics Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry transitions are compressing traditional product lifecycles while opening performance tiers previously unreachable with conventional fiber systems.
Electrospun nanofiber webs are decentralizing barrier function placement within protective ensembles. Fire service equipment manufacturers in Germany and the United States are integrating these layers between outer shells and thermal liners, replacing heavier microporous film laminates. This architecture is decentralizing supply relationships as specialized nanofiber producers bypass traditional textile converters to sell directly to finished garment manufacturers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating C8 and C6 fluorocarbon water-repellent chemistries from European supply chains. Industrial laundries serving oil and gas operators face reformulation deadlines that compress acceptable finishing alternatives to silicone, paraffin, or bio-based wax systems. German chemical suppliers are accelerating plasma-induced grafting technologies to maintain performance parity without fluorinated inputs.
Consolidated buying by national oil companies and utility monopsonies is compressing supplier rosters to pre-qualified fabric mills with integrated testing laboratories. Saudi Aramco and PetroChina procurement frameworks now mandate direct mill relationships, bypassing regional distributors. This concentration is most visible in Middle Eastern petrochemical corridor contracts where single-source agreements cover multi-year uniform programs.
Global Protective Fabrics Market Segmentation
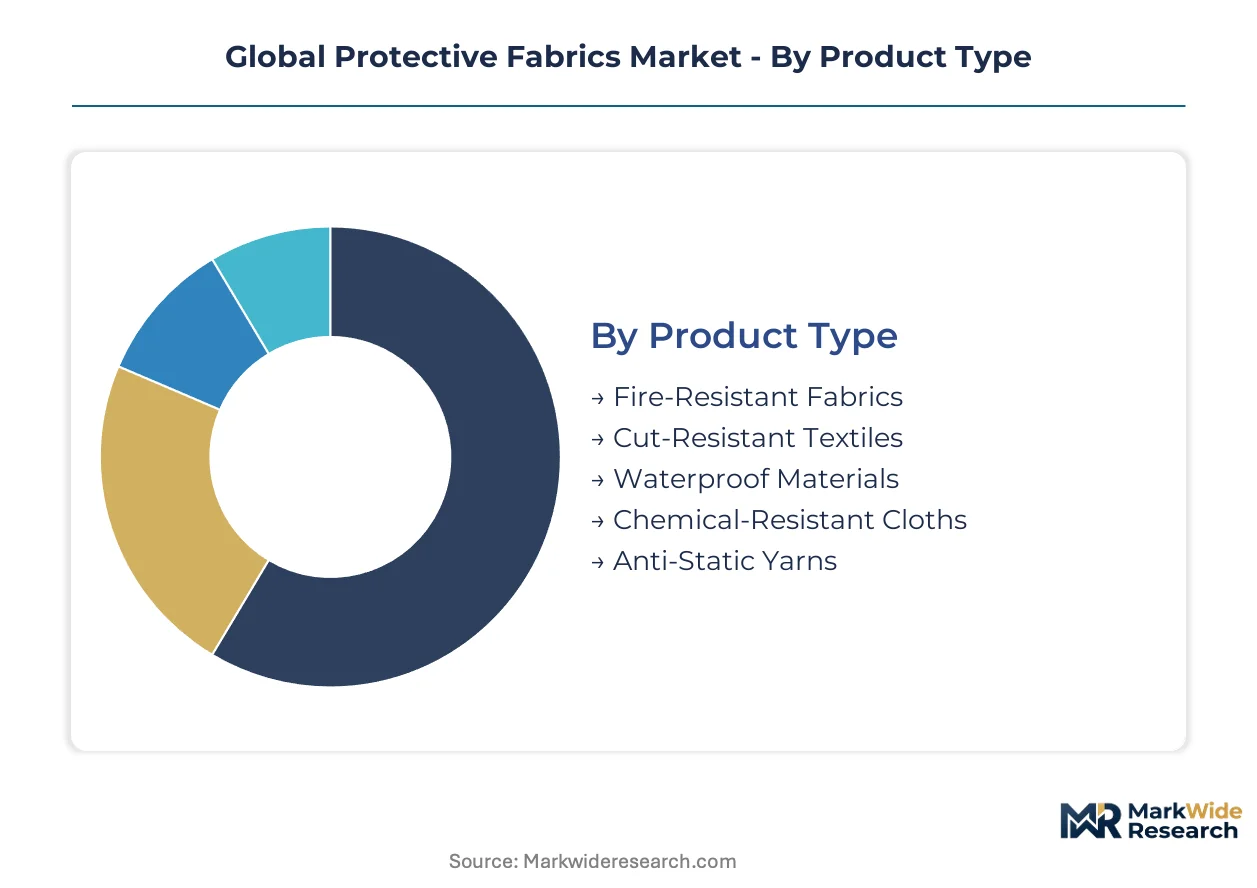
Protective fabrics command divergent pricing and certification pathways depending on hazard type and end-use intensity. Procurement specifications from municipal fire departments, national oil companies, and defense ministries fragment demand into distinct technical tiers with incompatible testing protocols.
Product Type:
Buyers prioritize certification grade over base material cost when specifying flame, chemical, or mechanical hazard protection.
- Fire-Resistant Fabrics:Meta-aramid and para-aramid woven systems dominate turnout gear specifications under NFPA 1971 and EN ISO 11612 protocols. Municipal fire departments in the United States and Germany concentrate procurement volume through multi-year fleet replacement programs.
- Cut-Resistant Textiles:High-performance polyethylene and composite yarns achieve EN 388 Level 5 ratings for metal fabrication and glass handling operations. European automotive assembly plants and Japanese shipyards drive specification upgrades as robotic handling systems reduce human exposure to severe laceration hazards.
- Waterproof Materials:Membrane-laminated constructions with PTFE or polyurethane layers protect outdoor utility workers. ECHA PFAS restrictions are forcing substitution toward silicone-based breathable barriers.
- Chemical-Resistant Cloths:Fluoropolymer-coated or multilayer barrier fabrics block permeation per EN 943 standards. Hazmat teams and pharmaceutical cleanroom operators specify these for vapor and liquid chemical exposure.
- Anti-Static Yarns:Carbon-core conductive fibers dissipate electrostatic discharge in petrochemical loading facilities. China's GB 12014-2019 mandate requires these in state-owned refinery operations.
Fire-Resistant Fabrics leads on scale; Nanofiber-enhanced variants within Chemical-Resistant Cloths lead on momentum.
End Use Industry:
Regulatory enforcement intensity and workforce unionization rates determine replacement frequency and performance tier selection.
- Oil & Gas Extraction:Offshore platform operators and pipeline maintenance crews require multi-hazard protection combining flame resistance, chemical splash protection, and visibility enhancement. Saudi Aramco and PetroChina procurement frameworks mandate direct mill relationships with integrated testing laboratories.
- Emergency Services:Structural firefighting, wildland suppression, and technical rescue operations each demand distinct fabric architectures. German fire service equipment manufacturers integrate electrospun nanofiber layers between outer shells and thermal liners to reduce ensemble weight.
- Construction:High-visibility flame-resistant apparel dominates commercial building and infrastructure projects. OSHA enforcement of workplace hazard assessments in American construction directly converts compliance into fabric procurement volume.
- Manufacturing Plants:Metal fabrication, chemical processing, and electronics assembly each specify different hazard combinations. Indian technical textile investments under the PLI scheme target this fragmented demand base.
- Transportation Sector:Rail maintenance crews and airport ground handling staff specify arc-flash and high-visibility combinations. European rail operators mandate EN ISO 20471 visibility certification alongside flame resistance.
Emergency Services leads on scale; Oil & Gas Extraction leads on momentum.
Application:
Garment architecture complexity and certification timeline duration segment margin pools across standardized and custom-engineered solutions.
- Military Uniforms:Multi-threat performance requirements combining flame resistance, infrared signature management, and ballistic protection justify premium pricing over standard industrial workwear. Defense procurement in the United States, China, and Germany concentrates volume through national textile reserve programs.
- Workwear:Industrial laundry service contracts drive recurring revenue through rental programs serving manufacturing and logistics sectors. North American and European rental operators consolidate supplier rosters to pre-qualified mills with vertical testing capabilities.
- Protective Gear:Gloves, aprons, and sleeve systems for specific task hazards supplement full garment programs. Japanese automotive suppliers specify cut-resistant gloves with touchscreen-compatible coatings.
- Safety Equipment:Tents, shelters, and temporary containment systems use coated fabrics for hazardous material response. German chemical suppliers accelerate plasma-induced grafting technologies for water-repellent finishes without fluorinated inputs.
- Industrial Covers:Welding blankets, machinery shields, and spark containment barriers use heavy-duty woven constructions. Petrochemical facility maintenance programs in the Middle East specify these for hot work permits.
Workwear leads on scale; Military Uniforms leads on momentum.
Material Technology:
Patent estate breadth and raw material supply concentration determine competitive moats and pricing power within fiber categories.
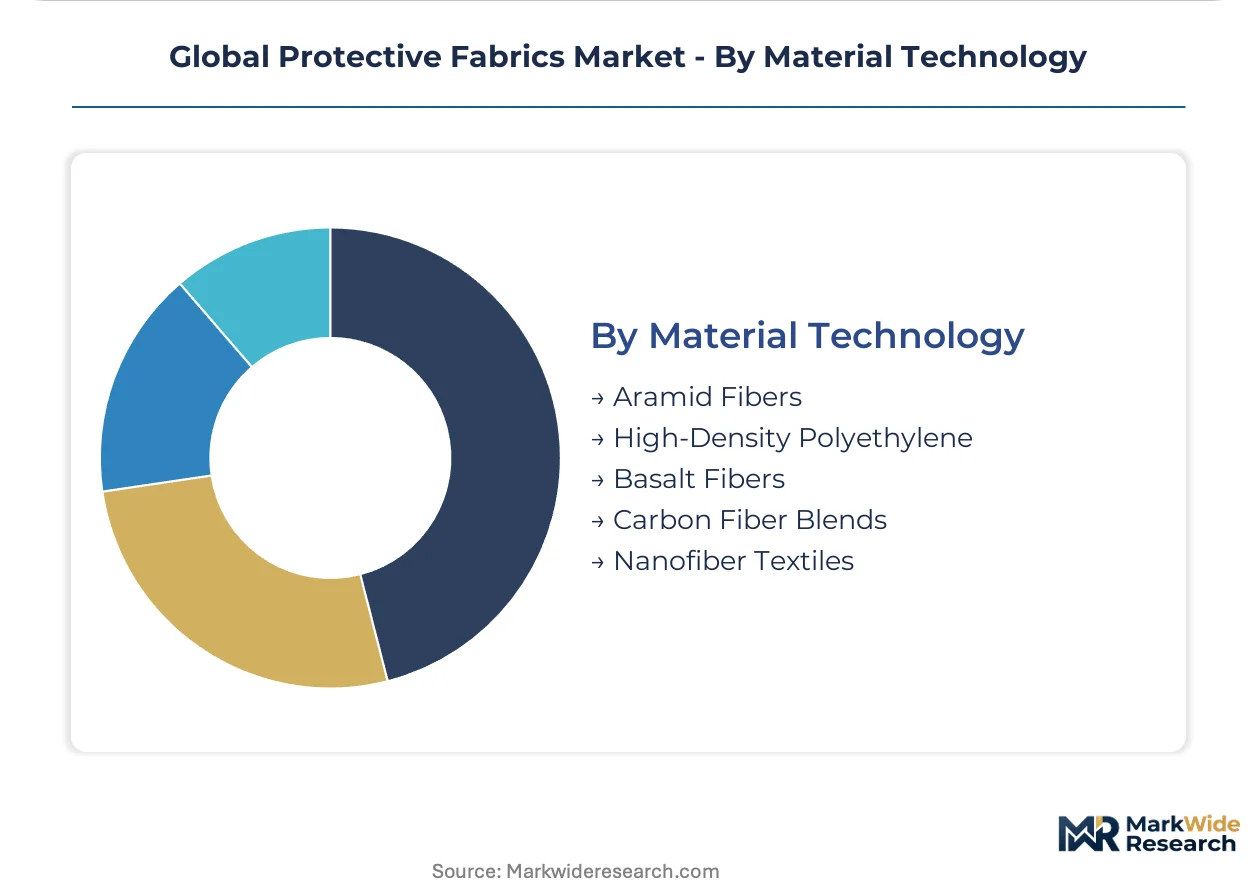
- Aramid Fibers:Meta-aramid for thermal protection and para-aramid for cut and ballistic resistance remain entrenched in fire service and electrical utility specifications. Three producers control over eighty percent of global para-aramid supply, creating vulnerability to trade restrictions.
- Nanofiber Textiles:Electrospun webs from polymer solutions achieve sub-micron filtration efficiency at fractions of traditional barrier fabric weight. Specialized nanofiber producers in Germany and the United States bypass traditional textile converters to sell directly to finished garment manufacturers.
- High-Density Polyethylene:Gel-spun fibers deliver cut protection and ballistic performance at lower density than aramid alternatives. Maritime and offshore applications favor these for water-resistance and chemical inertness.
- Basalt Fibers:Volcanic rock-derived filaments offer thermal stability and acoustic damping for industrial insulation and fire barriers. Russian and Chinese producers dominate raw fiber supply.
- Carbon Fiber Blends:Conductive properties enable anti-static and electromagnetic shielding functions. Aerospace ground crew and electronics manufacturing cleanrooms specify these for electrostatic discharge control.
Aramid Fibers leads on scale; Nanofiber Textiles leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting production investment toward compliance-friendly locations. Manufacturers face asymmetric cost burdens as EU REACH restrictions on PFAS chemistry outpace American state-level phase-outs, while China's GB standards create protected procurement channels for domestic mills.
United States
Municipal fire departments drive specification upgrades under NFPA 1971 thermal performance revisions. OSHA workplace hazard assessments convert regulatory compliance directly into fabric procurement volume across manufacturing plants. North Carolina and South Carolina textile clusters host integrated testing laboratories serving consolidated utility purchasing programs.
Germany
Fire service equipment manufacturers integrate electrospun nanofiber layers to reduce ensemble weight in structural turnout gear. ECHA PFAS restriction proposals under REACH Annex XVII eliminate C8 and C6 fluorocarbon water-repellent chemistries from domestic supply chains. Bavarian chemical suppliers accelerate plasma-induced grafting technologies as finishing alternatives.
China
State-owned petrochemical enterprises expand aramid fiber procurement under mandatory GB 12014-2019 anti-static workwear requirements. Domestic producers restructure capacity allocation toward military and aerospace programs. Yangtze River Delta industrial corridors concentrate technical textile manufacturing for defense applications.
India
Production-linked incentives under the PLI scheme for technical textiles attract greenfield investment in Gujarat and Tamil Nadu. Fragmented demand from metal fabrication and chemical processing plants creates entry opportunities for mid-scale mills. Mumbai-Pune industrial belt hosts emerging fabric finishing operations targeting export certification.
Saudi Arabia
National oil company procurement frameworks mandate direct mill relationships with integrated testing capabilities for offshore platform operators. Multi-year uniform programs concentrate volume through single-source agreements covering flame-resistant and chemical-splash protection. Eastern Province petrochemical corridors anchor Middle Eastern demand concentration.
Global Protective Fabrics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue nanofiber specialization and bio-based finishing alternatives. The market structure reflects moderate consolidation among aramid fiber suppliers alongside fragmentation in downstream fabric conversion. Three strategic archetypes dominate: integrated polymer-to-textile manufacturers, membrane-laminate technology specialists, and regional converters serving protected procurement channels. Competitive moves center on backward integration into fiber production and direct-to-utility procurement platform development.
Among diversified materials conglomerates, DuPont and 3M occupy positions representing heritage manufacturing scale and cross-industry technology application. Teijin Limited exemplifies the integrated Asian supply chain archetype with polymer-to-finished-textile control. These three entities anchor distinct competitive vectors—American defense contract access, multi-sector technology leverage, and captive Asian market supply—without overlapping strategic positioning.
| Leading Market Players |
|---|
| DuPont |
| 3M |
| Honeywell |
| Milliken & Company |
| Teijin Limited |
| W. L. Gore & Associates |
| TenCate Protective Fabrics |
| Lakeland Industries |
| Klopman International |
| Others |
Supply & Pricing Matrix
Electrospun nanofiber membrane adoption is compressing traditional laminated construction costs while fragmenting supply relationships as specialized producers bypass established textile converters. This technology shift simultaneously erodes margin pools for legacy membrane-laminate specialists and creates pricing power for nanofiber equipment manufacturers serving German and American fire service equipment makers.
Pricing Analysis
Distributor margins in municipal fire department procurement compress as consolidated utility purchasing programs negotiate direct mill relationships. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under NFPA 1971 and EN ISO 11612 protocols. Cost compression in mid-tier aramid fabrics is intensifying because Chinese state-owned enterprises restructure domestic capacity allocation. National oil companies exhibit lowest price sensitivity; rental laundry operators serving manufacturing plants show highest sensitivity to per-meter fabric costs.
Supply Chain Analysis
Certification gating through EN ISO 11612, EN 388, and EN 943 multi-hazard testing concentrates qualified supply among Western European and North American mills with captive laboratory capacity. Raw material supply draws from para-aramid fiber production concentrated in the United States, Japan, and China alongside high-performance polyethylene gel-spun fiber from the Netherlands and United States. Single-source vulnerability in para-aramid feedstock creates exposure to geopolitical trade restrictions or producer capacity reallocation. Distribution runs through direct mill relationships mandated by Saudi Aramco and PetroChina procurement frameworks, bypassing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protective fabrics market represents a late-cycle quality story as municipal fire departments and national oil companies prioritize multi-threat performance specifications over unit cost minimization. Premium tier demand from wildland fire management agencies and offshore platform operators justifies sustained margin structures despite input cost volatility.
For Market Incumbents: To counter PFAS chemistry phase-out threats, accelerate plasma-induced grafting technology deployment and secure backward integration into bio-based water-repellent feedstocks. Capture channel control by building direct-to-utility procurement platforms that bypass industrial distribution intermediaries in electrical utility segments.
For New Entrants and Emerging Players: Launch via specialized nanofiber barrier layer supply to German fire service equipment manufacturers seeking weight reduction in structural turnout gear. Target India's PLI scheme incentives for technical textiles in Gujarat and Tamil Nadu corridors. Penetrate through rental laundry service contracts serving fragmented metal fabrication and chemical processing demand.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabric converters with integrated testing laboratories but limited fiber production control. Long-term viability hinges on certification moat durability and regulatory chemistry transition execution. Watch ECHA PFAS restriction implementation timelines as inflection indicator for finishing technology substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Para-Aramid Fiber Production | Captures margin from three-producer supply concentration serving defense and fire service procurement. |
| Plasma-Induced Grafting Technology Deployment | Replaces fluorinated water-repellent chemistries eliminated by REACH Annex XVII restrictions. |
| Direct-to-Utility Procurement Platform Launch | Bypasses distributor intermediaries in consolidated electrical utility and oil company purchasing programs. |
| Nanofiber Membrane Integration Partnership | Reduces ensemble weight for German and American fire service equipment manufacturers. |
| India PLI Scheme Manufacturing Investment | Accesses production-linked incentives for technical textiles in Gujarat and Tamil Nadu industrial corridors. |
Research Methodology
Direct dialogue with fire service equipment procurement directors, textile mill technical directors, petrochemical facility safety managers, and industrial laundry service operators grounded qualitative assessment. Secondary validation drew from NFPA standard revision documentation, ECHA regulatory filings, Chinese GB standard publications, and customs trade data. Bottom-up and top-down triangulation reconciled fiber producer capacity disclosures with end-use procurement volume estimates.
Bottom-up modeling segmented volume and value across material technology, hazard type, and end-use intensity dimensions. The analytical framework projected replacement cycle timing for municipal fire department fleet programs and state-owned enterprise uniform mandates. CAGRs were derived from regression analysis of historical procurement patterns against regulatory enforcement intensity indices. Industry-specific inputs included OSHA workplace assessment citation rates and ECHA restriction proposal implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS chemistry bans or para-aramid supply disruptions. Projections reflect assumptions on certification timeline durations and raw material supply continuity. A model refresh is warranted upon material change in REACH Annex XVII implementation scope or Chinese military procurement priority shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Global Industrial Protective Clothing Fabrics Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
High Visibility Clothing Market