
 Global Fire Resistant Fabric Market | 2026-2036
Global Fire Resistant Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire Resistant Fabric Market Analysis
Project finance and operational leasing for protective apparel programs is narrowing the competitive field to firms with balance-sheet depth and long-dated contract capacity. DuPont leverages its backward integration into aramid polymer production to sustain margin capture across the value chain. TenCate Protective Fabrics anchors its position through dedicated weaving and finishing assets in European and North American manufacturing clusters. Milliken & Company differentiates via proprietary chemical treatment platforms that extend fabric durability under repeated thermal exposure.
Fire resistant fabric denotes textile engineered to resist ignition, inhibit flame propagation, and maintain structural integrity when exposed to heat flux exceeding specific thresholds, typically achieved through inherent aramid fibers or cotton substrates treated with phosphorus-based flame retardants. These materials serve primarily to protect personnel in environments with thermal, arc flash, or molten metal hazards. Aramid-based protective clothing commands the dominant value share due to its inherent non-flammability and strength-to-weight ratio, while glass fiber industrial curtains occupy a specialized but expanding niche in welding and smelting operations. Cotton flame-retardant treatments retain cost-sensitive volume in construction and general industrial applications where laundering cycles are less intensive.
OSHA workplace safety mandates, the EU PPE Regulation enforced by national market surveillance authorities, and NFPA 2112 certification requirements for flash fire protection collectively elevate minimum performance benchmarks and compress market access for uncertified suppliers. The EU F-Gas Regulation and REACH chemical restrictions further constrain formulation choices for flame-retardant chemistries, pushing investment toward halogen-free alternatives. Stakeholders must monitor evolving certification reciprocity between UL, EN ISO, and emerging Gulf standards as procurement specifications in Middle Eastern oil and gas projects diverge from legacy North American and European templates.
Market Dynamics
OSHA enforcement actions and EU PPE Regulation compliance deadlines are compressing procurement cycles, forcing industrial buyers to accelerate material certification timelines and consolidate supplier relationships around vertically integrated aramid producers.
Growth Catalysts
- NFPA 2112 Certification Mandates:Flash fire protection standards in US petrochemical operations now require third-party certified garments, eliminating untreated cotton from procurement lists and redirecting volume toward engineered aramid blends.
- Permian Basin Capacity Expansion:Oil and gas operators in West Texas and New Mexico are scaling workforce protective apparel programs to match drilling intensity, creating sustained pull for NFPA-certified coveralls and station wear.
- Halogen-Free Chemistry Transition:REACH restrictions on brominated flame retardants are accelerating formulation shifts toward phosphorus-based and bio-based alternatives that maintain laundering durability.
Market Restraints
- Meta-Aramid Monopoly Structure:Polymer supply concentrates among two dominant producers, creating input cost volatility when capacity constraints emerge in European and Asian manufacturing nodes.
- EU F-Gas Regulation Compliance:Fluorinated finishing agents used in water-repellent treatments face phase-down schedules, forcing reformulation investments that extend R&D timelines by 18-24 months.
- Cotton Price Arbitrage:Untreated cotton remains 40-60% cheaper than treated alternatives, preserving cost-sensitive volume in construction and general industrial segments where thermal hazard exposure is intermittent.
Strategic Opportunities
- Middle East Procurement Divergence:Saudi Aramco and ADNOC projects are developing Gulf-specific certification templates that favor suppliers with dual UL-EN ISO accreditation, creating first-mover advantages for certified European weavers.
- Electric Arc Flash Expansion:Utility sector electrification investments are extending NFPA 70E compliance requirements to secondary substation crews previously exempt from arc-rated clothing mandates.
- Digital Specification Platforms:Industrial distributors are deploying online configurators that bypass traditional mill-direct relationships, enabling mid-tier fabric producers to access fragmented construction and maintenance accounts.
Industry Challenges
- Certification Timeline Compression:Third-party testing backlogs at UL and Intertek extend product launch cycles, straining working capital for specialty finishers without captive laboratory capacity.
- Multi-Standard Harmonization:Divergent thermal performance testing protocols between EN ISO 11612 and NFPA 2112 force redundant development runs, complicating inventory positioning for multinational industrial laundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire Resistant Fabric Market |
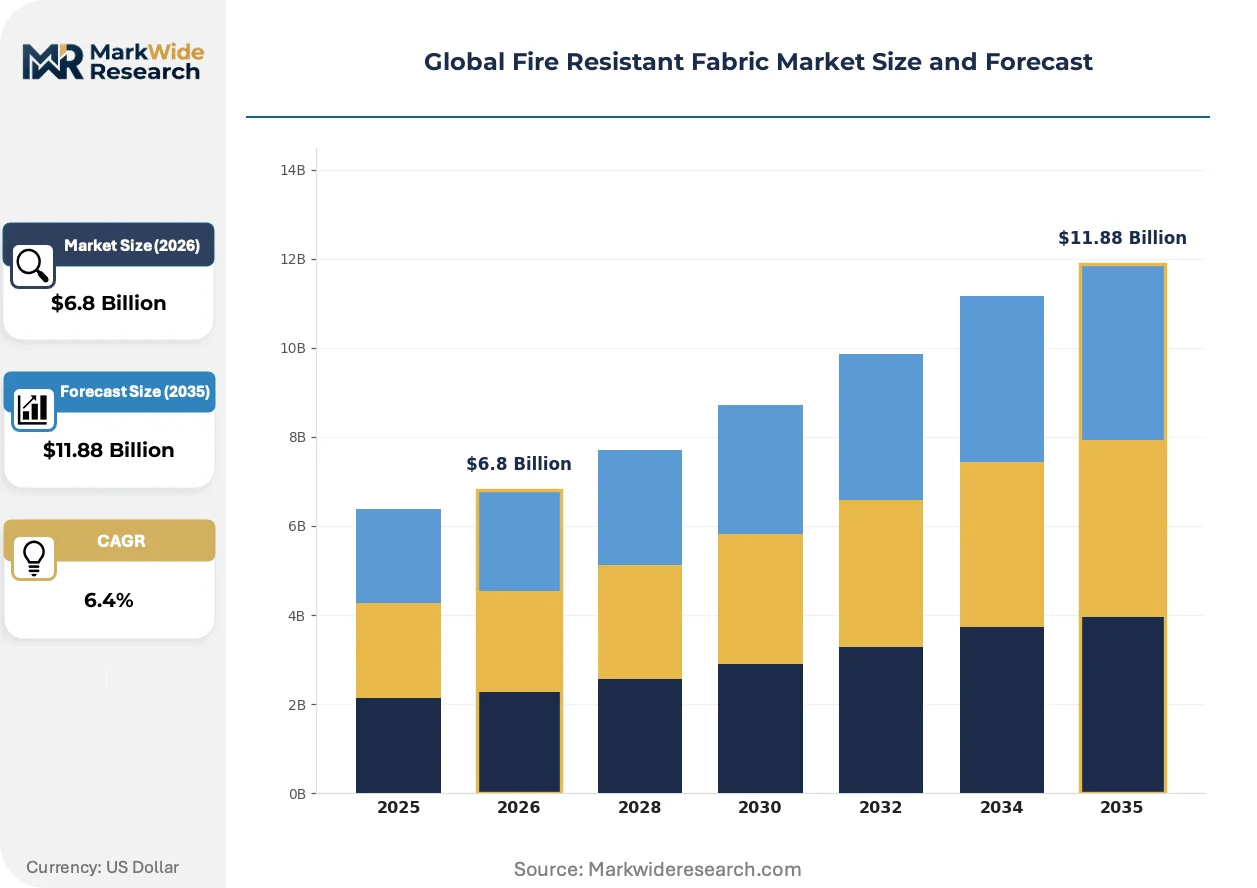
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aramid, Cotton, Polyester, Glass Fiber End User: Aerospace, Construction, Automotive, Oil & Gas Application: Protective Clothing, Upholstery, Industrial Curtains, Fire Blankets Certification: NFPA, UL, ISO, EN |
| Companies Covered | Teijin Aramid, TenCate Protective Fabrics, DuPont, W. L. Gore & Associates, Lenzing, Milliken & Company, Kaneka Corporation, Indorama Ventures, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire Resistant Fabric Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning around durability performance rather than initial cost, with procurement specifications increasingly weighting lifecycle cost-per-wash metrics.
Hybrid aramid-cellulosic constructions are migrating from niche military applications into mainstream industrial protective apparel. Municipal fire departments in Germany and utility cooperatives in the American Midwest are piloting these blends to reduce thermal burden while maintaining NFPA structural firefighting ratings. The migration from pure aramid systems is compressing premium pricing tiers and forcing incumbent polymer producers to demonstrate wash-durability equivalence.
ECHA's 2023 restriction proposal on per- and polyfluoroalkyl substances (PFAS) is eliminating durable water-repellent finishes from EU-certified protective clothing. Finishers in the Netherlands and northern Italy are accelerating silicone-based and hydrocarbon alternative development programs. The welding and molten metal splash segments, where surface repellency directly correlates with burn protection, are experiencing the most acute formulation disruption.
Industrial laundries are consolidating garment procurement through multi-year service agreements that bundle rental, cleaning, and replacement. Chemical plant operators in Louisiana and refinery maintenance contractors in Rotterdam are displacing traditional purchase-and-own models with per-wear pricing structures. This behavioral shift is most visible in North American petrochemical corridors where integrated service providers leverage route density to undercut standalone distributors.
Global Fire Resistant Fabric Market Segmentation
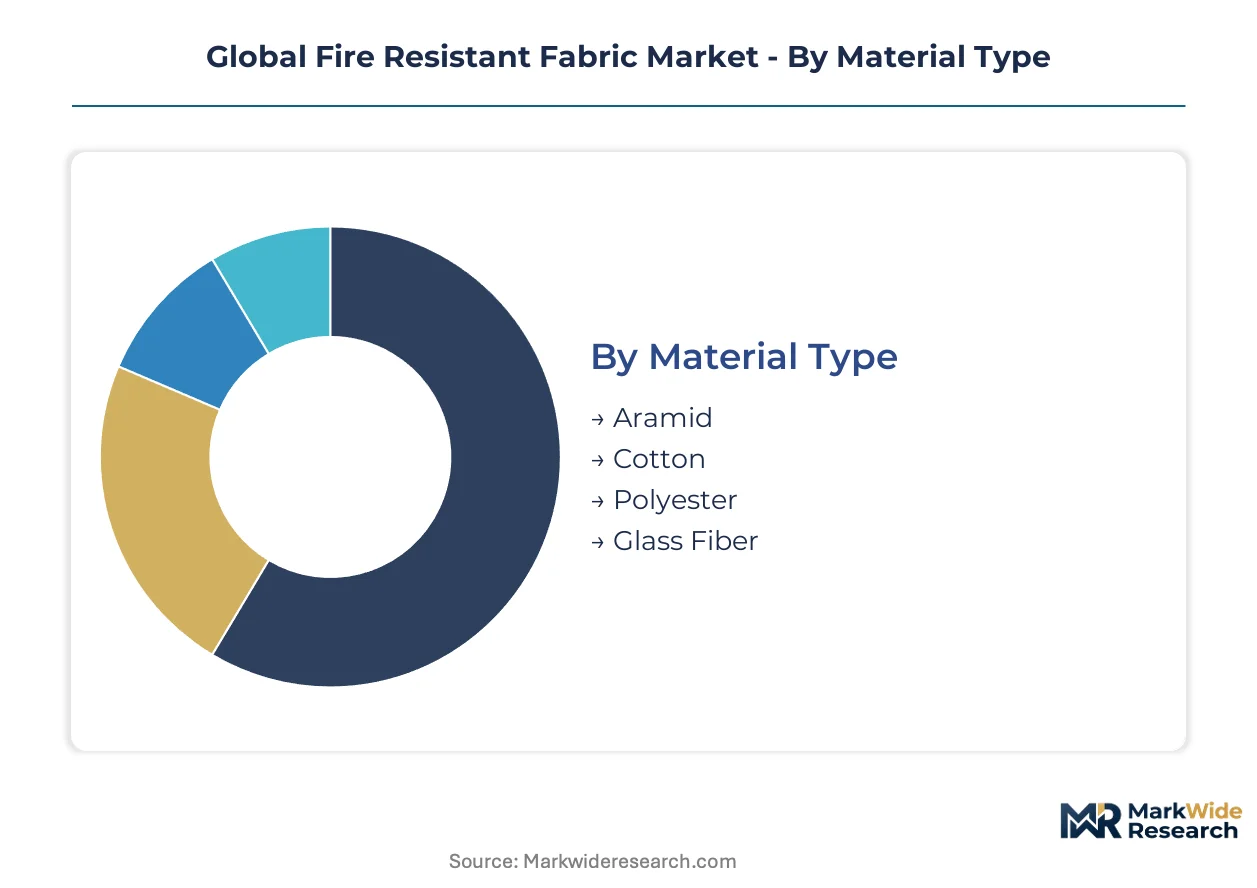
Segmentation in fire resistant fabrics separates procurement specifications by thermal hazard intensity, regulatory jurisdiction, and lifecycle cost structure. Buyers in oil and gas operations prioritize inherent flame resistance over treated alternatives due to laundering durability requirements. Certification alignment with regional safety mandates determines supplier qualification and contract eligibility across end-use verticals.
Material Type:
Replacement cycles vary dramatically: aramid garments last 3-5 years in heavy industrial use, while treated cotton requires renewal every 12-18 months in high-laundering environments.
- Aramid:Inherent non-flammability derived from aromatic polyamide molecular structure eliminates finish degradation through repeated industrial washing. Demand concentrates in Permian Basin drilling operations where NFPA 2112 mandates have eliminated cotton alternatives from flash fire exposure zones.
- Cotton:Cellulosic substrates receive phosphorus-based flame retardant treatments that bond to fiber surfaces through pad-dry-cure finishing sequences. Construction contractors in the American Southeast retain this segment for intermittent welding protection where thermal exposure remains below sustained ignition thresholds.
- Polyester:Synthetic fiber char-forming modifications create protective textiles at lower basis weights than cellulosic alternatives. Automotive seating applications in German and Japanese manufacturing clusters drive specification development.
- Glass Fiber:Silica-based non-combustible textiles woven from continuous filament yarns withstand molten metal splash temperatures exceeding 1000°C. Welding curtain installations in Rotterdam and Houston port facilities anchor this segment.
Aramid dominates installed base. Glass fiber is where expansion concentrates.
End User:
Procurement scale separates this category: oil and gas operators contract for thousands of garment units annually, while aerospace buyers specify small-lot engineered textiles with extended qualification timelines.
- Aerospace:Aircraft interior fabrics must satisfy FAA flammability standards for seat upholstery and cargo compartment liners. Boeing and Airbus tier-one suppliers in Wichita and Toulouse enforce lot-traceable fiber sourcing.
- Construction:Site-specific hazard assessments drive intermittent procurement of arc-rated shirts and welding blankets. General contractors in Texas and Florida bulk-purchase treated cotton for subcontractor distribution.
- Automotive:Electric vehicle battery enclosure insulation and charging cable sheathing create new specification categories. Korean and German OEMs are qualifying aramid nonwovens for thermal runaway containment.
- Oil & Gas:Integrated operators in West Texas and the North Sea mandate NFPA-certified coveralls for all personnel entering process areas. ExxonMobil and Shell procurement templates now require third-party certified fabric lots with chain-of-custody documentation.
Oil and gas commands the largest contract values. Automotive is climbing the fastest as electrification reshapes material requirements.
Application:
Performance durability separates segments: protective clothing undergoes 50-100 industrial laundering cycles annually, while fire blankets remain in static storage with minimal mechanical stress.
- Protective Clothing:Garment systems combine outer shells, moisture barriers, and thermal liners in multi-layer configurations. Municipal fire departments in Germany and utility cooperatives in the American Midwest are piloting hybrid aramid-cellulosic constructions to reduce thermal burden.
- Upholstery:Public venue seating in airports, stadiums, and hospitals requires cigarette-ignition resistance under California Technical Bulletin 133 and equivalent state fire codes. Contract furniture manufacturers in North Carolina specialize in this specification tier.
- Industrial Curtains:Flexible welding screens and smelter splash guards utilize glass fiber or silica cloth with grommeted edges for track mounting. Aluminum smelters in Quebec and Iceland specify these barriers for potline maintenance access.
- Fire Blankets:Compact emergency suppression textiles deploy from wall-mounted cabinets for kitchen and laboratory use. British Standards Institution certification dominates European institutional procurement.
Protective clothing generates the highest fabric tonnage. Industrial curtains are gaining share fastest as automated welding cell adoption accelerates.
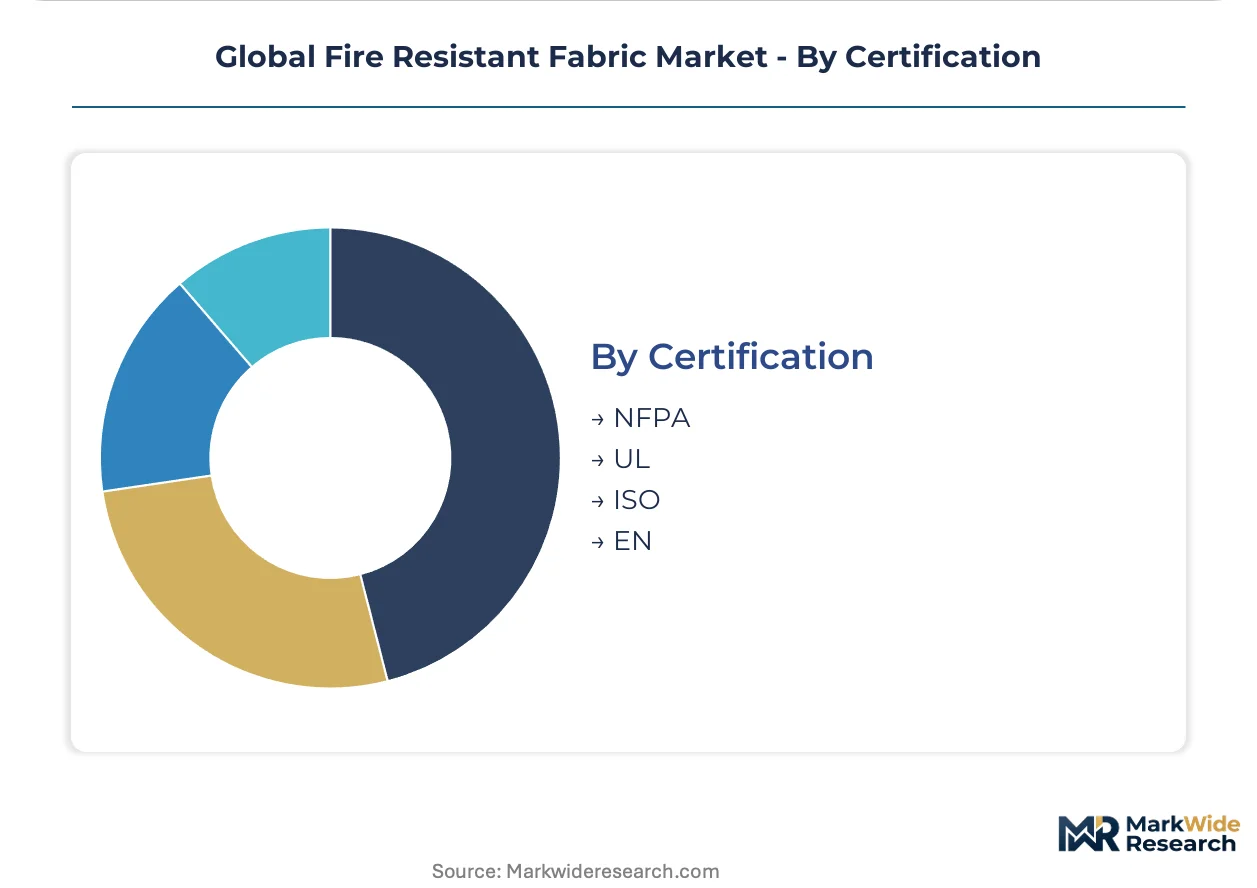
Certification:
Testing protocol divergence creates regional supply fragmentation: North American buyers prioritize flash fire simulation, while European specifications emphasize radiant heat and molten metal splash resistance.
- NFPA:National Fire Protection Association standards 2112 and 2113 govern flash fire protective garments through instrumented manikin testing with 3-second flame exposure. US petrochemical operators treat this certification as a procurement gate.
- UL:Underwriters Laboratories conducts independent third-party verification of fabric flame resistance and thermal shrinkage. Industrial laundries in Louisiana and Rotterdam require UL-listed fabrics to maintain service agreement compliance.
- ISO:International Organization for Standardization protocols enable cross-border specification harmonization for multinational oil and gas operators. Saudi Aramco projects increasingly reference ISO 11612 alongside legacy NFPA requirements.
- EN:European Norm standards enforced by national market surveillance authorities mandate CE marking for personal protective equipment. REACH chemical restrictions constrain finish formulations for EN-certified textiles.
NFPA governs the largest addressable market. EN is where regulatory complexity is expanding most quickly as ECHA restrictions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA enforcement actions and EU PPE Regulation compliance deadlines are compressing procurement cycles, forcing industrial buyers to accelerate material certification timelines and consolidate supplier relationships around vertically integrated aramid producers.
United States
Petrochemical capacity expansion in the Permian Basin and federal infrastructure investment are pulling significant fabric volume. OSHA workplace safety mandates and NFPA 2112 certification requirements for flash fire protection elevate minimum performance benchmarks. Oil and gas operators in West Texas and New Mexico are scaling workforce protective apparel programs to match drilling intensity.
Germany
Municipal fire departments are piloting hybrid aramid-cellulosic constructions to reduce thermal burden while maintaining structural firefighting ratings. ECHA's 2023 restriction proposal on PFAS is eliminating durable water-repellent finishes from EU-certified protective clothing. Finishers in the Netherlands and northern Italy are accelerating silicone-based alternative development programs.
China
Dual carbon goals and industrial safety standardization are driving upgrades in steel mill and chemical plant protective equipment. The country's national market surveillance authorities are aligning enforcement with emerging GB standards for thermal protective textiles. Manufacturing clusters in the Yangtze River Delta are expanding weaving and finishing capacity for export-certified fabrics.
Saudi Arabia
Saudi Aramco projects are developing Gulf-specific certification templates that favor suppliers with dual UL-EN ISO accreditation. ADNOC procurement specifications are diverging from legacy North American and European templates. Industrial cities in the Eastern Province are anchoring demand for high-temperature protective barriers in petrochemical processing zones.
Netherlands
Refinery maintenance contractors in Rotterdam are displacing traditional purchase-and-own models with per-wear pricing structures. EU F-Gas Regulation compliance deadlines are forcing reformulation investments that extend R&D timelines. Integrated service providers leverage route density to undercut standalone distributors in the Antwerp-Rotterdam petrochemical corridor.
Global Fire Resistant Fabric Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated polymer producers and specialized weaving operations with captive finishing assets. The vendor base separates into three distinct tiers: multinational chemical conglomerates with backward integration into aramid polymer production, dedicated protective fabric weavers with regional manufacturing clusters, and specialty finishers focused on proprietary treatment platforms. Dominant competitive moves include capacity expansion in European and North American manufacturing nodes and strategic partnerships to secure halogen-free chemistry supply chains.
Within the integrated chemical tier, DuPont and Teijin Aramid exemplify producers with captive polymer supply chains that capture margin across multiple value chain stages. TenCate Protective Fabrics represents the dedicated weaving specialist archetype, anchoring market position through concentrated manufacturing assets in key demand regions. These three firms collectively illustrate how supply-side configuration determines contract eligibility for NFPA-certified and EN ISO-compliant procurement channels.
| Leading Market Players |
|---|
| Teijin Aramid |
| TenCate Protective Fabrics |
| DuPont |
| W. L. Gore & Associates |
| Lenzing |
| Milliken & Company |
| Kaneka Corporation |
| Indorama Ventures |
| Solvay |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese meta-aramid polymer production is forcing European suppliers into selective idling, tightening supply discipline and compressing margin capture for non-integrated finishers dependent on spot polymer purchases.
Pricing Analysis
Certification level creates the primary spread between transaction tiers, with NFPA 2112-certified aramid blends commanding substantial premiums over EN ISO 11612 equivalents due to testing backlog scarcity at UL facilities. Three-tier pricing structure separates incumbent polymer producers from dedicated weavers and specialty finishers, with backward integration determining which tier a supplier occupies. Cost compression in treated cotton segments is intensifying because construction buyers retain purchasing autonomy and exploit cotton price arbitrage. Municipal fire departments exhibit the least price sensitivity due to lifecycle cost-per-wash procurement metrics, while general industrial contractors in the American Southeast remain acutely cost-conscious.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing conversations as aramid fiber imports face potential duty escalation under trade remedy investigations. Manufacturing gravity centers on the United States, Germany, and China, with polymer production anchored in European and Asian nodes while finishing concentrates in regional weaving clusters. Meta-aramid monomer supply draws from petrochemical feedstocks vulnerable to naphtha price volatility, while phosphorus-based flame retardant chemistries hinge on phosphate rock availability from Moroccan and Chinese mines. Single-source vulnerability in polymer supply creates input cost spikes when Teijin or DuPont announce force majeure events. Distribution runs through industrial laundries consolidating garment procurement under multi-year service agreements that displace traditional mill-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of captive laboratory capacity for accelerated thermal testing is consolidating contract eligibility around firms with in-house certification resources, locking out specialty finishers without UL or Intertek partnerships.
For Market Incumbents: Build certification moats by expanding captive testing capacity at UL-listed facilities to compress product launch cycles and capture procurement from buyers facing third-party backlog delays. Deepen polymer supply security through long-term offtake agreements with meta-aramid producers, insulating against Teijin or DuPont force majeure exposure. Defend against halogen-free chemistry transition disruption by accelerating silicone-based water-repellent development programs ahead of ECHA PFAS enforcement deadlines. For New Entrants and Emerging Players: Establish a beachhead in Middle Eastern oil and gas procurement by securing dual UL-EN ISO accreditation ahead of Saudi Aramco and ADNOC Gulf-specific template finalization. Target automotive electrification applications where Korean and German OEMs are qualifying aramid nonwovens for battery thermal runaway containment, a segment with extended qualification timelines that favor patient capital. Penetrate through digital specification platforms that bypass incumbent mill-direct relationships and access fragmented construction accounts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across halogen-free chemistry development programs as ECHA restrictions extend R&D timelines and require redundant formulation testing. Viability over the coming decade rests on identifying specialty finishers with proprietary treatment platforms and established industrial laundry channel relationships rather than pure commodity weaving assets. Watch for inflection signals in Saudi Aramco procurement template releases, which will abruptly resegment supplier qualification tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | DuPont and Teijin capture margin across multiple value chain stages through captive aramid supply. |
| Halogen-Free Chemistry Transition | Finishers in the Netherlands accelerate silicone-based alternatives to meet ECHA PFAS restrictions. |
| Dual Certification Investment | European weavers secure first-mover advantage in Saudi Aramco procurement divergence. |
| Digital Platform Partnership | Mid-tier fabric producers access fragmented construction accounts through online configurators. |
| Multi-Year Service Agreement Expansion | Integrated providers in Louisiana displace standalone distributors through per-wear pricing structures. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating procurement directors at ExxonMobil and Shell, technical R&D leads at TenCate and Milliken, and industrial laundry service managers in Louisiana and Rotterdam. Secondary validation drew from OSHA enforcement databases, ECHA restriction proposals, NFPA certification registries, and customs trade data for aramid fiber imports. Bottom-up volume estimates from end-use segmentation were triangulated against top-down polymer production capacity assessments.
Calibration against historical certification timeline data and polymer price series anchored the analytical framework across the analysis window. Segmentation dimensions modeled include material type, end-user vertical, application intensity, and certification jurisdiction cluster. CAGRs were derived from regression analysis of procurement volume trends against regulatory compliance deadline schedules, with particular weighting applied to Permian Basin drilling intensity metrics and EU PPE enforcement action frequencies.
Stress conditions across meta-aramid supply disruptions, ECHA restriction acceleration, and Middle Eastern procurement template divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OSHA enforcement continuity and REACH chemical restriction implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Rainwear Market