
 Global Industrial Protective Clothing Fabrics Market | 2026-2036
Global Industrial Protective Clothing Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Protective Clothing Fabrics Market Outlook
Energy sector buyers are unwinding from legacy cotton-heavy specifications toward aramid and flame-retardant synthetic blends. DuPont de Nemours, Inc. anchors North American supply through integrated Kevlar fiber-to-fabric operations. W. L. Gore & Associates, Inc. differentiates via expanded polytetrafluoroethylene membrane laminates for chemical barrier protection. Sioen Industries NV controls European distribution through vertically coated fabric manufacturing in Belgium.
Industrial protective clothing fabrics are engineered textile systems combining inherent or treated fibers to achieve thermal stability, chemical impermeability, or mechanical resistance measured by arc rating and breakthrough time. These materials protect workers in environments with flash fire, molten metal splash, or hazardous liquid exposure. Aramid fabrics dominate structural value due to inherent flame resistance and durability under repeated thermal cycling. Cotton blends retain volume share in developing manufacturing economies where cost sensitivity overrides multi-hazard specifications. Flame retardant applications command premium positioning as NFPA 70E and EN ISO 11612 certification complexity raises technical barriers to supply.
OSHA enforces permissible exposure limits that mandate employer-provided protective equipment across US industrial facilities. EPA regulations on chemical handling and waste containment indirectly drive fabric barrier performance requirements. EU REACH restrictions on hazardous substance migration affect coating chemistry choices for European market access. Stakeholders must monitor evolving certification harmonization between ASTM F1506 and EN ISO standards as multinational procurement consolidates around unified test protocols.
Market Dynamics
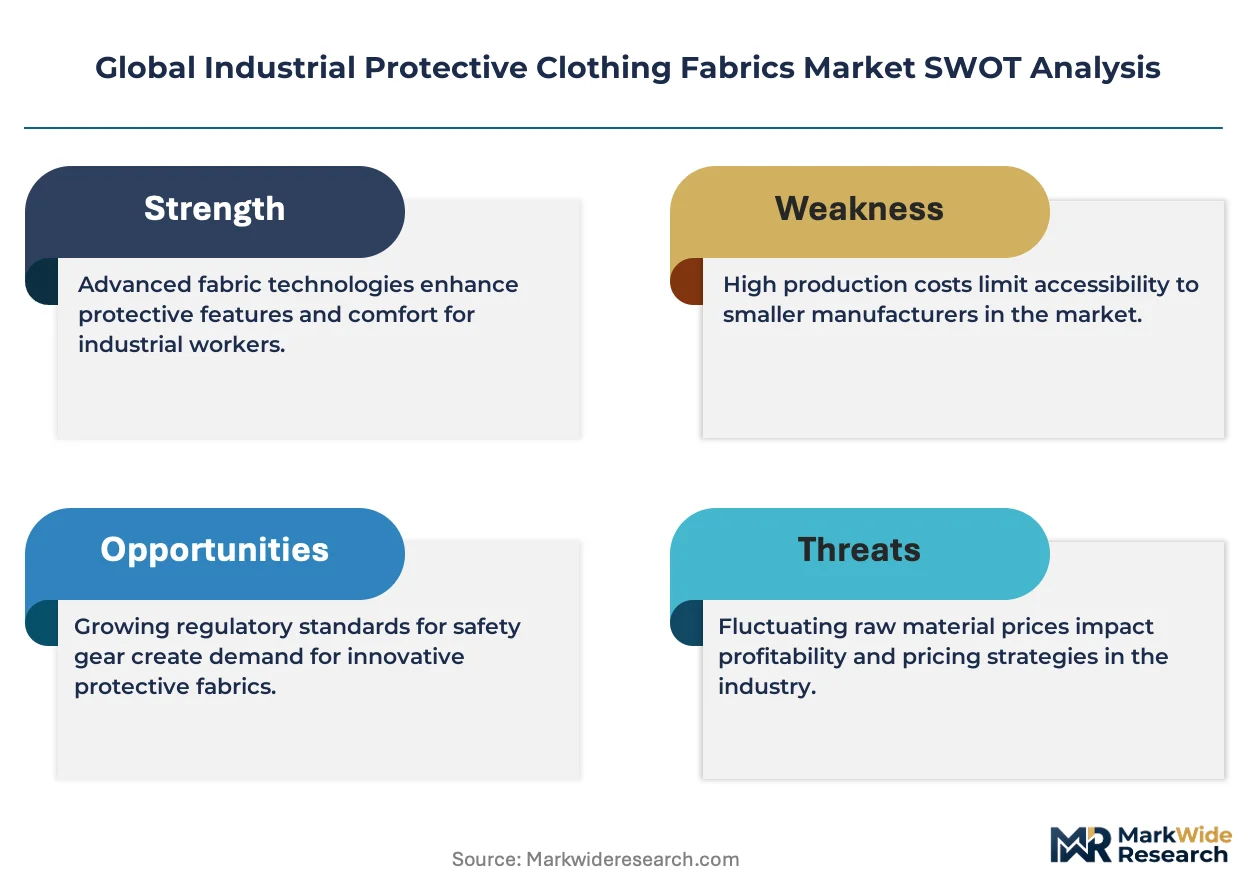
OSHA's tightening permissible exposure limits for chemical and thermal hazards are forcing employers across US manufacturing to upgrade from single-hazard cotton garments to certified multi-barrier fabric systems, compressing replacement cycles and elevating technical specifications throughout procurement.
Growth Catalysts
- REACH chemical restrictions:ECHA's evolving substance restrictions are compelling European chemical processors to replace legacy coated fabrics with advanced membrane laminates that eliminate hazardous plasticizers.
- Meta-aramid spunlace expansion:New production capacity in Zhejiang and Jiangsu provinces is lowering input costs for flame-resistant nonwovens serving Asia-Pacific oil and gas maintenance operations.
- NFPA 70E enforcement:Electrical utilities are mandating arc-rated daily wear, converting intermittent-use markets to continuous-protection specifications across North American transmission and distribution workforces.
Market Restraints
- Petrochemical input volatility:Meta-aramid and para-aramid polymers depend on benzene and p-phenylenediamine derivatives whose pricing fluctuates with crude oil and specialty chemical feedstock markets.
- DuPont Kevlar concentration:North American para-aramid supply remains captive to single-source fiber production, creating vulnerability for fabric converters during capacity allocation periods.
- Polytetrafluoroethylene membrane substitution:Emerging thermoplastic polyurethane barriers offer comparable chemical resistance at lower lamination costs for non-extreme temperature applications.
Strategic Opportunities
- India manufacturing expansion:BIS certification alignment with EN ISO 11612 is opening domestic procurement channels for multinational automotive and steel producers establishing local assembly operations.
- Wearable sensor integration:Convergence of fabric-embedded temperature and gas detection with traditional protective garments creates premium positioning for connected worker platforms in confined space entry.
- EU Green Deal procurement rules:Public sector tender requirements for recycled content and lifecycle assessment documentation favor European fabric producers with verified circular material flows.
Industry Challenges
- NFPA 2112 certification backlog:Third-party testing laboratory capacity constraints are extending flash fire garment approval timelines from 12 to 18 months, delaying new product introductions.
- Multi-hazard fabric engineering complexity:Simultaneous arc, flash fire, and chemical splash protection requires conflicting material properties that increase R&D iteration cycles and prototyping costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Protective Clothing Fabrics Market |
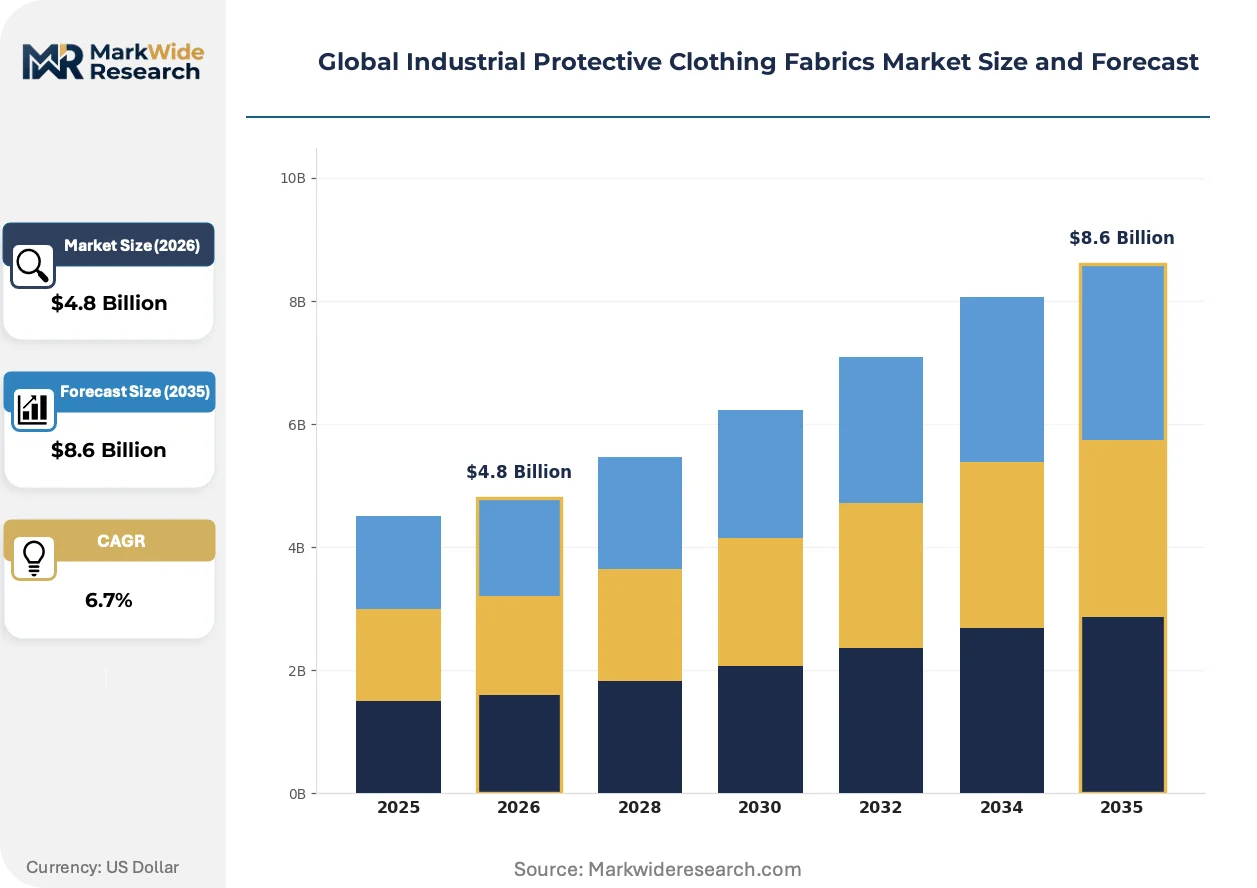
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fabric Type: Aramid, Cotton, Polyester, Polypropylene End User: Manufacturing, Construction, Oil & Gas, Healthcare Application: Flame Retardant, Chemical Resistant, Cut Resistant, High Visibility Certification Level: EN ISO 11611, EN ISO 11612, NFPA 70E, ASTM F1506 |
| Companies Covered | W. L. Gore & Associates, Inc., Lakeland Industries, Inc., DuPont de Nemours, Inc., Kermel, Sioen Industries NV, 3M Company, Milliken & Company, Glen Raven, Inc., Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Protective Clothing Fabrics Market Strategic Shifts
Material science breakthroughs and regulatory harmonization pressures are converging to redefine performance benchmarks across thermal, chemical, and mechanical protection categories. Fabric architectures are evolving from layered assemblies toward engineered single-ply systems.
Phase-change material microencapsulation is supplanting traditional moisture-wicking base layers in high-heat industrial environments. Foundries and aluminum smelters in Germany and the US Gulf Coast are specifying these thermoregulating fabrics for molten metal splash protection. The technology is compressing the three-layer garment system into dual-layer configurations, reducing bulk weight and laundering costs while maintaining EN ISO 11612 certification.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluorocarbon treatments from stain-resistant and oil-repellent fabric finishes. European protective clothing manufacturers are reformulating durable water-repellent chemistries with silicone and hydrocarbon alternatives. The transition is most acute in Benelux chemical processing hubs where ECHA enforcement inspections have accelerated compliance timelines.
Consolidated national oil company procurement is displacing fragmented distributor networks across Middle Eastern petrochemical complexes. Saudi Aramco and ADNOC are mandating direct supplier relationships with certified fabric mills to ensure batch traceability and consistent arc rating documentation. This behavioral shift is visible across new refinery and downstream chemical projects in Jubail Industrial City and Ruwais Derivatives Complex.
Global Industrial Protective Clothing Fabrics Market Segmentation
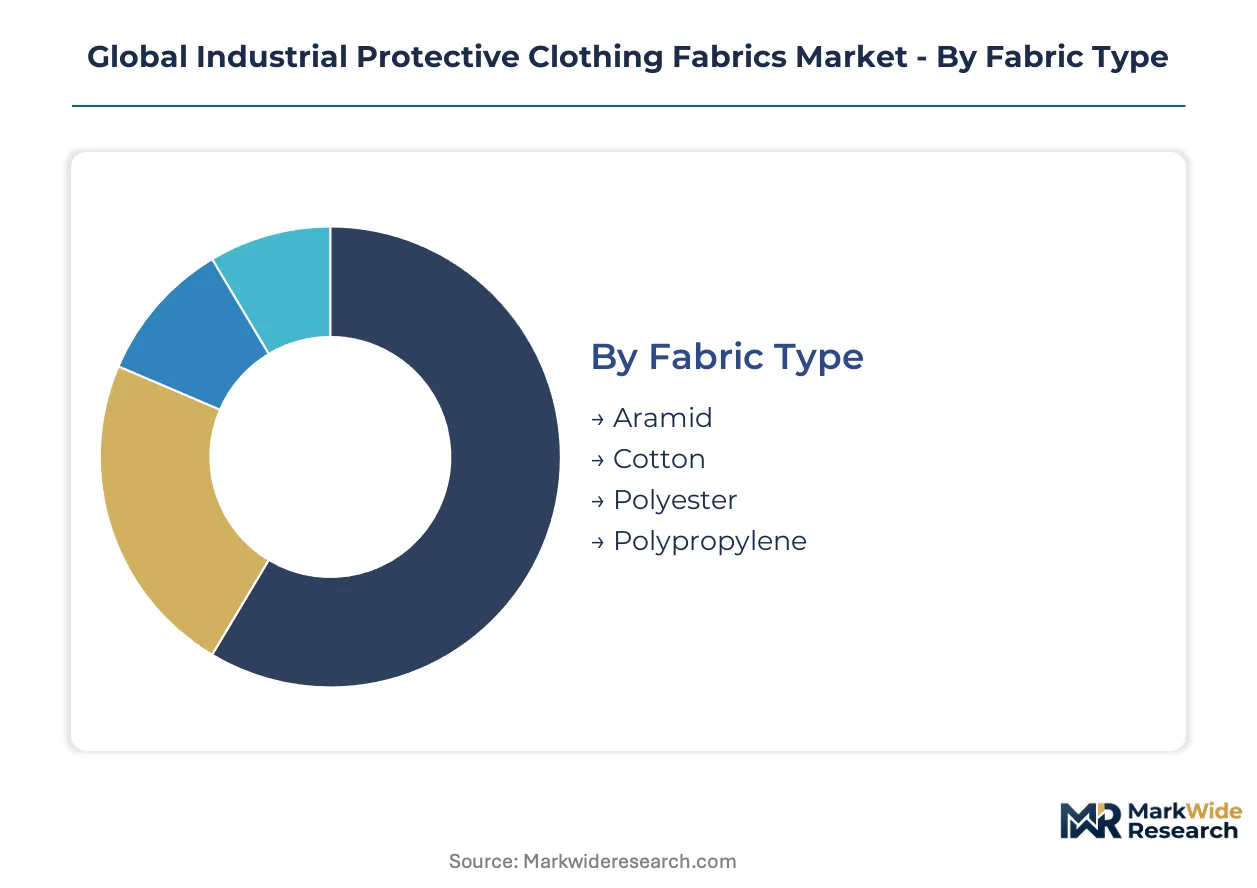
Industrial protective clothing fabrics segment across material chemistry, hazard specificity, and regulatory certification tiers. Procurement patterns diverge sharply between developed economies demanding multi-hazard certification and emerging markets prioritizing cost-efficient single-hazard coverage.
Fabric Type:
Domestic production clusters dominate aramid supply chains while cotton and polyester sourcing spans export-dependent manufacturing networks across South Asia and Southeast Asia.
- Aramid:Inherent flame-resistant meta-aramid and para-aramid polymers deliver thermal stability without chemical treatment degradation. German foundries and US electrical utilities specify these fibers for molten metal splash and arc flash protection where NFPA 70E compliance is non-negotiable.
- Cotton:ProComfort cotton and flame-retardant treated variants retain volume leadership in Indian textile manufacturing and Brazilian industrial laundries where procurement budgets constrain specification upgrades. Treated cotton faces replacement pressure as multi-hazard standards tighten enforcement.
- Polyester:High-tenacity polyester blends serve high-visibility applications with durable water-repellent finishes for European road maintenance crews.
- Polypropylene:Spunbond-meltblown-spunbond laminates provide disposable chemical barrier protection for Japanese pharmaceutical cleanrooms and US hazmat response teams.
Aramid commands the established base. The steepest expansion runs through treated cotton substitution in Asia-Pacific manufacturing economies.
End User:
Volume concentration sits with heavy industry while margin expansion tracks healthcare and specialized energy applications requiring certified traceability.
- Manufacturing:Automotive stamping plants and metal fabrication facilities in Michigan and Stuttgart drive demand for cut-resistant and thermal protective fabrics. OSHA enforcement of machine guarding standards elevates specification complexity beyond basic cotton coveralls.
- Construction:High-visibility polyester and aramid blends dominate infrastructure projects where EN ISO 20471 certification is mandatory for site access.
- Oil & Gas:Saudi Aramco and ADNOC direct procurement mandates favor integrated fabric mills with batch-level arc rating documentation for upstream and downstream operations.
- Healthcare:Chemical-resistant nonwovens serve pharmaceutical manufacturing and laboratory environments under FDA and EMA containment guidelines.
Manufacturing anchors current procurement volumes. Healthcare and oil & gas direct purchasing are gaining share fastest through specification premiumization.
Application:
Certification complexity stratifies pricing tiers with flame retardant and chemical resistant applications commanding technical premiums over mechanical protection categories.
- Flame Retardant:Inherent and treated fabrics meeting NFPA 2112 and EN ISO 11612 standards protect against flash fire and molten metal exposure. US Gulf Coast petrochemical complexes and German aluminum smelters specify dual-certified systems combining thermal and chemical barriers.
- Chemical Resistant:Microporous film laminates and expanded PTFE membranes block hazardous liquid penetration measured by ASTM F739 breakthrough time.
- Cut Resistant:High-performance polyethylene and glass fiber blends achieve ANSI/ISEA 105 cut level ratings for glass handling and metal stamping operations.
- High Visibility:Fluorescent polyester backgrounds with retroreflective tape meet EN ISO 20471 and ANSI/ISEA 107 standards for traffic-facing workforces.
Flame retardant applications anchor the revenue base. Chemical resistant specifications are climbing the fastest as REACH restrictions force coating chemistry upgrades.
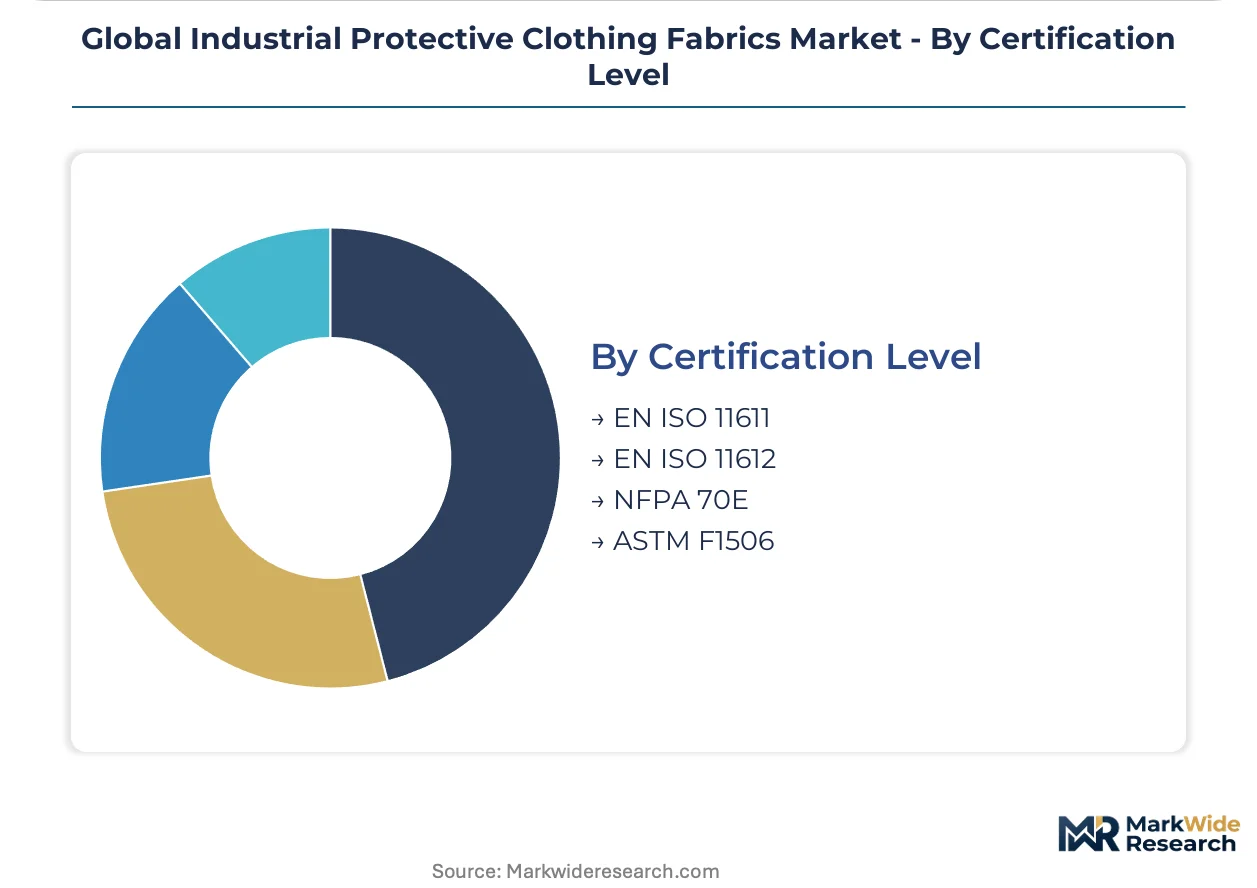
Certification Level:
Regional regulatory divergence creates specification fragmentation with EU and US standards commanding premium positioning over harmonized international protocols.
- EN ISO 11611:Welding and allied process protection standards dominate European procurement for shipyards in Gdańsk and automotive plants in Wolfsburg. Certification requires specific molten metal splash and radiant heat resistance testing.
- EN ISO 11612:Broad thermal hazard coverage including flame spread, heat transfer, and molten metal splash serves multi-risk European industrial environments.
- NFPA 70E:US electrical safety standards mandate arc-rated daily wear for utility workers and industrial electricians exposed to energized equipment.
- ASTM F1506:Arc-rated textile specifications for flame-resistant clothing align with OSHA 1910.269 enforcement in US electric power generation and transmission.
EN ISO 11612 commands the established European base. NFPA 70E enforcement is expanding most quickly through US utility sector procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports meta-aramid spunlace fabrics to Southeast Asian oil and gas maintenance operations, while Belgium and the United States supply coated laminates to Middle Eastern petrochemical complexes. Germany and Japan concentrate high-performance fiber production for European and Asian electrical utility procurement.
United States
OSHA enforces permissible exposure limits that compel manufacturing facilities to upgrade from cotton coveralls to NFPA 70E-certified arc-rated garments. The EPA regulates chemical handling standards that indirectly mandate barrier fabric performance in Gulf Coast petrochemical corridors. Houston and Beaumont industrial clusters drive specification premiums for multi-hazard protection systems.
Germany
Foundries and aluminum smelters in the Rhine-Ruhr region specify EN ISO 11612-certified fabrics for molten metal splash protection. ECHA REACH restrictions on per- and polyfluoroalkyl substances force coating chemistry reformulation across Benelux chemical processing hubs. Wolfsburg automotive stamping plants anchor demand for cut-resistant and thermal protective textiles.
China
Zhejiang and Jiangsu provinces concentrate new meta-aramid spunlace capacity serving Asia-Pacific oil and gas sector procurement. The country's national standards body aligns GB certification with international thermal protection protocols to facilitate export market access. Shanghai chemical industrial zones absorb domestic membrane laminate production for pharmaceutical manufacturing containment.
Saudi Arabia
Saudi Aramco mandates direct supplier relationships with certified fabric mills across upstream and downstream operations. The national oil company procurement directives displace fragmented distributor networks in Jubail Industrial City refinery expansions. Riyadh-based procurement offices enforce batch-level arc rating documentation for contractor workforce protection.
India
BIS certification alignment with EN ISO 11612 opens domestic channels for multinational automotive and steel producers establishing local assembly. The Bureau of Indian Standards harmonizes thermal protection testing with European protocols to reduce import dependency. Maharashtra and Gujarat industrial corridors absorb treated cotton substitution as cost sensitivity gradually yields to multi-hazard specifications.
Global Industrial Protective Clothing Fabrics Market Competitive Environment
Player mix skews toward integrated fiber-to-fabric operators and specialized coating laminators with regional distribution control. Three strategic archetypes dominate: captive aramid fiber producers with backward integration into fabric finishing, membrane technology specialists licensing barrier chemistries, and vertically coated fabric manufacturers with European logistics advantages. Competitive moves concentrate on capacity allocation discipline during raw material shortage periods and certification laboratory queue management to compress approval timelines.
Among integrated chemical giants, DuPont de Nemours, Inc. anchors North American para-aramid supply through captive Kevlar fiber production. W. L. Gore & Associates, Inc. occupies a position within the membrane laminate tier, representing the expanded polytetrafluoroethylene barrier specialization archetype. Sioen Industries NV exemplifies the European coated fabric vertical integration model with Belgium-based manufacturing and distribution control.
| Leading Market Players |
|---|
| W. L. Gore & Associates, Inc. |
| Lakeland Industries, Inc. |
| DuPont de Nemours, Inc. |
| Kermel |
| Sioen Industries NV |
| 3M Company |
| Milliken & Company |
| Glen Raven, Inc. |
| Toray Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month NFPA 2112 certification backlogs compress inventory turns for North American fabric converters while amplifying pricing power for European mills with in-house testing capabilities. DuPont's captive Kevlar fiber supply and Sioen's Belgium-based coating operations translate into divergent margin structures across Atlantic procurement channels.
Pricing Analysis
Next-generation membrane laminate pricing runs 40-60% above legacy coated fabric tiers, while treated cotton specifications face persistent cost compression from Asian spunlace imports. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification complexity—NFPA 70E arc-rated daily wear commands the top tier, EN ISO 11612 basic thermal protection occupies the middle, and untreated cotton coveralls anchor the bottom. Price differentiation hinges on certification grade and vertical integration depth; DuPont's fiber-to-fabric control insulates against benzene derivative volatility that squeezes independent converters. Price erosion runs through treated cotton segments as Zhejiang capacity expansion floods Asia-Pacific spot markets. Manufacturing buyers in India and Brazil exhibit highest price sensitivity, while Saudi Aramco direct procurement mandates absorb premium multi-hazard specifications without volume discount pressure.
Supply Chain Analysis
Benzene derivative supply from US Gulf Coast petrochemical corridors underwrites global para-aramid polymer availability, with any disruption cascading through Kevlar-dependent fabric converters. Geographic supply concentrates in China for meta-aramid spunlace, Belgium for coated laminates, and the United States for membrane barrier films. Raw material dependencies center on benzene and p-phenylenediamine for aramid synthesis, PTFE resin for expanded membrane production, and specialty chemical coatings for chemical splash protection. Single-source vulnerability runs through DuPont's North American para-aramid fiber monopoly, creating allocation risk during capacity constraints. Distribution runs through consolidated national oil company procurement in Saudi Arabia and ADNOC direct mill relationships, displacing fragmented distributor networks across Middle Eastern petrochemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial protective clothing fabrics function as a service-attach opportunity where certified laundering, batch traceability documentation, and arc rating verification services expand faster than base fabric hardware. Recurring revenue from managed garment programs and compliance auditing layers outpaces transactional fabric sales in North American utility and European chemical processing accounts.
For Market Incumbents: Secure captive fiber supply through backward integration or long-term offtake agreements with Zhejiang meta-aramid producers to offset DuPont concentration risk. Expand in-house NFPA and EN ISO certification laboratory capacity to compress 18-month approval timelines and capture competitor product launch delays. Prioritize Saudi Aramco and ADNOC direct supplier qualification to displace distributor-dependent rivals in Middle Eastern petrochemical procurement. For New Entrants and Emerging Players: NFPA 70E certification fast-track partnerships with third-party testing laboratories open entry paths into US electrical utility daily-wear procurement. Target India's Maharashtra and Gujarat industrial corridors where BIS-EN ISO 11612 alignment creates first-mover advantage over import-dependent incumbents. Pursue white-space in wearable sensor-embedded fabrics for confined space entry, positioning as connected worker platform partners rather than commodity fabric suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because OSHA permissible exposure limit tightening and REACH chemical restrictions structurally expand addressable market for certified multi-hazard fabrics. Acquisition targets should concentrate on European coated fabric specialists with verified circular material flows qualifying for EU Green Deal procurement preference. Watch ECHA enforcement inspection intensity across Benelux chemical hubs as inflection indicator for membrane laminate substitution velocity away from legacy coated fabrics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Production | Captive meta-aramid supply from Zhejiang capacity insulates margin pressure from benzene volatility. |
| In-House Certification Laboratory Buildout | Proprietary NFPA 2112 testing capacity compresses approval timelines from 18 to 12 months. |
| Direct Mill Relationships with National Oil Companies | Saudi Aramco procurement mandates displace fragmented distributor networks in Jubail expansions. |
| Sensor-Embedded Fabric Development | Temperature and gas detection integration captures connected worker platform premiums in confined space. |
| REACH-Compliant Coating Chemistry Reformulation | Silicone and hydrocarbon alternatives to fluorocarbon treatments secure Benelux chemical processor access. |
Study Parameters
Desk research of customs trade databases, ECHA regulatory filings, and SEC 10-K disclosures preceded structured interviews with plant safety managers, industrial laundry operators, and fabric procurement leads at national oil companies. Primary fieldwork with certification laboratory directors and aramid fiber R&D heads validated secondary demand estimates. Bottom-up fabric consumption modeling triangulated against top-down end-use industry spend analysis.
Variance decomposition across material chemistry, hazard specificity, and certification tier segments anchored the analytical framework over the projection horizon. Modeled dimensions spanned aramid versus cotton versus polyester substrate splits, flame retardant versus chemical resistant versus cut resistant application categories, and EN ISO versus NFPA versus ASTM certification clusters. CAGRs derived from segment-level volume trajectories weighted by regional regulatory enforcement intensity and industrial capital expenditure cycles. Forecast inputs incorporated OSHA permissible exposure limit revision timelines and ECHA REACH Annex XVII substance restriction schedules.
The analysis sits within stated boundaries; outcomes outside sustained petrochemical feedstock price stability or accelerated REACH compliance timelines would require recalibration. Forecasts reflect assumptions around certification harmonization progress and national oil company procurement centralization velocity. Practitioners should keep alternative scenarios live as EPA enforcement intensity and EU Green Deal recycled content mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Functional Workwear Apparel Market