
 Industrial Protective Fabrics Market | 2026-2036
Industrial Protective Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Protective Fabrics Market Analysis
Modular garment systems that separate outer shells from thermal liners and moisture barriers is recalibrating how industrial buyers evaluate total cost of ownership across replacement cycles. DuPont leverages its Kevlar and Nomex fiber platforms to sustain supply relationships with major uniform rental networks. Milliken & Company anchors its position through flame-resistant cotton and synthetic blends manufactured at scale in the southeastern United States. W. L. Gore & Associates differentiates via membrane technology that extends breathable chemical protection into applications previously served by heavier, less comfortable materials.
Industrial protective fabrics are engineered textile constructions—woven, non-woven, knitted, or coated—incorporating flame-resistant fibers, chemical-barrier membranes, or high-visibility colorants to shield workers from thermal, chemical, electrical, and mechanical hazards in occupational environments. Manufacturing processes include fiber modification, nanoscale coating deposition, and multi-layer lamination to achieve specified arc ratings, permeation resistance, or ANSI visibility standards. Coated fabrics command premium positioning due to their combined chemical and thermal barrier properties, while non-woven fabrics compete on disposability and cost efficiency in healthcare and light manufacturing settings. Fire retardant applications lead volume demand from oil and gas and electrical utility sectors, whereas high visibility requirements are expanding fastest as construction safety regulations tighten across jurisdictions.
OSHA enforces 29 CFR 1910.132 PPE standards that mandate hazard assessments and documented compliance for general industry employers in the United States, directly shaping procurement specifications for protective apparel. The EU PPE Regulation (EU) 2016/425 requires third-party certification by notified bodies for Category III protective fabrics, creating market access barriers for uncertified suppliers. NFPA 2112 and NFPA 70E standards in the United States further specify minimum thermal performance and arc flash protection levels that fabrics must demonstrate through certified testing. Buyers and suppliers must monitor evolving state-level adoption of enhanced electrical safety rules and potential harmonization gaps between North American and European certification protocols.
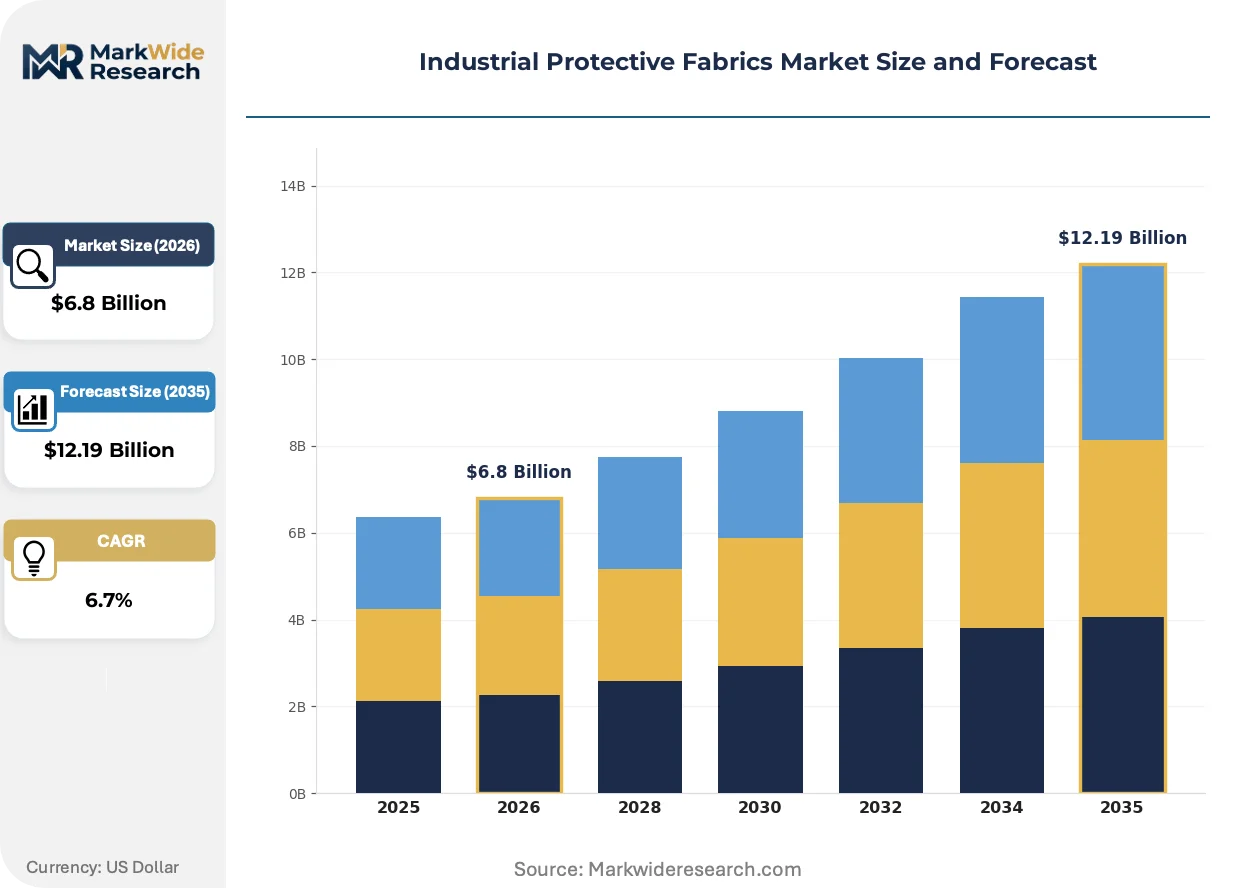
Market Dynamics
Modular garment architectures are restructuring procurement economics as industrial buyers recalibrate replacement cycles around separable thermal liners and moisture barriers rather than monolithic coveralls.
Growth Catalysts
- OSHA 29 CFR 1910.132 enforcement:Mandated hazard assessments in United States general industry are expanding documented PPE compliance programs and driving specification upgrades for flame-resistant apparel.
- Arc flash protection standards:NFPA 70E adoption across electrical utilities and petrochemical maintenance operations is elevating minimum fabric arc ratings and accelerating certified product turnover.
- Texas-Louisiana refining corridor investment:Sustained petrochemical capital deployment along the Gulf Coast is generating multi-year uniform rental contracts with volume commitments.
Market Restraints
- Aramid fiber supply concentration:Dependence on limited domestic sources for meta-aramid and para-aramid staple creates input cost volatility and allocation risk during demand surges.
- EU PPE Regulation (EU) 2016/425 certification barriers:Third-party notified body requirements for Category III fabrics extend market access timelines and elevate compliance costs for non-European suppliers.
- Legacy cotton-based alternatives:Untreated natural fiber workwear in price-sensitive maintenance segments competes on first-cost despite inferior thermal protection.
Strategic Opportunities
- Indian industrial safety expansion:BIS certification alignment with international flame-resistance standards is opening specification opportunities in steel and power generation sectors.
- Breathable chemical barrier convergence:Membrane-laminated constructions combining vapor permeability with liquid penetration resistance are penetrating laboratory and pharmaceutical manufacturing applications previously served by rigid suits.
- Rental channel consolidation:National uniform service networks are seeking exclusive supply agreements with certified fabric mills capable of consistent multi-shift durability.
Industry Challenges
- NFPA 2112 recertification complexity:Batch testing and documented traceability requirements for flash fire protection fabrics extend product development cycles and constrain rapid formulation changes.
- Multi-layer lamination capex intensity:Continuous coating and bonding equipment for membrane-barrier fabrics requires substantial capital commitment and technical commissioning expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Protective Fabrics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Coated Fabrics End User: Construction, Manufacturing, Oil & Gas, Healthcare Application: Fire Retardant, Chemical Resistant, Electrical Insulation, High Visibility Technology: Nanotechnology, Coating Technology, Membrane Technology, Fiber Modification |
| Companies Covered | DuPont, 3M, Milliken & Company, W. L. Gore & Associates, TenCate Protective Fabrics, Teijin Limited, Lakeland Industries, Klopman International, Glen Raven, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Protective Fabrics Market Emerging Trajectories
Active materials integration and regulatory harmonization pressures are compressing development timelines while expanding performance boundaries beyond traditional hazard categories.
Nanoscale surface modification is absorbing hydrophobic and oleophobic properties into base fabric structures without sacrificing breathability or hand feel. Oil and gas operators in the Permian Basin are specifying these treatments for coveralls exposed to drilling mud and hydraulic fluid contamination. The technology is absorbing maintenance cost reductions that previously justified disposable garment programs.
REACH chemical restriction amendments are forcing reformulation of durable water repellent chemistries away from long-chain fluorocarbon compounds. European fabric finishers are accelerating short-chain C6 and non-fluorinated alternatives through certification pipelines. Coated fabric segments face compressed compliance windows as downstream brands demand ZDHC-aligned chemistries for uniform rental contracts.
Rental service consolidation is compressing supplier bases as national networks consolidate regional operators and standardize fabric specifications. Multi-site petrochemical and utility employers are consolidating procurement through single-source national agreements. This concentration is most visible across the United States, where three rental networks now control majority share of flame-resistant apparel deployment in refining and electrical utility segments.
Industrial Protective Fabrics Market Segmentation
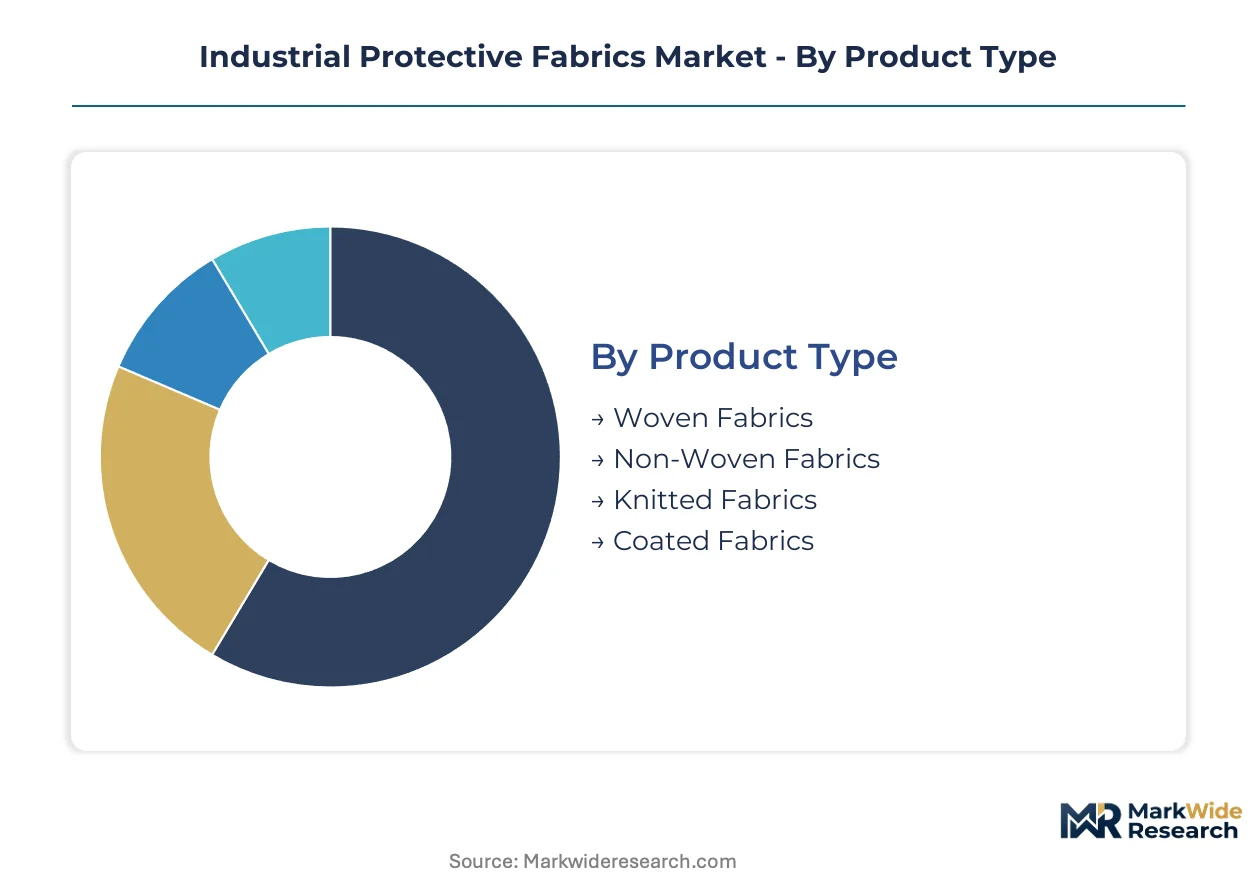
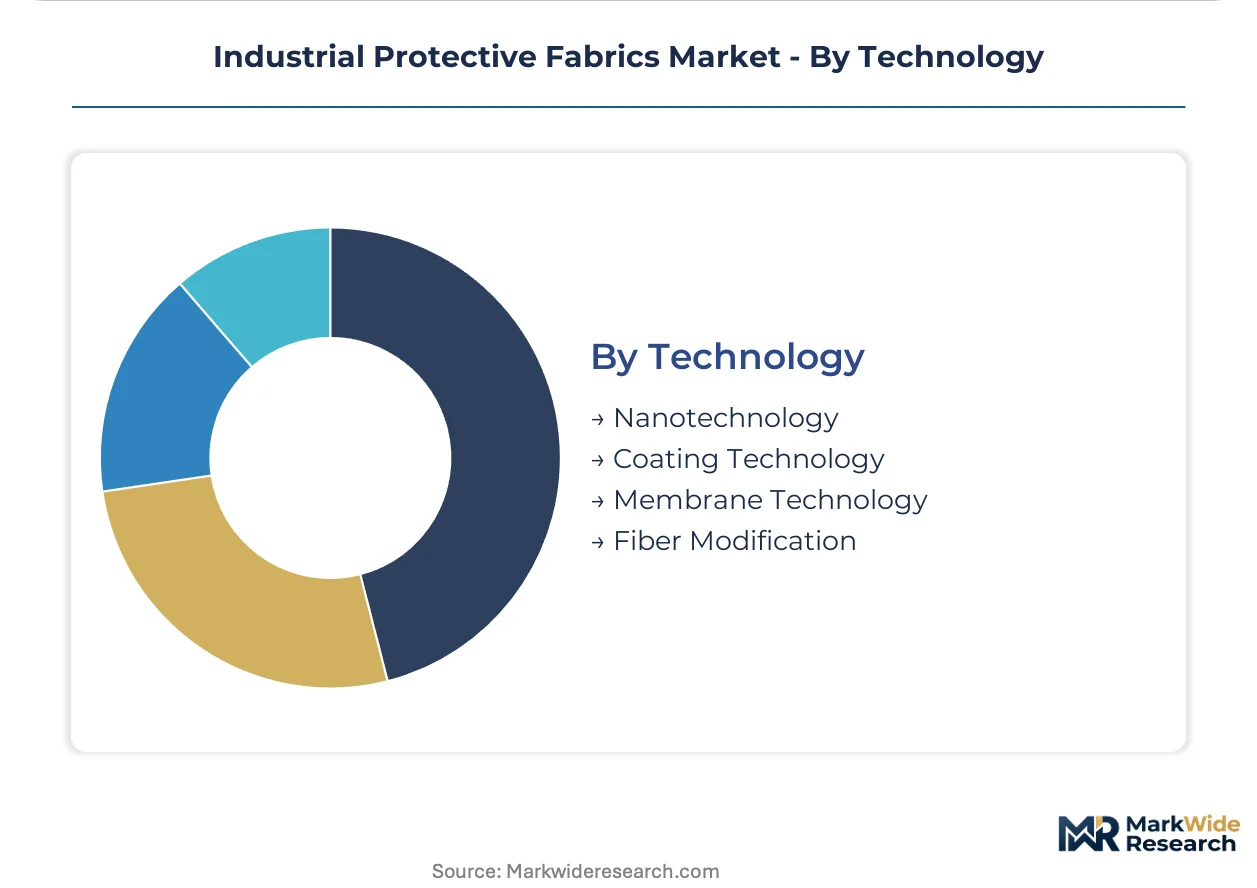
Procurement teams evaluate protective fabrics through multiple technical dimensions simultaneously—product construction, hazard application, and manufacturing technology—each carrying distinct replacement-cycle economics and certification burdens. Understanding how these categories intersect determines specification strategy for multi-year uniform contracts.
Product Type:
Upgrade decisions across product types hinge on separable-component architectures that allow thermal liners and moisture barriers to cycle on different schedules than outer shells.
- Woven Fabrics:Tight interlaced constructions of aramid, modacrylic, or flame-resistant cotton provide structural integrity for daily-wear coveralls and jackets. Demand concentrates in Texas and Louisiana refining corridors where petrochemical operators specify NFPA 2112-certified constructions for flash fire protection.
- Coated Fabrics:Multi-layer laminations combining substrate textiles with polymer or membrane barriers deliver combined chemical and thermal protection. Laboratory and pharmaceutical manufacturing applications in the United States are absorbing these constructions as replacements for heavier, less breathable rigid suits.
- Non-Woven Fabrics:Bonded fiber mats compete on disposability and first-cost in light manufacturing and healthcare settings where contamination protocols mandate single-use garments.
- Knitted Fabrics:Elastic looped constructions serve base-layer and comfort-critical applications requiring moisture management beneath outer protective shells.
Volume placements concentrate in woven fabrics; the faster expansion belongs to coated fabrics.
End User:
Cost-tier differentiation separates capital-intensive sectors with mandated compliance programs from price-sensitive maintenance operations.
- Oil & Gas:Upstream and downstream operators face the strictest thermal protection mandates, driving specification of arc-rated and flash fire-resistant apparel across drilling, refining, and pipeline maintenance. OSHA 29 CFR 1910.132 enforcement is expanding documented PPE compliance programs in this sector.
- Construction:High-visibility requirements are tightening across United States jurisdictions as state-level adoption of enhanced electrical safety rules elevates ANSI 107-compliant fabric demand.
- Manufacturing:Chemical processing and metal fabrication operations specify barrier fabrics for splash protection and spark resistance, with procurement patterns shifting toward rental channel consolidation.
- Healthcare:Infection control protocols sustain demand for disposable non-woven gowns and drapes, though this segment operates on separate supply chains from industrial protective textiles.
Contract value concentrates in oil and gas; construction is climbing the fastest as regulatory scope widens.
Application:
Application selection directly determines certification pathway complexity and batch testing obligations.
- Fire Retardant:Fabrics engineered with inherent or treated flame-resistant fibers meet NFPA 2112 and NFPA 70E standards for thermal protective performance. Electrical utilities across the United States are elevating minimum arc ratings, accelerating certified product turnover.
- Chemical Resistant:Barrier constructions with permeation resistance against specific industrial chemicals require material-specific testing under EPA and OSHA guidelines.
- High Visibility:Fluorescent background materials combined with retroreflective trim satisfy ANSI/ISEA 107 for workers in traffic or low-light industrial environments.
- Electrical Insulation:Dielectric strength specifications protect utility lineworkers and electricians from arc flash and shock hazards, with ratings calibrated to voltage exposure levels.
Unit volume concentrates in fire retardant; high visibility is gaining share fastest as construction safety rules proliferate.
Technology:
Technology tier separates premium membrane and nanoscale constructions from conventional fiber modification approaches.
- Membrane Technology:Microporous or hydrophilic films laminated to textile substrates enable vapor transmission while blocking liquid penetration. W. L. Gore & Associates anchors this segment with expanded polytetrafluoroethylene constructions.
- Coating Technology:Direct deposition of flame-resistant or chemical-barrier polymers onto fabric surfaces offers cost-efficient protection for moderate-hazard applications.
- Fiber Modification:Inherent flame resistance through aramid or modacrylic polymer chemistry eliminates topical treatment durability concerns.
- Nanotechnology:Surface engineering at molecular scale imparts hydrophobic, oleophobic, or antimicrobial properties without altering base fabric hand or breathability.
Deployment scale concentrates in coating technology; nanotechnology shows the steepest expansion trajectory as finishers reformulate to meet REACH chemical restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast Opportunity Zones in Texas and Louisiana concentrate petrochemical investment and flame-resistant apparel procurement through accelerated depreciation incentives and infrastructure grants.
United States
OSHA 29 CFR 1910.132 enforcement drives specification upgrades across electrical utilities and refining operations. The EPA coordinates with state regulators on chemical-barrier certification alignment. Houston and Lake Charles anchor multi-year uniform rental contracts with volume commitments from expanding petrochemical complexes.
Germany
REACH chemical restriction amendments force reformulation of durable water repellent chemistries away from long-chain fluorocarbon compounds. The ECHA administers substance authorization timelines that compress compliance windows for fabric finishers. The Rhine-Ruhr industrial corridor sustains demand for membrane-laminated constructions in chemical processing applications.
China
Steel and power generation sectors absorb specification-grade flame-resistant fabrics as industrial safety protocols tighten. The MIIT oversees GB standards alignment with international thermal protection benchmarks. The Yangtze River Delta manufacturing belt generates procurement volume for coated fabric constructions in pharmaceutical processing.
India
BIS certification alignment with NFPA and EN flame-resistance standards opens specification opportunities in metals and energy infrastructure. The CEA mandates enhanced electrical safety equipment for utility maintenance crews. Gujarat and Maharashtra industrial zones drive initial adoption of arc-rated apparel among state-owned power generators.
Saudi Arabia
SABIC-affiliated petrochemical complexes expand procurement of flash fire-resistant coveralls for downstream operations. The Saudi Standards, Metrology and Quality Organization implements PPE technical regulations mirroring EU Category III requirements. The Jubail Industrial City generates concentrated demand through integrated refining and chemical manufacturing clusters.
Industrial Protective Fabrics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base organizes around fiber producers, fabric mills, and membrane-lamination specialists with distinct certification capabilities. Three archetypes dominate: integrated fiber-to-fabric manufacturers, licensed technology platforms, and rental-channel-integrated suppliers. Capacity expansion and exclusive supply agreements constitute the primary competitive vectors as national uniform networks consolidate procurement.
Among integrated fiber specialists, DuPont and Teijin Limited occupy positions anchored by aramid polymer platforms. Milliken & Company exemplifies the scale-driven fabric mill archetype with southeastern United States manufacturing concentration. W. L. Gore & Associates represents the membrane-technology tier through microporous expanded polytetrafluoroethylene constructions.
| Leading Market Players |
|---|
| DuPont |
| 3M |
| Milliken & Company |
| W. L. Gore & Associates |
| TenCate Protective Fabrics |
| Teijin Limited |
| Lakeland Industries |
| Klopman International |
| Glen Raven |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up rental networks in the United States have consolidated procurement leverage, compressing fabric mill margins while extending volume commitments that lock in multi-year pricing corridors. This ownership concentration simultaneously concentrates supply risk among certified producers capable of meeting NFPA 2112 batch testing obligations.
Pricing Analysis
Margin tightening in standard-grade woven fabrics reflects aramid fiber allocation constraints and elevated certification costs under EU PPE Regulation third-party notified body requirements. Contract-based long-term offtake dominates, with pricing stratifying across NFPA 2112-certified premium constructions, standard FR cotton blends, and untreated natural fiber economy alternatives. Price differentiation hinges on arc rating tier and vertical integration into fiber production. Cost-down pressure on economy segments accelerates because legacy cotton workwear competes on first-cost despite inferior thermal protection. Maintenance contractors in price-sensitive segments exhibit highest price sensitivity; electrical utilities with mandated compliance programs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with domestic meta-aramid and para-aramid staple producers, creating allocation risk during demand surges from Gulf Coast petrochemical expansion. Manufacturing draws from United States southeastern fabric mills, German membrane-lamination specialists, and Chinese coated substrate producers. Raw material dependencies center on aramid polymers, modacrylic fibers, and expanded polytetrafluoroethylene membranes. Tariff exposure on imported chemical-barrier substrates constitutes the primary structural risk. Distribution runs through national uniform rental networks that have consolidated regional operators and standardized specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aramid fiber supply concentration props pricing discipline, as limited qualified sources constrain rapid capacity response to demand spikes from OSHA enforcement expansion.
For Market Incumbents: Anchor market position through backward integration into fiber modification capabilities and exclusive supply agreements with consolidating rental networks. Defend against membrane-technology specialists penetrating chemical-barrier applications by accelerating nanoscale surface modification R&D. Prioritize certification investment to maintain NFPA 2112 and NFPA 70E batch testing throughput. For New Entrants and Emerging Players: Capture specification opportunities in India's steel and power generation sectors as BIS certification alignment with international flame-resistance standards opens procurement access. Target arc-rated apparel deployment among state-owned power generators in Gujarat and Maharashtra. Pursue go-to-market partnerships with regional industrial safety distributors rather than direct rental network competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified fabric mills with stranded capacity in the southeastern United States amid rental channel consolidation. Long-term viability centers on membrane-lamination technical capabilities and sustained petrochemical capital deployment along the Gulf Coast. Watch OSHA state-plan adoption rates as the inflection signal for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Production | Captive supply of meta-aramid staple insulates against allocation risk during Texas-Louisiana demand surges. |
| Membrane Technology Licensing Agreement | Expanded polytetrafluoroethylene construction access penetrates laboratory and pharmaceutical manufacturing applications. |
| National Rental Network Partnership | Exclusive supply contracts with consolidated uniform services lock in multi-shift durability specifications. |
| REACH-Compliant Finishing Capacity Expansion | Short-chain C6 and non-fluorinated chemistry pipelines capture European uniform rental contract demand. |
| Indian BIS Certification Investment | Steel and power generation sector specification access opens as CEA mandates enhanced electrical safety equipment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with fabric mill procurement directors, rental network supply chain managers, petrochemical safety officers, and notified body certification specialists. OSHA enforcement databases, EU PPE Regulation compliance registries, NFPA standard revision documentation, and petrochemical capital expenditure disclosures supplied triangulation points. Bottom-up unit demand modeling and top-down market sizing converged on value estimates.
Segment-level granularity applied to woven, coated, non-woven, and knitted product constructions; oil and gas, construction, manufacturing, and healthcare end users; fire retardant, chemical resistant, high visibility, and electrical insulation applications; and membrane, coating, fiber modification, and nanotechnology processing tiers across the analysis window. CAGRs derived from regression against petrochemical investment cycles and regulatory adoption curves. Arc rating upgrade trajectories and rental channel consolidation velocity served as industry-specific forecast inputs.
The model holds under sustained OSHA enforcement intensity and Gulf Coast petrochemical capital deployment; deviation in aramid fiber supply disruption or REACH restriction acceleration would shift trajectory bounds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Winter Hats Market