
 Functional Workwear Apparel Market | 2026-2036
Functional Workwear Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Workwear Apparel Market Analysis
The functional workwear apparel market is restructuring around a widening split between premium technical garments and commodity uniform basics. Helly Hansen Workwear leverages Arctic-tested membrane technologies to command position in extreme-climate segments. Carhartt anchors its presence through heritage brand equity and direct-to-trade channel control in North American construction supply chains. Engelbert Strauss differentiates via integrated manufacturing in Central Europe, compressing lead times for customized enterprise uniform programs.
Functional workwear apparel comprises engineered garments designed to protect wearers from occupational hazards including thermal exposure, chemical splash, electrical arc flash, and mechanical abrasion, typically constructed with reinforced seams, specialized fiber blends, and compliance-tested finishes such as ATPV-rated fabrics or EN ISO 20471 high-visibility tape. Coveralls and jackets lead volume in heavy-industrial deployment where multi-hazard protection consolidates procurement spend, while anti-microbial treated scrubs within healthcare end use represent the fastest-expanding margin pool as infection-control protocols harden. Cotton-polyester blends dominate material selection for breathability-durability balance, though nylon is displacing legacy canvas in logistics roles where weight reduction improves mobility across extended shifts.
OSHA, NFPA, and ANSI/ISEA standards collectively dictate minimum performance thresholds for flame resistance, high-visibility, and personal protective equipment classification in the United States, creating compliance-driven replacement cycles that insulate demand from pure discretionary cuts. The EU's PPE Regulation and REACH chemical restrictions impose parallel certification burdens for exporters, while China's GB standards and emerging SAMR enforcement reshape competitive access for imported brands. Stakeholders must monitor how evolving heat-stress exposure limits and state-level right-to-know chemical disclosure rules recalibrate fabric specification requirements ahead of next procurement cycles.
Market Dynamics
OSHA's updated heat-illness prevention rulemaking and NFPA 2112 fabric certification tightening are forcing accelerated replacement cycles across North American industrial employers, compressing procurement timelines and elevating technical specification authority within safety departments.
Growth Catalysts
- Infrastructure Investment Surge:The Bipartisan Infrastructure Law directs capital toward bridge rehabilitation and grid modernization across the United States, expanding field workforce headcount and protective garment procurement volumes.
- NFPA 70E Arc-Flash Mandates:Electrical utilities and oilfield services in Texas and California face stepped-up enforcement of flame-resistant clothing requirements, sustaining demand for ATPV-rated coveralls and base layers.
- Phase-Change Material Integration:Microencapsulated paraffin wax treatments are penetrating logistics and warehouse roles, addressing heat-stress liability without sacrificing mobility during extended shifts.
Market Restraints
- Cotton-Polyester Feedstock Volatility:Gulf Coast petrochemical supply disruptions and Texas cotton harvest variability are compressing margin stability for mid-tier garment assemblers dependent on blended knits.
- Certification Bottleneck Concentration:Third-party NFPA and ANSI testing capacity clusters with three accredited laboratories in the United States, extending lead times for new product qualification.
- Disposable Coverall Substitution:Chemical processing plants in Louisiana and New Jersey are shifting toward single-use Tyvek alternatives for intermittent hazardous tasks, eroding reusable garment penetration in episodic exposure roles.
Strategic Opportunities
- Smart PPE Convergence:Biometric sensor integration with moisture-wicking base layers is creating real-time heat-stress monitoring capability for California agriculture and Arizona construction employers.
- Enterprise Rental Program Expansion:Industrial laundries in Ohio and Illinois are launching subscription-based garment management services, capturing procurement budget previously held by direct uniform purchasers.
- State Right-to-Know Expansion:New Jersey and Massachusetts chemical disclosure rulemakings are mandating enhanced protective specifications for maintenance crews, opening premium fabric upgrade cycles.
Industry Challenges
- Pattern-Making Talent Scarcity:Domestic vocational programs in apparel engineering have contracted, constraining domestic manufacturers' ability to execute rapid fit customization for female workforce proportions.
- Multi-Standard Certification Complexity:Simultaneous OSHA, NFPA, and ANSI compliance documentation requirements are extending product development timelines and elevating legal review costs for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Workwear Apparel Market |
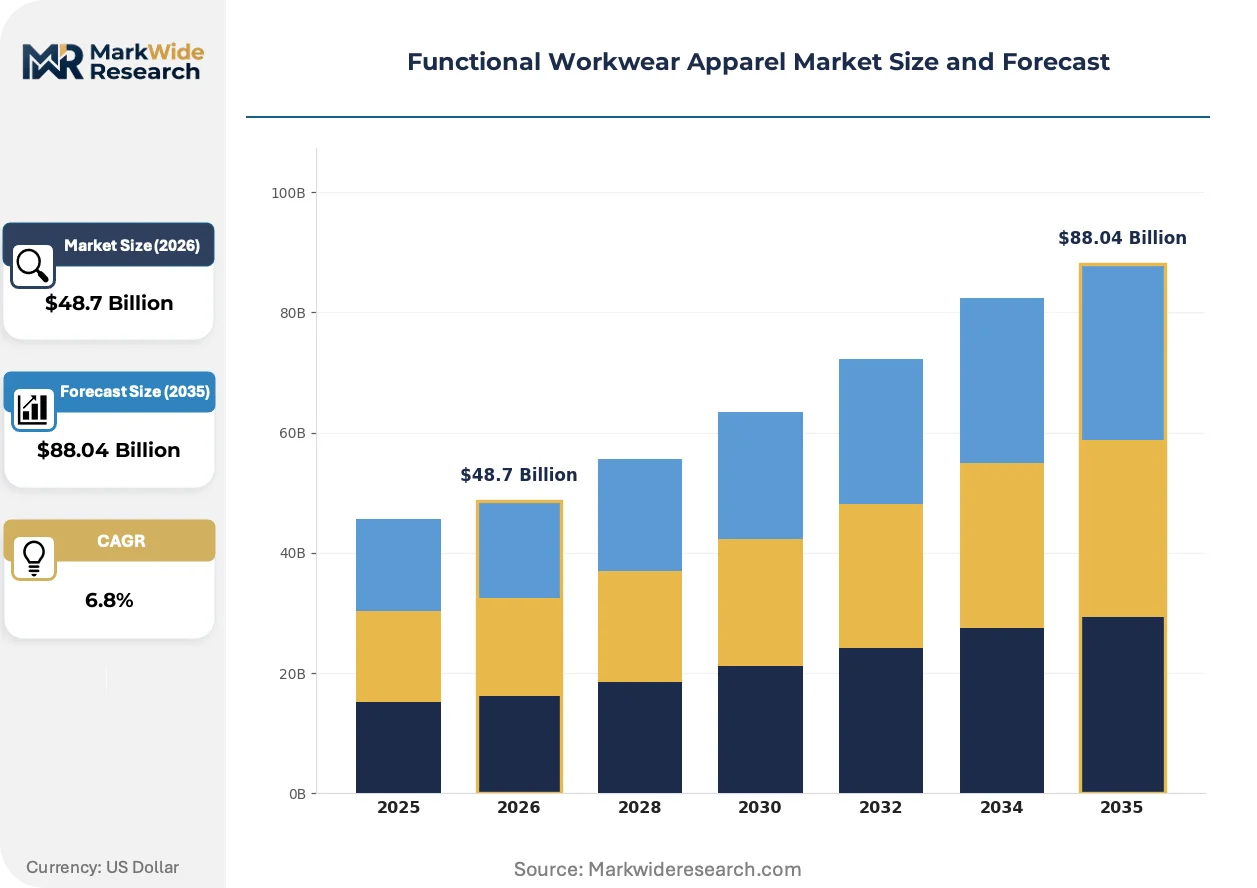
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Pants, Coveralls, Boots Material: Cotton, Polyester, Nylon, Canvas End User: Construction, Healthcare, Food Service, Manufacturing Feature: Water-Resistant, Fire-Resistant, Anti-Microbial, High-Visibility |
| Companies Covered | Helly Hansen Workwear, Engelbert Strauss, Carhartt, Portwest, Fristads, Dickies, Timberland PRO, Red Kap, Snickers Workwear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Workwear Apparel Market Emerging Trajectories
Material science convergence with biometric monitoring is redefining functional workwear from passive protection to active hazard management, while procurement centralization and rental-service expansion are restructuring channel economics across industrial end-uses.
Adaptive membrane technology is unifying breathability and liquid-barrier performance in single-fabric constructions. Refinery maintenance contractors in Texas and chemical plant operators in Louisiana are specifying these materials for multi-hazard environments. The technology is unifying previously separate garment categories into unified coverall platforms, reducing inventory complexity for enterprise safety departments.
OSHA's proposed heat-illness prevention standard is elevating evaporative cooling and ventilation design to mandatory specification criteria. California's Division of Occupational Safety and Health has already issued emergency regulations for outdoor workers. Agriculture and logistics employers in the Central Valley are responding with phase-change treated garments and ventilated high-visibility vests.
Centralized procurement through integrated facility management providers is displacing decentralized site-level purchasing. Large manufacturing campuses in Michigan and Ohio are consolidating garment specification authority with corporate safety directors. This concentration is visible most acutely in automotive assembly and food processing verticals, where enterprise-wide contract value justifies dedicated account management by regional distributors.
Functional Workwear Apparel Market Segmentation
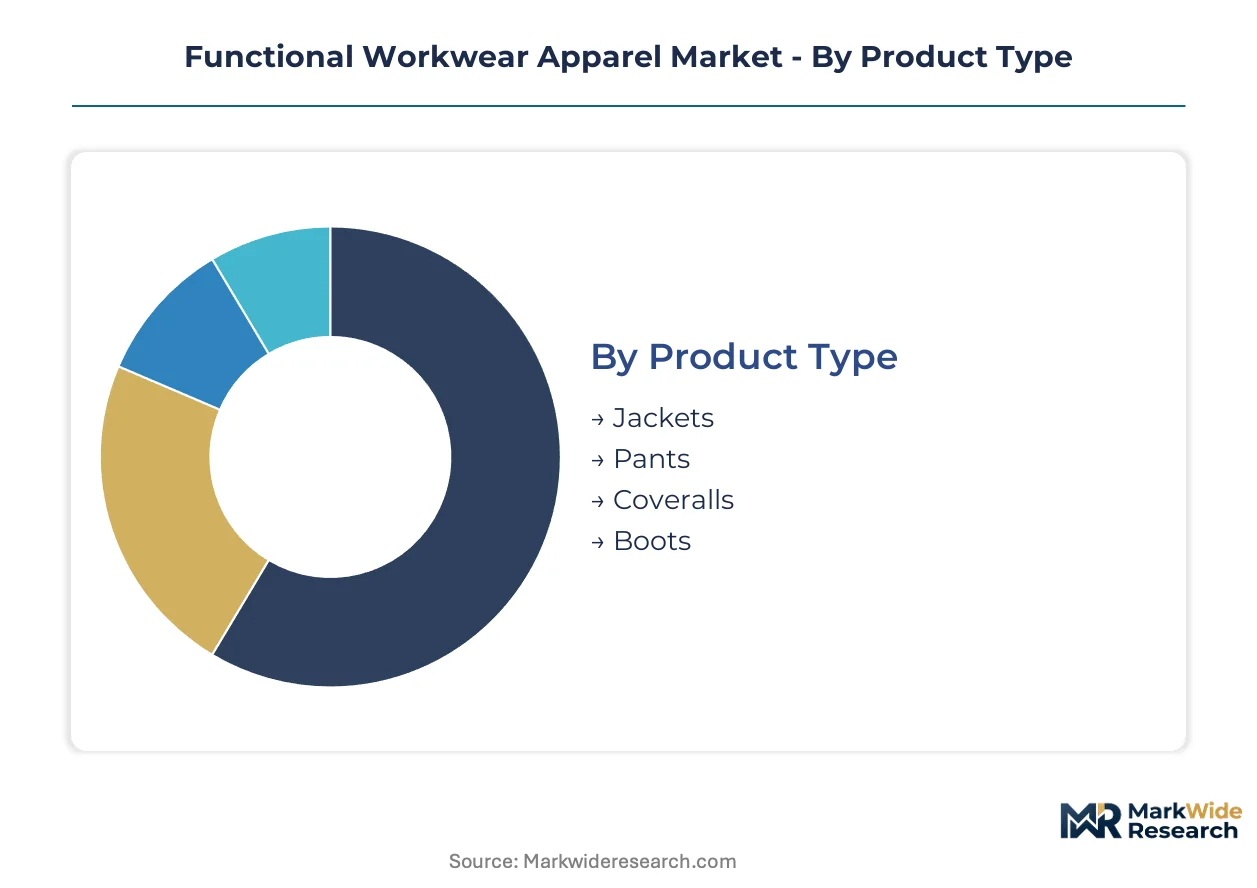
Segmentation in functional workwear apparel determines procurement authority, certification burden, and margin structure. Product type dictates multi-hazard protection consolidation, while material selection governs breathability-durability tradeoffs and feedstock exposure.
Product Type:
OSHA and NFPA certification requirements cluster differently across garment categories, with arc-flash-rated coveralls demanding the most intensive third-party validation.
- Coveralls:Single-piece construction consolidates multi-hazard protection for refinery maintenance and electrical utilities. ATPV-rated fabrics and NFPA 2112 certification dominate procurement specifications in Texas and California oilfield operations.
- Jackets:Layering systems with detachable thermal liners address seasonal variability in construction and logistics roles. High-visibility tape integration per ANSI/ISEA 107 drives replacement cycles in port and highway work zones.
- Pants:Reinforced knee panels and tool-pocket configurations serve mechanical trades and warehouse operations. Cotton-polyester blends balance mobility with abrasion resistance in manufacturing floors.
- Boots:Composite toe and electrical hazard ratings align with ASTM F2413 specifications for heavy industrial deployment. Chemical-resistant outsoles penetrate chemical processing and agricultural chemical handling.
Leading the category by volume: Coveralls. Growing fastest: Jackets with integrated sensor pockets for smart PPE convergence.
Material:
Cost tier stratification separates premium technical fibers from commodity blends, with certification-grade fabrics commanding substantial price premiums over basic uniform knits.
- Cotton-Polyester Blends:Dominant material selection balancing breathability with durability across construction and logistics applications. Gulf Coast petrochemical supply and Texas cotton harvest variability compress margin stability for mid-tier assemblers.
- Nylon:Lightweight abrasion resistance displacing legacy canvas in warehouse and distribution roles. Weight reduction improves mobility across extended shifts in e-commerce fulfillment centers.
- Cotton:Natural fiber preference in food processing and some healthcare settings where synthetic contamination risks elevate. Limited flame resistance without chemical treatment restricts industrial applicability.
- Canvas:Heavy-duty cotton duck construction persists in heritage workwear and welding applications. Thickness and stiffness tradeoffs limit adoption in roles requiring sustained mobility.
Volume concentration: Cotton-polyester blends. Steepest expansion trajectory: Nylon in logistics-specific specifications.
End User:
Application-driven hazard profiles dictate fabric engineering priorities, from arc-flash protection in electrical trades to infection control in clinical environments.
- Construction:Infrastructure investment surge expands field workforce headcount across bridge rehabilitation and grid modernization projects. Multi-hazard exposure combines mechanical abrasion, thermal stress, and fall protection integration.
- Healthcare:Anti-microbial treated scrubs and lab coats represent the fastest-expanding margin pool as infection-control protocols harden. Fluid-resistant barriers and laundering durability drive specification authority.
- Manufacturing:Automated assembly and metal fabrication demand cut-resistant and flame-resistant specifications. Enterprise rental programs are capturing procurement budgets previously held by direct uniform purchasers.
- Food Service:HACCP compliance and color-coded uniform systems prevent cross-contamination in processing and preparation environments. Disposable apron substitution erodes reusable garment penetration in intermittent exposure roles.
Dominant procurement volume: Construction. Gaining share fastest: Healthcare with anti-microbial premiumization.
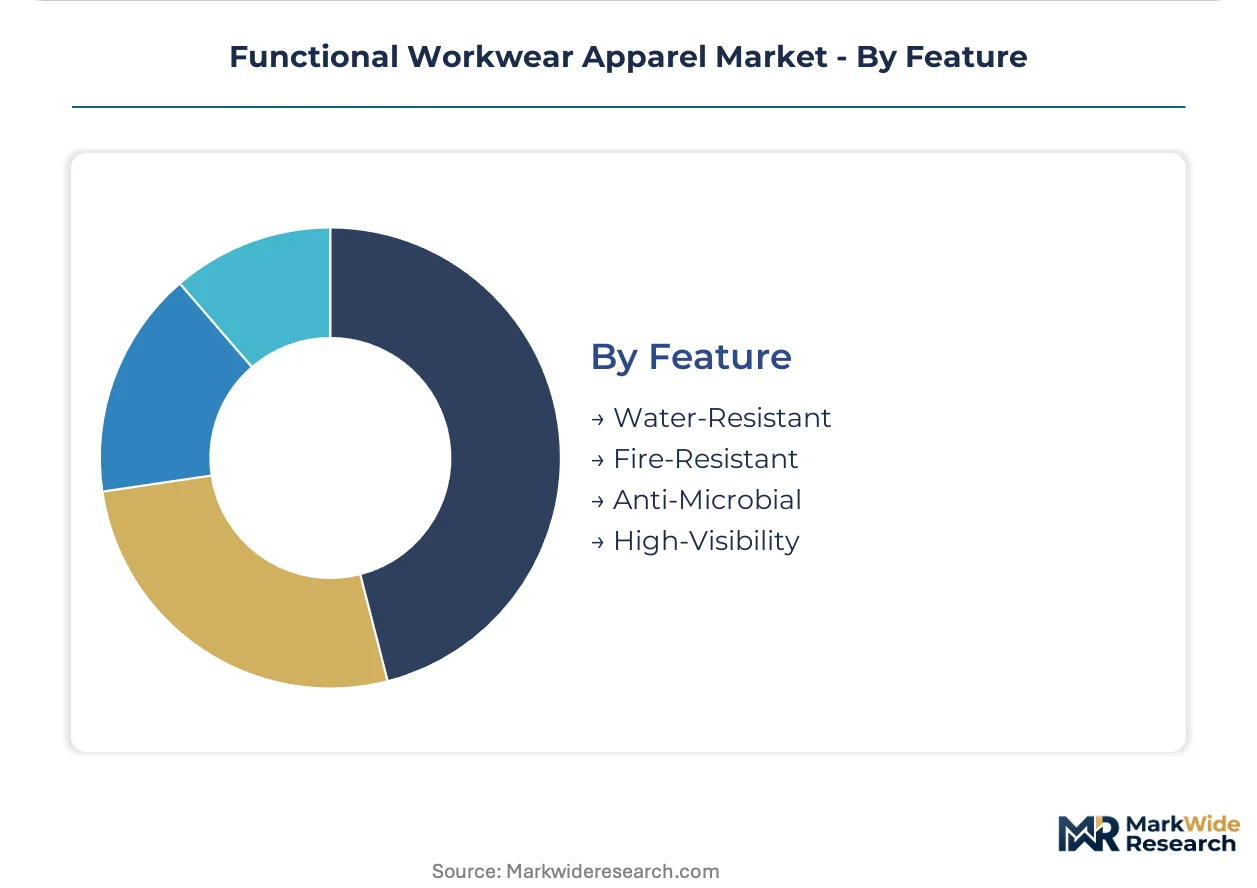
Feature:
Certification-grade features command tiered pricing separation, with ATPV-rated and high-visibility specifications structurally insulated from commodity uniform pricing pressure.
- Fire-Resistant:ATPV-rated fabrics meeting NFPA 70E and NFPA 2112 standards sustain demand in electrical utilities and oilfield services. Certification testing bottleneck concentration with three accredited US laboratories extends new product qualification timelines.
- High-Visibility:EN ISO 20471 and ANSI/ISEA 107 compliant tape configurations mandatory for highway maintenance and port logistics. Retroreflective performance degradation drives replacement cycles in outdoor exposure roles.
- Water-Resistant:Membrane technologies and DWR finishes protect against liquid splash and weather exposure in outdoor construction and utility work. Breathability-performance tradeoffs differentiate premium from economy tier offerings.
- Anti-Microbial:Silver-ion and quaternary ammonium treatments address odor control and bioburden reduction in healthcare and food processing. REACH chemical restrictions in EU export markets impose parallel compliance burdens.
Highest certification burden: Fire-resistant with dual NFPA standards. Expanding most quickly: Anti-microbial with healthcare infection-control hardening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the densest concentration of functional workwear procurement in the United States, where oilfield services and petrochemical maintenance drive premium ATPV-rated garment volumes. Infrastructure corridors across Germany and China's industrial heartland are generating parallel demand surges as capital deployment accelerates.
United States
Texas and California dominate procurement volumes through oilfield services in the Permian Basin and port logistics in Los Angeles-Long Beach. OSHA's updated heat-illness prevention rulemaking is compressing replacement cycles for outdoor construction employers. The Central Valley agriculture sector is adopting phase-change treated garments under Cal/OSHA emergency regulations.
Germany
Automotive assembly in Bavaria and chemical processing in North Rhine-Westphalia sustain demand for multi-hazard protection. REACH chemical restrictions and the EU's PPE Regulation impose parallel certification burdens for domestic and export-oriented manufacturers. The Ruhr industrial corridor is consolidating procurement through integrated facility management providers.
China
Manufacturing clusters in Guangdong and Jiangsu provinces are upgrading protective specifications as SAMR enforcement tightens. GB standards alignment with international norms is reshaping competitive access for imported brands. The Yangtze River Delta logistics hubs are specifying lightweight nylon garments for e-commerce fulfillment workforce mobility.
United Kingdom
Construction activity in London and the Southeast is expanding field workforce headcount for infrastructure renewal. The Health and Safety Executive's enforcement of PPE regulations is elevating technical specification authority within corporate safety departments. Scottish North Sea oil maintenance contractors are specifying adaptive membrane coveralls for multi-hazard offshore environments.
India
Industrial corridor development in Maharashtra and Gujarat is generating protective garment procurement from manufacturing and port logistics employers. BIS certification requirements and state-level factory safety inspections are hardening compliance-driven replacement cycles. The Delhi-Mumbai Industrial Corridor infrastructure projects are expanding heavy-industrial workforce deployment.
Functional Workwear Apparel Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered market strata. Integrated manufacturers with captive textile operations command margin stability against assemblers dependent on volatile cotton-polyester feedstock markets. Three archetypes dominate: heritage workwear brands leveraging channel control, technical specialists with membrane technology portfolios, and regional champions compressing lead times through proximity manufacturing. Consolidation pressure is accelerating through enterprise rental program expansion and direct-to-trade channel capture.
Among heritage-positioned specialists, Carhartt anchors North American construction supply chain presence through direct-to-trade channel control. Helly Hansen Workwear occupies the extreme-climate technical tier with Arctic-tested membrane positioning. Engelbert Strauss exemplifies integrated manufacturing efficiency through Central European proximity production for customized enterprise uniform programs.
| Leading Market Players |
|---|
| Helly Hansen Workwear |
| Engelbert Strauss |
| Carhartt |
| Portwest |
| Fristads |
| Dickies |
| Timberland PRO |
| Red Kap |
| Snickers Workwear |
| Others |
Supply Flow & Price Mechanics
Certification-grade ATPV-rated fabrics and basic cotton-polyester uniform knits occupy opposite ends of a widening price-performance divide, with the former commanding sustained premiums through NFPA 2112 testing bottlenecks while the latter faces margin compression from Gulf Coast petrochemical volatility and Texas cotton harvest variability. This bifurcation reshapes supplier economics: integrated manufacturers with captive textile operations in Central Europe maintain pricing power through lead-time compression, while garment assemblers dependent on spot-market feedstock purchases absorb cost volatility without corresponding pricing recovery.
Pricing Analysis
Value-based pricing anchored to heat-stress liability reduction and arc-flash protection outcomes dominates procurement specifications for electrical utilities and oilfield services. Three-tier pricing structure across premium ATPV-rated, standard high-visibility, and economy uniform tiers separates procurement budgets by hazard exposure level. Cost compression in commodity cotton-polyester blends is intensifying because Gulf Coast petrochemical supply disruptions and harvest variability erode assembler margins. Construction site supervisors exhibit highest price sensitivity for basic uniform replenishment, while corporate safety directors in Texas and California oilfield operations demonstrate lowest sensitivity for certified flame-resistant specifications.
Supply Chain Analysis
Workforce availability constraints in Bangladesh, Vietnam, and China's Yangtze River Delta industrial zones are elevating labor costs for cut-and-sew operations and accelerating automation investment in Central European proximity manufacturing. Raw material sourcing draws from Texas cotton harvests, Gulf Coast petrochemical derivatives for polyester fiber, and South Korean nylon polymer production. Single-source vulnerability concentrates in NFPA-certified fabric finishing, where three accredited US laboratories create qualification bottlenecks for new product entry. Distribution runs through direct-to-trade channels anchored by regional industrial distributors and emerging enterprise rental program providers in Ohio and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where OSHA's updated heat-illness prevention rulemaking and NFPA 2112 certification tightening construct barrier-to-entry moats favoring incumbent players with established testing relationships and documented safety department authority.
For Market Incumbents: Anticipate accelerated replacement cycle compression by securing exclusive testing capacity commitments with NFPA-accredited laboratories before qualification timelines extend further. Defend channel position through backward integration into adaptive membrane fabric finishing, capturing margin pools currently held by specialized textile suppliers. Monitor disposable Tyvek substitution threats in Louisiana and New Jersey chemical processing plants as a margin erosion signal requiring premium feature differentiation response. For New Entrants and Emerging Players: Begin with smart PPE convergence opportunities in California agriculture and Arizona construction, where biometric sensor integration with moisture-wicking base layers lacks established supplier relationships. Target enterprise rental program white space in Michigan and Ohio automotive assembly corridors, where centralized procurement through integrated facility management providers displaces decentralized site-level purchasing. Pursue go-to-market partnerships with industrial laundries launching subscription-based garment management services rather than competing against their established customer relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated facility management providers seeking vertical control over protective garment supply chains. Long-term viability favors manufacturers with captive textile operations and multi-standard certification capabilities across OSHA, NFPA, and ANSI requirements. Watch state-level right-to-know chemical disclosure rulemakings in New Jersey and Massachusetts as the inflection indicator for premium fabric upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fabric Finishing | Captures ATPV-rated margin pools from specialized textile suppliers while compressing NFPA qualification timelines. |
| Smart PPE Sensor Integration | Creates real-time heat-stress monitoring capability for Cal/OSHA-regulated California agriculture employers. |
| Enterprise Rental Program Launch | Captures procurement budgets from direct uniform purchasers in Michigan and Ohio automotive assembly. |
| Multi-Standard Certification Investment | Accelerates product entry across OSHA, NFPA, and ANSI compliance documentation requirements. |
| Adaptive Membrane Technology Licensing | Unifies breathability and liquid-barrier performance for Texas refinery maintenance contractor specifications. |
Methodological Framework
Document review covered OSHA regulatory filings, NFPA standard revision records, and ANSI/ISEA certification databases, complemented by interviews with corporate safety directors, industrial laundry operators, textile procurement managers, and regional workwear distributors. Secondary validation drew from customs trade data, SEC 10-K disclosures of publicly traded apparel manufacturers, and Bureau of Labor Statistics occupational safety incident reports. Bottom-up demand modeling triangulated against top-down market sizing from infrastructure investment flow analysis.
Historical shipment data cross-referenced against panel input from safety equipment distributors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-use industry, and certification feature tier. CAGRs derived from weighted average of historical trajectory and forward-looking procurement intention surveys. Industry-specific inputs incorporated OSHA rulemaking timelines and NFPA laboratory capacity constraints.
Underlying measurement precision varies by segment; ATPV-rated flame-resistant garments carry tighter precision than commodity uniform basics due to documented certification requirements. Forecasts reflect assumptions regarding infrastructure investment continuity and regulatory enforcement intensity. Material deviation in OSHA heat-illness prevention standard finalization or Gulf Coast petrochemical supply disruption severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market