
 High Visibility Clothing Market | 2026-2036
High Visibility Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
High Visibility Clothing Market Outlook
Buyer fragmentation across mid-sized construction subcontractors is repositioning procurement patterns away from national fleet contracts toward regional sourcing agreements. Carhartt Inc. leverages its workwear brand strength to anchor direct-to-crew sales channels. Honeywell International Inc. competes through integrated safety system bundling that extends beyond garments into connected worker platforms. Portwest Ltd. specializes in European-certified high-visibility lines that navigate complex EN ISO 20471 compliance tiers.
High visibility clothing denotes safety apparel engineered with fluorescent background materials and retroreflective strips to maximize conspicuity under vehicular headlights and ambient light conditions, typically manufactured through heat-transfer lamination of glass-bead or microprismatic tape onto polyester or blended fabric substrates. The primary purpose is to reduce struck-by incidents in environments where workers operate near moving traffic or mechanized equipment. Vests dominate volume sales as the entry-level compliance purchase for temporary and seasonal workforces, while jackets command margin concentration due to weatherproofing integration and extended replacement cycles. Polyester leads material selection for its fluorescent color retention and abrasion resistance, though cotton blends gain traction in welding and electrical applications where static dissipation and spark resistance matter.
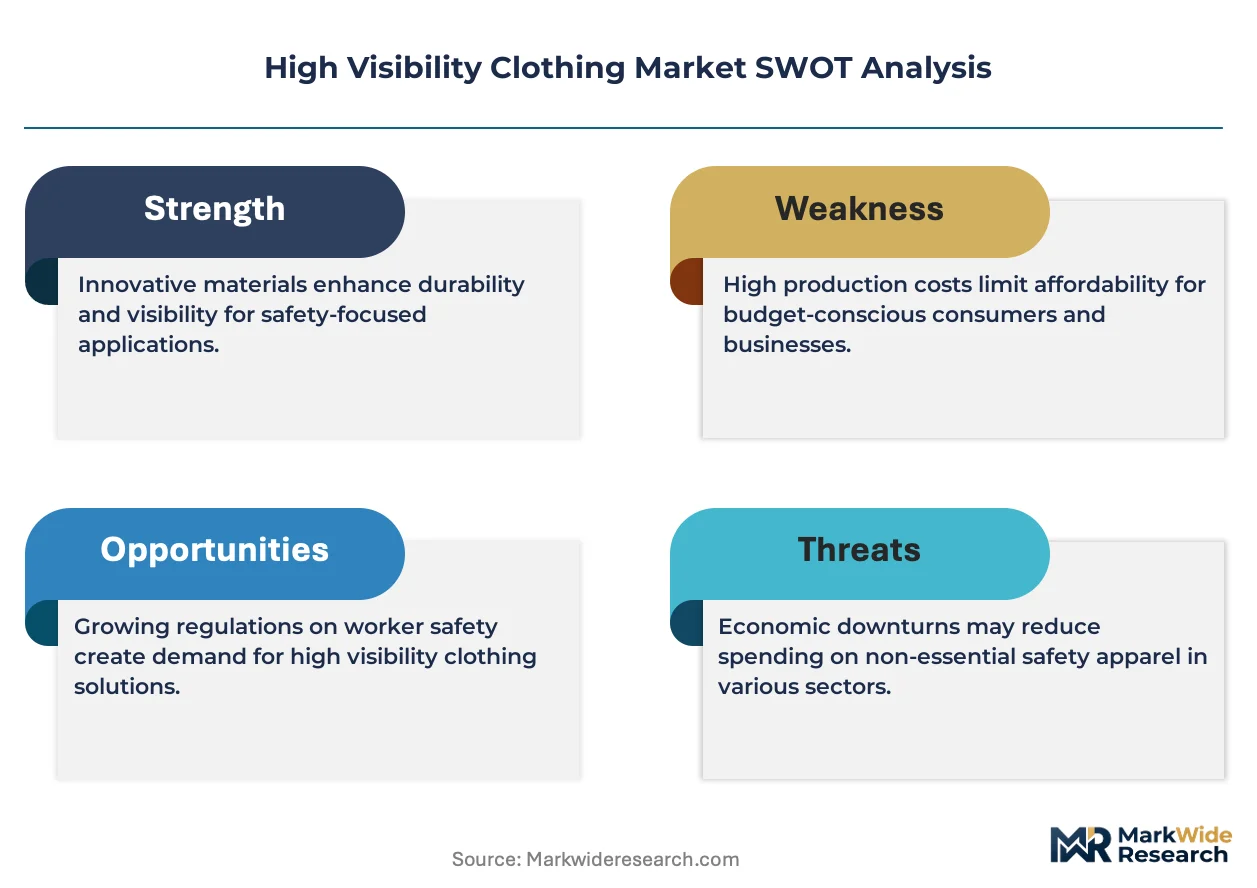
OSHA workplace safety directives and ANSI/ISEA 107 standards in the United States, alongside EN ISO 20471 in Europe and CSA Z96 in Canada, collectively mandate minimum visible surface areas and retroreflective performance classes that shape product design and market access requirements. China's GB 20653 standard and emerging provincial enforcement by MEE-affiliated labor inspectorates are tightening compliance verification for domestic manufacturers and export-bound suppliers alike. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's ecodesign requirements will reshape material sourcing, dye chemistry, and end-of-life garment recovery obligations.
Market Dynamics
Construction sector procurement of ANSI/ISEA Class 3 garments is forcing suppliers to reposition around multi-shift durability guarantees rather than unit price competition.
Growth Catalysts
- Infrastructure spending mandates:Federal highway appropriations in the United States are accelerating occupational safety enforcement by OSHA-affiliated state plans. Demand for Class 3 ensembles concentrates on bridge and roadway rehabilitation crews.
- EN ISO 20471 certification tiers:European Union member states are harmonizing visible surface area requirements for temporary traffic management. Portwest Ltd. and specialized suppliers are capturing margin through compliance navigation services.
- Microprismatic retroreflective tape:Glass-bead technology is losing share to microprismatic substrates that maintain coefficient of retroreflection across wash cycles. Polyester substrate lamination lines are retooling for higher adhesive bond strength.
Market Restraints
- Petroleum-derived input volatility:Polyester fiber and synthetic dye precursors track crude oil futures. Margin compression hits mid-tier suppliers without backward integration into polymer production.
- Regional sourcing concentration:High-visibility garment assembly concentrates in Guangdong and Zhejiang provinces. MEE-affiliated labor inspectorates are tightening environmental compliance verification, extending lead times for export-bound orders.
- Technical limitation in cotton blends:Fluorescent color retention in cotton-polyester substrates degrades faster than pure polyester under UV exposure. Welding applications face trade-offs between spark resistance and conspicuity longevity.
Strategic Opportunities
- Connected worker platform integration:Honeywell International Inc. and industrial safety conglomerates are bundling garments with IoT-enabled location tracking. Retroreflective strips now embed RFID and low-power beacon substrates.
- India infrastructure build-out:National highway expansion and smart city programs are creating first-time demand for certified high-visibility apparel. BIS standards alignment with EN ISO 20471 is opening import substitution opportunities.
- Ecodesign and end-of-life recovery:EU Green Deal requirements are mandating recycled polyester content and take-back programs. Suppliers with closed-loop chemical recycling capabilities are securing preferential procurement status.
Industry Challenges
- Multi-standard certification complexity:Simultaneous compliance with ANSI/ISEA 107, EN ISO 20471, and CSA Z96 requires distinct pattern grading and testing protocols. Product development cycles extend by 4-6 months for cross-border portfolios.
- Heat-transfer lamination skill scarcity:Microprismatic tape application demands precise temperature and pressure calibration. Technical operators with garment-finishing expertise command wage premiums in manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Visibility Clothing Market |
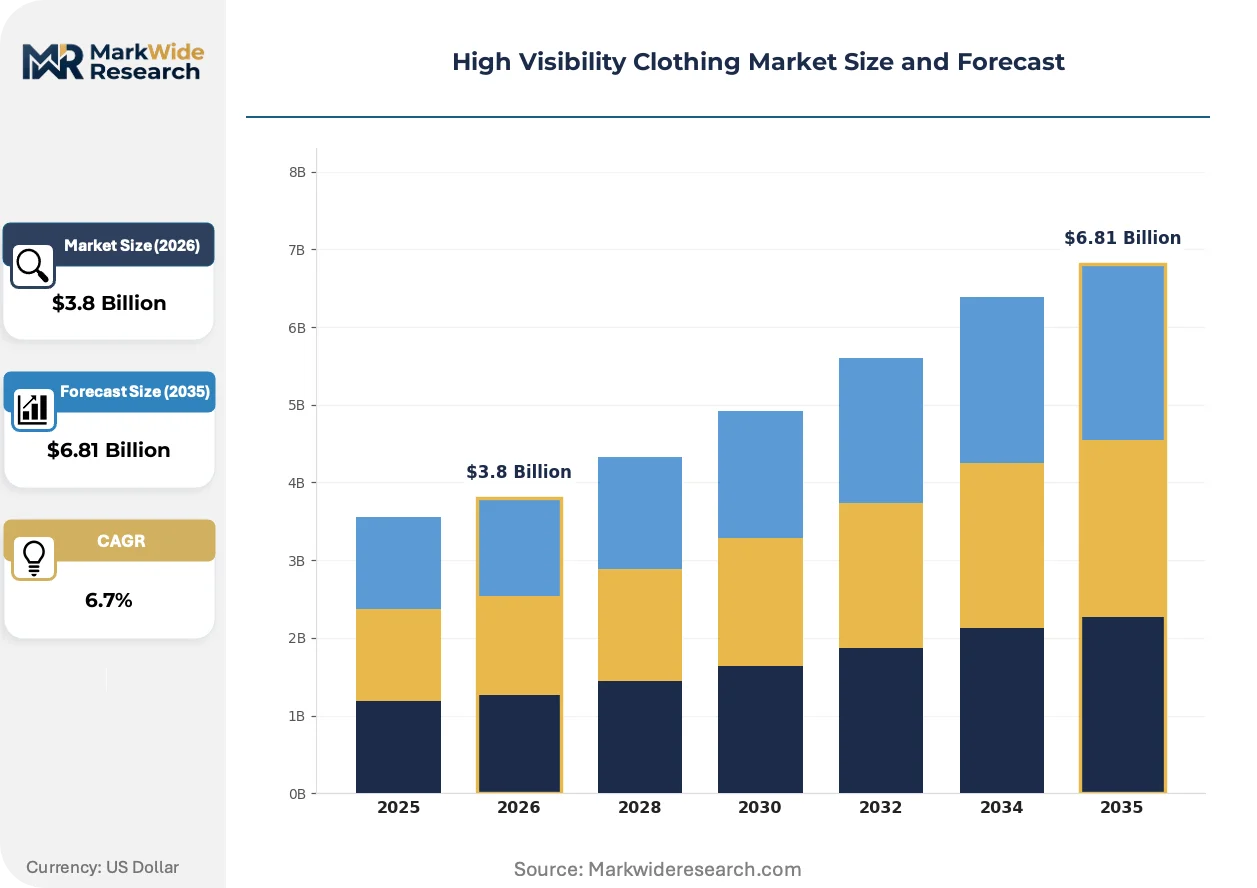
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vests, Jackets, Trousers, Overalls Material: Polyester, Cotton, Blended Fabrics, Reflective Tape End User: Construction, Road Safety, Emergency Services, Warehouse Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Ansell Ltd., Carhartt Inc., 3M Company, Cintas Corporation, Lakeland Industries Inc., Honeywell International Inc., DuPont de Nemours, Inc., Delta Plus Group, Portwest Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Visibility Clothing Market Strategic Shifts
Retroreflective technology convergence with digital tracking systems is redefining garment functionality beyond passive visibility. Material science advances and regulatory harmonization pressures are simultaneously elevating performance floors and compressing compliance timelines.
Microprismatic retroreflective tape is expanding into multi-shift durability applications previously served by glass-bead substrates. Municipal transportation departments and utility contractors are specifying microprismatic coefficients for 50+ wash cycle retention. This displacement is compressing supplier margins on legacy glass-bead lines while rewarding capital investment in precision lamination equipment.
EU Green Deal ecodesign requirements are mandating recycled content thresholds and chemical hazard disclosure across textile supply chains. REACH compliance costs for fluorescent dye formulations are rising, favoring suppliers with in-house toxicology and substitution capabilities. Premium workwear brands are responding with blockchain-tracked material provenance to preempt regulatory friction.
Regional sourcing agreements are displacing national fleet contracts among mid-sized construction subcontractors. Carhartt Inc. and direct-to-crew channels are capturing volume previously routed through industrial distributors. This fragmentation is most visible in Texas, Florida, and California where infrastructure spending concentrates and local safety councils enforce ANSI compliance variably.
High Visibility Clothing Market Segmentation
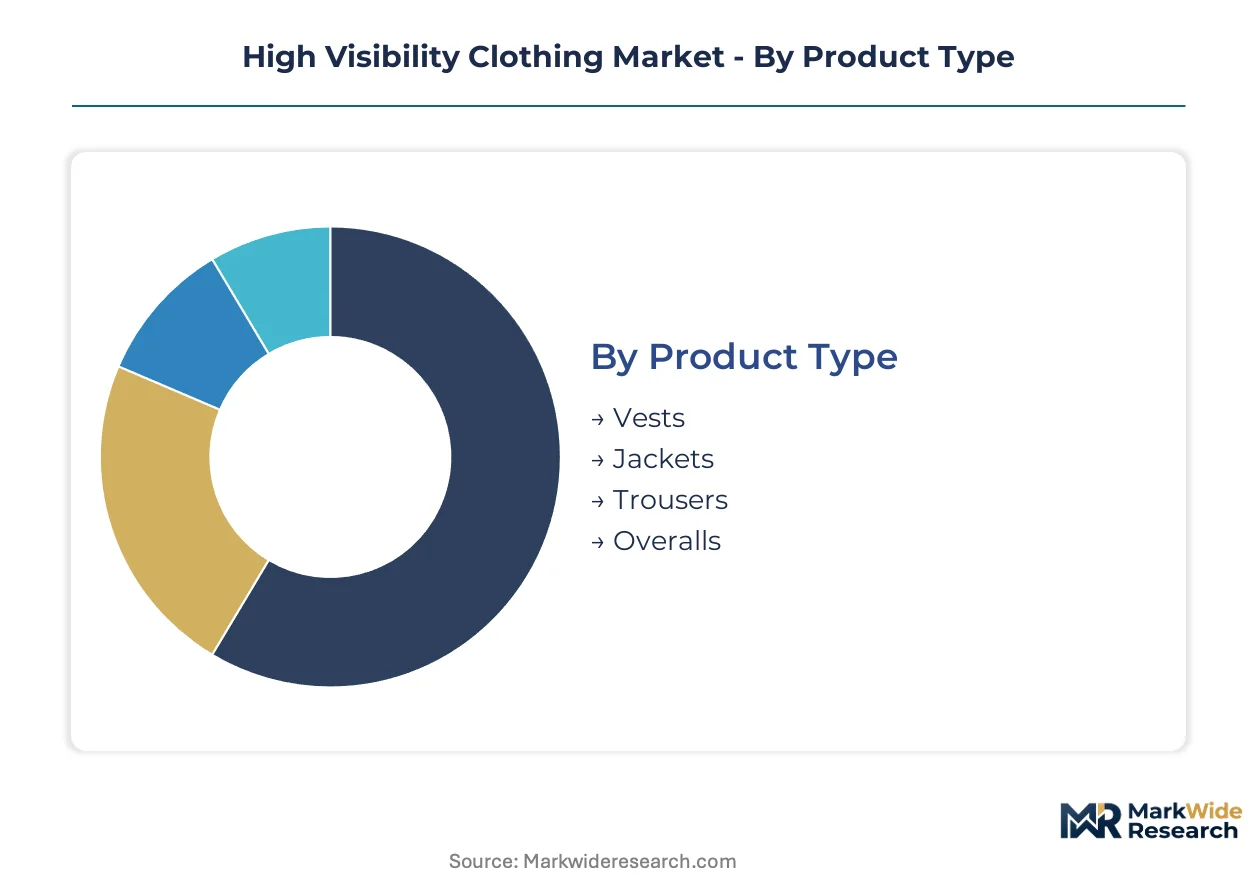
Segmentation in high visibility clothing reflects divergent procurement logics across compliance regimes, environmental exposure, and workforce mobility patterns. Buyers prioritize certification tier, material durability under specific hazards, and channel convenience rather than brand loyalty alone.
Product Type:
Volume concentration versus margin capture drives purchase decisions across garment categories.
- Vests:Sleeveless designs with fluorescent polyester shells and retroreflective striping dominate entry-level compliance purchases. Road safety crews and temporary construction labor in the United States and Germany absorb standardized Class 2 and Class 3 vests through high-frequency replacement cycles driven by soiling and mechanical wear.
- Jackets:Weatherproofed shells with integrated thermal liners and extended retroreflective surface areas command premium positioning. Bridge rehabilitation contractors and utility workers in climates with extended wet seasons specify jackets for multi-shift durability guarantees rather than per-unit cost minimization.
- Trousers:Lower-body visibility garments with segmented reflective banding address struck-from-behind incidents in warehousing and logistics environments.
- Overalls:Full-coverage designs combining upper and lower visibility requirements serve specialized applications in rail maintenance and tunnel construction.
Vests lead on scale; jackets lead on momentum.
Material:
Performance under environmental stress and regulatory chemistry restrictions shapes substrate selection.
- Polyester:Synthetic fibers with superior fluorescent dye retention and abrasion resistance anchor standard-issue procurement. OSHA-affiliated state plans in the United States and EN ISO 20471 enforcement across European Union member states validate polyester as the baseline compliance material for high-cycle applications.
- Blended Fabrics:Cotton-polyester combinations balance spark resistance with moderate conspicuity for welding and electrical trades. Utility contractors in Germany and France specify blends where static dissipation matters more than wash-cycle longevity.
- Cotton:Natural fiber substrates serve niche applications requiring maximum breathability in extreme heat conditions.
- Reflective Tape:Glass-bead and microprismatic substrates laminated to base garments determine coefficient of retroreflection performance independent of shell material.
Polyester leads on scale; blended fabrics lead on momentum.
End User:
Regulatory enforcement intensity and incident liability exposure differentiate sector procurement priorities.
- Construction:Highway and bridge contractors face the strictest ANSI/ISEA 107 and EN ISO 20471 compliance verification. Federal infrastructure appropriations in the United States and national highway expansion in India are concentrating demand for Class 3 ensembles with documented wash-cycle retention.
- Road Safety:Municipal transportation departments and temporary traffic management operators specify microprismatic performance tiers for nighttime visibility under variable lighting conditions.
- Emergency Services:Fire and rescue personnel require flame-resistant shells with retroreflective trim that survives thermal exposure.
- Warehouse:Indoor logistics operations with forklift traffic prioritize cost-efficient Class 2 compliance over weatherproofing features.
Construction leads on scale; road safety leads on momentum.
Distribution Channel:
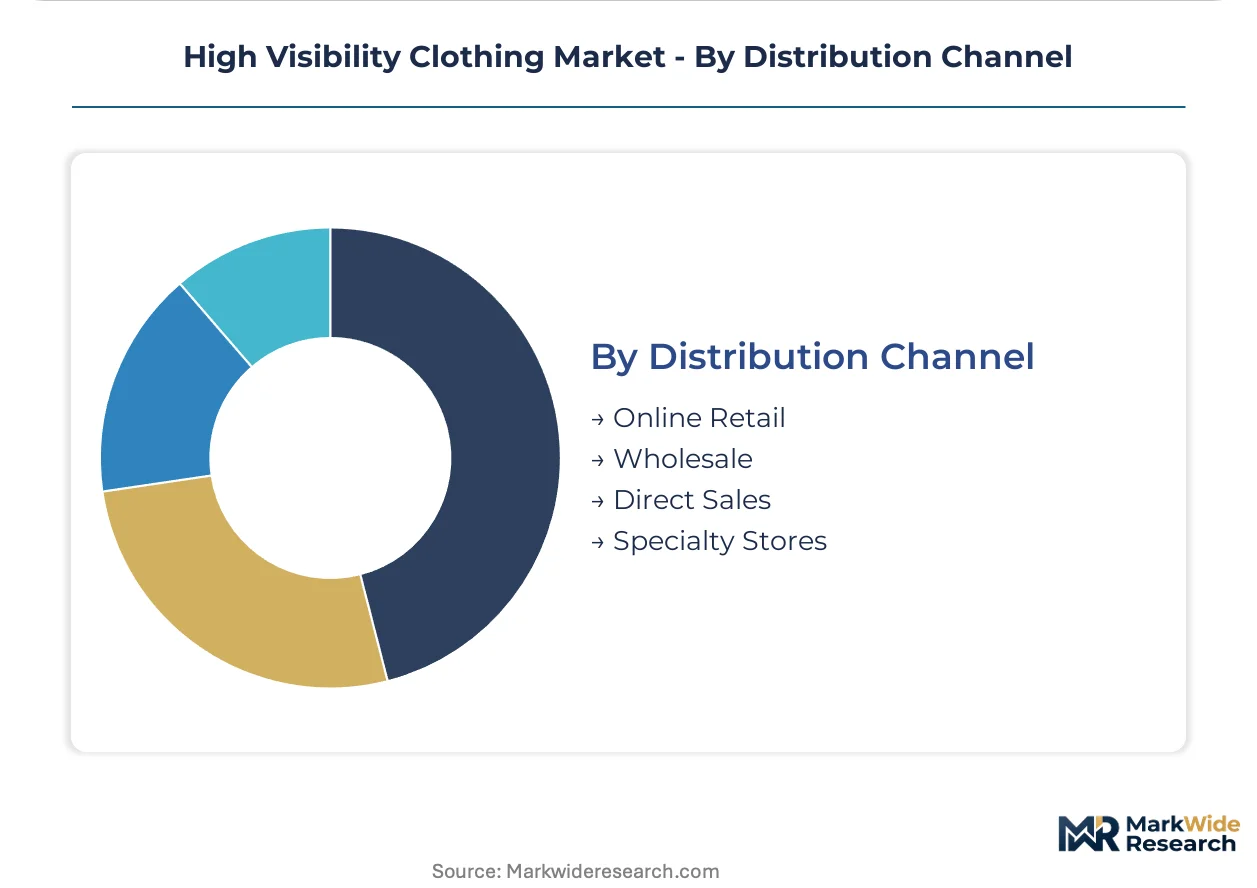
Buyer scale and replenishment urgency determine channel selection across fragmented and concentrated procurement patterns.
- Wholesale:Industrial distributors aggregate volume for mid-sized construction subcontractors and municipal fleet purchasers. Regional sourcing agreements in Texas, Florida, and California displace national contracts as local safety councils enforce variable ANSI compliance interpretations.
- Direct Sales:Manufacturer-to-crew channels bypass distributor markups for large employers with standardized specifications. Carhartt Inc. anchors this channel through workwear brand recognition among construction foremen.
- Online Retail:E-commerce platforms serve small contractors and individual tradespeople with immediate replenishment needs.
- Specialty Stores:Local safety equipment retailers provide fit verification and compliance consultation for complex multi-standard requirements.
Wholesale leads on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's infrastructure build-out and the United States' federal highway appropriations are driving divergent procurement patterns, with the former emphasizing export manufacturing capacity and the latter concentrating on domestic compliance enforcement.
United States
Federal highway rehabilitation programs and bridge maintenance contracts are accelerating ANSI/ISEA Class 3 garment procurement. OSHA-affiliated state plans in Texas, California, and Florida enforce variable compliance interpretations that favor regional sourcing agreements over national fleet contracts. Houston and Dallas construction clusters are absorbing multi-shift durability guarantees as procurement criteria displace unit-price competition.
Germany
Autobahn expansion and renewable energy infrastructure projects are concentrating demand for EN ISO 20471-certified ensembles. REACH compliance costs for fluorescent dye formulations are rising, favoring suppliers with in-house toxicology capabilities. The Ruhr industrial corridor and Bavarian construction hubs are validating polyester substrates for high-cycle applications under stricter chemical disclosure mandates.
China
Provincial enforcement by MEE-affiliated labor inspectorates is tightening environmental compliance verification for export-bound manufacturers. Dual carbon goals are reshaping material sourcing and dye chemistry across Guangdong and Zhejiang garment assembly clusters. Shenzhen and Hangzhou production facilities are retooling for higher adhesive bond strength in microprismatic tape lamination lines.
India
National highway expansion and smart city programs are creating first-time demand for certified high-visibility apparel. BIS standards alignment with EN ISO 20471 is opening import substitution opportunities for domestic manufacturers. Maharashtra and Karnataka infrastructure corridors are specifying Class 2 and Class 3 compliance for road safety crews and bridge rehabilitation contractors.
Canada
Municipal transportation departments and utility contractors are specifying CSA Z96-compliant garments for nighttime visibility under variable lighting conditions. Federal infrastructure spending is concentrating procurement in Ontario and British Columbia construction markets. Vancouver and Toronto metropolitan areas are adopting microprismatic performance tiers for temporary traffic management operations.
High Visibility Clothing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers and distribution channels. The vendor base separates into three strategic archetypes: industrial safety conglomerates bundling garments with connected worker platforms, workwear heritage brands anchoring direct-to-crew channels, and European-certified specialists navigating complex compliance hierarchies. Dominant competitive moves include portfolio diversification into IoT-enabled location tracking and geographic expansion through regional sourcing partnerships.
Within the workwear heritage tier, Carhartt Inc. exemplifies brand-driven direct sales positioning among construction foremen. Honeywell International Inc. represents the industrial safety conglomerate archetype through integrated system bundling. Portwest Ltd. occupies a specialized position in European-certified high-visibility lines, anchoring compliance navigation services for EN ISO 20471 tiered requirements.
| Leading Market Players |
|---|
| Ansell Ltd. |
| Carhartt Inc. |
| 3M Company |
| Cintas Corporation |
| Lakeland Industries Inc. |
| Honeywell International Inc. |
| DuPont de Nemours, Inc. |
| Delta Plus Group |
| Portwest Ltd. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into polyester fiber production anchors pricing power for high-visibility garment suppliers operating across Guangdong and Zhejiang provinces. Captive control over fluorescent dye formulation and retroreflective tape lamination insulates margin structures from petroleum derivative volatility while enabling compliance premium capture.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for entry-level ANSI Class 2 vests. Three-tier pricing structure across premium microprismatic, standard glass-bead, and economy uncertified levels stratifies procurement decisions. Cost compression in economy tiers intensifies because of raw material pass-through from crude oil futures. Municipal fleet purchasers exhibit highest price sensitivity; utility contractors with multi-shift durability requirements demonstrate lowest.
Supply Chain Analysis
Skilled heat-transfer lamination operators command wage premiums in Guangdong and Zhejiang manufacturing clusters. Supply draws from China, Vietnam, and Bangladesh for garment assembly, with retroreflective tape sourcing concentrated in China and the United States. Raw material dependencies include polyester chips, glass-bead substrates, and microprismatic films. Single-source vulnerability in certified tape suppliers creates bottleneck risk. Distribution runs through industrial distributors and direct-to-crew channels to construction subcontractors and municipal fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's tightening MEE environmental enforcement and India's emerging BIS certification infrastructure creates margin capture opportunities for suppliers repositioning production footprints.
For Market Incumbents: Deploy compliance navigation services as a lever to lock in municipal transportation department contracts before EN ISO 20471 harmonization completes. Invest in closed-loop chemical recycling capabilities to preempt EU Green Deal recycled content mandates. Counter glass-bead to microprismatic substitution pressure by anchoring multi-shift durability guarantees. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian road safety procurement creates white-space entry. Target Maharashtra and Karnataka infrastructure corridors where BIS standards alignment with EN ISO 20471 is opening first-time certified apparel demand. Capture volume through regional sourcing partnerships with state-level contractors bypassing national distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for European-certified specialists because fragmented EN ISO 20471 compliance navigation services lack scale players. Five-to-ten year viability hinges on carbon border adjustment mechanism exposure and recycled polyester feedstock access. Monitor MEE-affiliated labor inspectorate enforcement intensity in Guangdong as inflection indicator for supply chain relocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Microprismatic Tape Lamination Capacity Expansion | Retooling polyester substrate lines for 50+ wash cycle retention meets municipal specification upgrades. |
| Connected Worker Platform Integration | Embedding RFID and low-power beacon substrates into retroreflective strips enables IoT-enabled location tracking bundling. |
| Regional Sourcing Partnership Development | Direct-to-crew channels in Texas and Florida capture volume from fragmented mid-sized construction subcontractors. |
| Closed-Loop Chemical Recycling Investment | In-house polyester recovery capabilities secure preferential procurement status under EU Green Deal requirements. |
| Multi-Standard Certification Portfolio Buildout | Simultaneous ANSI/ISEA 107, EN ISO 20471, and CSA Z96 compliance extends product development cycles but opens cross-border contracts. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged safety apparel procurement managers at highway contractors, regulatory affairs leads at certification bodies, plant managers at polyester fiber producers, and channel heads at industrial distributors. Secondary sources included OSHA enforcement databases, ECHA REACH registration dossiers, MEE environmental compliance bulletins, and customs trade records for retroreflective tape imports. Bottom-up volume modeling and top-down market sizing triangulated demand estimates.
Granularity-level modeling applied product type, material substrate, end-use sector, and distribution channel dimensions across the analysis window. CAGRs derived from segment-level growth rate reconciliation against macroeconomic infrastructure spending trajectories. Forecast inputs incorporated federal highway appropriation schedules, provincial enforcement intensity indices for MEE labor inspectorates, and microprismatic tape adoption curves in municipal specifications.
Caveats apply where petroleum price volatility, tariff restructuring, or sudden regulatory harmonization could materially shift the outlook. Forecasts reflect assumptions about infrastructure spending continuity and certification standard stability. Practitioners should monitor EN ISO 20471 amendment cycles and dual carbon goal implementation pace in China for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market