
 Workwear Market | 2026-2036
Workwear Market Size, Share, and Industry Trends Forecast 2026-2036
Workwear Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is repositioning workwear demand toward garments with verifiable recycled content and transparent supply chains. In this context, Carhartt leverages its brand heritage in durability while adapting to new material standards for its core customer base. Honeywell International specializes in high-performance protective gear, integrating advanced materials to meet stringent safety and sustainability criteria. Meanwhile, Engelbert Strauss dominates the European market through direct-to-consumer channels and innovative product designs that blend function with modern aesthetics.
Workwear encompasses apparel and accessories designed for specific occupational tasks, prioritizing durability, safety, and functionality. These garments often feature reinforced seams, specific fabric weights such as 12-ounce cotton duck, and treatments for properties like flame resistance or water repellency. Demand from the construction and manufacturing end-user segments continues to drive volume for standard workwear products. High-visibility and flame-resistant clothing categories command higher margins due to specialized material requirements and mandatory performance certifications.
Occupational safety regulations, such as those from the US Occupational Safety and Health Administration (OSHA), mandate specific protective qualities in hazardous work environments. In Europe, the REACH regulation governs chemical use in textiles, directly influencing material selection for manufacturers. Concurrently, global standards like ISO 20471 for high-visibility clothing create a baseline for product design and market access. Stakeholder success will depend on navigating the complex interplay between regional safety mandates and emerging global sustainability benchmarks for textiles.
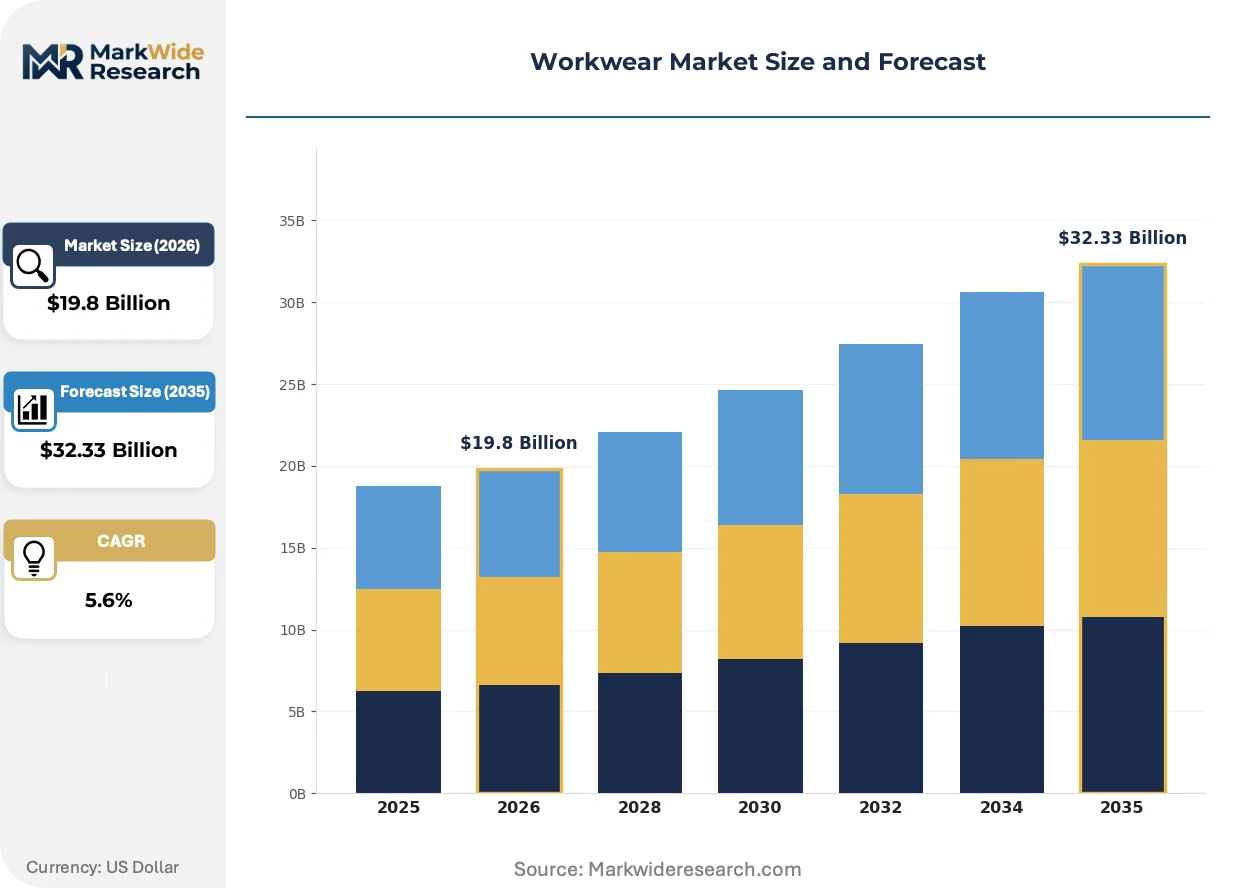
Market Dynamics
The convergence of stringent occupational safety mandates and emerging sustainability disclosure rules is the central structural force shaping the workwear market. This dual pressure accelerates innovation in material science and demands greater transparency throughout the supply chain.
Growth Catalysts
- Infrastructure Spending:Heightened infrastructure investment in the United States directly boosts demand for certified protective apparel in construction, governed by OSHA standards.
- Sustainability Reporting:The EU's CSRD framework pressures companies to adopt workwear with verifiable recycled content, shifting procurement criteria for industrial buyers.
- Advanced Materials:Lighter, more breathable flame-resistant fabrics are expanding adoption in the energy sector, where comfort improves compliance with safety protocols.
Market Restraints
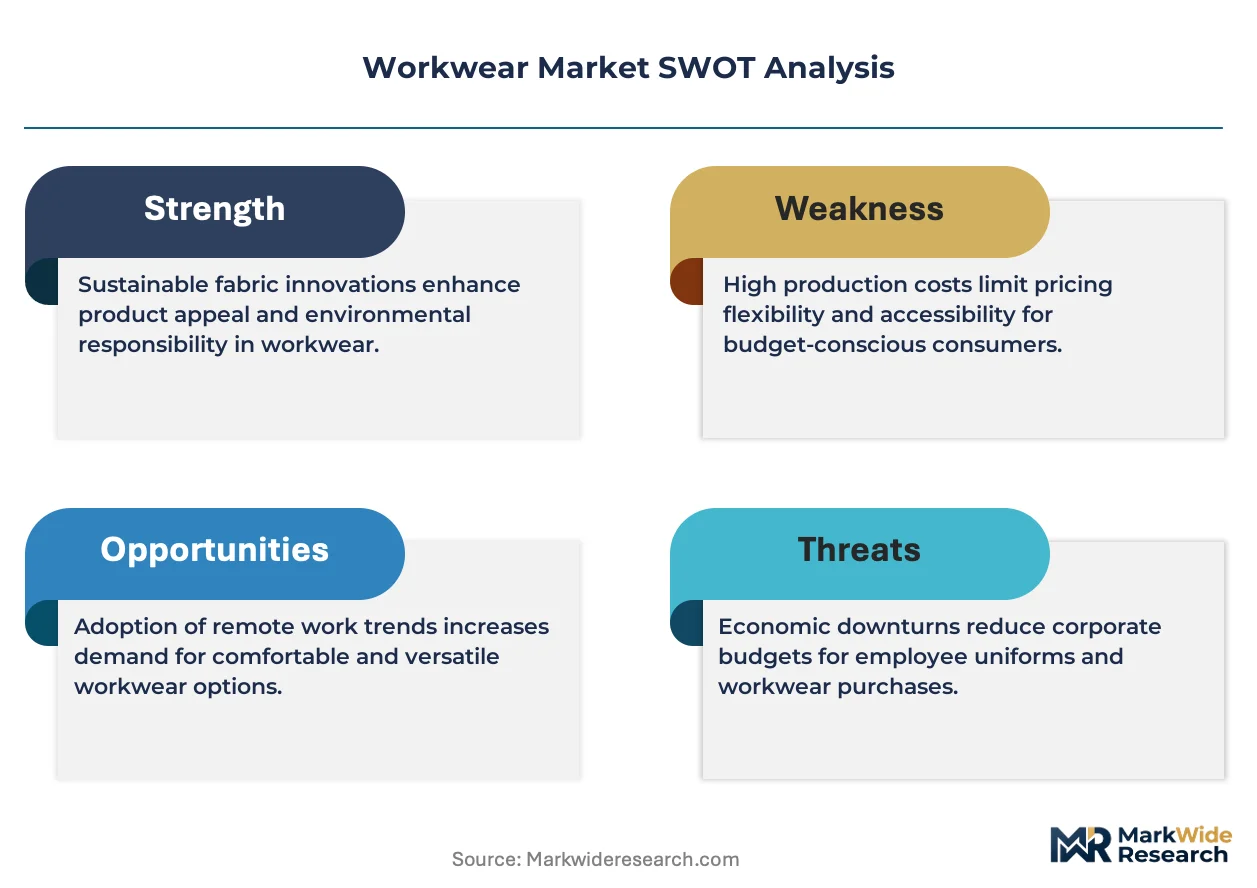
- Raw Material Volatility:Price fluctuations in cotton and petroleum-derived synthetic fibers create margin pressure and complicate long-term pricing for manufacturers.
- Regulatory Fragmentation:Divergent certification requirements, such as Europe's CE marking versus US ANSI standards, increase design and testing costs for global suppliers.
- Manufacturing Concentration:Heavy reliance on textile production hubs in a few Asian countries creates supply chain vulnerabilities and geopolitical risk exposure.
Strategic Opportunities
- Smart Workwear Integration:Embedding biometric sensors into garments offers new data-driven safety services for high-risk sectors like mining and emergency response.
- Emerging Market Penetration:Growing safety standard adoption in Latin American and Southeast Asian industrial sectors presents new markets for certified workwear.
- Direct-to-Consumer Channels:D2C e-commerce platforms allow brands to engage directly with independent contractors, bypassing traditional industrial distributors for specialized trades.
Industry Challenges
- Dynamic Regulatory Compliance:Managing chemical inventories to comply with evolving substance restrictions, such as the EU's REACH regulation, requires continuous supply chain auditing and material re-qualification.
- Counterfeit PPE:The circulation of uncertified and counterfeit protective garments, particularly through online marketplaces, poses a direct safety hazard and undermines the value of legitimate certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workwear Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.33 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Workwear, High-visibility Clothing, Flame-resistant Clothing, Protective Gear End User: Construction, Manufacturing, Healthcare, Hospitality Material: Cotton, Polyester, Leather, Nylon Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Honeywell International, Cintas, Carhartt, Portwest, 3M Company, Dickies, Aramark Corporation, Engelbert Strauss, VF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workwear Market Strategic Shifts & Innovations
A fundamental shift is underway from passive, durable apparel to active, intelligent systems that monitor worker safety in real-time. This evolution is driven by advancements in sensor technology and the growing demand for verifiable worksite safety data.
Integrated sensor technology embeds biometric and environmental detectors directly into the fabric of workwear. High-risk industries, including mining and utilities, are piloting these garments to monitor worker vitals and detect hazardous exposures. This fusion of textiles and electronics is electrifying the concept of personal protective equipment, turning passive garments into active safety monitoring platforms.
The global adoption of the ISO 45001 standard for occupational health and safety management systems is influencing corporate PPE procurement policies. This framework encourages a risk-based approach, moving beyond mere compliance to proactive hazard mitigation for employees. Consequently, multinational corporations are standardizing their workwear specifications globally, favoring suppliers who can meet these elevated, consistent safety benchmarks across different regions.
Procurement models are evolving from capital purchases to managed service contracts that include garment rental, cleaning, and maintenance. This disrupts traditional distributor relationships and moves workwear costs from capex to opex for end-users. This trend is most prominent among large enterprises in North America and Europe seeking to ensure compliance and offload inventory management.
Workwear Market Segmentation
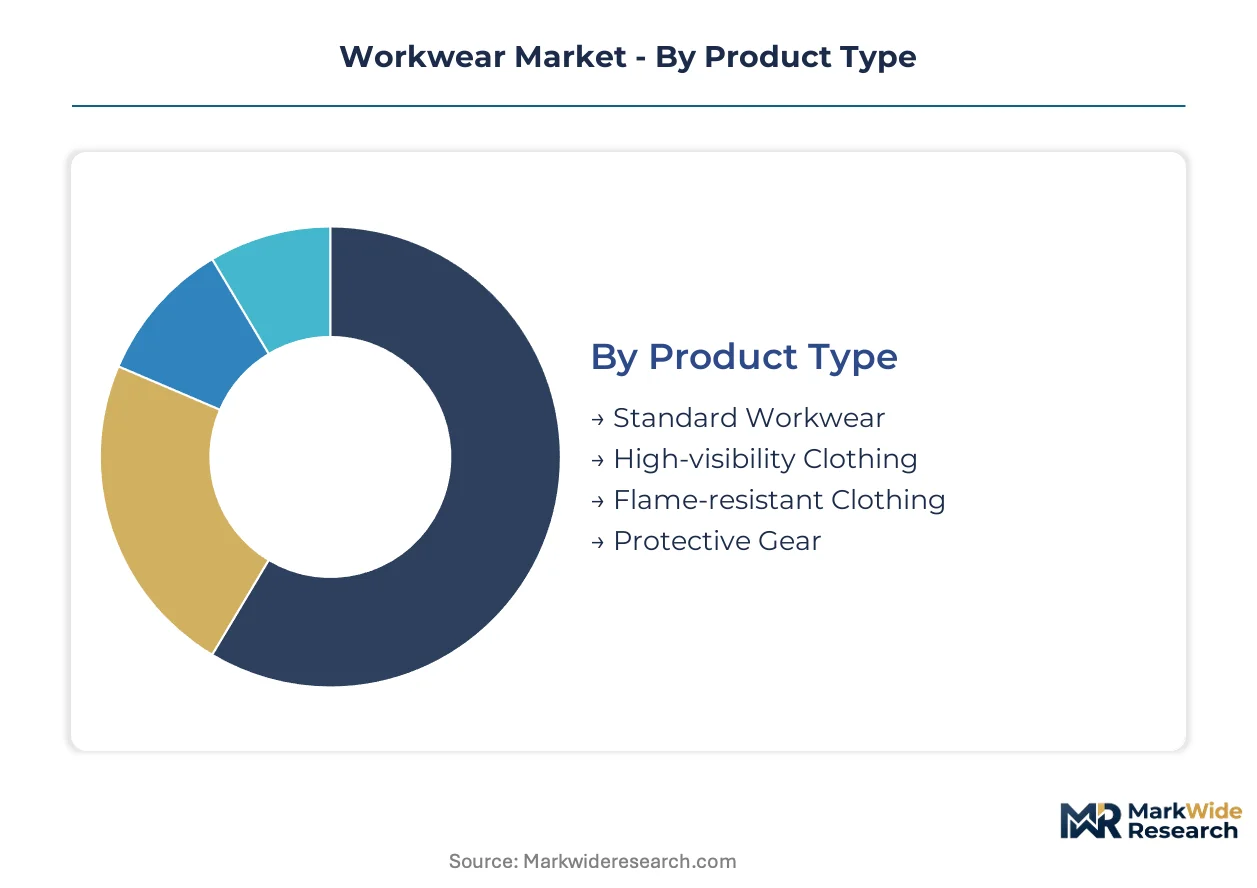
The workwear market's segmentation reflects the diverse requirements of various industries, driven by specific safety standards, material innovations, and evolving procurement methods. Understanding these distinct segments is crucial for manufacturers to tailor product development and for buyers to optimize their protective apparel strategies.
Product Type:
Workwear is categorized by the specific protective technologies and functional specifications embedded within the garments.
- High-visibility Clothing:These garments incorporate fluorescent materials and reflective strips to ensure worker visibility, particularly in low-light conditions or high-traffic areas. Demand concentrates in construction and road maintenance, driven by safety mandates like ISO 20471 standards.
- Flame-resistant Clothing:Designed with inherently flame-resistant fabrics or chemically treated materials, these garments protect against thermal hazards and arc flashes. The energy sector and heavy manufacturing drive procurement, often mandated by OSHA regulations for worker safety.
- Standard Workwear:This category encompasses durable apparel focused on comfort, abrasion resistance, and longevity for general industrial tasks. It forms the volume backbone across various blue-collar professions.
- Protective Gear:This segment includes accessories such as gloves, helmets, and safety footwear, providing specialized protection for specific occupational hazards.
Standard Workwear leads on scale; Flame-resistant Clothing leads on momentum.
End User:
The application context defines the requirements for workwear, with distinct needs across various industrial and service sectors.
- Construction:This segment demands rugged, durable, and often high-visibility workwear capable of withstanding harsh environmental conditions and physical stress. Heightened infrastructure investment in the United States and stringent OSHA mandates drive significant volume.
- Manufacturing:Workers in manufacturing require apparel that offers protection against machinery, chemicals, and heat, alongside comfort for prolonged wear. Industrial corridors globally, particularly where advanced manufacturing occurs, generate consistent demand.
- Healthcare:This sector requires workwear that prioritizes hygiene, ease of cleaning, and comfort for medical professionals. Garments often feature antimicrobial properties and specific ergonomic designs.
- Hospitality:Workwear in hospitality focuses on professional appearance, stain resistance, and comfort for staff in hotels, restaurants, and catering services.
Construction and Manufacturing collectively represent the largest volume drivers for workwear products.
Material:
The choice of raw material significantly influences garment performance, cost structure, and sustainability profile in workwear production.
- Cotton:A natural fiber known for its breathability, comfort, and absorbency, cotton is a staple in general workwear. Sustainability initiatives, particularly those focused on verifiable recycled content, are influencing its procurement.
- Polyester:This synthetic fiber offers durability, wrinkle resistance, and moisture-wicking properties, making it suitable for high-performance and blended workwear. Its price volatility, however, creates margin pressure for manufacturers.
- Leather:Primarily used for protective accessories like gloves and aprons, leather provides superior cut, abrasion, and heat resistance. It serves specialized heavy-duty applications.
- Nylon:Renowned for its strength-to-weight ratio and elasticity, nylon is incorporated into specialized protective garments requiring high durability and flexibility.
Sustainability pressures are re-evaluating the long-term material mix, especially concerning recycled content in synthetics.
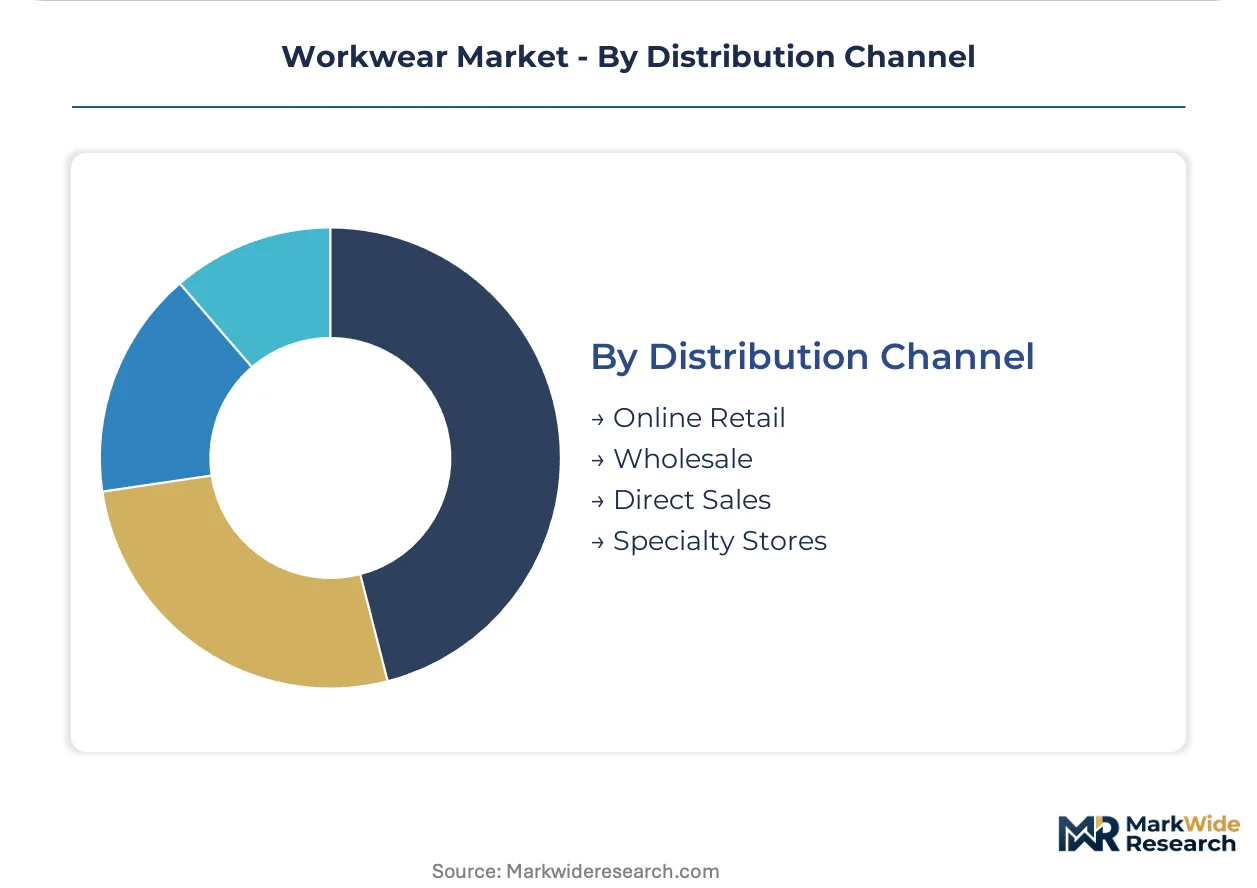
Distribution Channel:
Customer purchasing preferences and supply chain efficiency dictate the primary distribution pathways for workwear products.
- Wholesale:This channel involves large-volume sales to industrial distributors and corporate clients, often through established supply chain networks. It facilitates managed service contracts for large enterprises.
- Online Retail:E-commerce platforms provide a direct-to-consumer model, allowing brands to reach independent contractors and specialized trades directly. This channel offers convenience and broader product accessibility.
- Direct Sales:Manufacturers engage directly with large institutional buyers for customized workwear solutions and bulk orders. This approach allows for tailored product offerings and service agreements.
- Specialty Stores:These retail outlets offer a curated selection of workwear, often providing expert advice and fitting services for specific occupational requirements.
The shift towards direct-to-consumer models through online retail is altering traditional distribution dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The workwear market's foundational demand originated in industrializing nations, particularly with the rise of heavy manufacturing and construction in the United States and Western Europe. Early safety standards and the need for durable garments established initial production centers. This historical lineage continues to influence regional market dynamics and regulatory frameworks.
United States
Heightened infrastructure investment drives demand for certified protective apparel in construction. OSHA mandates specific protective qualities for hazardous work environments. Industrial corridors across the Midwest and Southeast exhibit strong localized demand for high-performance workwear.
Germany
The market benefits from a strong manufacturing base and stringent occupational safety standards. REACH regulation governs chemical use in textiles, influencing material selection for German manufacturers. The Rhine-Ruhr region, a historic industrial heartland, remains a hub for workwear procurement.
China
Rapid industrial expansion and growing awareness of worker safety are boosting demand for compliant workwear. GB standards are progressively aligning with international safety benchmarks for personal protective equipment. Manufacturing clusters in the Yangtze River Delta drive significant volume.
India
Infrastructure projects and an expanding manufacturing sector are accelerating the need for durable workwear. The country's national occupational safety guidelines are being reinforced to improve worker protection. Industrial zones around Mumbai and Chennai show increasing procurement.
United Kingdom
Strong construction activity and established industrial sectors maintain consistent demand for protective apparel. Health and Safety Executive (HSE) regulations enforce compliance for workplace safety gear. Manufacturing facilities in the Midlands region represent a significant end-user segment.
Workwear Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the workwear market, creating a tiered structure. The market exhibits consolidation among established brands providing certified protective gear, alongside fragmentation among smaller, specialized apparel manufacturers. Two strategic archetypes emerge: integrated manufacturers controlling supply chains, and design-focused brands leveraging outsourcing. Dominant competitive moves include strategic partnerships for material innovation and geographic expansion into emerging industrial markets.
At the scale-driven end, Honeywell International, a multinational conglomerate, exemplifies companies offering a broad portfolio of high-performance protective gear and advanced material integration. Carhartt, leveraging its long-standing heritage, represents brands focused on durability and traditional workwear aesthetics for core customer bases. Engelbert Strauss, a European-based company, occupies a position among innovators blending function with modern design, often utilizing direct-to-consumer channels for market penetration. These entities collectively anchor different facets of the market, from highly technical safety solutions to lifestyle-oriented functional apparel.
| Leading Market Players |
|---|
| Honeywell International |
| Cintas |
| Carhartt |
| Portwest |
| 3M Company |
| Dickies |
| Aramark Corporation |
| Engelbert Strauss |
| VF Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration by large manufacturers anchors their supply position and grants them significant pricing power in specialized workwear segments. This strategic choice influences both cost structures and market entry barriers for new competitors.
Pricing Analysis
Contract-based long-term agreements dominate procurement for large industrial buyers, while transactional pricing serves smaller businesses. Price differentiation stems from mandated safety certifications and the verifiable sustainable material content of garments. Margin compression stems from raw material volatility in cotton and synthetic fibers, impacting manufacturers' profitability. Independent contractors exhibit higher price sensitivity than multinational corporations prioritizing compliance with stringent safety standards.
Supply Chain Analysis
Raw material supply for workwear largely draws from textile production hubs in China, India, and Southeast Asian countries. Dependencies include cotton fibers, petroleum-derived synthetics, and specialized chemical treatments for properties like flame resistance. Geopolitical risk exposure creates structural vulnerabilities within this concentrated manufacturing base. Wholesale industrial distributors remain the primary downstream channel for large enterprises, alongside growing direct-to-consumer online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workwear market functions as a late-cycle quality story, with demand shifting toward premium specifications driven by heightened safety protocols and sustainability mandates.
For Market Incumbents: Acquire advanced material science firms to secure intellectual property in lighter, more breathable flame-resistant fabrics. This defends against emerging specialized entrants and counteracts margin pressure from raw material fluctuations. Investment in digital traceability platforms can combat counterfeit PPE circulation and reinforce certification integrity under ISO 45001 standards.
For New Entrants and Emerging Players: A price-point gap exists between highly specialized protective gear and basic standard workwear, offering market entry opportunities. Focus on smart workwear integration for high-risk sectors like mining, leveraging data-driven safety services. Penetrate Latin American industrial sectors through direct-to-consumer e-commerce platforms, offering certified products that meet local safety standards.
For Investors and Strategic Acquirers: Roll-up economics work for industrial safety solution providers because regulatory compliance drives stable, recurring demand for certified apparel. Target specialized PPE manufacturers with strong intellectual property in advanced materials or unique distribution channels. The global standardization of safety frameworks, such as ISO 45001, serves as a key signal to watch for accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Innovation Partnerships | Accelerates development of sustainable and high-performance fabrics for specialized applications. |
| Supply Chain Digitization | Enhances transparency and traceability, crucial for sustainability reporting and counterfeit prevention. |
| D2C Channel Expansion | Allows direct engagement with independent contractors and specialized trades, bypassing intermediaries. |
| Emerging Market Entry | Captures new demand in regions with growing industrialization and safety standard adoption. |
| Smart PPE Development | Integrates sensor technology for real-time worker safety monitoring in hazardous environments. |
Research Approach
Multiple input streams — primary interviews with workwear manufacturers, industrial procurement managers, and safety officers, alongside secondary validation from regulatory documents — were reconciled. Textile material scientists also contributed insights. Secondary sources included OSHA publications, REACH compliance documents, ISO standards, and trade association reports. This approach ensured bottom-up and top-down triangulation.
This data-stream reconciliation informed the analytical framework for projecting market dynamics across the modeling period. Segmentation dimensions included product type, end-user industry, material composition, distribution channel, and regional regulatory environments. Compound Annual Growth Rates were derived from historical trends and forward-looking market drivers. Infrastructure spending forecasts and sustainability mandate implementation timelines served as key inputs.
Caveats apply where raw material price shocks or unforeseen regulatory shifts could materially shift the outlook for workwear demand. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Camouflage Suit Market