
 Industrial Curtains Market | 2026-2036
Industrial Curtains Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Curtains Market Analytics
North American vinyl fabric producers is decoupling from Asian supply chains for industrial-grade curtain materials. HIMSTRIP leverages its specialization in strip-door configurations to serve high-traffic manufacturing environments. Steel Guard Safety Corp. anchors its position through fire-retardant PVC formulations that meet stringent facility safety codes. Fabri-Tech Inc. differentiates via custom-sewn containment solutions for cleanroom and welding applications.
Industrial curtains are flexible barrier systems constructed from reinforced polyethylene, vinyl-coated polyester, or woven mesh, typically rated for specific tensile strength, flame resistance, and opacity levels to control dust, noise, temperature, or contaminants in commercial environments. Permanent installations dominate warehouse and manufacturing applications where structural integration with existing building systems provides long-term operational cost advantages. Portable and retractable configurations represent the fastest-expanding material segment, driven by just-in-time logistics operations requiring rapid facility reconfiguration across distribution networks.
OSHA mandates workplace hazard containment protocols that directly specify curtain performance standards for welding fume and chemical splash protection. The EPA's volatile organic compound regulations constrain solvent-based coating processes used in vinyl curtain manufacturing, pushing producers toward water-based alternatives. Stakeholders must monitor evolving fire-resistance certification requirements from NFPA and regional building code authorities, as compliance timelines will determine which material suppliers retain market access versus face product line obsolescence.
Market Dynamics
OSHA workplace safety standards are compressing installation timelines for fire-resistant curtain systems across US manufacturing facilities, forcing rapid specification upgrades that favor certified domestic suppliers over uncertified imports.
Growth Catalysts
- Warehouse Automation Retrofits:Distribution centers in the United States are deploying modular partition solutions to create flexible picking zones that adapt to seasonal volume swings.
- REACH Chemical Compliance:European manufacturers are reformulating vinyl coatings to eliminate restricted phthalates, opening certified product lines to cross-border facility contracts.
- Acoustic Curtain Mandates:German automotive plants are expanding noise containment installations to meet workplace exposure limits below 85 decibels.
Market Restraints
- Petrochemical Feedstock Volatility:PVC resin prices fluctuate with crude oil benchmarks, compressing margin stability for vinyl-coated polyester producers.
- Asian Supply Chain Concentration:Woven mesh substrates depend heavily on Zhejiang province mills, creating single-source vulnerability for North American fabricators.
- Welding Fume Standard Complexity:NFPA 701 fire testing protocols conflict with some OSHA ventilation requirements, forcing redundant certification spending.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for electronics assembly are creating first-mover demand for cleanroom curtain installations in Tamil Nadu and Karnataka.
- Water-Based Coating Transition:EPA volatile organic compound limits are pushing solvent-free formulation R&D, rewarding early patent filers with regulatory headroom.
- Retractable System Integration:Convergence of motorized track hardware with IoT sensors enables automated facility reconfiguration tied to production scheduling software.
Industry Challenges
- Fire-Resistance Certification Backlogs:NFPA and UL testing facility capacity constraints are extending product approval timelines to 14-18 months.
- Skilled Installation Labor Scarcity:Certified riggers for overhead track systems remain concentrated in legacy manufacturing belts, limiting rapid deployment in emerging logistics corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Curtains Market |
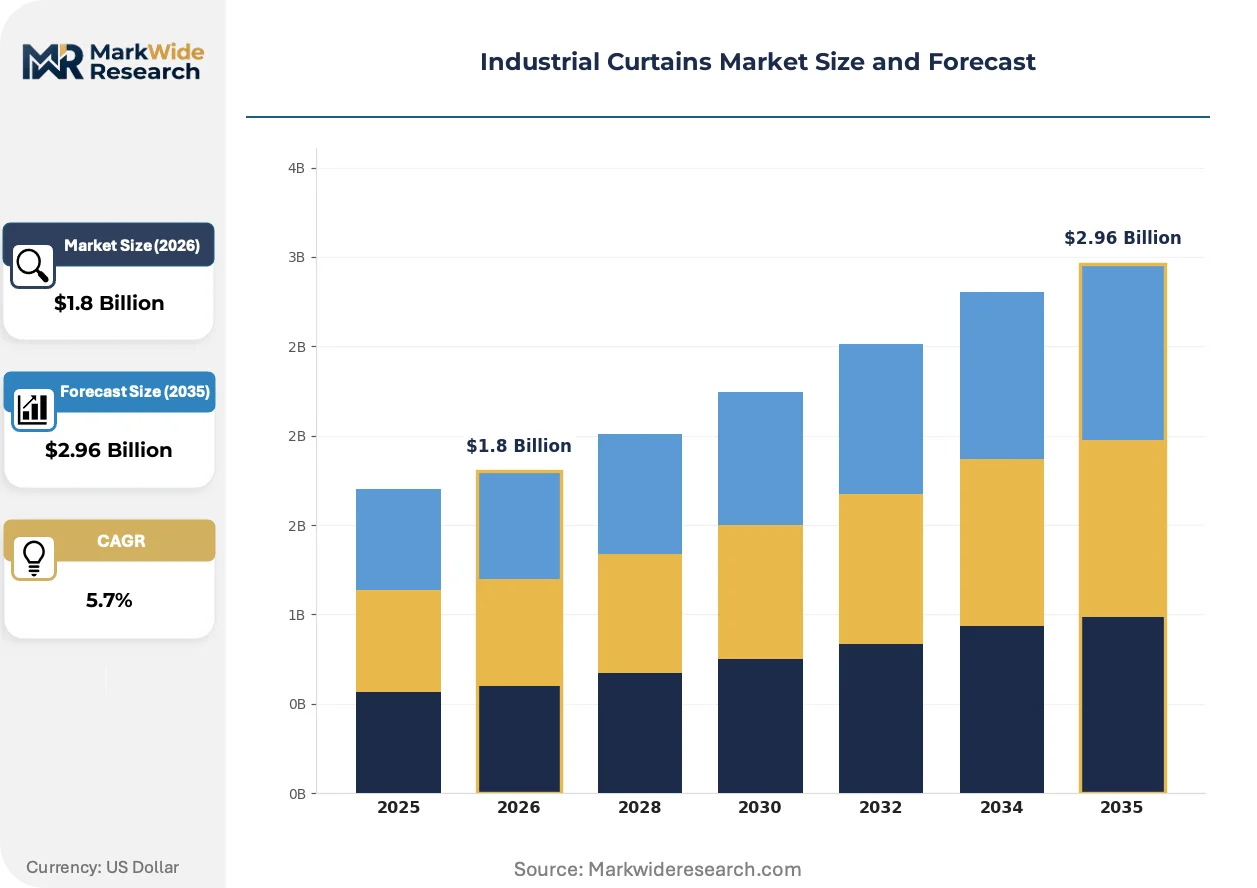
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Curtains, Portable Curtains, Retractable Curtains, Acoustic Curtains Material: Polyethylene, Vinyl, Mesh, Fabric Application: Warehouse, Manufacturing, Shipping, Distribution Installation Type: Wall-Mounted, Ceiling-Mounted, Free-Standing, Modular |
| Companies Covered | HIMSTRIP, Fabri-Tech Inc., Steel Guard Safety Corp., Deal Rite Inc., Plastic Fabric Solutions Inc., John Boyt Industrial Sewing Inc., Advanced Fabric Technologies, Harken Canvas, Emco Industrial Plastics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Curtains Market Evolving Landscape
Material science advances and regulatory chemistry mandates are restructuring competitive advantage around certified formulation expertise rather than basic fabrication capacity.
Smart curtain systems incorporating RFID-tagged fabric panels and automated track sensors are absorbing facility management budgets previously allocated to static barrier installations. Third-party logistics operators in the Netherlands and Belgium are piloting these configurations for real-time zone reconfiguration. The technology is absorbing market share from conventional manual systems by reducing labor reconfiguration hours.
EPA volatile organic compound regulations are constraining solvent-based coating processes across vinyl curtain manufacturing, forcing capital redeployment toward water-based alternatives. Producers in Ohio and Texas are retrofitting production lines to maintain facility access under tightening emissions budgets. Welding protection applications face the steepest compliance cost escalation due to thicker coating requirements.
Direct procurement relationships between end-use facility managers and specialized fabricators are displacing distributor intermediaries for large-scale containment projects. Automotive OEMs in Stuttgart and Wolfsburg now specify custom acoustic curtain geometries through engineering-to-order contracts. This pattern is most pronounced in Germany, where just-in-sequence production demands rapid specification iteration unavailable through catalog distributors.
Industrial Curtains Market Segmentation
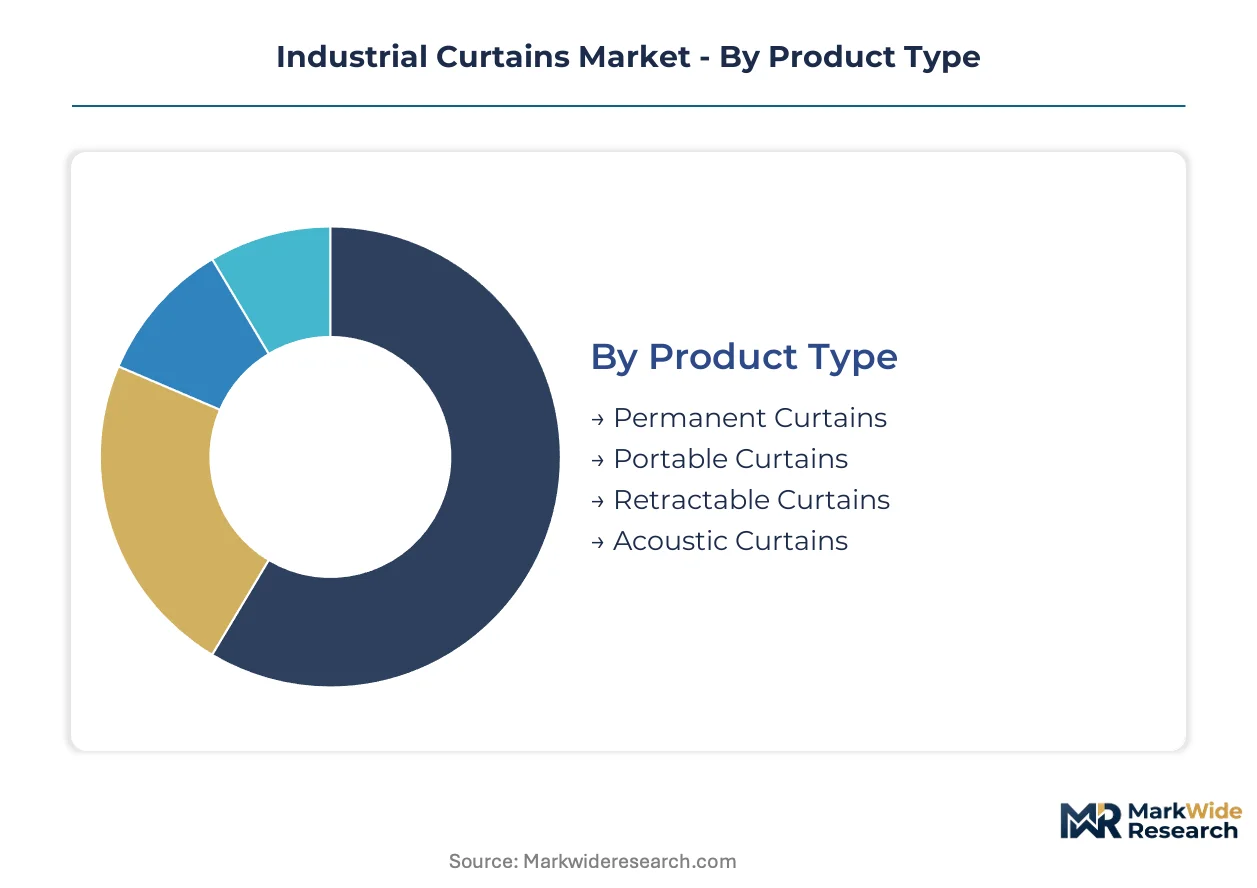
Industrial curtain procurement decisions hinge on facility lifecycle planning, with capital allocation shifting between permanent infrastructure and flexible reconfiguration systems. Material certification requirements and installation complexity create divergent margin profiles across segment boundaries.
Product Type:
Permanent curtain installations demand the heaviest upfront capital commitment, requiring structural integration with building systems and certified rigging infrastructure.
- Permanent Curtains:Reinforced vinyl or fabric panels anchored to fixed track systems, rated for continuous load-bearing and fire-resistance compliance. Automotive assembly plants in Germany specify these for long-term weld-booth containment, driven by workplace exposure mandates below 85 decibels.
- Retractable Curtains:Motorized track configurations enabling automated facility reconfiguration through IoT-linked production scheduling software. Third-party logistics operators in Belgium and the Netherlands pilot these systems for real-time zone adaptation, absorbing budgets previously allocated to static barriers.
- Portable Curtains:Lightweight frame-mounted barriers for temporary containment during facility maintenance or seasonal volume peaks.
- Acoustic Curtains:Multi-layer composite panels engineered for noise attenuation in high-decibel manufacturing environments.
Most installed capacity flows through Permanent Curtains. Expansion is steepest in Retractable Curtains.
Material:
Cost tiering separates commodity-grade polyethylene from certified vinyl formulations required for regulated environments.
- Vinyl:PVC-coated polyester substrates delivering flame resistance per NFPA 701 and OSHA welding fume containment standards. Steel Guard Safety Corp. anchors its market position through fire-retardant formulations meeting stringent facility safety codes, with EPA volatile organic compound regulations now forcing water-based coating transitions.
- Polyethylene:Reinforced polyethylene sheeting for dust and debris containment in non-regulated warehouse zones. Distribution centers in the United States deploy these for cost-effective seasonal partition creation during peak fulfillment periods.
- Mesh:Woven substrates for ventilation-permeable barriers in temperature-controlled environments.
- Fabric:Custom-sewn textile solutions for cleanroom and specialized containment applications.
Certified vinyl commands premium pricing in regulated manufacturing. Polyethylene volumes dominate warehouse and logistics procurement.
Application:
End-use concentration determines specification complexity, with manufacturing applications demanding multi-certification compliance absent in general warehousing.
- Manufacturing:Integrated barrier systems for weld-fume containment, chemical splash protection, and acoustic compliance. OSHA mandates workplace hazard containment protocols that directly specify curtain performance standards, compressing installation timelines for fire-resistant systems.
- Warehouse:Modular partition solutions for zone creation in automated distribution networks. United States warehouse automation retrofits drive demand for rapid-reconfiguration systems adapting to seasonal volume swings.
- Shipping:Weather-resistant barriers for dock door containment and loading zone climate control.
- Distribution:Flexible sorting zone divisions for high-throughput fulfillment operations.
Manufacturing applications absorb the highest specification investment. Distribution center deployments are gaining share fastest through automation retrofit cycles.
Installation Type:
Customer technical capability and facility lease structures drive selection between permanent mounting and reconfigurable systems.
- Wall-Mounted:Fixed-track installations integrated with building structural elements for maximum stability. These configurations dominate automotive manufacturing in Stuttgart and Wolfsburg, where just-in-sequence production demands engineering-to-order specification iteration.
- Modular:Interconnecting panel systems enabling rapid assembly without specialized rigging. Skilled installation labor scarcity in emerging logistics corridors favors these systems for rapid deployment.
- Ceiling-Mounted:Overhead track configurations maximizing floor space utilization in dense production environments.
- Free-Standing:Self-supporting frame systems for leased facilities or temporary containment needs.
Wall-Mounted systems retain the largest installed base. Modular configurations are climbing the fastest as facility reconfiguration frequency accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns in industrial curtain manufacturing increasingly track divergent regulatory compliance costs, with European REACH chemical mandates and U.S. EPA emissions standards creating arbitrage opportunities for certified producers in lower-cost jurisdictions.
United States
Warehouse automation retrofits across distribution networks drive modular partition procurement, with seasonal volume swings requiring rapid facility reconfiguration. OSHA workplace safety standards compress installation timelines for fire-resistant systems, favoring domestic suppliers with certified product lines. The Midwest manufacturing belt and Southeast logistics corridors concentrate demand for overhead track installations.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg specify custom acoustic curtain geometries through engineering-to-order contracts for weld-booth containment. Workplace exposure mandates below 85 decibels accelerate noise containment investments. KBA vehicle production standards indirectly shape facility safety specifications across supplier parks.
China
Zhejiang province mills supply woven mesh substrates that North American fabricators depend on, creating single-source vulnerability. MIIT industrial upgrading programs push domestic manufacturers toward higher-value coated fabric production. Yangtze River Delta clusters concentrate vinyl coating capacity for export markets.
India
PLI scheme incentives for electronics assembly in Tamil Nadu and Karnataka generate first-mover demand for cleanroom curtain installations. Central Electricity Authority building codes increasingly specify fire-resistant partitioning for manufacturing facilities. Maharashtra and Gujarat industrial zones anchor domestic fabrication capacity expansion.
Netherlands
Third-party logistics operators in Rotterdam and Venlo pilot smart curtain systems with RFID-tagged panels and automated track sensors for real-time zone reconfiguration. EU Green Deal emissions budgets constrain solvent-based coating processes, pushing producers toward water-based alternatives. Belgian and Dutch distribution hubs absorb technology budgets previously allocated to static barriers.
Industrial Curtains Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue retractable system integration and IoT-enabled facility management software. The vendor base distributes across three maturity levels: legacy fabricators with certified formulation expertise, mid-scale specialists in strip-door or acoustic configurations, and technology-forward entrants converging hardware with sensor platforms. Competitive positioning hinges on fire-resistance certification holdings and installation labor network density. Dominant moves include geographic expansion into India manufacturing corridors and portfolio diversification toward water-based coating formulations.
Within the specialty-tier segment, HIMSTRIP exemplifies strip-door configuration expertise for high-traffic manufacturing environments, while Steel Guard Safety Corp. anchors fire-retardant PVC formulation capabilities. Fabri-Tech Inc. occupies a position in custom-sewn containment solutions. These three fabricators represent divergent specialization archetypes: modular traffic management, certified safety compliance, and engineered-to-order cleanroom applications.
| Leading Market Players |
|---|
| HIMSTRIP |
| Fabri-Tech Inc. |
| Steel Guard Safety Corp. |
| Deal Rite Inc. |
| Plastic Fabric Solutions Inc. |
| John Boyt Industrial Sewing Inc. |
| Advanced Fabric Technologies |
| Harken Canvas |
| Emco Industrial Plastics Inc. |
| Others |
Value Network & Pricing Analysis
Water-based coating transitions across vinyl curtain manufacturing are simultaneously elevating production costs and redistributing supplier power toward certified domestic fabricators with EPA-compliant facilities. This technical shift compresses margins for solvent-dependent producers while creating pricing premiums for early reformulators in Ohio and Texas.
Pricing Analysis
Distributor markups of 25-40 percent on standard-grade polyethylene curtains collapse to sub-15 percent margins for direct-to-OEM engineering contracts in automotive and cleanroom applications. Three-tier pricing structure across premium certified vinyl, standard fire-resistant formulations, and economy-grade polyethylene segments the market by compliance burden. Cost compression in the mid-tier vinyl segment is intensifying because REACH phthalate restrictions and EPA volatile organic compound limits force dual-certification spending. Warehouse distribution centers exhibit highest price sensitivity, while German automotive OEMs accept substantial premiums for custom acoustic geometries.
Supply Chain Analysis
Domestic-content mandates under the US Buy American Act and India's PLI scheme incentives are reshaping sourcing patterns for certified curtain fabricators serving government and electronics assembly contracts. Raw material flows draw from Zhejiang province for woven mesh substrates, Texas and Ohio for vinyl coating capacity, and Germany for precision track hardware. Single-source vulnerability concentrates in Zhejiang's substrate mills, where any disruption cascades through North American fabrication. Distribution runs through specialized industrial fabric distributors for small-to-mid projects, with direct procurement displacing intermediaries for large-scale containment installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial curtain procurement has shifted toward late-cycle quality specifications, with facility managers prioritizing multi-certification compliance over first-cost minimization. This demand pivot rewards producers with established NFPA, OSHA, and REACH certification portfolios.
For Market Incumbents: Deepen backward integration into vinyl coating capacity to capture margins currently flowing to third-party compounders, while accelerating water-based formulation patents ahead of EPA enforcement timelines. Consolidate installation labor networks through certified rigger apprenticeship programs in Southeast logistics corridors, addressing the scarcity that delays deployment in emerging distribution hubs. Threat substitution from smart curtain systems with IoT integration demands preemptive hardware-software bundling investments. For New Entrants and Emerging Players: E-commerce procurement platforms for standardized polyethylene warehouse partitions offer low-friction market entry with minimal certification overhead. Target India's Tamil Nadu and Karnataka electronics corridors for cleanroom curtain installations, where PLI scheme incentives outpace local fabrication capacity. Direct-to-facility digital sales channels bypass entrenched distributor relationships that lock out new suppliers in mature North American markets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists with certified formulation expertise but underdeveloped IoT integration capabilities, representing asymmetric upside from technology convergence. Long-term viability hinges on regulatory chemistry compliance rather than basic fabrication scale. Monitor NFPA and UL testing facility capacity expansion as the inflection signal—approval timeline compression from 14-18 months toward 8-12 months would unlock working capital efficiency and accelerate market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Transition | EPA volatile organic compound compliance secures facility access for Ohio and Texas producers. |
| Smart Curtain System Integration | RFID-tagged panels with IoT sensors absorb budgets from static barrier installations in Dutch logistics hubs. |
| India Manufacturing Expansion | PLI scheme electronics assembly incentives generate first-mover cleanroom demand in Tamil Nadu. |
| Installation Labor Network Buildout | Certified rigger concentration in legacy belts limits rapid deployment in emerging Southeast corridors. |
| Direct Procurement Channel Development | Engineering-to-order contracts with Stuttgart automotive OEMs displace catalog distributors. |
Research Methodology
Coverage spans the United States, Germany, China, India, and the Netherlands, with primary inputs from each market cluster combining facility manager interviews, vinyl compounder technical assessments, and distribution channel partner consultations. Secondary validation draws from OSHA regulatory filings, EPA emissions compliance databases, NFPA certification registries, and customs trade data for woven mesh substrate flows. Bottom-up demand modeling from end-use facility capex plans triangulates against top-down supply-side capacity assessments across coating and fabrication operations.
Rate-of-change decomposition separates volume growth from price-mix effects across permanent, retractable, and portable product configurations, with material-grade tiering and installation complexity as cross-cutting dimensions. CAGRs emerge from segment-level growth rate aggregation weighted by base-year revenue shares. Forecast inputs incorporate REACH chemical restriction timelines, NFPA 701 testing protocol evolution, and warehouse automation retrofit cycle phasing across major distribution networks.
The model assumes a particular technology adoption path for water-based coating transitions; alternative pathways involving solvent-recapture systems or bio-based polymer substitutes would alter the outlook for capital deployment and supplier competitive position. Forecasts reflect assumptions regarding regulatory enforcement intensity, petrochemical feedstock price stability, and testing facility capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Compression Garments Market