
 Cut Resistant Fabrics Market | 2026-2036
Cut Resistant Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Cut Resistant Fabrics Market Analysis
High-performance fiber blending is fragmenting the traditional single-material supply model for protective textiles. DuPont de Nemours, Inc. leverages its Kevlar polymer heritage to anchor premium positioning in aramid-based protective layers. W. L. Gore & Associates competes through membrane-lamination expertise that extends cut resistance into breathable, waterproof garment systems. TenCate Protective Fabrics dominates military and first-responder channels with vertically controlled weaving and finishing operations.
Cut resistant fabrics are engineered textiles constructed from high-tenacity synthetic fibers such as para-aramids or ultra-high-molecular-weight polyethylene, typically achieving ANSI/ISEA Level A4-A9 cut protection ratings through controlled yarn geometry and fabric density. These materials serve primarily to prevent laceration injuries in environments with sharp tools, abrasive surfaces, or mechanical hazards. Kevlar-based constructions occupy the mature core of the market, while Dyneema and Spectra segments capture expanding share in lightweight, high-dexterity applications where reduced garment weight improves worker compliance. Coating and lamination technologies command margin concentration by transforming base fabrics into multi-hazard protective systems that command price premiums over commodity woven alternatives.
OSHA mandates in the United States, CE marking requirements under EU PPE Regulation, and ISO 13997 cut resistance testing protocols collectively define minimum performance thresholds that filter substandard suppliers from commercial procurement channels. China's GB standards and SAMR enforcement are tightening domestic quality benchmarks, pressuring regional mills to upgrade fiber selection and process control. Stakeholders must monitor evolving national implementation timelines for revised blade-cut test methodologies that could reclassify existing product portfolios and trigger replacement demand cycles.
Market Dynamics
High-tenacity fiber blending is fragmenting the traditional single-material supply model for protective textiles, forcing incumbent weavers to reconfigure yarn sourcing strategies and certification pathways.
Growth Catalysts
- OSHA enforcement tightening:Stricter personal protective equipment standards in the United States elevate baseline performance requirements and trigger replacement cycles for aging garment inventories.
- Industrial manufacturing expansion:Automotive and metal fabrication facilities are scaling workforce protective programs to reduce laceration injury rates and workers compensation exposure.
- China domestic fiber scaling:Local textile producers are ramping high-tenacity para-aramid and UHMWPE output, reducing import dependency while building export capacity.
Market Restraints
- Petrochemical input volatility:Para-aramid and UHMWPE production remains tethered to propylene and ethylene derivative pricing, compressing margin predictability for fabric converters.
- Concentrated upstream supply:Polymer-grade fiber production clusters in a handful of chemical complexes, creating geographic chokepoints that amplify disruption risk.
- Technical dexterity ceiling:Current Level A9-rated constructions still sacrifice tactile sensitivity, limiting adoption in precision assembly tasks where cut protection competes with productivity.
Strategic Opportunities
- India industrial formalization:Factory safety mandates under BIS and state labor inspectorates are creating first-time protective garment demand in metalworking and glass processing clusters.
- Multi-hazard convergence:Lamination of cut-resistant base fabrics with thermal barrier and arc-flash layers opens premium positioning in utilities and welding applications.
- Direct-to-employer digital channels:Specialized industrial distributors are building configuration platforms that bypass traditional uniform rental intermediaries, capturing margin and data.
Industry Challenges
- ANSI/ISEA test method transitions:Laboratories and manufacturers face compressed recertification timelines as blade-cut testing protocols evolve, straining quality assurance bandwidth.
- Specialized weaving technician scarcity:High-density warp and weft configurations for cut-resistant grades require skills that textile training programs have deprioritized amid apparel offshoring.
- Legacy finishing chemistry compliance:Water-repellent and flame-retardant treatments must reformulate to meet evolving PFAS restrictions and state-level chemical disclosure laws.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cut Resistant Fabrics Market |
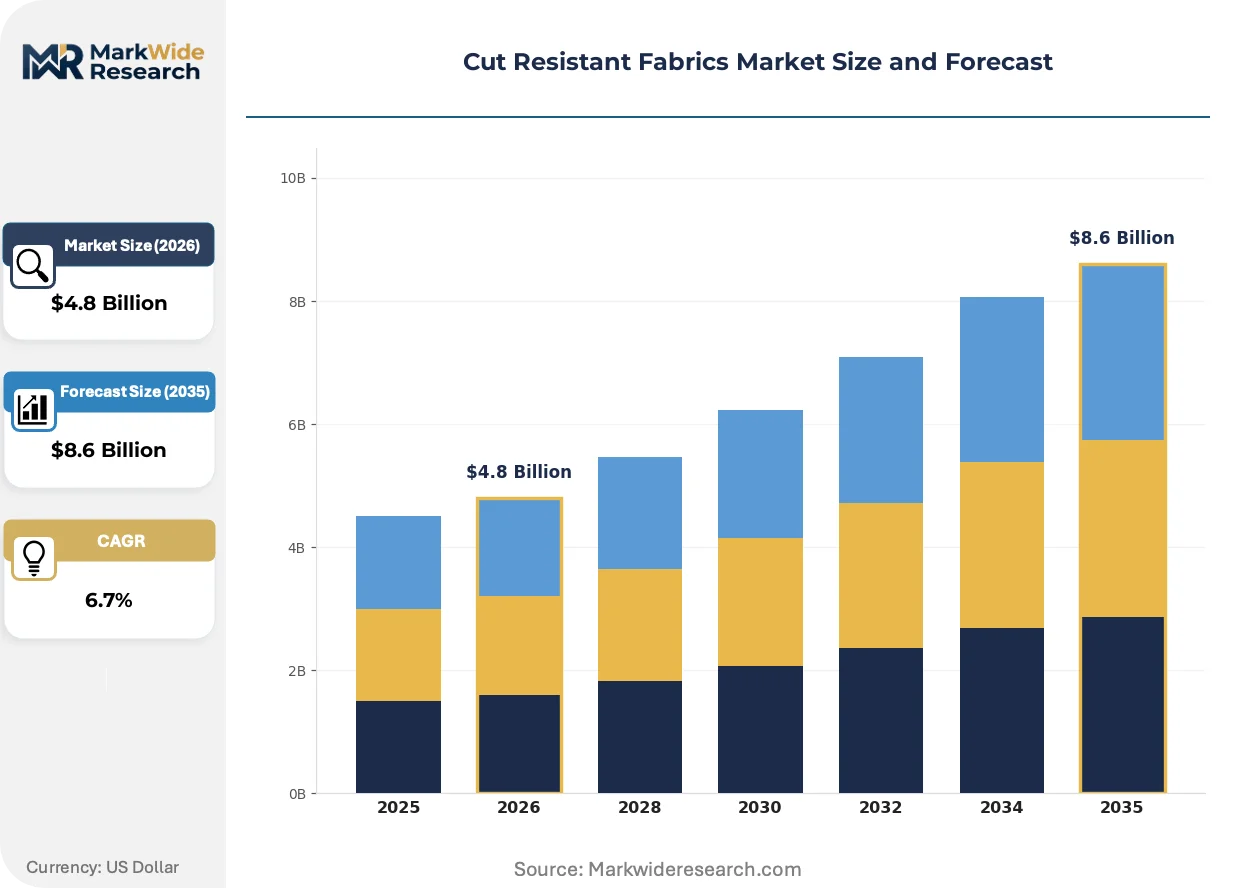
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Kevlar, Dyneema, Spectra, Steel Fiber Application: Construction, Manufacturing, Healthcare, Automotive End User: Industrial Workers, Medical Personnel, Home Users, Firefighters Technology: Weaving, Knitting, Coating, Lamination |
| Companies Covered | TenCate Protective Fabrics, Lakeland Inc, DuPont de Nemours, Inc., Nam Liong Global Corporation, Glen Raven Inc., 3M, Milliken & Company, Cut-Tex, W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cut Resistant Fabrics Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are compressing product development cycles while opening new performance tiers that redefine competitive differentiation.
Hybrid fiber constructions combining para-aramid with ultra-high-molecular-weight polyethylene are migrating from niche tactical applications into mainstream industrial workwear. Safety managers in automotive assembly and aerospace maintenance are specifying these blends to achieve ANSI Level A5-A7 ratings at 30% lower basis weight than traditional Kevlar-dominant fabrics. The migration from single-polymer heritage products toward engineered multi-fiber systems is compressing pricing premiums for established aramid suppliers while rewarding converters with lamination and coating capabilities.
EU PPE Regulation harmonization with ISO 13997 cut resistance testing is forcing recertification of legacy product portfolios across European distribution channels. Manufacturers serving Germany, France, and Benelux industrial markets must resubmit technical documentation under revised blade-cut methodologies, creating temporary supply friction. The segment most affected is mid-tier woven fabrics previously certified under withdrawn EN 388:2003 protocols, which now face reclassification or delisting.
Industrial buyers are consolidating protective garment procurement through specialized safety distributors that bundle cut-resistant apparel with site-level hazard assessment services. This displaces fragmented purchasing through general industrial suppliers and uniform rental networks. The shift is most visible in North American manufacturing conglomerates with multi-site operations, where centralized safety committees demand SKU rationalization and consolidated reporting on injury reduction metrics.
Cut Resistant Fabrics Market Segmentation
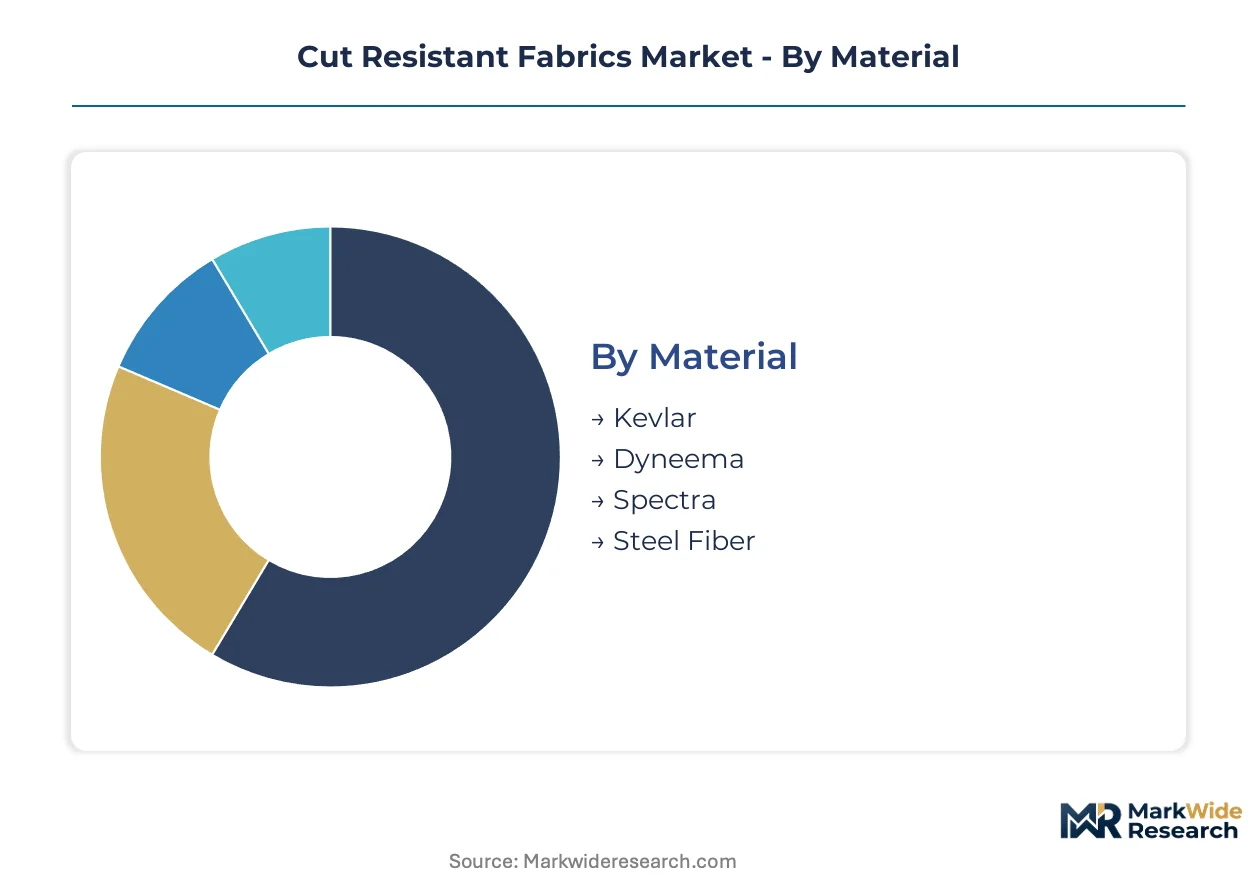
Segmentation in cut resistant fabrics reveals how fiber chemistry, fabrication method, and hazard exposure combine to determine procurement priorities. Safety managers weight ANSI cut levels against garment durability and worker compliance, creating distinct demand profiles across material and application categories.
Material:
Replacement cycles vary dramatically by fiber chemistry—para-aramid garments depreciate through UV and moisture degradation faster than UHMWPE alternatives, while steel fiber composites outlast both but sacrifice flexibility.
- Kevlar:Para-aramid polymer chains deliver thermal stability and ANSI Level A4-A6 protection through spun yarn constructions. Automotive assembly plants in Michigan and South Carolina specify Kevlar-dominant sleeves for powertrain operations where moderate cut resistance must coexist with heat exposure from engine components.
- Dyneema:Ultra-high-molecular-weight polyethylene achieves equivalent cut ratings at 40% lower basis weight than para-aramid through gel-spinning that aligns molecular chains. Food processing facilities in the Netherlands and Germany are migrating to Dyneema gloves to reduce hand fatigue during eight-hour shifts while maintaining EN 388 compliance.
- Spectra:Honeywell's UHMWPE variant targets tactical and marine applications requiring flotation compatibility alongside cut protection.
- Steel Fiber:Stainless steel filaments woven with polyester cores deliver maximum ANSI Level A9 ratings for glass handling and metal recycling where laceration severity demands absolute barrier performance.
Kevlar anchors the volume base while Dyneema gains share at the steepest rate.
Application:
Cost tier stratification separates premium multi-hazard specifications from commodity single-risk garments across industrial verticals.
- Construction:Heavy-gauge woven fabrics with cement and abrasion resistance dominate scaffolding and masonry operations. OSHA recordable laceration rates in Texas and Florida commercial building sites are pushing general contractors toward Level A6-A7 specifications for framing crews.
- Manufacturing:Metal fabrication and stamping facilities require the highest cut ratings combined with oil repellency. Tier-1 automotive suppliers in Ontario and Bavaria mandate coated Kevlar-Dyneema hybrids for press operators handling sharp-edged sheet steel.
- Healthcare:Lightweight knit gloves prevent scalpel and instrument injuries in surgical and laboratory settings.
- Automotive:Battery assembly for electric vehicles introduces new cut-and-puncture combinations from cell tabbing and busbar installation.
Manufacturing commands the largest procurement spend while automotive applications expand most quickly.
End User:
Customer type determines whether procurement flows through centralized safety departments or fragmented individual purchasing.
- Industrial Workers:Manufacturing and logistics employers with formal safety programs drive volume through contracted uniform services. Amazon fulfillment centers and FedEx Ground hubs in Indiana and Tennessee have standardized Level A5 glove programs across sortation and package handling operations.
- Medical Personnel:Hospitals and outpatient clinics purchase cut-resistant undergloves for surgical teams. The Cleveland Clinic and Mayo Clinic systems specify sterile Dyneema blends for orthopedic and cardiovascular procedures where suture needle sticks pose infection risk.
- Home Users:DIY enthusiasts and culinary hobbyists represent emerging retail demand through hardware and kitchen specialty channels.
- Firefighters:Turnout gear manufacturers integrate cut-resistant layers in wrist and neck protection zones.
Industrial Workers generate the dominant revenue stream while Medical Personnel adoption climbs fastest.
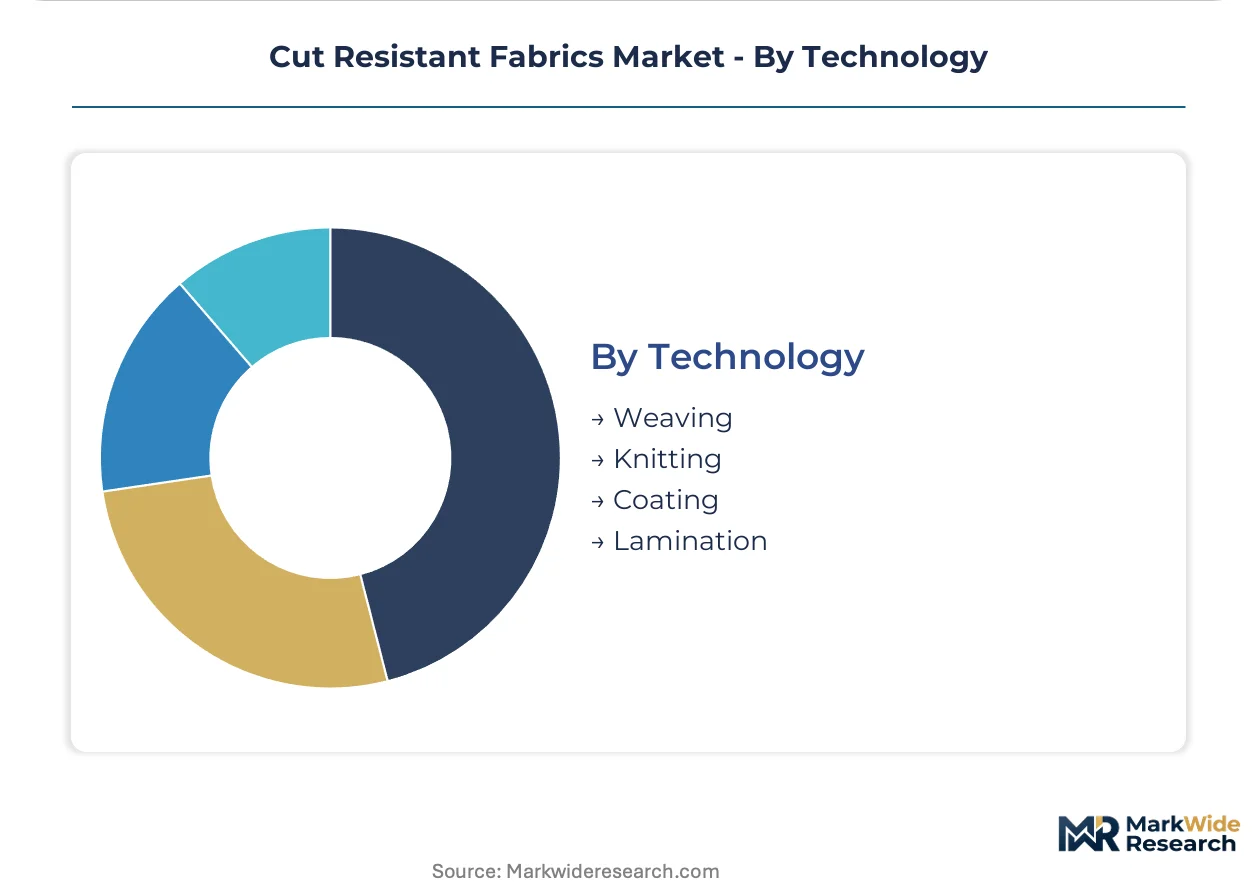
Technology:
Supply concentration in high-density weaving and precision coating creates margin capture opportunities for converters with captive finishing capabilities.
- Weaving:Plain and twill constructions from high-tenacity warp and weft yarns remain the volume foundation. Mills in North Carolina and South Carolina operate shuttle and projectile looms optimized for aramid and UHMWPE tension requirements.
- Knitting:Seamless glove machines produce form-fitting cut protection with engineered stretch zones. Shima Seiki and Steiger equipment in Chinese knitting clusters near Ningbo and Dongguan dominate global glove shell output.
- Coating:Nitrile, polyurethane, and silicone surface treatments add grip and chemical resistance to base fabrics.
- Lamination:Membrane and thermal barrier bonding creates multi-hazard systems for extreme environments.
Weaving retains the installed capacity base while Lamination delivers the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports high-tenacity para-aramid and UHMWPE fibers to European and North American garment converters, establishing itself as the dominant upstream supply corridor for cut-resistant textile manufacturing.
United States
Automotive assembly plants in Michigan and South Carolina drive demand for Kevlar-dominant protective sleeves. OSHA enforcement of stricter PPE standards elevates baseline performance requirements and triggers replacement cycles for aging garment inventories. The Carolinas textile belt hosts weaving operations optimized for aramid tension requirements.
China
Domestic textile producers scale high-tenacity fiber output for both local consumption and export markets. GB standards and SAMR enforcement tighten domestic quality benchmarks, pressuring regional mills to upgrade fiber selection. The Yangtze River Delta clusters near Ningbo and Dongguan dominate global glove shell output on Shima Seiki and Steiger equipment.
Germany
Food processing facilities in Bavaria migrate to Dyneema gloves to reduce hand fatigue during extended shifts while maintaining EN 388 compliance. EU PPE Regulation harmonization with ISO 13997 cut resistance testing forces recertification of legacy product portfolios. The Rhine-Ruhr industrial corridor concentrates metal fabrication demand for coated Kevlar-Dyneema hybrids.
India
Factory safety mandates under BIS and state labor inspectorates create first-time protective garment demand in metalworking and glass processing clusters. Maharashtra and Gujarat industrial zones formalize safety programs as manufacturing employment expands. The Delhi-NCR region sees rising procurement from logistics employers with multi-site operations.
Netherlands
Distribution hubs in Rotterdam and Eindhoven serve as consolidation points for European industrial buyers seeking SKU rationalization. CE marking requirements filter substandard suppliers from commercial procurement channels. The Randstad logistics network enables specialized safety distributors to bundle cut-resistant apparel with site-level hazard assessment services.
Cut Resistant Fabrics Market Vendor Landscape
On the supply side, the industry is structured around three distinct capability tiers: polymer-grade fiber producers, specialized weaving and knitting converters, and integrated garment system suppliers. Chemical conglomerates with aramid or UHMWPE heritage anchor the upstream tier. Mid-tier fabricators compete on lamination expertise and certification bandwidth. Downstream, turnout gear and industrial workwear brands capture end-user relationships. Dominant competitive moves include backward integration into captive fiber supply and geographic expansion through distributor acquisition.
Within the integrated system supplier tier, TenCate Protective Fabrics and W. L. Gore & Associates occupy positions defined by vertically controlled manufacturing and membrane-lamination expertise respectively. DuPont de Nemours, Inc. anchors the polymer heritage archetype through its Kevlar brand equity. These three companies exemplify how upstream material science capabilities translate into premium positioning across military, first-responder, and industrial channels.
| Leading Market Players |
|---|
| TenCate Protective Fabrics |
| Lakeland Inc |
| DuPont de Nemours, Inc. |
| Nam Liong Global Corporation |
| Glen Raven Inc. |
| 3M |
| Milliken & Company |
| Cut-Tex |
| W. L. Gore & Associates |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta knitting clusters near Ningbo and Dongguan anchor global glove shell capacity on Shima Seiki and Steiger equipment, concentrating downstream pricing power in converters with captive finishing operations while squeezing margin capture for pure-play weavers lacking lamination capabilities.
Pricing Analysis
Next-generation Dyneema-Dyneema blends command 30-40% premiums over legacy Kevlar-dominant constructions, while prior-generation steel fiber composites trade at commodity levels. Three-tier pricing structure across premium, standard, and economy levels separates ANSI Level A9 multi-hazard laminates from Level A5-A7 woven base fabrics and uncoated knit gloves. Cost compression in the standard tier is intensifying because Chinese domestic fiber scaling has reduced import dependency for para-aramid and UHMWPE feedstock. Industrial workers in formal safety programs show lowest price sensitivity, while home users and informal construction crews drive volume at economy tiers.
Supply Chain Analysis
Propylene and ethylene derivative feedstock for para-aramid and UHMWPE polymerization centers on chemical complexes in the United States, China, and the Netherlands, creating geographic chokepoints that amplify disruption risk. Raw material sourcing draws from petrochemical crackers, gel-spinning facilities, and stainless steel filament producers. Single-source vulnerability concentrates in polymer-grade fiber production where DuPont de Nemours and Honeywell anchor aramid and Spectra supply respectively. Distribution runs through specialized industrial safety distributors that bundle hazard assessment services with garment procurement, displacing fragmented uniform rental intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as specialized safety distributors build configuration platforms that bypass traditional intermediaries, creating interoperability standards between hazard assessment software and procurement systems that reward converters with data integration capabilities.
For Market Incumbents: Harden certification bandwidth against ANSI/ISEA test method transitions by investing in captive laboratory capacity and pre-positioning technical documentation for recertification waves. Deepen upstream control over high-tenacity fiber supply through long-term offtake agreements with Chinese domestic producers scaling para-aramid and UHMWPE output. Channel control through distributor acquisition protects margin position as digital platforms displace traditional rental networks.
For New Entrants and Emerging Players: Build out lamination and coating capabilities to capture premium positioning in multi-hazard convergence applications where thermal barrier and arc-flash layers command price premiums over commodity woven alternatives. White-space targets cluster in India industrial formalization under BIS mandates and electric vehicle battery assembly where cut-and-puncture combinations from cell tabbing create new specification demand. Go-to-market angle through direct-to-employer digital channels bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from chemical conglomerates with underutilized aramid or UHMWPE heritage assets seeking to monetize non-core fiber production. Long-term viability over a five-to-ten year window rests on converters with vertically controlled weaving and finishing operations that can absorb test method transitions and PFAS chemistry reformulation costs. Signal to monitor is OSHA enforcement intensity in Michigan and South Carolina automotive corridors, where replacement cycle acceleration would trigger inventory restocking demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive supply of para-aramid or UHMWPE insulates margin from petrochemical input volatility. |
| Multi-Hazard Lamination Capability Expansion | Thermal barrier and arc-flash layering opens premium positioning in utilities and welding applications. |
| Digital Platform Development | Configuration tools that bundle hazard assessment with procurement capture margin and end-user data. |
| Certification Bandwidth Investment | In-house testing laboratories compress recertification timelines for evolving blade-cut protocols. |
| Geographic Expansion through Distributor Acquisition | Control over specialized industrial safety channels defends against platform disintermediation. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary engagement with plant safety managers at Tier-1 automotive suppliers, procurement leads at specialized industrial distributors, technical R&D directors at weaving and knitting converters, and regulatory affairs specialists at fiber producers; and secondary validation through customs and trade data, OSHA enforcement records, SEC 10-K filings of public chemical conglomerates, and technical documentation from ANSI/ISEA and ISO standards bodies. Bottom-up triangulation across fiber production volumes, fabric conversion capacity, and end-user procurement patterns was cross-checked against top-down market sizing from petrochemical derivative demand models.
Forecast inputs considered material segmentation by fiber chemistry, fabrication method by weaving versus knitting versus lamination, application vertical across manufacturing and automotive and construction, and end-user type from industrial workers through medical personnel. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating industrial employment growth in formal safety programs, regulatory enforcement intensity by geography, and substitution dynamics between Kevlar and Dyneema constructions. Industry-specific inputs included automotive assembly plant expansion in battery electric vehicle manufacturing and BIS implementation timelines in Indian industrial zones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic fiber producers scaling export capacity or by platform-native distributors acquiring converter assets would shift outcomes. Cross-checking against OSHA recordable injury rate trends and workers compensation cost data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market