
 Global Professional Coffee Machine Market | 2026-2036
Global Professional Coffee Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Professional Coffee Machine Market Outlook
Market Dynamics
Capital-intensity divergence between integrated manufacturers and assembly-focused competitors is rotating competitive advantage toward firms with in-house boiler and brewing unit production. WMF Group leverages its German engineering base to sustain premium positioning in fully automatic systems for offices and hotels. La Marzocco anchors artisanal café demand through hand-built espresso machines manufactured in Florence. Jura Elektroapparate AG differentiates via proprietary pulse extraction process technology across European and Asian markets.
Product and Technology Landscape
Professional coffee machines encompass commercial-grade equipment engineered for continuous brewing cycles, typically operating at nine-bar extraction pressure and integrating precision temperature stability systems for consistent beverage quality in high-volume settings. Espresso machines occupy the dominant revenue position due to café and restaurant reliance on pressure-based extraction, while super-automatic technology commands expanding share as offices and hotels prioritize labor reduction and drink consistency without trained barista staff. Drip coffee makers retain mature demand in North American institutional settings where batch brewing aligns with consumption patterns.
Regulatory Environment
The EU Ecodesign Directive and associated energy labeling frameworks mandate standby power limits and efficiency benchmarks for commercial catering equipment across member states, directly influencing product development timelines and compliance costs for manufacturers serving European accounts. The US Department of Energy maintains parallel efficiency standards through ENERGY STAR certification programs that shape procurement criteria for American office and hospitality buyers. Stakeholders must monitor evolving material restrictions under REACH and RoHS frameworks, as boiler components and electronic controls face intensifying substance compliance requirements that will determine market access trajectories.
Market Dynamics
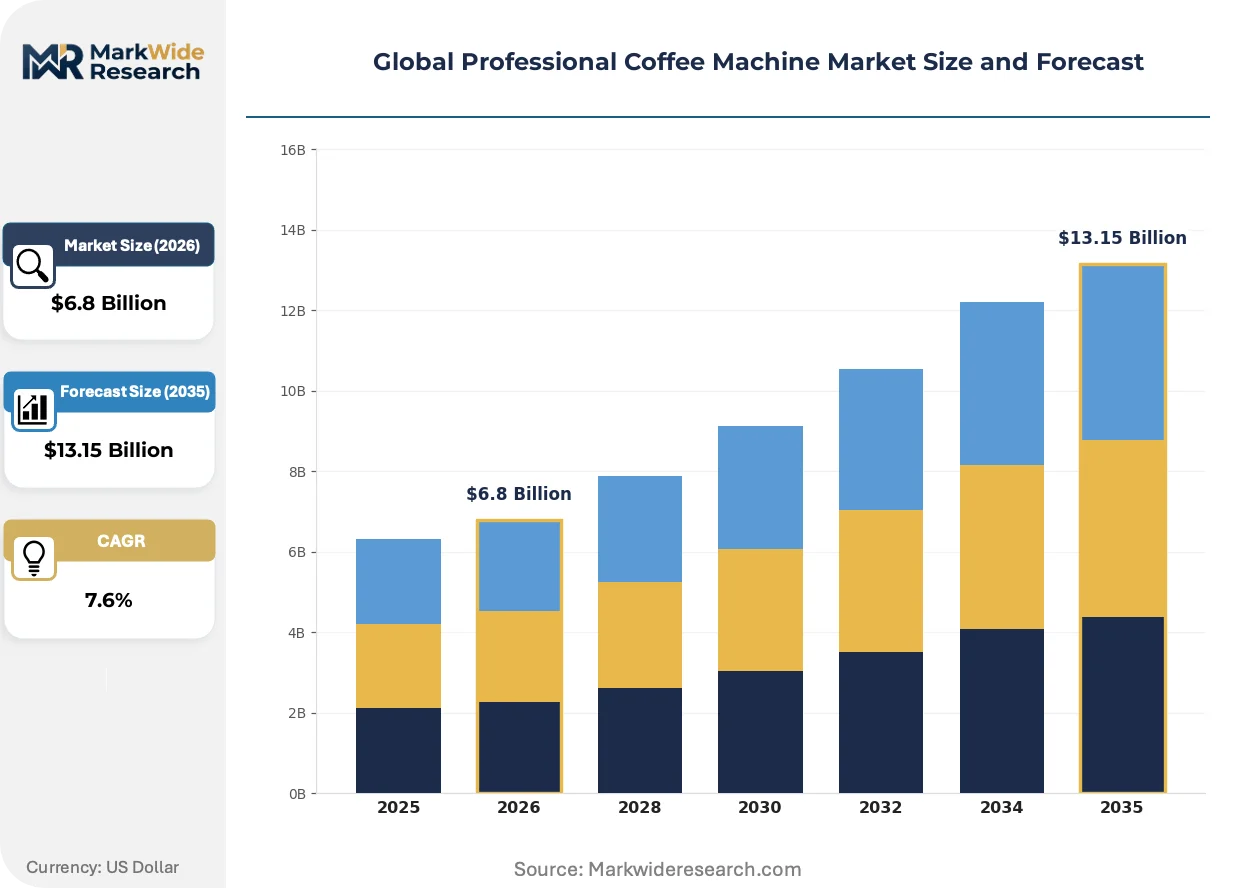
The EU Ecodesign Directive is compressing product development cycles as manufacturers redesign thermal systems to meet standby power limits, while specialty café demand in Germany and Italy pulls super-automatic equipment into premium positioning.
Growth Catalysts
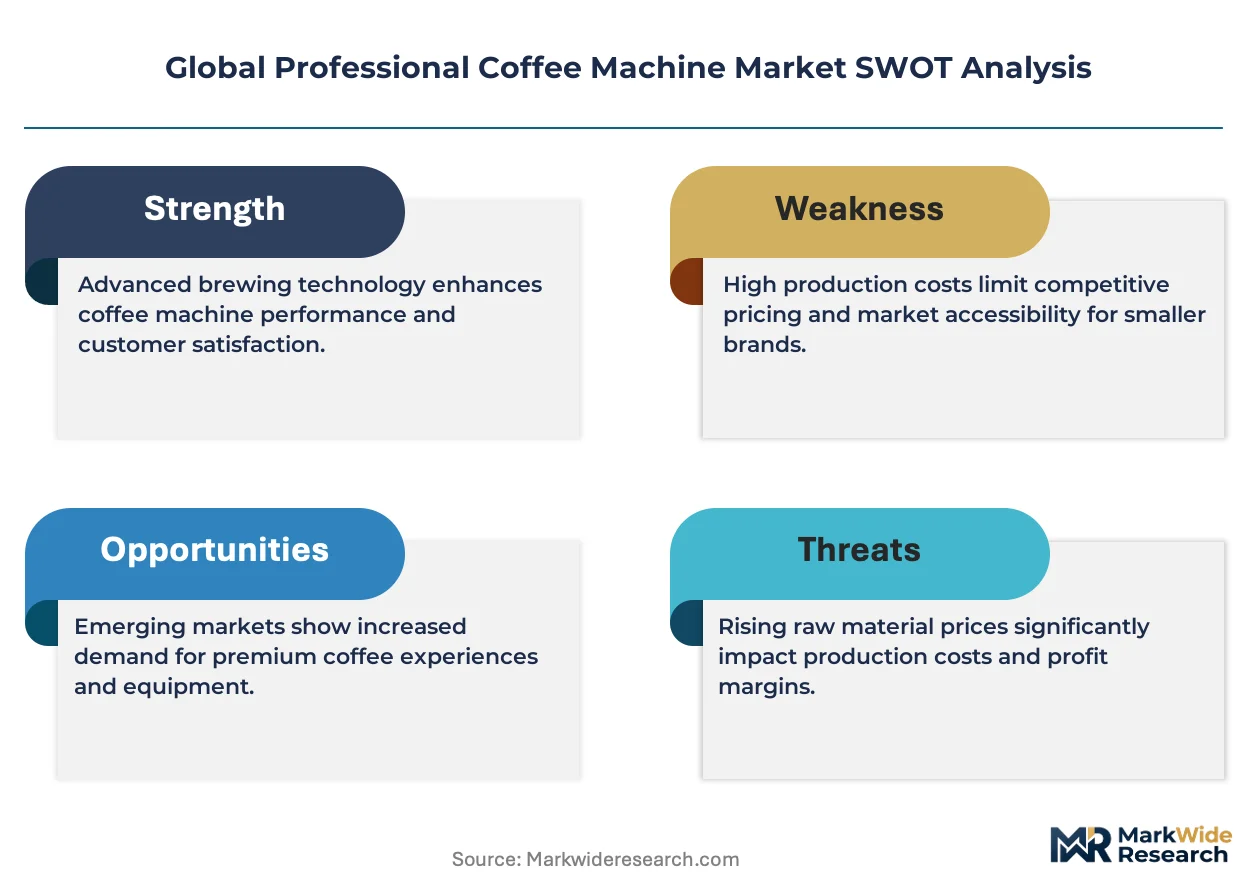
- Energy Efficiency Mandates:The EU Ecodesign Directive creates replacement demand across Western European commercial kitchens as aging equipment fails to meet standby power thresholds.
- Office Channel Expansion:Corporate facilities managers in Switzerland and the Netherlands prioritize labor-free brewing systems for workplace amenity programs.
- Pulse Extraction Technology:Proprietary brewing processes that optimize extraction time and temperature consistency reduce training requirements for hotel foodservice operations.
Market Restraints
- Stainless Steel Input Volatility:Boiler and brewing unit fabrication depends on nickel-chromium alloy pricing, exposing margin structures to commodity swings.
- Component Supply Concentration:Precision pressure valves and PID controllers concentrate among Italian and German component specialists, creating single-source vulnerabilities.
- Manual Machine Substitution Ceiling:Artisanal café segments in Florence and Melbourne resist automation, capping addressable market for fully integrated systems.
Strategic Opportunities
- Saudi Arabian Hospitality Buildout:Giga-project developments in Riyadh and Jeddah generate demand for high-throughput equipment in luxury hotel F&B operations.
- Connected Machine Convergence:IoT telemetry integration with predictive maintenance software creates recurring revenue streams for equipment financiers.
- US Inflation Reduction Act Credits:Commercial kitchen electrification incentives accelerate replacement of gas-powered espresso systems in California and New York foodservice.
Industry Challenges
- Certification Timeline Compression:REACH substance restrictions and RoHS material declarations extend compliance documentation for electronic control modules.
- Barista Skill Polarization:Super-automatic adoption in hotels and offices erodes the technician pipeline while artisanal cafés compete for scarce hand-crafting talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Professional Coffee Machine Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso Machines, Drip Coffee Makers, Percolators, French Presses End User: Cafés, Restaurants, Hotels, Offices Technology: Automatic, Semi-Automatic, Manual, Super-Automatic Installation: Countertop, Wall-Mounted, Built-In, Portable |
| Companies Covered | Rancilio Group, WMF Group, De'Longhi Group, CMA Astoria, La Cimbali, Jura Elektroapparate AG, Nestlé Nespresso Professional, La Spaziale, La Marzocco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Professional Coffee Machine Market Strategic Shifts
Equipment connectivity and thermal efficiency engineering are rewriting procurement criteria across European and North American commercial foodservice, compressing traditional equipment replacement cycles.
Gravimetric brewing technology is fragmenting extraction control standards by integrating precision load cells that measure output mass in real time. Specialty cafés in Melbourne and Copenhagen adopt these systems to eliminate shot-to-shot variance. The technology is fragmenting competitive positioning between sensor-integrated premium tiers and timer-based economy equipment.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in milk cooling systems integrated into super-automatic machines. Manufacturers serving German and French accounts must redesign thermal loops to accommodate natural refrigerants with higher pressure ratings. Espresso equipment with integrated refrigeration faces the steepest compliance cost escalation.
Hotel procurement departments are unbundling equipment purchase from service contracts, shifting toward third-party maintenance providers for multi-brand fleet management. This disintermediation pressures OEM service revenue in Spanish and Portuguese resort markets. Independent service organizations gain negotiating leverage through consolidated spare parts purchasing.
Global Professional Coffee Machine Market Segmentation
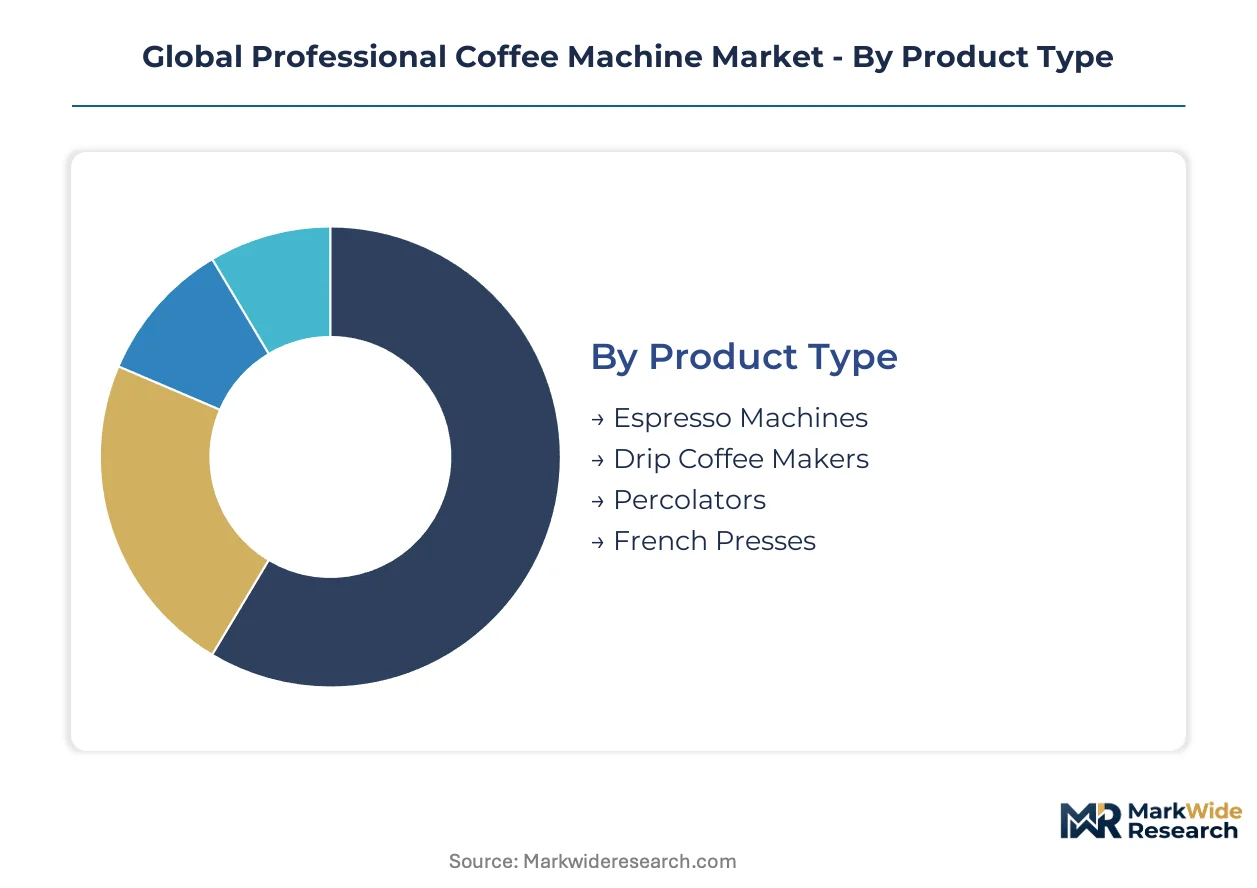
Professional coffee machine procurement channels diverge sharply by operational intensity and labor availability, with cafés prioritizing pressure-based extraction systems while offices and hotels gravitate toward touch-button consistency. Understanding these channel-specific requirements illuminates why technology and installation configurations cluster around distinct end-use economics rather than spreading evenly across the market.
Product Type:
Equipment flows through fundamentally different sales channels depending on brew method complexity and throughput requirements, with espresso systems dominating dealer networks while drip equipment concentrates in foodservice distributors.
- Espresso Machines:Pressure-based systems operating at nine-bar extraction with precision temperature stability dominate café and restaurant procurement. Specialty operators in Germany and Italy upgrade to multi-group configurations as out-of-home consumption remains structurally embedded in Western European markets.
- Drip Coffee Makers:Batch-brewing systems retain mature demand in North American institutional settings. Corporate dining contracts in the United States specify high-volume thermal carafe systems for breakfast service and conference catering.
- Percolators:Recirculating brew systems serve legacy hospitality accounts with established equipment replacement cycles. Older hotel properties in Switzerland and Austria maintain these systems for continuity in banquet operations.
- French Presses:Immersion brewing equipment addresses niche premium positioning in boutique hospitality. Small-footprint service in Danish and Swedish design-forward cafés favors manual preparation for guest-facing theater.
By volume, drip coffee makers lead in North American institutional procurement. By growth pace, espresso machines are climbing the fastest as specialty café culture expands across Middle Eastern and Asian urban centers.
End User:
Customer type determines automation level and service contract structure, with labor cost arbitrage driving divergence between technician-dependent and touch-button operational models.
- Cafés:Artisanal operators prioritize equipment enabling shot customization and milk texturing control. Melbourne and Copenhagen clusters invest in gravimetric brewing technology to eliminate variance in high-volume morning rushes.
- Restaurants:Full-service operators balance speed with beverage quality for post-meal service. Italian and French fine-dining establishments specify compact two-group machines for back-bar integration without dedicated barista stations.
- Hotels:F&B directors prioritize labor reduction and drink consistency across multiple service points. Saudi Arabian giga-project developments in Riyadh and Jeddah generate concentrated demand for high-throughput super-automatic systems in luxury property breakfast outlets.
- Offices:Facilities managers in the Netherlands and Switzerland specify fully automatic equipment for workplace amenity programs. Corporate procurement prioritizes machines requiring no trained staff while maintaining specialty-grade output quality.
By installed base, cafés hold the largest equipment population. By replacement velocity, offices are expanding most quickly as hybrid work patterns reshape amenity investment priorities.
Technology:
Automation tier selection correlates directly with labor availability and training investment capacity across end-use segments.
- Automatic:Programmable volumetric systems balance consistency with limited user control. Mid-market restaurants in Spain and Portugal deploy these systems where staff turnover complicates manual technique retention.
- Semi-Automatic:Barista-controlled extraction with automated pressure delivery dominates specialty café positioning. Hand-built equipment from Florentine manufacturers anchors this tier through artisanal brand association.
- Manual:Lever-operated and direct-lever systems serve enthusiast segments and competition preparation. Limited commercial penetration outside Melbourne, London, and Tokyo specialty clusters where technique demonstration carries marketing value.
- Super-Automatic:Integrated grinding, tamping, brewing, and milk handling eliminate operator skill requirements. Hotel procurement in German-speaking markets increasingly specifies these systems for 24-hour lobby service points.
By revenue concentration, semi-automatic systems lead in specialty café supply. By adoption momentum, super-automatic configurations are gaining share fastest in hospitality and corporate channels.
Installation:
Physical configuration constraints shape equipment selection based on available utility connections and service flow architecture.
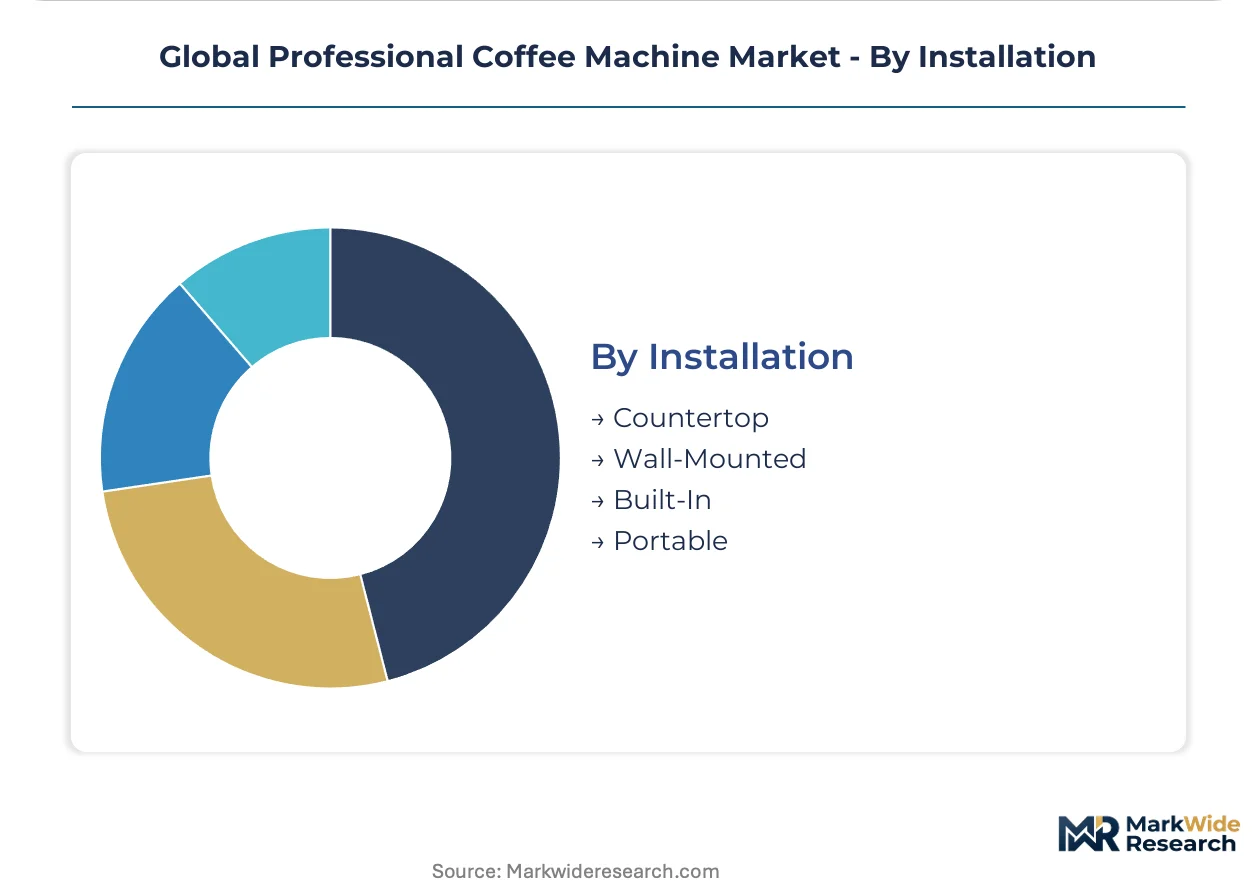
- Countertop:Freestanding units on work surfaces dominate café and restaurant deployment. Flexibility for equipment repositioning supports seasonal layout adjustments in French and Italian outdoor dining operations.
- Wall-Mounted:Space-saving configurations address compact urban premises with severe footprint limitations. Tokyo and Hong Kong espresso bars utilize these systems to maximize customer seating density.
- Built-In:Integrated millwork installations serve high-end hospitality and corporate flagship locations. Design-forward hotel properties in Copenhagen and Stockholm specify custom paneling for lobby coffee service integration.
- Portable:Mobile cart and event-serving configurations address catering and temporary activation requirements. Festival and exhibition operators in Germany and the Netherlands favor these systems for rapid deployment.
By shipment volume, countertop installations dominate commercial foodservice supply. By specification growth, built-in configurations are expanding most quickly in premium hospitality development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Italian engineering clusters while cost-sensitive procurement dominates North American institutional channels. Western European markets command premium positioning through regulatory stringency and artisanal café density. Middle Eastern hospitality buildouts are reshaping volume distribution toward high-throughput super-automatic specifications.
Germany
Specialty café upgrading and office channel expansion drive equipment refresh cycles. The EU Ecodesign Directive compresses development timelines for thermal system redesigns. Stuttgart and Hamburg engineering clusters anchor super-automatic production for corporate amenity programs.
Italy
Artisanal espresso culture sustains demand for hand-built pressure systems in Florence and Milan. REACH substance restrictions extend compliance documentation for boiler component suppliers. Bologna and Venice manufacturing districts concentrate semi-automatic equipment fabrication for export markets.
United States
Corporate dining contracts specify high-volume drip systems for institutional breakfast service. ENERGY STAR certification shapes procurement criteria for office and hospitality buyers. California and New York foodservice operators accelerate replacement of gas-powered equipment through IRA electrification incentives.
Saudi Arabia
Giga-project developments in Riyadh and Jeddah generate concentrated demand for luxury hotel F&B operations. SFDA foodservice equipment standards govern commercial kitchen installations. Western Region hospitality clusters specify high-throughput super-automatic systems for 24-hour lobby service points.
Japan
Tokyo espresso bars utilize wall-mounted configurations to maximize seating density in compact urban premises. METI energy efficiency guidelines influence commercial equipment specifications. Osaka and Nagoya corporate campuses prioritize labor-free brewing systems for workplace amenity investment.
Global Professional Coffee Machine Market Competitive Environment
Concentration sits with integrated engineering specialists and assembly-focused competitors competing across automation tiers. German and Italian fabricators dominate premium positioning through captive boiler and brewing unit production. Three archetypes define competitive structure: vertically integrated engineering houses, component-assembly specialists, and brand-marketing licensors. M&A activity targets thermal system capabilities while geographic expansion focuses on Middle Eastern hospitality procurement.
Among European engineering specialists, WMF Group and La Marzocco exemplify divergent positioning strategies. WMF Group represents the integrated super-automatic tier with German manufacturing heritage. La Marzocco occupies the artisanal hand-built segment anchored in Florentine production traditions. Jura Elektroapparate AG sits within the proprietary technology tier, exemplifying differentiation through pulse extraction process development.
| Leading Market Players |
|---|
| Rancilio Group |
| WMF Group |
| De'Longhi Group |
| CMA Astoria |
| La Cimbali |
| Jura Elektroapparate AG |
| Nestlé Nespresso Professional |
| La Spaziale |
| La Marzocco |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with capacity reservations lock in thermal component access and price visibility for German and Italian manufacturers navigating EU Ecodesign Directive compliance costs. Equipment financiers bundle maintenance obligations into lease structures that stabilize revenue streams while insulating buyers from nickel-chromium alloy volatility.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard catalog equipment in the professional coffee machine market. Three-tier pricing structure across premium, standard, and economy levels reflects automation complexity, with super-automatic systems capturing highest margins in Saudi Arabian hospitality procurement. Price differentiation stems from CE certification tier and after-sales service bundling. Cost compression in economy drip equipment is intensifying because North American institutional buyers consolidate vendor relationships. Corporate facilities managers in the Netherlands exhibit greatest price sensitivity, while luxury hotel F&B directors in Riyadh prioritize throughput reliability over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites stainless steel alloy shipments to Middle Eastern hospitality buildouts, exposing delivery schedules to geopolitical friction. Boiler and brewing unit fabrication draws from German, Italian, and Swiss engineering clusters. Nickel-chromium alloys, precision pressure valves, and PID controllers anchor raw material dependencies. Single-source vulnerability concentrates among Bologna and Stuttgart component specialists. Distribution runs through dealer networks for espresso systems and foodservice distributors for drip equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The professional coffee machine market is recovering from pandemic-induced replacement deferrals as Western European café upgrading and Middle Eastern hospitality construction restore equipment demand cycles.
For Market Incumbents: Secure captive supply of precision pressure valves through backward integration into Stuttgart and Bologna component specialists. Deepen channel control over German office procurement by bundling predictive maintenance software with equipment leases, countering independent service organization disintermediation in Iberian resort markets.
For New Entrants and Emerging Players: Lead with gravimetric brewing technology to penetrate Melbourne and Copenhagen specialty café clusters where shot-to-shot variance elimination commands premium positioning. Target Saudi Arabian giga-project developments through direct F&B director relationships, bypassing established dealer networks. Position as third-party maintenance providers for multi-brand fleet management in Spanish and Portuguese hospitality.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated engineering houses with in-house boiler production and established EU Ecodesign Directive compliance documentation. Long-term viability favors manufacturers with thermal system capabilities rather than assembly-focused competitors. Watch F-Gas Regulation phase-down timelines as inflection indicators for milk cooling system redesign costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Component Manufacturing | Captive supply of precision valves insulates German manufacturers from Bologna specialist bottlenecks. |
| IoT Telemetry Platform Development | Predictive maintenance software creates recurring revenue streams for equipment financiers serving Dutch corporate accounts. |
| Natural Refrigerant Thermal Loop Redesign | F-Gas Regulation compliance enables continued market access for German and French super-automatic suppliers. |
| Direct Hospitality Procurement Relationships | Bypassing dealer networks captures Saudi Arabian giga-project volume before incumbent lock-in. |
| Third-Party Maintenance Organization Buildout | Multi-brand fleet management gains negotiating leverage through consolidated spare parts purchasing in Iberia. |
Study Parameters
The analysis maps super-automatic, semi-automatic, and manual brewing systems, each validated through F&B directors, facilities managers, and aftermarket service heads across primary interviews. Secondary sources include EU Ecodesign Directive filings, ENERGY STAR certification databases, and customs records for nickel-chromium alloy trade flows. Bottom-up equipment shipment tallies triangulate against top-down hospitality construction pipeline estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include automation tier, end-use channel, installation configuration, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and new buildout penetration rates. Industry-specific forecast inputs incorporate EU F-Gas Regulation phase-down schedules and Saudi Arabian giga-project development timelines.
The analysis sits within stated boundaries; outcomes outside sustained Western European café investment and Middle Eastern hospitality construction would require recalibration. Forecasts reflect assumptions regarding nickel-chromium pricing stability and REACH substance restriction timelines. Practitioners should keep alternative scenarios live as EU energy efficiency mandates and SFDA equipment standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Tea and Coffee Bags Market
Coffee
Coffee Brewers Market
Coffee
US Coffee Roaster Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Oceania Coffee Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Adaptogen Coffee Market
Coffee
Coffee Capsules Market
Coffee
Germany Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Encapsulated Caffeine Market
Coffee
Singapore Coffee Roaster Market
Coffee
Coffee Pods and Capsules Market
Coffee
Office Coffee Service (OCS) Market