
 Oceania Coffee Market | 2026-2036
Oceania Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Oceania Coffee Market Analytics
Multi-source green bean procurement is broadening across Oceania roasters seeking supply resilience against climate volatility in traditional growing regions. Gloria Jean's Coffees leverages its franchised store network to sustain brand visibility in suburban Australian markets. Jacobs Douwe Egberts anchors the instant and capsule segments through manufacturing scale in regional production facilities. Seven Miles competes on specialty-grade sourcing, differentiating through direct-trade relationships with Pacific Island cooperatives.
Oceania coffee encompasses roasted and unroasted beans, soluble extracts, and ready-to-drink beverages derived from Coffea arabica and Coffea canephora species, typically processed through wet or dry milling to achieve moisture content below 12% for stable shelf life and flavor development. The primary commercial purpose spans foodservice preparation, retail packaged goods, and home consumption across temperature-variable brewing applications. Arabica dominates premium positioning in specialty stores and espresso-focused coffee shops, while cold brew adoption accelerates fastest among office worker and events consumer types. Ground coffee retains volume leadership in supermarkets, though online retail channels capture margin pools through subscription-based specialty distribution.
Food Standards Australia New Zealand (FSANZ) mandates compositional standards and labeling requirements that shape product formulation and import compliance across the trans-Tasman market. Biosecurity Australia enforces strict quarantine protocols on green bean imports, directly affecting sourcing flexibility and supplier qualification timelines. Australian Competition and Consumer Commission (ACCC) oversight of country-of-origin claims influences marketing strategies for roasters emphasizing provenance. Stakeholders must monitor evolving sustainability disclosure obligations and carbon accounting frameworks as procurement criteria harden across institutional buyers.
Market Dynamics
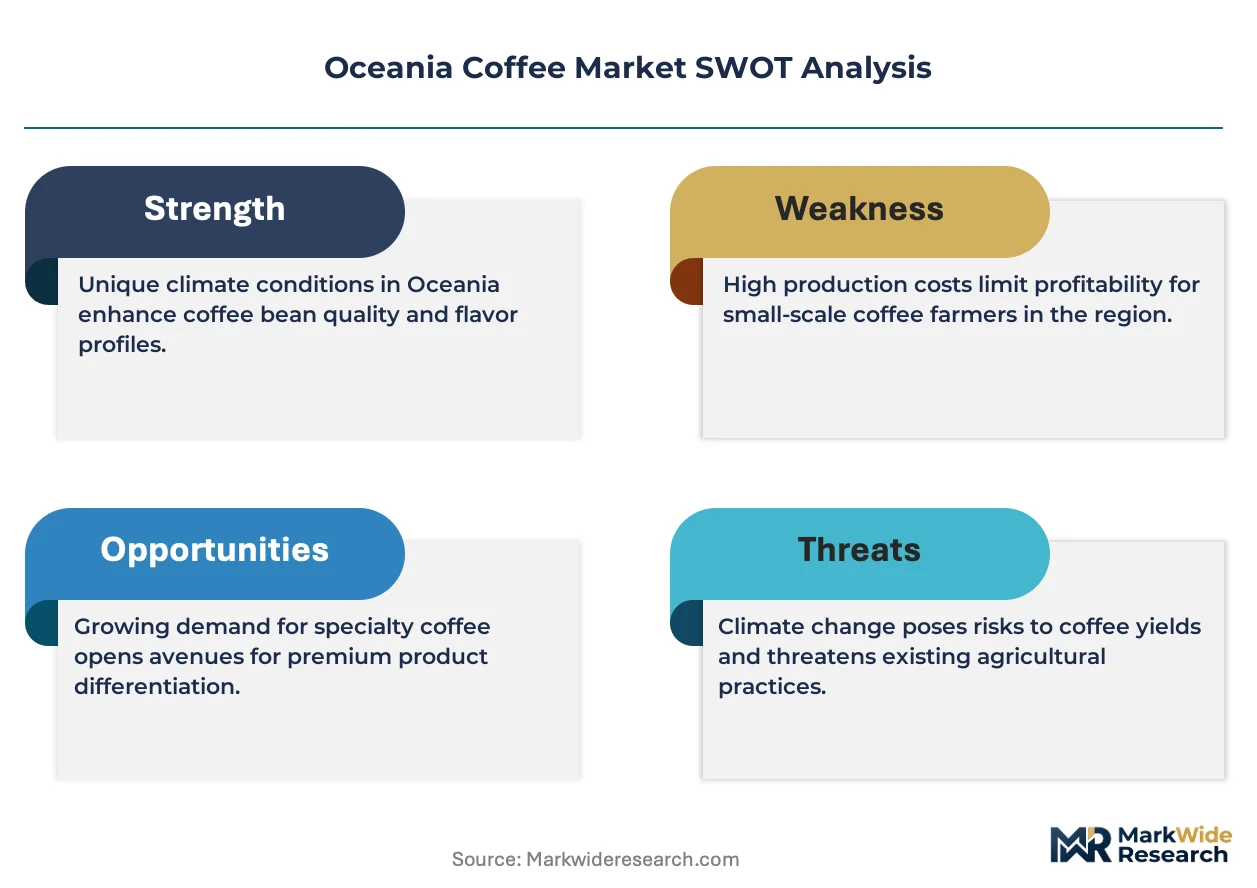
FSANZ labeling mandates and Biosecurity Australia quarantine protocols are restructuring procurement timelines, forcing roasters to diversify sourcing networks beyond traditional Pacific Island suppliers toward African and Latin American origins.
Growth Catalysts
- Cold brew processing:Nitrogen-infused and flash-chilled extraction methods are capturing office worker and events segments through extended shelf stability and on-tap dispensing formats.
- Direct-trade certification:Roasters building relationships with Papua New Guinea and Solomon Islands cooperatives secure preferential bean access and provenance storytelling for metropolitan café corridors.
- Subscription channel expansion:Online retail platforms specializing in single-origin curation are bypassing supermarket intermediaries to capture specialty-grade margin pools.
Market Restraints
- Arabica price volatility:Brazilian frost cycles and Colombian drought patterns transmit directly to Oceania roaster input costs, compressing blending flexibility.
- Green bean import quarantine:Biosecurity Australia fumigation requirements add 4-6 week delays to Ethiopian and Kenyan shipments, constraining just-in-time roasting schedules.
- Instant coffee substitution:Capsule and soluble formats retain price-sensitive household penetration, limiting whole-bean expansion into suburban Australian markets.
Strategic Opportunities
- Queensland and Western Australia café penetration:Melbourne and Sydney saturation creates whitespace for premium espresso programs in Brisbane, Perth, and Gold Coast corridors.
- Carbon accounting integration:Institutional buyers adopting Scope 3 disclosure frameworks favor roasters with Pacific Island cooperative traceability and maritime shipping offsets.
- Ready-to-drink canning:Cold brew and nitro coffee in aluminum formats is displacing glass bottle distribution through convenience store and petrol station channels.
Industry Challenges
- Q-grader certification scarcity:Specialty roasting expansion outpaces qualified cupping professionals, delaying new product launches and origin verification protocols.
- Roaster capex intensity:Probat and Giesen equipment backlogs extend facility expansion timelines, constraining capacity additions in response to demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oceania Coffee Market |
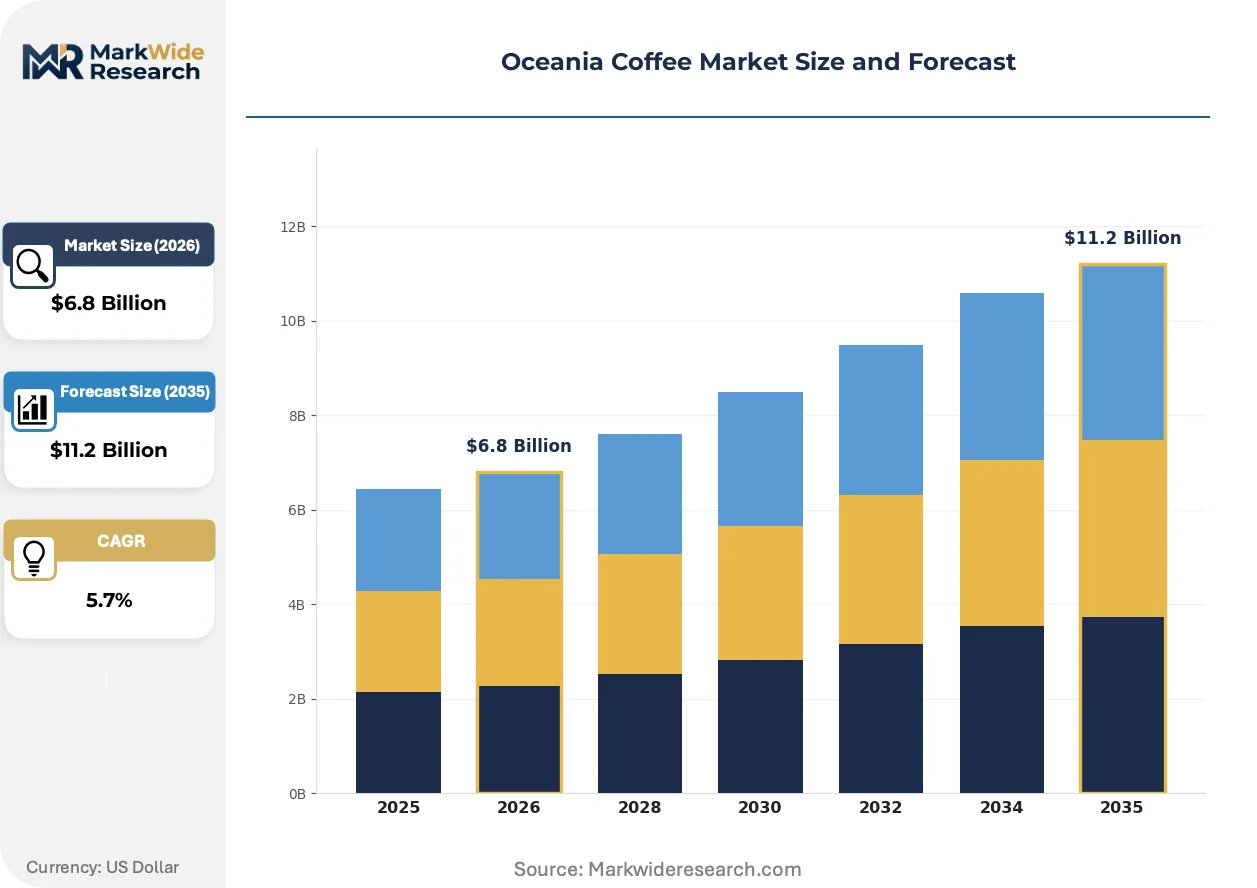
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Espresso, Ground Coffee Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Coffee Shops Consumer Type: Home Users, Office Workers, Café Owners, Events Brewing Method: Drip, French Press, Espresso Machine, Cold Brew |
| Companies Covered | Moccona, Seven Miles, Nestle SA, Lavazza, Cantarella Bros Pty Ltd, Starbucks Coffee Company, McDonald's, Gloria Jean’s Coffees, Jacobs Douwe Egberts, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oceania Coffee Market Evolving Landscape
Cold extraction technologies and sustainability disclosure mandates are converging to reshape product formats and procurement transparency across Australian and New Zealand coffee markets.
Pulse-brew and vacuum cold extraction systems are absorbing capital investment from mid-scale roasters seeking flavor consistency at volume. These systems enable batch-scale nitro infusion previously limited to draft beer equipment, allowing café chains to standardize across Melbourne, Sydney, and Auckland locations. The technology is absorbing market share from traditional immersion cold brew methods by compressing extraction time from 18 hours to 90 minutes while maintaining soluble solids concentration.
FSANZ updated allergen labeling requirements and impending sustainability disclosure frameworks are forcing reformulation of flavored roast and ready-to-drink portfolios. Roasters must now declare processing aids and cross-contamination risks for nut-derived flavorings, adding compliance layers to product development cycles. The regulations most directly affect supermarket ground coffee and capsule segments, where pack redesign timelines stretch 18-24 months.
Corporate procurement departments are consolidating coffee service contracts under single-source agreements with integrated equipment and bean supply. This displaces fragmented arrangements where facilities managers separately negotiated machine leases and roaster contracts. The consolidation is most visible in Sydney and Melbourne CBD office towers, where tenant experience teams prioritize consistent café-quality throughput over brand variety.
Oceania Coffee Market Segmentation
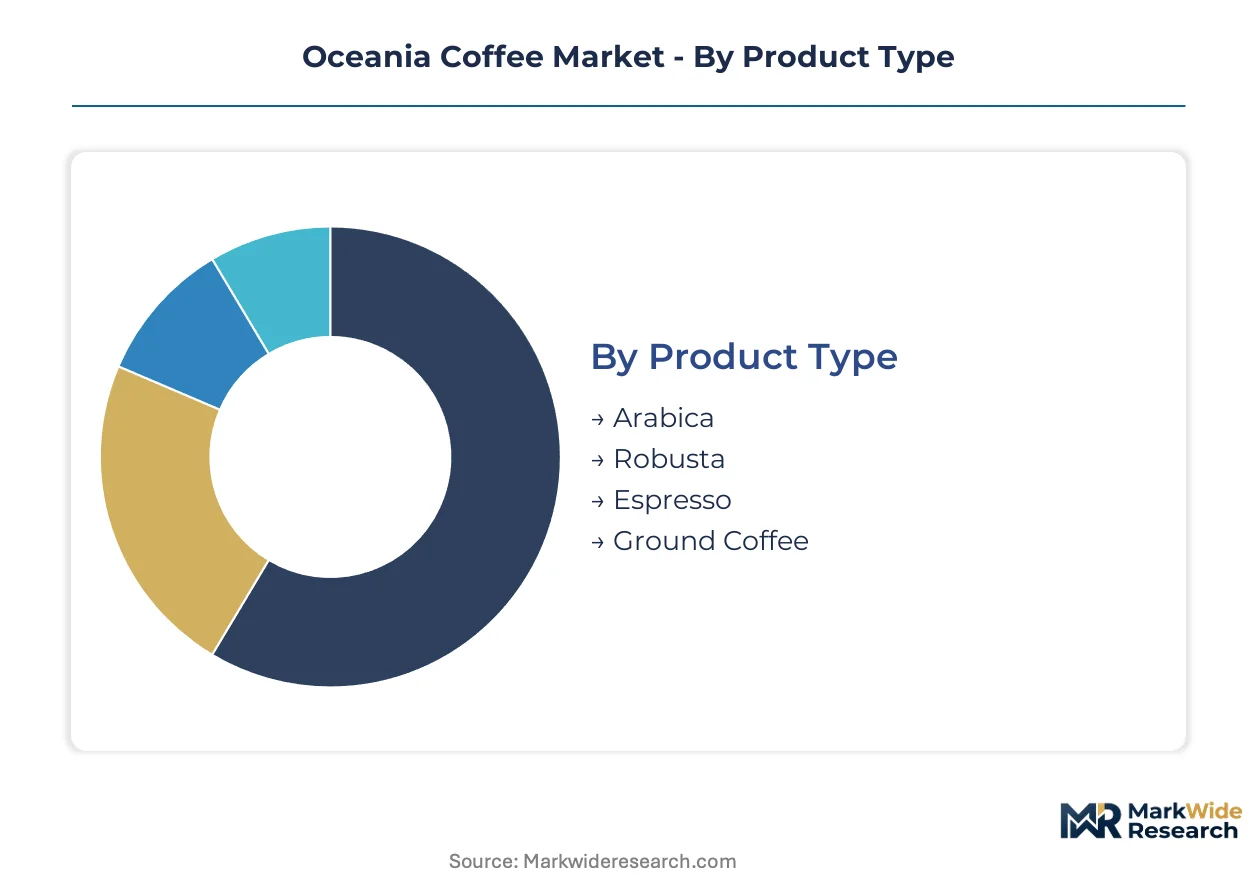
Segmentation in Oceania coffee reveals how brewing equipment replacement cycles and café format evolution drive purchasing patterns across product types and channels. Understanding these divisions exposes where margin pools shift between commodity formats and specialty-grade positioning.
Product Type:
Equipment refresh cycles in metropolitan cafés reshape bean procurement, with espresso machine upgrades triggering simultaneous shifts in roast profile specifications.
- Arabica:Higher-altitude varieties with 18-22% soluble solids dominate specialty espresso programs across Melbourne and Sydney café corridors. Premium single-origin positioning in these cities commands sustained price premiums despite Brazilian frost volatility transmitting directly to roaster input costs.
- Espresso:Darker roast profiles optimized for 9-bar extraction pressure and 25-30 second pull times anchor foodservice procurement volumes. Brisbane and Perth café expansions are absorbing equipment-integrated espresso formats as these markets replicate Melbourne's specialty infrastructure.
- Robusta:Higher caffeine content and crema-stabilizing lipids support Italian-style blends and instant coffee manufacturing at Jacobs Douwe Egberts regional facilities.
- Ground Coffee:Pre-milled formats for home drip and French press applications retain supermarket volume leadership through convenience positioning in suburban Australian markets.
Volume placements concentrate in Ground Coffee; the faster expansion belongs to Espresso.
Distribution Channel:
Channel selection in Oceania tracks customer acquisition cost thresholds, with high-frequency café users migrating toward direct subscription models that bypass retail markups.
- Online Retail:Subscription platforms specializing in single-origin curation capture specialty-grade margin pools through recurring revenue models. Direct-to-consumer roasting operations in Auckland and Sydney are displacing supermarket intermediaries for households exceeding 500g weekly consumption.
- Coffee Shops:On-premise consumption and bean retail from roasting operations build provenance storytelling through direct-trade relationships with Papua New Guinea cooperatives. These venues absorb premium positioning through equipment-integrated experiences unavailable in packaged formats.
- Supermarkets:Packaged ground and instant formats retain price-sensitive household penetration through promotional cycling and shelf-space dominance.
- Specialty Stores:Curated equipment and bean assortments serve enthusiast segments seeking grinder calibration and brewing consultation services.
Revenue concentrates in Supermarkets; the steepest expansion trajectory belongs to Online Retail.
Consumer Type:
Consumption occasion segmentation determines format specifications, with workplace and event applications demanding shelf-stable formats unavailable to home espresso setups.
- Office Workers:Nitrogen-infused cold brew and flash-chilled extraction methods capture this segment through extended shelf stability and on-tap dispensing formats. Sydney and Melbourne CBD corporate procurement departments are consolidating coffee service contracts under single-source agreements with integrated equipment supply.
- Café Owners:Equipment-integrated bean procurement and technical support contracts dominate this segment's vendor relationships across metropolitan Australian markets.
- Home Users:Capsule and soluble formats retain penetration among price-sensitive suburban households, constraining whole-bean expansion.
- Events:Mobile cold brew and nitro coffee canning in aluminum formats displaces glass bottle distribution through convenience store and petrol station channels.
Volume concentrates in Home Users; the fastest share gain belongs to Office Workers.
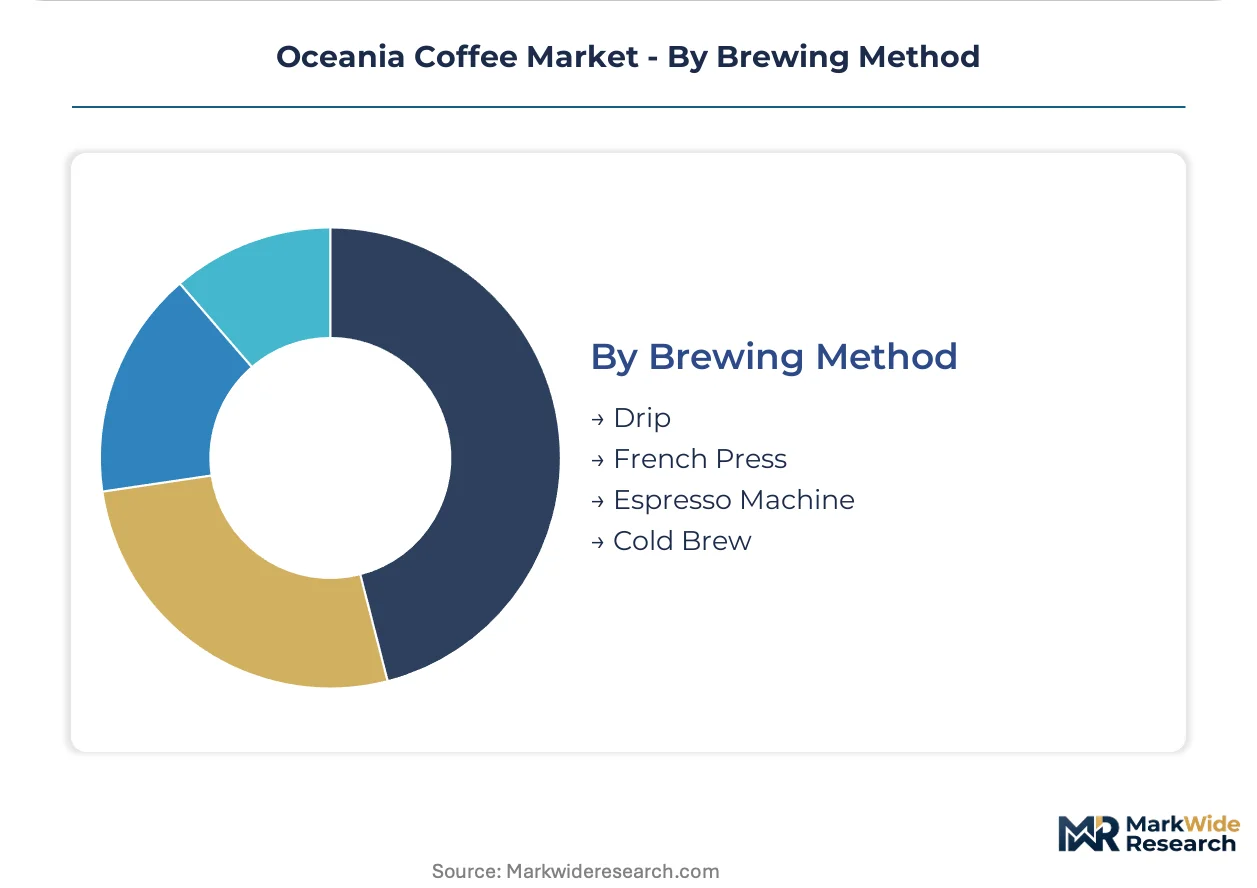
Brewing Method:
Method adoption curves follow equipment accessibility and time-to-brew constraints, with cold extraction technologies compressing preparation barriers for volume applications.
- Cold Brew:Pulse-brew and vacuum cold extraction systems compress extraction time from 18 hours to 90 minutes while maintaining soluble solids concentration. These systems enable batch-scale nitro infusion previously limited to draft beer equipment, allowing café chains to standardize across Melbourne, Sydney, and Auckland locations.
- Espresso Machine:9-bar pressure systems with PID temperature control anchor commercial foodservice preparation and enthusiast home markets through equipment-integrated bean sales.
- Drip:Gravity-fed paper filter methods retain volume leadership in home and office batch preparation through equipment accessibility.
- French Press:Immersion brewing with metal mesh filtration serves enthusiast segments prioritizing body and oil retention over clarity.
Volume concentrates in Drip; the expansion climbing fastest belongs to Cold Brew.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Papua New Guinea's highland cooperatives supply arabica to roasting operations across the Tasman Sea, anchoring regional trade flows. Australian metropolitan café corridors absorb the majority of processed volume, while New Zealand's specialty roasting sector concentrates in Auckland and Wellington.
Australia
Melbourne and Sydney café corridors drive premium espresso bean procurement through equipment-integrated roasting partnerships. Food Standards Australia New Zealand mandates allergen labeling and compositional standards that reshape flavored roast portfolios. Brisbane and Perth café expansions replicate Melbourne's specialty infrastructure, absorbing capital investment in Probat and Giesen equipment installations.
New Zealand
Auckland's direct-to-consumer roasting operations bypass supermarket intermediaries through subscription-based single-origin curation. Biosecurity New Zealand enforces quarantine protocols on green bean imports that add processing delays to Pacific Island shipments. Wellington's specialty roasting sector builds provenance storytelling through relationships with Papua New Guinea cooperatives.
Papua New Guinea
Highland cooperative arabica production supplies Melbourne and Sydney roasters seeking direct-trade certification for metropolitan café positioning. The country's national agricultural regulator oversees export quality standards that affect bean qualification timelines. Eastern Highlands Province concentrates wet-milling operations serving Australian specialty roasting contracts.
Solomon Islands
Smallholder robusta and arabica production feeds Australian roaster diversification strategies seeking supply resilience against Brazilian frost volatility. The Solomon Islands Commerce Ministry administers export licensing that shapes cooperative market access. Guadalcanal Province harbors expanding wet-milling capacity targeting Australian direct-trade procurement.
Fiji
Domestic consumption and limited export-grade arabica production serve regional tourism and local roasting operations. Fiji's national biosecurity authority regulates plant material imports that constrain varietal improvement programs. Viti Levu's Suva-Nadi corridor concentrates café development serving international visitor demand.
Oceania Coffee Market Competitive Landscape
Global majors compete with regional champions across distribution channel control, with multinational instant and capsule manufacturers holding supermarket shelf-space dominance while Australian and New Zealand roasting specialists capture specialty-grade margin pools through direct-trade relationships and subscription platforms. The market structure fragments across three tiers: multinational FMCG conglomerates with regional manufacturing scale, mid-scale roasting specialists with Pacific Island cooperative networks, and micro-roasters with hyperlocal café integration. Strategic moves concentrate on backward integration into green bean sourcing and forward integration into equipment-integrated service contracts for corporate procurement departments.
Among multinational FMCG conglomerates, Nestle SA and Jacobs Douwe Egberts occupy positions defined by manufacturing scale and instant coffee segment dominance. Within the regional specialty roasting tier, Seven Miles exemplifies the direct-trade archetype through Pacific Island cooperative relationships, while Gloria Jean's Coffees represents franchised network expansion across suburban Australian markets. Starbucks Coffee Company anchors the café-format multinational segment with metropolitan presence in Sydney, Melbourne, and Auckland.
| Leading Market Players |
|---|
| Moccona |
| Seven Miles |
| Nestle SA |
| Lavazza |
| Cantarella Bros Pty Ltd |
| Starbucks Coffee Company |
| McDonald's |
| Gloria Jean's Coffees |
| Jacobs Douwe Egberts |
| Others |
Value Network & Pricing Analysis
Green bean procurement costs cascade through Oceania roasting operations into three distinct pricing tiers, with Biosecurity Australia fumigation requirements adding fixed compliance layers that compress margins most severely at the economy end of the spectrum.
Pricing Analysis
Equipment-integrated service contracts bundle Probat and Giesen roasting hardware with multi-year bean supply agreements, unbundling these components exposes buyers to volatile Arabica spot markets. Three-tier pricing structure across premium, standard, and economy levels separates direct-trade single-origin offerings from blended supermarket grounds and instant formats. Cost compression in standard-tier ground coffee is intensifying because Jacobs Douwe Egberts manufacturing scale anchors price ceilings. Home users in suburban Australian markets exhibit highest price sensitivity; café owners purchasing through integrated contracts show lowest.
Supply Chain Analysis
High-altitude Arabica supply rests on Brazilian, Colombian, and Papua New Guinean highland cooperative production networks. Wet-milled green beans, nitrogen gas for cold brew infusion, and aluminum canning materials constitute critical input dependencies. Single-source vulnerability concentrates in Ethiopian and Kenyan shipments facing Biosecurity Australia quarantine delays. Distribution runs through Melbourne and Sydney metropolitan roasting hubs before radiating to Brisbane, Perth, and Auckland secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Probat and Giesen equipment backlogs stretching facility expansion timelines prop pricing power for incumbent roasters with installed capacity. Supply constraints favor operators able to secure qualified Q-grader talent and Pacific Island cooperative relationships.
For Market Incumbents: Anchor market position through backward integration into Papua New Guinea and Solomon Islands wet-milling capacity, securing preferential bean access against Brazilian frost volatility. Deepen equipment-integrated service contracts with Sydney and Melbourne CBD corporate procurement departments to lock out subscription-platform competitors. Invest in Q-grader certification pipelines to overcome specialty roasting expansion bottlenecks. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Queensland and Western Australia café corridors offers whitespace for mid-tier espresso programs replicating Melbourne's specialty infrastructure. Target Brisbane and Perth equipment-integrated roasting partnerships as the most penetrable geography. Pursue direct-trade certification with Guadalcanal Province cooperatives to differentiate provenance storytelling. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale roasting specialists with Pacific Island cooperative networks and established subscription revenue streams in Auckland and Sydney. Long-term viability across the analysis window hinges on carbon accounting integration and maritime shipping offset capabilities. Watch institutional buyer Scope 3 disclosure mandate adoption as inflection indicator for valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pacific Island Wet-Milling | Secures preferential bean access from Papua New Guinea highland cooperatives for direct-trade certification. |
| Equipment-Integrated Corporate Service Contracts | Locks out subscription competitors through Probat and Giesen hardware bundled with multi-year bean supply. |
| Q-Grader Certification Pipeline Investment | Overcomes specialty roasting expansion bottlenecks delaying new product launches and origin verification. |
| Carbon Accounting and Maritime Offset Integration | Aligns with institutional buyer Scope 3 disclosure frameworks favoring traceable Pacific Island sourcing. |
| Queensland and Western Australia Café Expansion | Captures whitespace in Brisbane and Perth corridors replicating Melbourne's specialty espresso infrastructure. |
Research Methodology
Document review covered FSANZ regulatory filings, Biosecurity Australia quarantine protocols, and Australian Competition and Consumer Commission enforcement actions, complemented by interviews with roasting operations directors, café procurement managers, Pacific Island cooperative export coordinators, and equipment distribution specialists. Secondary validation drew from customs import records, Food Standards Australia New Zealand compositional standard updates, and Australian Bureau of Agricultural and Resource Economics trade data. Bottom-up roasting capacity surveys and top-down consumption modeling were triangulated against subscription platform revenue disclosures.
Segmented outputs across product type, distribution channel, consumer type, and brewing method were generated through the projection horizon. CAGRs were derived from equipment replacement cycle analysis and café format penetration curves calibrated against metropolitan corridor saturation metrics. Arabica price volatility transmission coefficients and cold brew adoption velocity served as industry-specific forecast inputs.
Inputs from Pacific Island cooperative export coordinators and Biosecurity Australia processing time records were available through the study window; gaps in real-time Q-grader certification pipeline data introduce uncertainty bands around specialty segment growth assumptions. Forecasts reflect documented assumptions regarding equipment delivery timelines and regulatory enforcement intensity. A small set of triggers—Brazilian frost severity, FSANZ sustainability disclosure finalization, and corporate procurement contract consolidation velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
US Instant Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
High Protein Coffee Market
Coffee
Coffee Bottle Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
RTD Coffee Market
Coffee
Coffee Capsules Market
Coffee
Green Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Middle East Coffee Market
Coffee
Butter Coffee Market
Coffee
Global Cafe Market
Coffee
Espresso Coffee Market
Coffee
Coffee Cherry Market
Coffee
Middle East and Africa Coffee Market