
 Breakroom Refreshment and Coffee Services Market | 2026-2036
Breakroom Refreshment and Coffee Services Market Size, Share, and Industry Trends Forecast 2026-2036
Breakroom Refreshment and Coffee Services Market Insights
OSHA workplace wellness guidelines are realigning the cost-of-entry calculus for breakroom service providers. Aramark Refreshment Services leverages its institutional scale to dominate corporate and healthcare contracts. Nestlé Professional anchors its position through deep product specialization in single-serve and bean-to-cup systems. Farmer Brothers competes aggressively on direct-route density across mid-market accounts.
Breakroom refreshment and coffee services encompass the integrated provisioning of brewed beverages, packaged snacks, hydration systems, and dispensing equipment to commercial workplaces, typically under contractual service arrangements with scheduled replenishment and equipment maintenance. Equipment specifications span plumbed-in espresso systems with 1.5-bar pressure ratings to gravity-fed hot water dispensers, all configured for high-throughput, low-downtime operation in multi-shift environments. Office Coffee leads service type revenue due to entrenched per-employee consumption habits, while Vending Solutions captures the fastest structural expansion as cashless payment integration and telemetry-enabled inventory management reduce service costs. Corporations dominate end-user spending, though Healthcare Facilities represent a concentrated margin pool where 24-hour operational demands justify premium service tiers.
The FDA governs nutrition disclosure and allergen labeling for packaged refreshment items distributed through workplace channels, while the EPA sets effluent and energy-efficiency standards for brewing and refrigeration equipment. OSHA indoor air quality and ergonomic guidelines indirectly shape equipment placement and breakroom design specifications. Stakeholders must monitor how state-level extended producer responsibility frameworks for single-use cups and pods rewrite supplier accountability before committing to long-term equipment leases.
Market Dynamics
Hybrid work normalization has fractured the traditional five-day office consumption model, forcing service providers to reconfigure route density algorithms and equipment depreciation schedules around compressed weekly utilization patterns.
Growth Catalysts
- OSHA workplace wellness mandates:Federal ergonomic and indoor air quality guidelines are mandating upgraded breakroom infrastructure in multi-shift facilities, expanding the addressable equipment base.
- Telemetry-enabled inventory systems:IoT sensors and cashless payment integration are collapsing service visit frequencies while improving stockout prevention, lowering per-location operating costs.
- Healthcare facility 24-hour operations:Hospitals and long-term care centers require continuous refreshment provisioning, creating stable demand pools with premium service tier acceptance.
Market Restraints
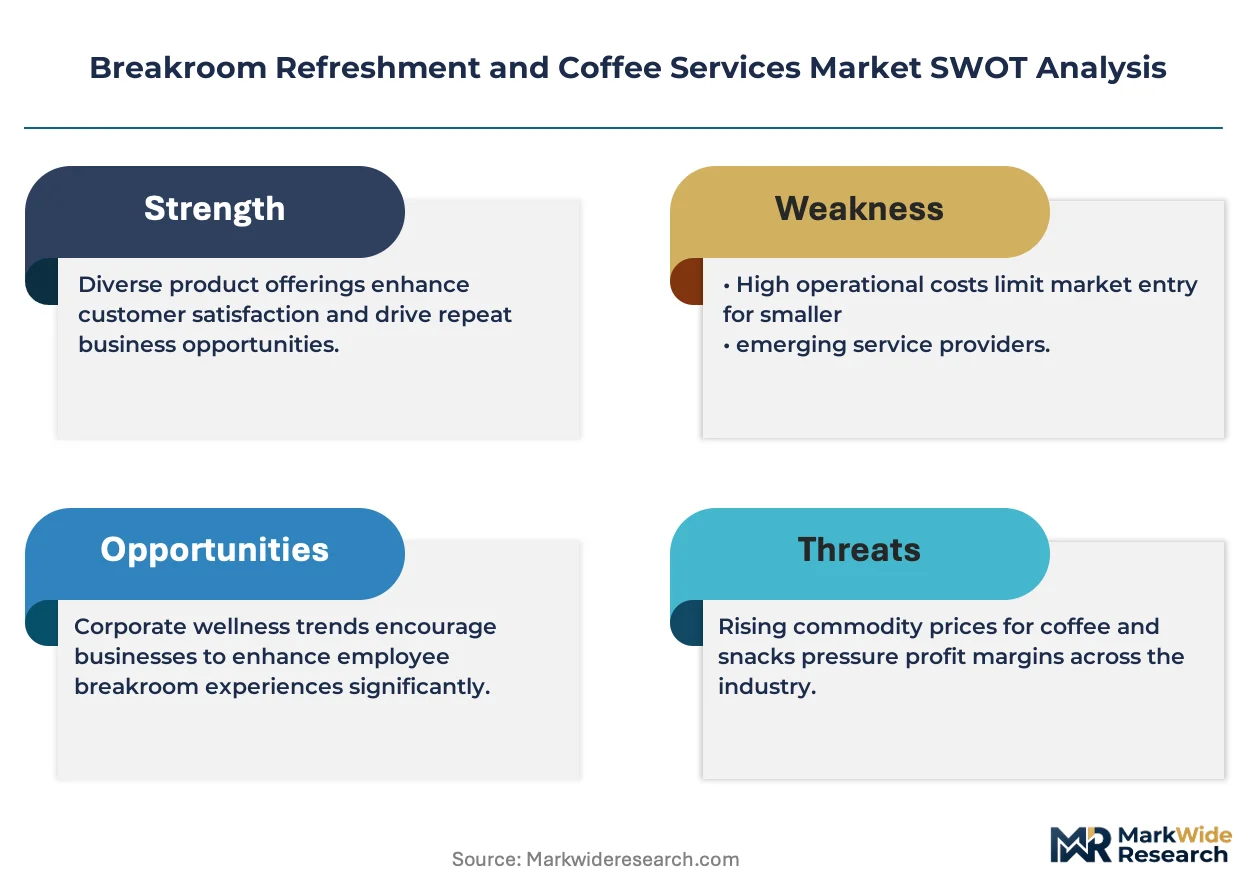
- Arabica coffee price volatility:Weather-driven supply disruptions in Brazil and Vietnam are compressing gross margins on bean-to-cup service contracts with fixed pricing terms.
- Single-use pod regulatory pressure:Extended producer responsibility frameworks in multiple states are imposing end-of-life fees and collection mandates on plastic and aluminum capsule systems.
- Route density collapse in suburban office parks:Hybrid schedules have thinned daily foot traffic below minimum thresholds for profitable vending and OCS service economics.
Strategic Opportunities
- Underpenetrated light industrial manufacturing:Warehouse and distribution centers lack structured breakroom programs, presenting greenfield contract opportunities with high employee density.
- EPA Energy Star equipment incentives:Federal efficiency rebates for refrigeration and brewing systems are accelerating capital refresh cycles among cost-sensitive mid-market accounts.
- Direct-to-employer subscription models:Home delivery of office-grade coffee and snacks for remote workers is bypassing traditional facility-based service channels.
Industry Challenges
- Technician workforce shortages:Equipment repair and preventive maintenance roles require specialized training on plumbed espresso and telemetry systems that vocational programs have not scaled to meet.
- Legacy ERP integration friction:Smaller service operators struggle to connect telemetry platforms with existing inventory and billing systems, delaying IoT deployment timelines.
- Multi-site contract standardization:Enterprise clients demand unified service levels across dispersed locations with varying municipal health codes and union work rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breakroom Refreshment and Coffee Services Market |
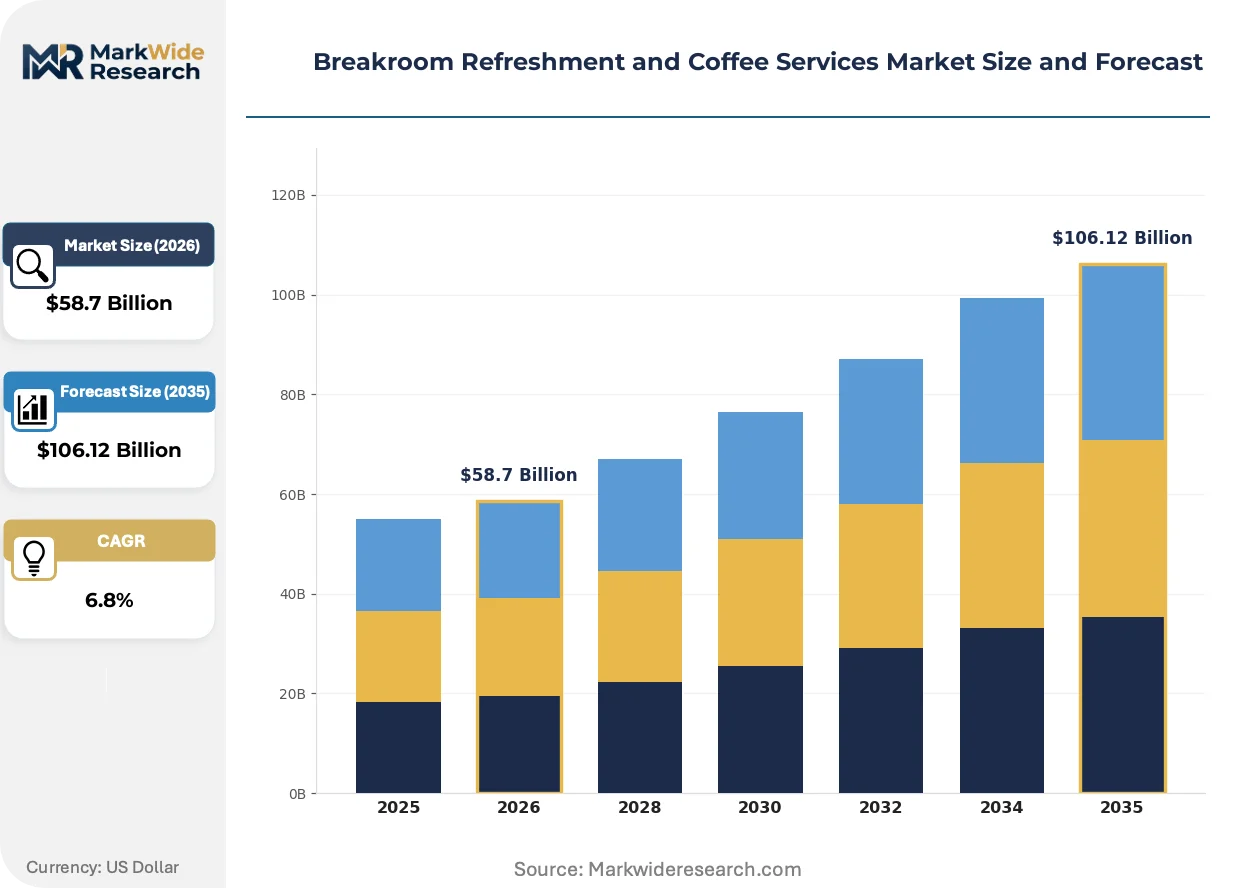
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Office Coffee, Snack Delivery, Vending Solutions, Water Supply End User: Corporations, SMBs, Educational Institutions, Healthcare Facilities Product Type: Coffee Machines, Tea Dispensers, Beverage Supplies, Snack Options Distribution Channel: Direct Sales, Online Platforms, Wholesalers, Retail Outlets |
| Companies Covered | Aramark Refreshment Services, Compass Group, Keurig Dr Pepper, Nestlé Professional, Sodexo, Westrock Coffee, Farmer Brothers, Royal Cup Coffee, Canteen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breakroom Refreshment and Coffee Services Market Trends and Innovations
Service models are pivoting from scheduled replenishment toward predictive, data-driven provisioning as telemetry penetration reshapes cost structures and client expectations simultaneously.
Bean-to-cup brewing systems with integrated grinders and customizable strength settings are converging with cashless payment and mobile ordering platforms. Corporate campuses with 500-plus employees are deploying these units at replacement rates exceeding traditional pour-over and satellite brewer retirements. The convergence is compressing the viable equipment lifecycle from seven years toward four, accelerating capital rotation for leasing companies and direct-route operators.
EU Green Deal packaging regulations and single-use plastic directives are mandating compostable cup and lid standards for workplace foodservice channels. Manufacturers serving multinational corporate accounts must certify compliance across divergent national implementation timelines. German and French facilities are experiencing the earliest enforcement waves, with suppliers accelerating biodegradable material transitions to maintain contract eligibility.
Enterprise procurement teams are consolidating refreshment spending under integrated facilities management umbrellas rather than standalone coffee service contracts. This bundling is displacing specialized OCS vendors in favor of broad-service contractors with multi-trade capabilities. The shift is most pronounced in United States coastal metros where real estate operators prefer single-vendor accountability for tenant amenity programming.
Breakroom Refreshment and Coffee Services Market Segmentation
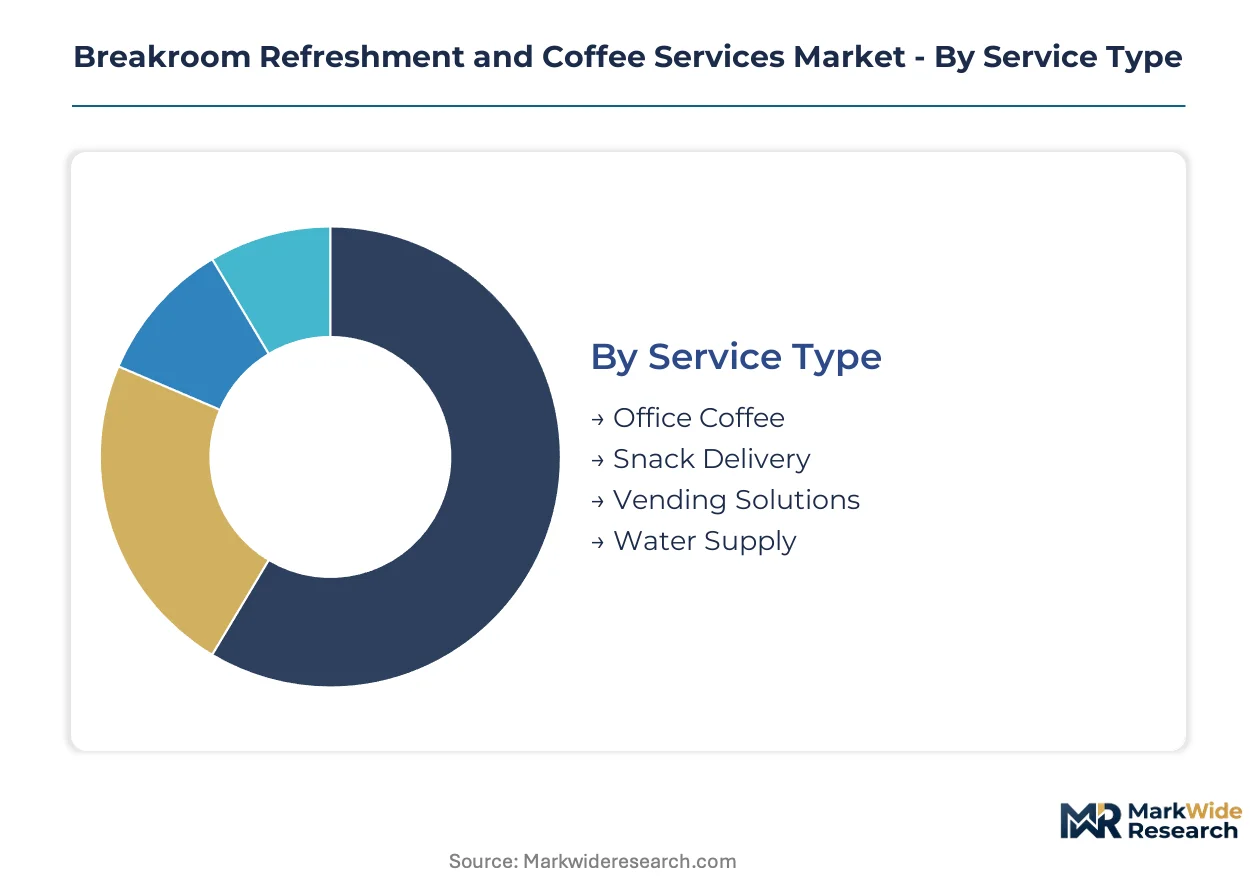
Breakroom refreshment and coffee services fragment across operational models, equipment specifications, and procurement channels. Understanding these divisions reveals where margin pools concentrate and which service configurations align with post-pandemic workplace utilization patterns.
Service Type:
Volume-driven route density competes against premium experience tiers across four distinct provisioning models.
- Office Coffee:Scheduled replenishment of brewed beverages through pour-over systems, satellite brewers, and bean-to-cup equipment under fixed-term contracts. Demand concentrates in United States corporate campuses where per-employee consumption habits justify dedicated equipment footprints and technician service networks.
- Vending Solutions:Cashless-enabled machines with telemetry-backed inventory management dispensing packaged snacks and beverages. Healthcare facilities in Germany and France drive premium-tier adoption due to 24-hour operational requirements and EU Green Deal packaging compliance mandates.
- Snack Delivery:Curated boxed and bulk snack provisioning with scheduled drop schedules. Corporate headquarters in suburban office parks favor this model for meeting-heavy environments requiring grab-and-go convenience without equipment capital expenditure.
- Water Supply:Plumbed and bottle-fed hydration systems with filtration and temperature control specifications. Light industrial manufacturing sites in Vietnam and Mexico present greenfield contract opportunities where municipal water quality drives employer-provided alternatives.
Today's leader: Office Coffee. Tomorrow's challenger: Vending Solutions.
End User:
Contract value and service tier acceptance diverge sharply across organizational scale and operational intensity.
- Corporations:Enterprise accounts with 500-plus employees demanding unified service levels across multi-site portfolios. United States coastal metros show pronounced bundling under integrated facilities management umbrellas, displacing standalone coffee service vendors.
- Healthcare Facilities:Hospitals and long-term care centers requiring continuous refreshment provisioning with premium tier acceptance. OSHA workplace wellness guidelines and FDA nutrition labeling requirements reshape procurement standards for this concentrated margin pool.
- SMBs:Mid-market accounts with 50-250 employees competing on direct-route density and equipment lease flexibility. EPA Energy Star rebates accelerate capital refresh cycles among this cost-sensitive segment.
- Educational Institutions:Universities and K-12 systems with seasonal demand fluctuations and municipal procurement rules. Extended producer responsibility frameworks for single-use pods complicate equipment selection in states with active mandates.
Corporations anchor current revenue. Healthcare Facilities offer the steepest expansion trajectory.
Product Type:
Equipment lifecycle compression and interoperability standards reshape capital deployment decisions.
- Coffee Machines:Bean-to-cup systems with integrated grinders and customizable strength settings converging with mobile ordering platforms. Equipment replacement cycles compress from seven years toward four as telemetry penetration accelerates.
- Snack Options:Packaged and fresh food assortments governed by FDA allergen labeling and state-level extended producer responsibility frameworks. Compostable packaging transitions maintain contract eligibility for multinational accounts.
- Tea Dispensers:Hot water systems with temperature precision for specialty tea preparation. Lower capital intensity appeals to SMB segments prioritizing equipment lease minimization.
- Beverage Supplies:Syrups, creamers, and alternative milk SKUs requiring refrigerated supply chain coordination. SKU proliferation strains legacy ERP integration for smaller service operators.
Coffee Machines dominate capital allocation. Snack Options gain share fastest through bundling mandates.
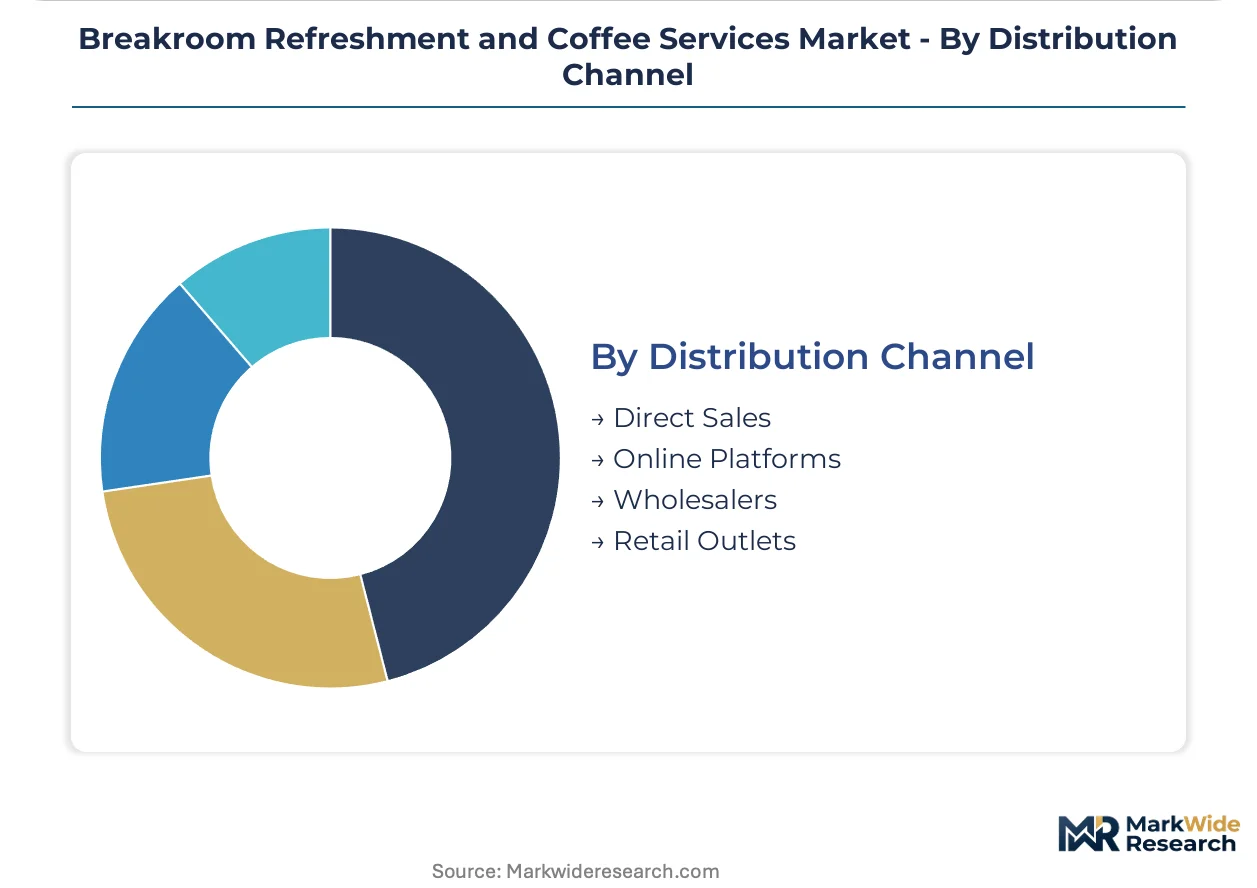
Distribution Channel:
Route economics and customer acquisition costs determine viable channel strategies by account size.
- Direct Sales:Field-based account executives and technician teams securing multi-year equipment leases with scheduled replenishment. Corporate and healthcare contracts in the United States depend on this channel for complex service level negotiations.
- Wholesalers:Third-party distributors reaching SMB and educational accounts below minimum thresholds for direct-route profitability. Inventory ownership transfer complicates telemetry integration for demand forecasting.
- Online Platforms:E-commerce portals for home delivery subscription models targeting remote workers. Direct-to-employer offerings bypass traditional facility-based service channels entirely.
- Retail Outlets:Big-box and specialty retailers serving micro-businesses and home office segments. Limited service attachment constrains lifetime value relative to contractual alternatives.
Direct Sales captures enterprise value. Online Platforms represent the most disruptive channel emergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The breakroom refreshment and coffee services industry traces its modern commercial roots to post-war United States office culture, where institutional foodservice operators first systematized workplace beverage provisioning. Federal workplace safety mandates and corporate amenity competition subsequently drove standardization across developed markets. Today, demand geography reflects hybrid work reinvestment patterns, healthcare facility expansion, and regulatory divergence on packaging sustainability.
United States
Corporate campuses in coastal metros and suburban office parks drive service contract volume as employers compete for talent through upgraded breakroom amenities. OSHA indoor air quality guidelines and FDA nutrition labeling requirements reshape equipment specifications and packaged snack procurement standards. Dallas-Fort Worth and Atlanta clusters show pronounced route density investments as service providers optimize suburban logistics networks.
Germany
Industrial manufacturing sites and healthcare facilities anchor demand for plumbed espresso systems and 24-hour vending solutions. EU Green Deal packaging regulations and extended producer responsibility frameworks accelerate compostable cup transitions and end-of-life fee structures for single-use pods. The Rhine-Ruhr industrial corridor concentrates contract opportunities where municipal waste ordinances outpace federal implementation timelines.
Japan
Corporate headquarters and precision manufacturing campuses sustain premium-tier bean-to-cup adoption with integrated mobile ordering platforms. METI energy-efficiency standards and workplace wellness guidelines elevate equipment specifications for multi-shift operations. Osaka-Kobe manufacturing clusters demonstrate concentrated demand for telemetry-enabled inventory systems that minimize service visit frequencies.
United Kingdom
London financial services and professional services firms drive integrated facilities management bundling that displaces standalone coffee service contracts. CSRD sustainability disclosure requirements and post-Brexit packaging regulations complicate multinational contract standardization for suppliers serving EU and UK accounts simultaneously. The Thames Valley technology corridor shows emerging demand for subscription-based home delivery models targeting hybrid workforces.
India
IT services campuses and multinational back-office operations in Bengaluru and Hyderabad create structured breakroom program demand previously served through ad hoc arrangements. FSSAI food safety standards and state-level plastic waste management rules reshape equipment and packaging procurement for corporate accounts. The Mumbai-Pune industrial belt presents greenfield opportunities as warehouse and distribution center density accelerates.
Breakroom Refreshment and Coffee Services Market Competitive Landscape
The competitive structure tilts toward diversified institutional foodservice operators with multi-trade capabilities. Tier-one contractors leverage integrated facilities management relationships to bundle refreshment services with broader workplace amenity portfolios. Three archetypes dominate: scale-driven route operators optimizing density algorithms, specialized coffee service providers with deep equipment expertise, and broad-service contractors capturing enterprise procurement consolidation. M&A activity concentrates on telemetry platform acquisitions and regional route density expansion. Strategic partnerships between equipment manufacturers and service operators accelerate bean-to-cup system deployment.
Within the diversified foodservice tier, Aramark Refreshment Services and Compass Group exemplify scale-driven operators with institutional contract depth. Sodexo occupies a position bridging corporate and healthcare segments through multi-site service standardization. Among specialized coffee service providers, Farmer Brothers and Royal Cup Coffee represent route-density competitors with regional technician networks. Keurig Dr Pepper and Nestlé Professional anchor equipment and product supply relationships that shape downstream service provider procurement. Westrock Coffee and Canteen sit within the vending and automated retail specialization, where cashless payment integration and telemetry-enabled inventory management define competitive positioning.
| Leading Market Players |
|---|
| Aramark Refreshment Services |
| Compass Group |
| Keurig Dr Pepper |
| Nestlé Professional |
| Sodexo |
| Westrock Coffee |
| Farmer Brothers |
| Royal Cup Coffee |
| Canteen |
| Others |
Pricing and Supply Chain Analysis
Technician workforce shortages in the United States Midwest and Southeast widen spreads between premium service tiers and economy route-density contracts. Labor-cost differentials between these regions and coastal metros translate directly into pricing-tier stratification, with employers in high-wage markets absorbing elevated per-location service fees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract negotiations, with differentiation hinging on equipment specification grade and after-sales service bundling. Premium tiers command acceptance from healthcare facilities requiring 24-hour technician response, while SMBs in suburban office parks exhibit acute price sensitivity due to compressed utilization from hybrid schedules. Pricing pressure stems from Arabica coffee commodity volatility and single-use pod regulatory fees, forcing providers to renegotiate fixed-term contracts mid-cycle.
Supply Chain Analysis
Equipment refurbishment and end-of-lease return flows from corporate accounts in the United States feed secondary markets in Mexico and Central America. Manufacturing concentration for bean-to-cup systems rests on Germany, Italy, and China, with brewing components drawing from precision metalwork suppliers in Switzerland and Japan. Single-source vulnerability in semiconductor chips for telemetry-enabled dispensers creates delivery uncertainty, while distribution runs through direct-route operators owning last-mile technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the United States, where OSHA wellness mandates justify premium service tiers, and Vietnam or Mexico, where light industrial manufacturing lacks structured breakroom programs and regulatory compliance costs remain minimal.
For Market Incumbents: Extend telemetry platform coverage into legacy equipment fleets before smaller operators achieve ERP integration parity. Consolidate route density in Dallas-Fort Worth and Atlanta clusters to defend against margin compression from suburban office park underutilization. Invest in EPA Energy Star certification pipelines to capture federal rebate flows among cost-sensitive mid-market accounts. For New Entrants and Emerging Players: Begin with warehouse and distribution center contracts in the Mumbai-Pune industrial belt, where employer density outpaces service provider penetration. Target home delivery subscription models for remote workers in the Thames Valley technology corridor, bypassing facility-based channel conflict entirely. Lead with compostable packaging compliance to disqualify pod-dependent incumbents in EU Green Deal enforcement zones. For Investors and Strategic Acquirers: Diversified foodservice operators with integrated facilities management capabilities are the most active acquirer in this space, consolidating standalone coffee service vendors in United States coastal metros. Long-term viability hinges on telemetry platform ownership and multi-site contract standardization expertise. Monitor state-level extended producer responsibility framework adoption as the inflection signal for equipment lease portfolio repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Acquisition | IoT sensor networks collapse service visit frequencies for Aramark-scale route operators. |
| Compostable Packaging Transition | EU Green Deal compliance maintains contract eligibility for multinational corporate accounts in Germany. |
| Direct-to-Employer Subscription Launch | Home delivery models bypass traditional facility-based channels for hybrid workforces in the United Kingdom. |
| Energy Star Equipment Refresh | Federal rebates accelerate capital rotation among EPA-compliant mid-market accounts. |
| Technician Training Program Scale-Up | Vocational pipeline expansion addresses workforce shortages constraining plumbed espresso service capacity. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and India, with primary inputs from each market. Interviews with route operations directors, facilities management procurement leads, equipment manufacturer product managers, and healthcare foodservice administrators combined with secondary validation from OSHA guidance documents, FDA nutrition labeling regulations, EPA Energy Star certifications, and EU Green Deal implementation timelines. Bottom-up location-level service contract analysis triangulates against top-down institutional foodservice spending estimates.
Granularity-level modeling disaggregates revenue across service type, end-user vertical, equipment specification tier, and distribution channel throughout the forecast period. CAGRs derive from weighted average growth across segment-level demand drivers including hybrid work normalization, healthcare facility expansion, and regulatory compliance cost pass-through. Forecast inputs incorporate telemetry penetration curves, equipment replacement cycle compression, and state-level extended producer responsibility adoption schedules.
Several conditions sit outside the modeled scope, including extreme weather events affecting Arabica supply, unanticipated federal tariff structures on brewing equipment imports, and pandemic-era workplace utilization pattern reversals. Forecasts reflect assumptions about sustained hybrid work stabilization and gradual EU packaging regulation harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Mushroom Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Cafix Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Nitrogenated Coffee Market
Coffee
High Protein Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Global Portable Coffee Makers Market
Coffee
Italy Coffee Market
Coffee
Cold Brew Coffee Makers Market