
 Singapore Coffee Roaster Market | 2026-2036
Singapore Coffee Roaster Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Coffee Roaster Market Insights
NEA emissions standards for commercial kitchen equipment is rebalancing the cost-of-entry calculus for new roasting operations in Singapore. Nylon Coffee Roasters leverages its vertical integration from green bean sourcing to retail brewing. Tiong Hoe Specialty Coffee anchors its competitive position through decades of heritage brand strength in local distribution channels. Common Man Coffee Roasters differentiates via technology leadership in precision profiling systems.
A coffee roaster is a thermal processing machine that applies controlled heat between 180°C and 230°C to green coffee beans, triggering Maillard reactions and pyrolysis to develop aromatic compounds and soluble solids for beverage extraction. Medium Roast commands the dominant volume position among product types due to its balance of acidity and body suited to Southeast Asian palates. Online distribution channels represent the fastest-growing segment as direct-to-consumer subscription models reshape how specialty roasters reach households and independent cafés.
Singapore's National Environment Agency sets mandatory emissions thresholds for commercial roasting equipment, while the Singapore Food Agency enforces hygiene and food safety protocols across processing facilities. Enterprise Singapore promotes productivity grants that subsidize automation upgrades for local manufacturers. Stakeholders must monitor how tightening carbon accounting requirements will reshape equipment replacement cycles and supplier qualification criteria.
Market Dynamics
Singapore's National Environment Agency emissions mandates for commercial roasting equipment are compressing equipment replacement cycles and elevating capital requirements for new market entrants. This regulatory pressure intersects with specialty coffee cluster formation in heritage neighborhoods, creating localized demand concentrations that reshape distribution patterns.
Growth Catalysts
- NEA Emissions Compliance Deadlines:Mandatory equipment upgrades in Tiong Bahru and Everton Park roasting clusters accelerate capital deployment toward cleaner-burning thermal systems.
- Heritage District Café Density:Specialty coffee concentration in Everton Park and Chinatown generates sustained equipment demand from independent micro-roasteries seeking proximity to consumer bases.
- Enterprise Singapore Productivity Grants:Automation subsidies lower effective equipment costs for local manufacturers integrating precision profiling technology.
Market Restraints
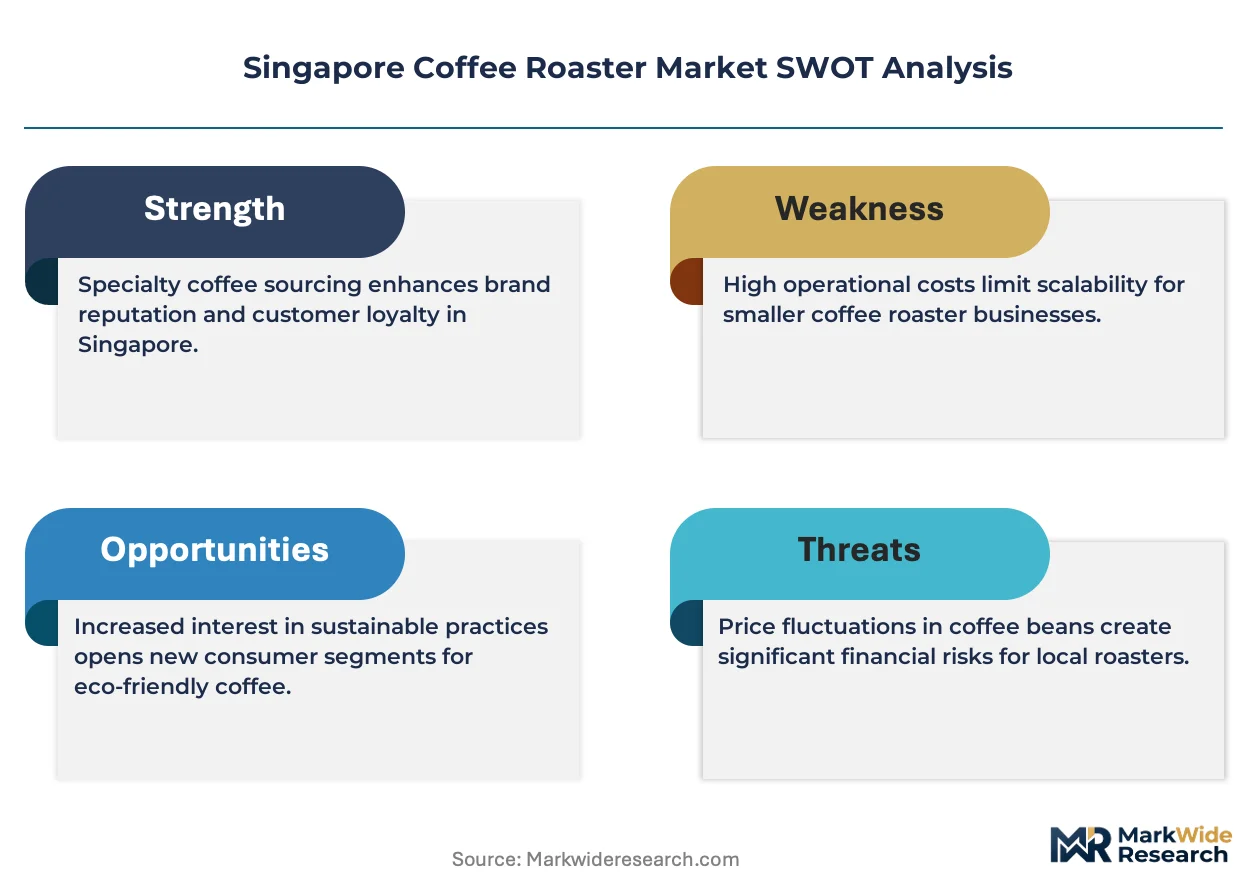
- Green Bean Price Volatility:Arabica futures fluctuations from Brazilian and Colombian supply disruptions compress roasting margin buffers for small-batch operators.
- Equipment Supply Concentration:German and Italian roasting system manufacturers dominate premium thermal processing equipment, creating import dependency and currency exposure.
- NEA Certification Timelines:Pre-operational emissions testing and facility approval processes extend new entrant time-to-revenue by four to six months.
Strategic Opportunities
- Direct-to-Consumer Subscription Channels:Online distribution platforms enable micro-roasteries in the Central Business District to bypass traditional wholesale intermediaries and capture retail margins.
- Carbon Accounting Integration:Enterprise Singapore sustainability reporting incentives reward roasteries deploying blockchain-traceable green bean sourcing systems.
- Precision Profiling Technology:Convergence of IoT sensor arrays with machine learning roast curve optimization creates differentiation for technology-forward operators.
Industry Challenges
- Roastmaster Talent Scarcity:Specialized thermal processing expertise for small-batch Arabica roasting commands premium compensation, constraining scaling capacity for independent operations.
- Legacy Equipment Integration:Retrofitting pre-2015 roasting systems with NEA-compliant afterburner and filtration technology requires substantial capital outlay without productivity gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Coffee Roaster Market |
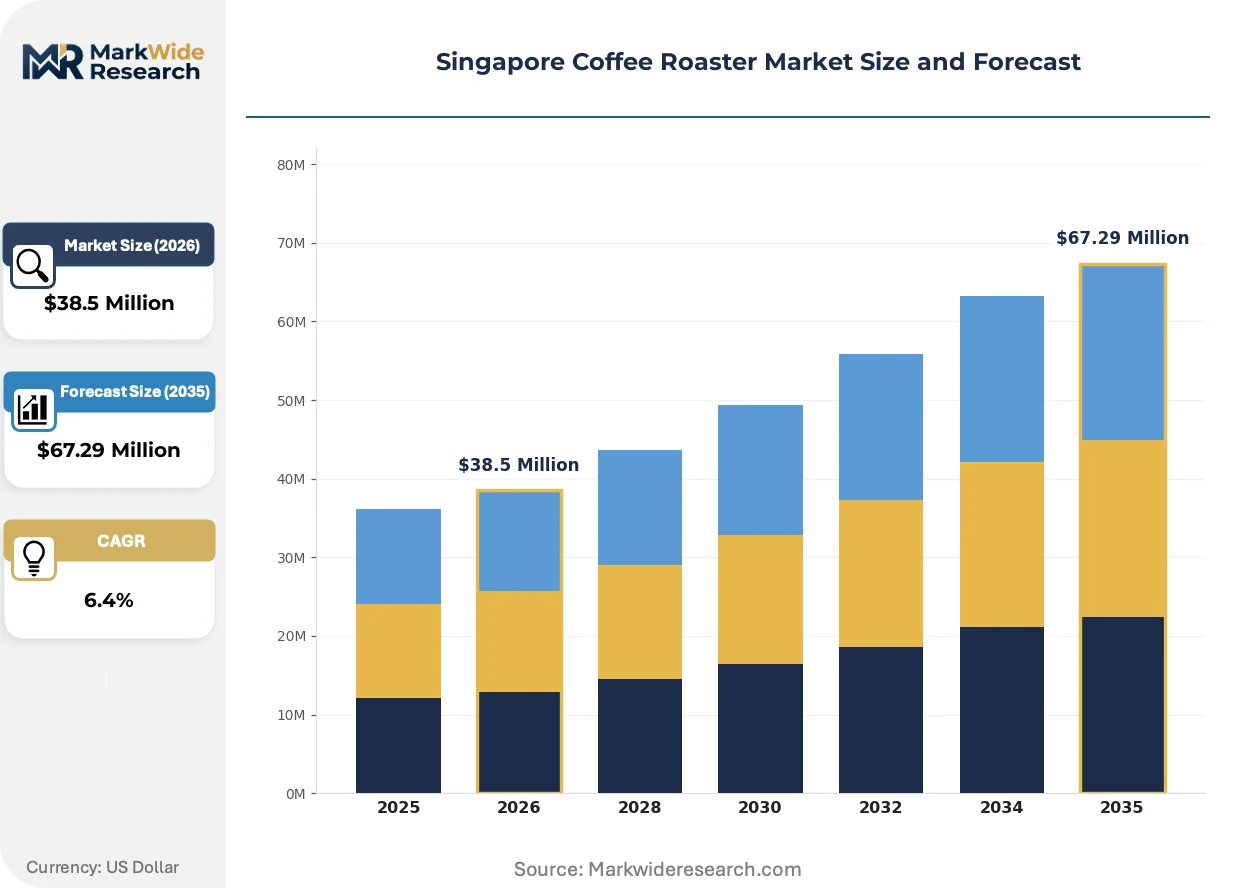
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $67.29 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Roast, Medium Roast, Dark Roast, Flavored Customer Type: Household, Cafés, Restaurants, Retailers Distribution Channel: Online, Specialty Stores, Supermarkets, Wholesalers Grind Size: Whole Bean, Coarse, Medium, Fine |
| Companies Covered | Nylon Coffee Roasters, Fore Coffee, Apartment Coffee, Kopi & Co, Tiong Hoe Specialty Coffee, Five Oars Coffee Roasters, Timbre+, Woodlands Coffee Roasters, Common Man Coffee Roasters, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Coffee Roaster Market Trends and Innovations
Technology convergence, regulatory stringency, and channel disintermediation are restructuring how roasting equipment is specified, financed, and deployed across Singapore's specialty coffee ecosystem. These forces compress traditional equipment procurement cycles while elevating performance expectations.
Precision profiling software is converging with cloud-based roast analytics platforms to enable real-time thermal curve adjustment. Independent roasteries in the Central Business District are adopting these systems at accelerating rates to differentiate cup consistency. This technology compression is collapsing the traditional gap between artisan roasting craft and industrial process control.
Singapore's National Environment Agency tightened particulate matter thresholds for commercial kitchen equipment in 2024, mandating catalytic afterburner installation for roasting operations above specified throughput levels. This policy compression forces equipment replacement decisions earlier than depreciation schedules would suggest. Micro-roasteries in Tiong Bahru are responding by consolidating roasting volumes to amortize compliance costs across larger batch runs.
Direct equipment financing from manufacturers is displacing traditional bank lending for roasting system procurement. Independent café chains and hotel foodservice operations are leveraging vendor-backed payment structures to preserve working capital for green bean inventory. This financing shift is most visible among new entrants in the Joo Chiat and Katong heritage districts seeking to minimize upfront capital commitment.
Singapore Coffee Roaster Market Segmentation
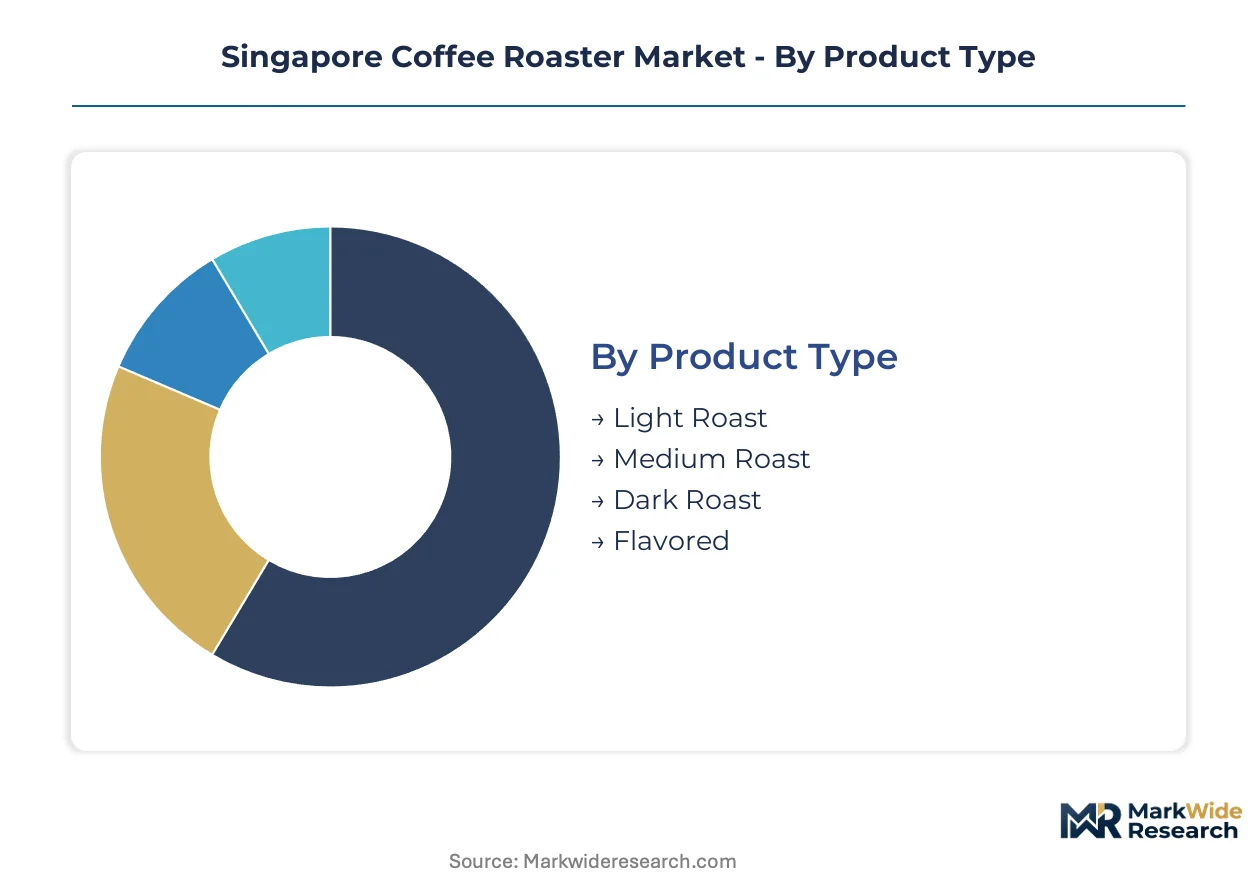
Roast profile preferences and channel economics create distinct equipment specification tiers across Singapore's specialty coffee ecosystem. Understanding these segment boundaries clarifies where capital deployment concentrates and where margin compression threatens operator viability.
Product Type:
Volume leadership sits with balanced roast profiles, while premium positioning attaches to lighter thermal treatments that preserve origin characteristics.
- Medium Roast:Thermal processing between 210°C and 220°C develops caramelized sugars without sacrificing acidity clarity. Demand concentrates among independent cafés in Tiong Bahru and Everton Park where Southeast Asian palates favor body-acidity equilibrium. NEA emissions compliance costs per kilogram of output favor operators running medium roast at scale.
- Light Roast:Lower terminal temperatures between 180°C and 200°C preserve volatile aromatic compounds and origin-specific terroir. Micro-roasteries in the Central Business District deploy precision profiling technology to differentiate through cup transparency. Equipment utilization rates run lower due to extended development times and smaller batch economics.
- Dark Roast:Extended pyrolysis above 225°C produces carbon-forward flavor profiles with reduced acidity. Traditional kopitiam chains and hotel foodservice operations specify these profiles for consistency across high-volume extraction.
- Flavored:Post-roast coating with oil-based flavoring agents requires dedicated handling equipment to prevent cross-contamination. Niche demand from themed cafés in heritage districts drives specialized roasting line configurations.
Mature deployment sits with Medium Roast. Newer deployment is concentrated in Light Roast.
Customer Type:
Equipment specification diverges sharply between household-scale appliances and commercial thermal processing systems rated for continuous duty cycles.
- Cafés:Independent specialty operators in heritage neighborhoods drive demand for 5-15kg batch roasters with integrated afterburner systems. Enterprise Singapore productivity grants subsidize automation upgrades for roasting-to-retail verticals.
- Restaurants:Fine-dining establishments and hotel foodservice operations prioritize consistency systems with programmable roast curves. Procurement concentrates through equipment-leasing arrangements to preserve working capital.
- Household:Enthusiast-grade drum roasters and fluid-bed systems serve home roasting communities. Online distribution channels enable direct-to-consumer subscription models for green bean supply.
- Retailers:Supermarket chains and specialty grocers specify private-label roasting capacity with packaging integration for shelf-ready distribution.
Volume procurement runs through Cafés. Margin expansion concentrates in Restaurant specifications.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics for roasting operations at varying scale.
- Online:Direct-to-consumer subscription platforms enable micro-roasteries to bypass wholesale intermediaries and capture retail margins. Blockchain-traceable sourcing systems align with Enterprise Singapore sustainability reporting incentives.
- Specialty Stores:Curated retail environments in Tiong Bahru and Everton Park provide tactile evaluation of roast freshness. Staff training requirements elevate operational overhead relative to self-service channels.
- Supermarkets:Mass retail distribution demands packaging automation and extended shelf-life protocols. Price compression from private-label competition constrains specialty positioning.
- Wholesalers:Traditional intermediaries serve independent cafés and restaurants outside heritage district clusters. Inventory financing terms vary with green bean price volatility exposure.
Established volume flows through Wholesalers. Channel expansion is climbing the fastest in Online.
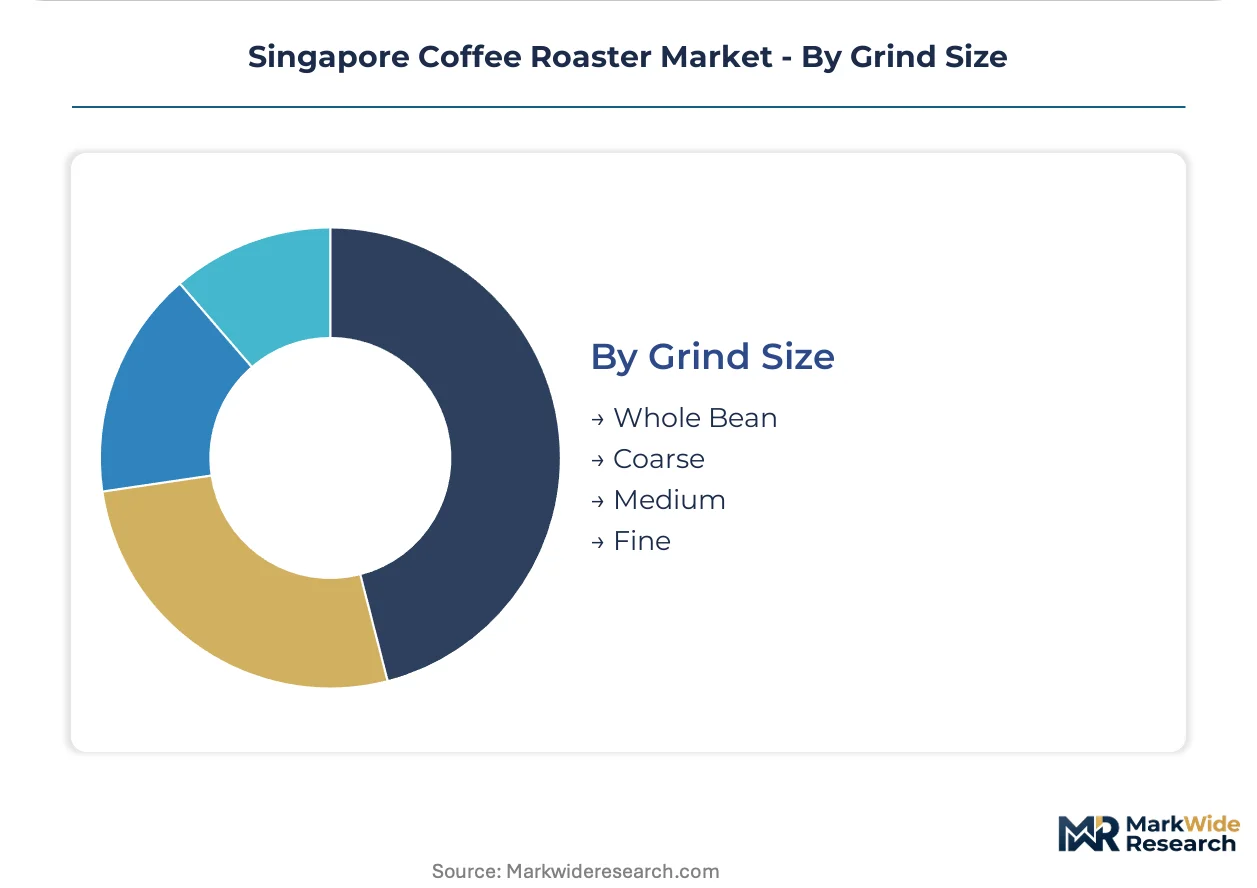
Grind Size:
Grind specification at the roasting facility versus point-of-consumption creates divergent equipment and packaging requirements.
- Whole Bean:Unprocessed output preserves aromatic compound stability during storage. Specialty cafés and enthusiast households specify whole bean for grinding immediacy before extraction.
- Medium:Drip-filter grind size dominates foodservice and office coffee service channels. Packaging nitrogen flushing extends shelf life for pre-ground distribution.
- Coarse:French press and cold brew applications demand uniform particle size distribution. Limited roasting facility grinding capacity drives co-manufacturing arrangements.
- Fine:Espresso-grade grinding requires precision burr systems with temperature control. On-site grinding at cafés predominates due to rapid aromatic degradation post-processing.
Quality-sensitive procurement concentrates in Whole Bean. Convenience-driven demand is expanding most quickly in Medium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jurong Innovation District and one-north research corridor concentrate specialty coffee equipment demand through proximity to food-tech R&D facilities and venture-backed roasting ventures. Enterprise Singapore's Pioneer Generation incentives and productivity grants channel capital toward automation upgrades in designated industrial zones. Heritage neighborhood clusters in Tiong Bahru and Everton Park anchor consumer-facing roasting operations.
Central Business District
Independent micro-roasteries cluster around Tanjong Pagar and Raffles Place, driven by corporate catering contracts and premium office coffee service demand. The National Environment Agency enforces emissions testing protocols for commercial roasting equipment in dense commercial zones. Precision profiling technology adoption concentrates here as operators differentiate through cup consistency for discerning professional clientele.
Tiong Bahru
Heritage shophouse conversions generate sustained equipment demand from boutique roasting operations seeking proximity to affluent residential consumers. NEA catalytic afterburner mandates compress equipment replacement cycles for pre-2015 thermal systems. The Tiong Bahru Market food cluster creates cross-traffic between traditional kopitiam culture and third-wave specialty roasting.
Everton Park
Café density in this heritage neighborhood drives small-batch roasting equipment procurement from independent operators. Enterprise Singapore productivity grants subsidize automation upgrades for roasting-to-retail verticals in designated conservation areas. The Everton Park conservation estate provides protected commercial space for specialty coffee cluster formation.
Joo Chiat and Katong
Peranakan heritage tourism intersects with specialty coffee retail, generating equipment demand from themed roasting operations. Vendor-backed equipment financing structures predominate among new entrants seeking to minimize upfront capital commitment. The Katong Shopping Centre and surrounding shophouses host emerging micro-roasteries targeting weekend consumer traffic.
Jurong and Western Industrial Zones
Large-scale roasting operations concentrate in Jurong's food manufacturing precincts, driven by export-oriented production and private-label supply contracts. The Singapore Food Agency enforces hygiene protocols across processing facilities in designated industrial estates. Jurong Port proximity facilitates green bean import logistics for volume roasting operations serving regional markets.
Singapore Coffee Roaster Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Singapore's coffee roasting equipment value chain. The market structure tilts toward fragmentation, with independent micro-roasteries and heritage-brand operators coexisting alongside venture-backed scaling ventures. Three archetypes dominate: vertically integrated roasting-to-retail operators, technology-forward precision profiling adopters, and heritage-brand distributors with decades of local channel presence. Competitive moves concentrate on strategic partnerships with equipment manufacturers and backward integration into green bean sourcing.
Among heritage-brand operators, Tiong Hoe Specialty Coffee anchors traditional distribution channel strength, while Nylon Coffee Roasters exemplifies vertical integration from sourcing through retail brewing. Common Man Coffee Roasters occupies a position on the technology-forward vector, representing precision profiling system adoption. These three entities collectively illustrate the competitive tension between artisan craft heritage and automated process control that defines equipment specification debates across Singapore's specialty coffee ecosystem.
| Leading Market Players |
|---|
| Nylon Coffee Roasters |
| Fore Coffee |
| Apartment Coffee |
| Kopi & Co |
| Tiong Hoe Specialty Coffee |
| Five Oars Coffee Roasters |
| Timbre+ |
| Woodlands Coffee Roasters |
| Common Man Coffee Roasters |
| Others |
Pricing and Supply Chain Analysis
Backward integration from green bean sourcing through retail brewing anchors both supply security and pricing power for established Singapore roasteries. This captive supply structure insulates margin buffers against Arabica futures volatility while NEA emissions compliance costs concentrate pricing leverage among operators with scale to amortize catalytic afterburner investments.
Pricing Analysis
Premium pricing attaches to short lead-time fulfillment for precision-profiled small-batch roasts, while spot inventory of standard medium roasts trades at narrower spreads. Three-tier pricing structure across premium single-origin, standard house blends, and economy foodservice tiers differentiates by certification grade and after-sales cupping support. Cost compression in the economy tier is intensifying because private-label supermarket competition erodes brand premiums. Independent cafés in heritage districts exhibit least price sensitivity, while hotel foodservice procurement teams drive hardest bargain.
Supply Chain Analysis
Singapore's absence of domestic-content mandates leaves sourcing exposed to import dependency patterns reshaping equipment and raw material flows. Green bean supply concentrates in Brazil, Colombia, and Ethiopia, while thermal processing equipment draws from Germany and Italy. Logistics chokepoints at Jurong Port create single-point vulnerability for volume roasting operations. Distribution runs through direct-to-consumer subscription platforms alongside traditional wholesale intermediaries serving independent cafés outside Tiong Bahru and Everton Park clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's National Environment Agency emissions mandates function as a cost-of-compliance moat, elevating capital barriers that protect incumbent positions while filtering out undercapitalized new entrants unable to absorb pre-operational testing timelines.
For Market Incumbents: Hedge against green bean price volatility through long-term offtake agreements with Colombian and Brazilian cooperatives. Consolidate roasting volumes across Tiong Bahru and Everton Park facilities to amortize NEA catalytic afterburner compliance costs. Channel R&D investment toward IoT-enabled precision profiling systems that differentiate cup consistency for corporate catering contracts in the Central Business District.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels to bypass wholesale margin compression and capture retail price realization. Target underpenetrated Joo Chiat and Katong heritage districts where Peranakan tourism intersects with specialty coffee demand. Deploy vendor-backed equipment financing to minimize upfront capital commitment while NEA certification timelines extend time-to-revenue.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to regional foodservice conglomerates seeking Singapore roasting capacity for ASEAN market access. Long-term viability favors vertically integrated operators with captive green bean sourcing and retail channel control. Monitor Enterprise Singapore productivity grant disbursement rates as inflection indicator for automation adoption velocity among independent micro-roasteries.
| Strategic Initiative | Industry Significance |
|---|---|
| NEA Emissions Compliance Upgrade | Catalytic afterburner installation satisfies National Environment Agency mandates while filtering out undercapitalized competitors. |
| Direct-to-Consumer Channel Launch | Subscription platforms bypass wholesale intermediaries and capture retail margins from affluent Central Business District households. |
| Precision Profiling Technology Adoption | IoT sensor arrays with machine learning roast curve optimization differentiate cup consistency for corporate catering contracts. |
| Green Bean Sourcing Integration | Backward integration into Brazilian and Colombian cooperatives insulates margin buffers against Arabica futures volatility. |
| Enterprise Singapore Grant Utilization | Productivity subsidies lower effective equipment costs for automation upgrades in designated Jurong industrial zones. |
Research Methodology
Multi-period observation of NEA compliance timelines, Enterprise Singapore grant disbursement patterns, and heritage district café formation rates anchored the trend analysis, supplemented by interviews with roasting equipment manufacturers, independent café operators, green bean importers, and hotel foodservice procurement directors. Secondary validation drew from National Environment Agency regulatory filings, Singapore Food Agency hygiene protocols, Enterprise Singapore productivity scheme documentation, and customs import records for thermal processing equipment. Bottom-up equipment procurement tracking across Tiong Bahru, Everton Park, and Central Business District clusters triangulated against top-down market size estimates.
Segment-weighting across roast profile tiers, customer type specifications, and distribution channel economics structured the analytical framework across the projection horizon. Product type segmentation modeled medium, light, dark, and flavored roast categories against café, restaurant, household, and retailer customer archetypes. CAGRs derived from equipment replacement cycle compression under NEA mandates and direct-to-consumer subscription growth trajectories. Forecast inputs incorporated green bean futures volatility bands and Enterprise Singapore automation subsidy uptake rates.
Regulatory enforcement variance, Arabica supply disruption severity, and equipment import currency exposure are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Pods and Capsules Market
Coffee
US Coffee Machine Market
Coffee
Germany Coffee Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Global Portable Coffee Makers Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Mushroom Coffee Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Coffee Premixes Market
Coffee
Vietnam Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Decaffeinated Coffee Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Asia Pacific Coffee Market