
 Coffee Pods and Capsules Market | 2026-2036
Coffee Pods and Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Pods and Capsules Market Intelligence
Vietnam is narrowing its role as a robusta processing hub for pod-format coffee destined for European and North American markets. Nestlé SA leverages its Nespresso vertical network to control aluminum capsule supply from bean to retail shelf. Keurig Dr Pepper Inc anchors North American single-serve demand through licensed manufacturing partnerships with grocery and foodservice channels. Luigi Lavazza SpA competes on Italian espresso heritage, sustaining premium positioning in European hospitality segments.
Coffee pods and capsules are pre-portioned, sealed containers—typically 5–12 grams of ground coffee encased in plastic, aluminum, or compostable barriers—designed for pressure-brew extraction at 9–19 bar in compatible machines. Their primary purpose is to deliver consistent portion control, flavor preservation, and operational simplicity across home, office, and foodservice environments. Single serve pods occupy the largest volume share, while biodegradable material formats are gaining fastest as regulatory pressure on plastic waste intensifies across the EU and select US states. Aluminum capsules retain the strongest margin pools due to barrier performance and recyclability infrastructure, particularly in Nespresso-dominated European markets.
The EU Single-Use Plastics Directive and FDA food-contact material standards shape product compliance pathways, with EFSA migration limits governing aluminum-lining adhesives and plastic composition. BIS certification requirements in India and China's GB standards for food packaging are creating divergent testing regimes for exporters. Stakeholders must monitor how extended producer responsibility schemes in France, Germany, and Italy redefine cost structures and material specifications before committing to capacity investments or geographic expansion.
Market Dynamics
The EU Single-Use Plastics Directive is compressing plastic pod margins while accelerating aluminum and compostable material transitions, reshaping supply chain configurations across European manufacturing hubs.
Growth Catalysts
- Office Coffee Services:North American workplace beverage programs are standardizing pod-format equipment, embedding single-serve systems into corporate procurement contracts and facility management frameworks.
- Biodegradable Material Mandates:EFSA migration limits and extended producer responsibility schemes in France, Germany, and Italy are creating compliant product demand that commands shelf space premiums in retail channels.
- Pressure-Brew Machine Penetration:German households maintain Europe's highest pod-compatible appliance density, generating installed-base pull that sustains recurring capsule consumption and brand lock-in.
Market Restraints
- Aluminum Input Cost Volatility:Primary aluminum pricing fluctuations and energy-intensive smelting requirements compress capsule manufacturing margins, particularly for producers without captive metal supply.
- Supply Concentration in Vietnam:Robusta processing and green coffee sourcing cluster in Vietnamese export hubs, exposing pod-format roasters to logistics disruptions and quality variability in bean supply.
- Recyclability Infrastructure Gaps:Compostable barrier films require industrial composting facilities that remain scarce outside Nordic markets and select German municipalities, limiting material claims credibility.
Strategic Opportunities
- Underpenetrated Indian Households:BIS certification pathways and rising appliance ownership in urban centers create first-mover positioning for pod-compatible system entrants before market saturation.
- Foodservice Channel Innovation:Licensed manufacturing partnerships with hotel and restaurant chains enable branded capsule placement in European hospitality segments without dedicated equipment investment.
- Regulatory Tailwind from China's GB Standards:Stricter food-contact material specifications are elevating compliance costs for local producers, creating import windows for certified international suppliers.
Industry Challenges
- Adhesive Migration Testing Complexity:EFSA limits on aluminum-lining adhesives require extended laboratory validation timelines that delay new product launches and reformulation cycles.
- Capex Intensity for Compostable Lines:Biodegradable barrier film extrusion equipment and sealing technology upgrades demand capital commitments that strain mid-capacity manufacturers.
- Legacy Machine Compatibility Standards:Proprietary brewing chamber dimensions and piercing mechanisms fragment the installed base, forcing capsule producers to maintain multiple tooling configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Pods and Capsules Market |
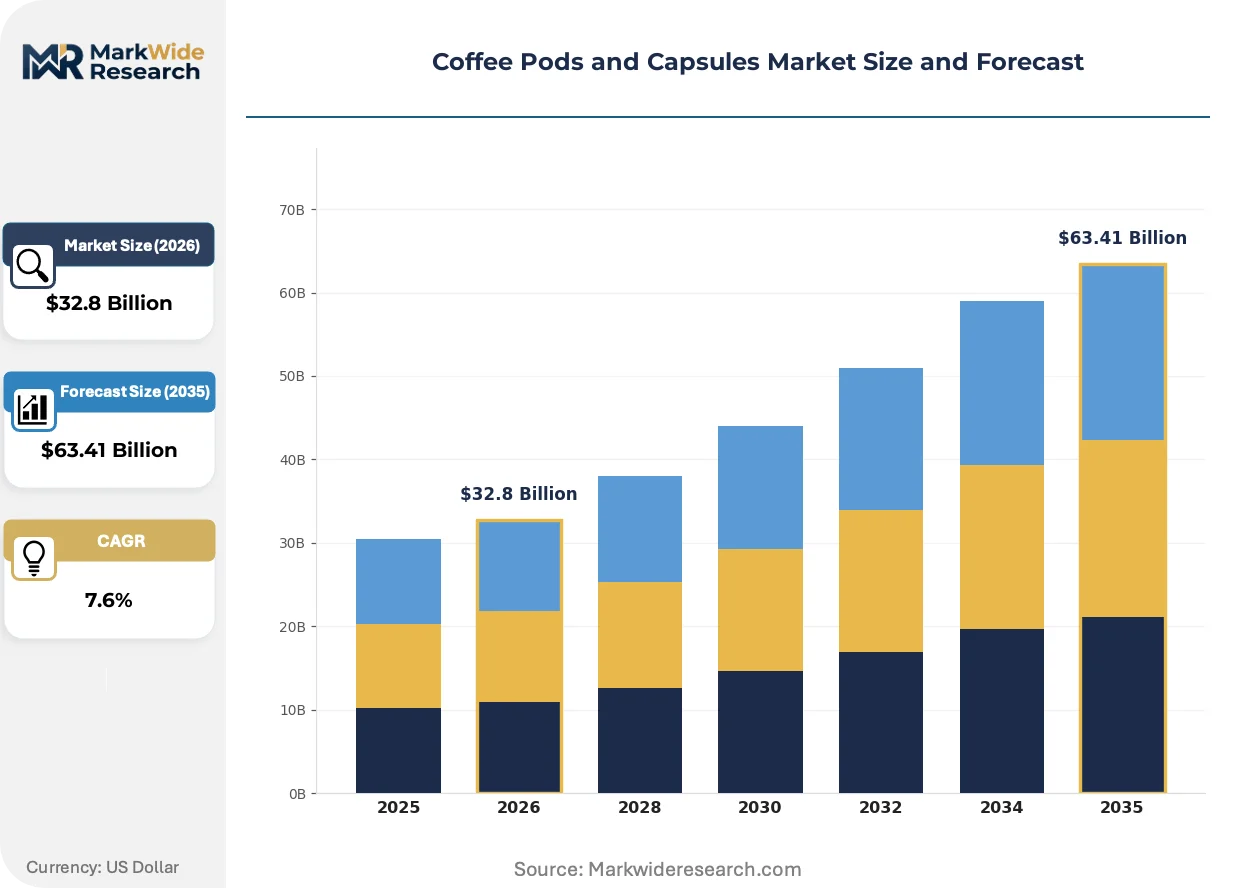
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $63.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Serve Pods, Capsules, Specialty Coffee Pods, Decaf Pods Material: Plastic, Aluminum, Biodegradable, Paper Flavor: Espresso, Light Roast, Dark Roast, Flavored Brand: Keurig, Nespresso, Starbucks, McCafe |
| Companies Covered | Starbucks Corporation, The J M Smucker Company, Keurig Dr Pepper Inc, illycaffè S.p.A, JAB Holding Company, Nestlé SA, The Kraft Heinz Company, Nestlé Nespresso SA, Luigi Lavazza SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Pods and Capsules Market Strategic Shifts & Innovations
Material science advances and extraction system intelligence are converging to redefine product performance claims, with sustainability credentials now functioning as primary purchase filters rather than secondary attributes.
Smart brewing systems equipped with RFID capsule recognition and programmable pressure profiling are digitizing the home extraction experience, enabling beverage customization previously confined to commercial espresso equipment. Premium household segments in Germany and Switzerland are adopting these connected machines at accelerated replacement cycles. This connectivity layer is digitizing consumption data capture, allowing roasters to optimize blend formulations and predict reorder intervals with precision unavailable in conventional retail channels.
REACH substance restrictions and the EU Green Deal's packaging waste targets are compelling aluminum capsule producers to document closed-loop recycling rates and reduce adhesive content in barrier laminates. Industrial consequence includes reformulation timelines extending 18-24 months for compliant product certification. The premium European hospitality segment is responding fastest, with hotel procurement specifications now requiring third-party verified recyclability documentation for in-room coffee programs.
Direct-to-subscriber replenishment models are displacing supermarket aisle purchasing among urban professionals in France and the United Kingdom, compressing traditional retail margin capture. Roasters with captive subscription platforms are capturing lifetime value through automated reorder algorithms and limited-edition release access. This channel rotation is most visible in Paris, London, and Berlin metropolitan zones where delivery density supports same-day fulfillment economics.
Coffee Pods and Capsules Market Segmentation
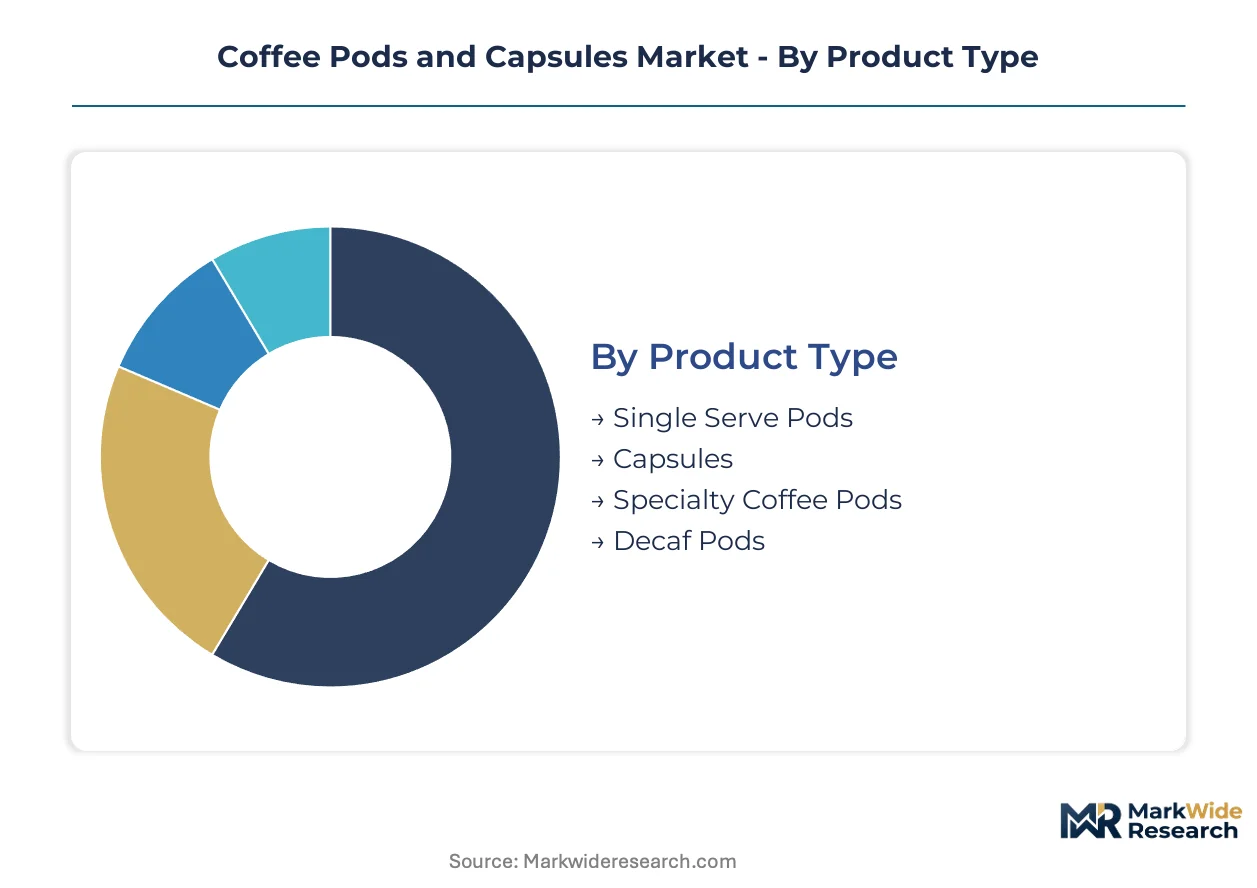
Segmentation in the coffee pods and capsules market reveals how material compliance costs, flavor preferences, and machine compatibility requirements fragment procurement patterns across home, office, and foodservice channels. Understanding these divisions exposes where margin pools concentrate and which product configurations face regulatory pressure.
Product Type:
Replacement cycles vary dramatically across formats, with daily-consumption households turning over inventory fastest while specialty and decaf variants move through pantries at substantially slower velocities.
- Single Serve Pods:Pre-portioned ground coffee sealed in plastic or paper filters, designed for drip-style extraction at low pressure. Demand concentrates in North American office coffee services and suburban households where Keurig-compatible machines dominate installed bases, driven by procurement contracts that standardize pod-format equipment across corporate facilities.
- Capsules:Aluminum or plastic shells engineered for 9-19 bar pressure extraction in pierced-brewing chamber systems. German and Swiss households sustain the densest penetration of capsule-compatible appliances in Europe, generating recurring consumption that locks users into proprietary format ecosystems.
- Specialty Coffee Pods:Single-origin or small-batch roasts in limited-release formats targeting enthusiast segments.
- Decaf Pods:Swiss water or CO2-decaffeinated coffee in standard pod geometries for caffeine-restricted consumption occasions.
Single Serve Pods anchors the volume base while Specialty Coffee Pods gains share at the steepest rate.
Material:
Cost structures diverge sharply across barrier technologies, with aluminum commanding premium shelf pricing and biodegradable films absorbing compliance-driven R&D overhead that plastic competitors avoid.
- Plastic:Polypropylene or polystyrene shells with multi-layer oxygen barriers, the legacy standard facing margin compression from EU Single-Use Plastics Directive compliance costs. French and Italian extended producer responsibility schemes are reallocating waste management fees toward plastic formats, accelerating demand migration toward alternatives.
- Aluminum:Rolled metal bodies with internal food-grade lacquer linings, prized for oxygen impermeability and established recycling infrastructure. Nespresso's closed-loop collection programs in Germany and Switzerland validate premium positioning through documented re-melt rates that satisfy hospitality procurement specifications.
- Biodegradable:PLA or cellulose-based barrier films requiring industrial composting infrastructure for valid end-of-life claims.
- Paper:Filter-based pods with compostable sealing layers, common in North American drip-format systems.
Plastic retains the widest installed-base compatibility while Biodegradable climbs the fastest as regulatory deadlines approach.
Flavor:
Application context drives flavor selection intensity, with foodservice channels demanding standardized espresso profiles while home experimentation expands roast variety experimentation.
- Espresso:Dark-roasted, finely ground blends optimized for high-pressure short extraction, the default specification for European hospitality in-room programs and Italian-format capsule systems. Paris and London hotel procurement teams now require third-party verified recyclability documentation alongside flavor consistency guarantees.
- Dark Roast:Extended Maillard reaction profiles emphasizing body and reduced acidity, preferred in North American office environments where bitterness signals coffee strength to casual consumers.
- Light Roast:Shorter roasting preserving origin characteristics and higher caffeine retention per bean.
- Flavored:Vanilla, hazelnut, or seasonal spice infusions targeting occasional drinkers and gift purchasing occasions.
Espresso dominates hospitality procurement specifications while Light Roast expands most quickly among home enthusiast segments.
Brand:
Customer type stratification separates licensed grocery distribution from captive ecosystem control, with direct-to-subscriber models displacing traditional retail margin capture in urban professional segments.
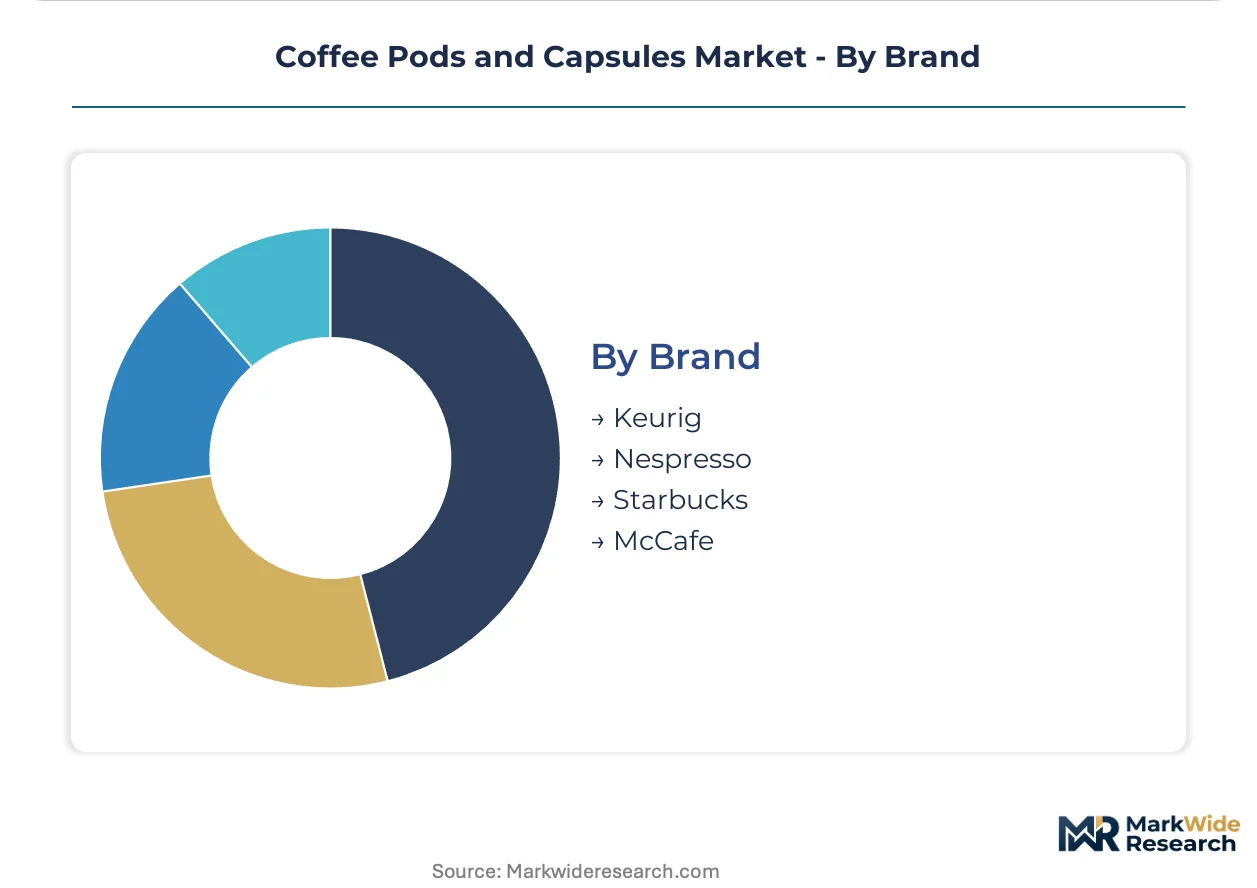
- Nespresso:Vertically controlled aluminum capsule ecosystem with proprietary brewing chamber geometry, sustained by boutique retail presence and direct replenishment platforms. Swiss and German metropolitan zones demonstrate highest subscription density, where same-day fulfillment economics support automated reorder algorithms.
- Keurig:Licensed K-Cup format enabling grocery and foodservice channel manufacturing partnerships without dedicated equipment investment.
- Starbucks:Branded capsule licensing leveraging roasted coffee recognition in retail and hospitality placement.
- McCafe:Quick-service restaurant brand extension targeting value-oriented household and office segments.
Nespresso captures the steepest lifetime value per subscriber while Keurig sustains the broadest format licensing footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary European entry point for green coffee destined for pod-format processing, while Vietnam's Cai Mep deepwater terminals anchor robusta export flows to North American and European roasting facilities.
United States
Office coffee service contracts and workplace beverage procurement programs drive single-serve pod consumption across corporate campuses and healthcare facilities. FDA food-contact material standards govern plastic and aluminum barrier compositions, with migration testing requirements extending product development timelines. Seattle and Chicago metropolitan clusters concentrate licensed manufacturing partnerships between pod-format roasters and foodservice distributors.
Germany
Household penetration of pressure-brew capsule machines remains the densest in Europe, generating recurring demand that locks consumers into proprietary format ecosystems. Extended producer responsibility schemes under the EU Single-Use Plastics Directive reallocate waste management fees toward plastic formats, accelerating aluminum and biodegradable transitions. The Hamburg-Bremen industrial corridor hosts aluminum capsule re-melting facilities that validate closed-loop recycling claims for hospitality procurement specifications.
Vietnam
Robusta processing and green coffee sourcing cluster in export hubs serving pod-format roasters in Europe and North America. The country's national food safety regulator enforces pesticide residue limits that govern bean acceptance at European ports. Dak Lak Province and Ho Chi Minh City anchor wet-milling and export logistics infrastructure that supplies medium-roast blends for North American office coffee programs.
France
Direct-to-subscriber replenishment models displace supermarket purchasing among urban professionals in Paris and Lyon metropolitan zones. EFSA migration limits on aluminum-lining adhesives require extended laboratory validation that delays new product launches by roasters serving the hospitality segment. The Île-de-France region concentrates boutique roasting operations that supply limited-release specialty pods to subscription platforms.
India
Rising appliance ownership in Mumbai, Bangalore, and Delhi urban centers creates first-mover positioning for pod-compatible system entrants before market saturation. BIS certification requirements for food-contact materials create divergent testing regimes that elevate compliance costs for imported capsules. Karnataka's coffee-growing districts supply arabica beans that domestic roasters process into pod-format products for emerging premium household segments.
Coffee Pods and Capsules Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in green coffee sourcing and barrier material supply. The vendor base organizes around three strategic archetypes: vertically integrated roasters with captive capsule manufacturing, licensed-format producers supplying grocery and foodservice channels, and specialty roasting houses with direct subscription platforms. Capacity expansion in compostable barrier film extrusion and strategic partnerships for aluminum recycling infrastructure represent the dominant competitive moves as regulatory deadlines approach.
Among Swiss and Italian roasting houses with heritage positioning, Nestlé SA and Luigi Lavazza SpA exemplify divergent platform strategies—one through boutique retail presence and direct replenishment ecosystems, the other through licensed hospitality placement. Keurig Dr Pepper Inc occupies the North American licensed-format tier, enabling grocery channel manufacturing partnerships without dedicated equipment investment. These three anchors illustrate how geographic origin and corporate structure shape competitive archetype selection in a market where material compliance costs increasingly determine margin capture.
| Leading Market Players |
|---|
| Starbucks Corporation |
| The J M Smucker Company |
| Keurig Dr Pepper Inc |
| illycaffè S.p.A |
| JAB Holding Company |
| Nestlé SA |
| The Kraft Heinz Company |
| Nestlé Nespresso SA |
| Luigi Lavazza SpA |
| Others |
Cost & Logistics Intelligence
Dak Lak Province's wet-milling capacity expansions are compressing green coffee spot premiums for European and North American roasters, transferring margin downstream toward capsule-forming and barrier-lamination stages where aluminum and compostable material transitions command shelf-space premiums.
Pricing Analysis
Volume-discount tiering separates subscription-direct subscribers from grocery-aisle purchasers and foodservice contract buyers, with the former capturing per-capsule economics 15-25% below retail single-unit pricing. Price differentiation rests on material certification grade and brand heritage positioning, with EFSA-compliant aluminum formats sustaining premium placement against plastic alternatives. Pricing pressure stems from EU Single-Use Plastics Directive compliance costs accelerating through French and German extended producer responsibility schemes. Foodservice procurement teams exhibit highest price sensitivity due to standardized volume contracts, while direct-subscriber households demonstrate lowest sensitivity given automated replenishment convenience.
Supply Chain Analysis
Upstream green coffee feedstock draws from Vietnamese robusta clusters, Brazilian arabica belts, and Colombian specialty-grade highlands, creating origin-diversified sourcing that buffers against single-weather-event disruptions. Raw material dependencies center on aluminum coil stock for barrier performance, PLA resin for compostable transitions, and food-grade adhesive laminates for lining integrity. Supply chain risk concentrates in logistics chokepoints at Hamburg and Cai Mep container terminals where port congestion propagates through roasting schedules. Distribution runs through three-channel architecture: direct-to-subscriber platforms capturing lifetime value, licensed grocery manufacturing partnerships enabling broad shelf placement, and hospitality procurement specifications governing in-room coffee programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a switching-cost fortress where proprietary brewing chamber geometries and subscription-platform data assets create defensive moats that compound with each replacement machine sale.
For Market Incumbents: Pre-empt biodegradable material transitions by locking industrial composting partnerships in Nordic markets and select German municipalities before regulatory deadlines compress plastic-format margins. Secure captive aluminum supply through backward integration into European re-melting infrastructure, defending against primary metal price volatility that strains competitors without vertical control. Channel control through direct-subscriber platform density in Swiss and German metropolitan zones remains the priority lever against licensed-format grocery competitors. For New Entrants and Emerging Players: Build out BIS certification capabilities for Indian urban centers before appliance ownership saturation closes first-mover windows in Mumbai, Bangalore, and Delhi. Target underpenetrated Indian households through appliance-bundle pricing that subsidizes machine cost against recurring capsule margins, mirroring the German installed-base pull model. Foodservice channel innovation through licensed hotel partnerships offers lowest capital-intensity entry path without dedicated equipment manufacturing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated roasters with captive subscription platforms and proprietary format ecosystems, generating predictable cash flows across multi-year subscriber lifecycles. Long-term viability favors acquisition targets with compostable barrier film extrusion capabilities and established EFSA compliance documentation, as regulatory tailwinds from EU Green Deal packaging targets reshape material specifications. The signal to watch is industrial composting infrastructure buildout rates in France, Germany, and Italy, which determine whether biodegradable material claims achieve credible end-of-life validation.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Material Line Investment | EFSA compliance documentation and industrial composting partnerships secure shelf-space premiums ahead of EU Single-Use Plastics Directive deadlines. |
| Direct-to-Subscriber Platform Buildout | Automated replenishment algorithms in Paris, London, and Berlin capture lifetime value and displace traditional retail margin capture. |
| Aluminum Recycling Infrastructure Partnership | Hamburg-Bremen re-melting facility access validates closed-loop claims for hospitality procurement specifications requiring third-party documentation. |
| BIS Certification Pathway Establishment | Indian food-contact material compliance creates import windows before domestic producers achieve cost-competitive certification. |
| Smart Brewing System Integration | RFID capsule recognition and pressure profiling digitization enables beverage customization previously confined to commercial espresso equipment. |
Research Approach
A spread of perspectives from roasting operations directors, hospitality procurement managers, barrier material R&D leads, and subscription platform executives converged on the working assumptions governing consumption velocity and format transition timelines. Primary interview intelligence combined with secondary validation from customs trade records, EFSA migration limit documentation, SEC 10-K filings by licensed manufacturers, and Nielsen retail audit data. Bottom-up machine installed-base modeling and top-down green coffee flow analysis triangulated on segment-level consumption estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning material compliance tier, brewing pressure format, channel architecture, and regional regulatory cluster. CAGRs derived from replacement cycle dynamics, household appliance penetration curves, and foodservice contract renewal patterns. Industry-specific forecast inputs included EU Single-Use Plastics Directive implementation schedules and BIS certification processing timelines for Indian market entry.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese producers with GB-standard compliance and cost-advantaged compostable lines would shift outcomes beyond modeled ranges. Cross-checking against EFSA pre-submission consultation outcomes and industrial composting facility permitting data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Instant Coffee Market
Coffee
Single Origin Coffee Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Organic Coffee Market
Coffee
US Instant Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Butter Coffee Market
Coffee
China Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
Specialty Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Freeze Dried Coffee Market
Coffee
North America Instant Coffee Market
Coffee
Sparkling Coffee Market
Coffee
Oceania Coffee Market