
 Encapsulated Caffeine Market | 2026-2036
Encapsulated Caffeine Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Caffeine Market Foresight
Multi-source encapsulation partnerships is realigning supply strategies across the value chain as brands seek to balance proprietary coating know-how with cost flexibility. Balchem Corporation leverages its integrated mineral and nutrient delivery platforms to sustain captive supply advantages in North American sports nutrition. Sensient Technologies Corporation competes through color-and-flavor integration with active encapsulation, extending its position in beverage-ready formats. Glatt GmbH anchors European demand through precision fluid bed equipment and contract manufacturing services that dominate pharmaceutical-grade caffeine processing.
Encapsulated caffeine refers to active caffeine molecules enclosed within protective matrices—commonly lipid, protein, or carbohydrate shells ranging from 10 to 1000 microns—to enable controlled release, mask bitterness, and shield against moisture-driven degradation during shelf storage. The primary commercial purpose centers on stabilizing caffeine in functional foods, dietary supplements, and ready-to-drink beverages where thermal processing and extended distribution cycles would otherwise degrade standard anhydrous caffeine. Powders occupy the largest volume position due to their compatibility with dry-blend supplement manufacturing and bulk ingredient handling, while gels represent the fastest-expanding structural category as beverage brands adopt liquid-filled capsule and stick-pack formats for on-the-go energy positioning. Sports nutrition applications command the deepest margin pools, with pre-workout and endurance segments driving premium pricing for time-release and pH-dependent coating technologies.
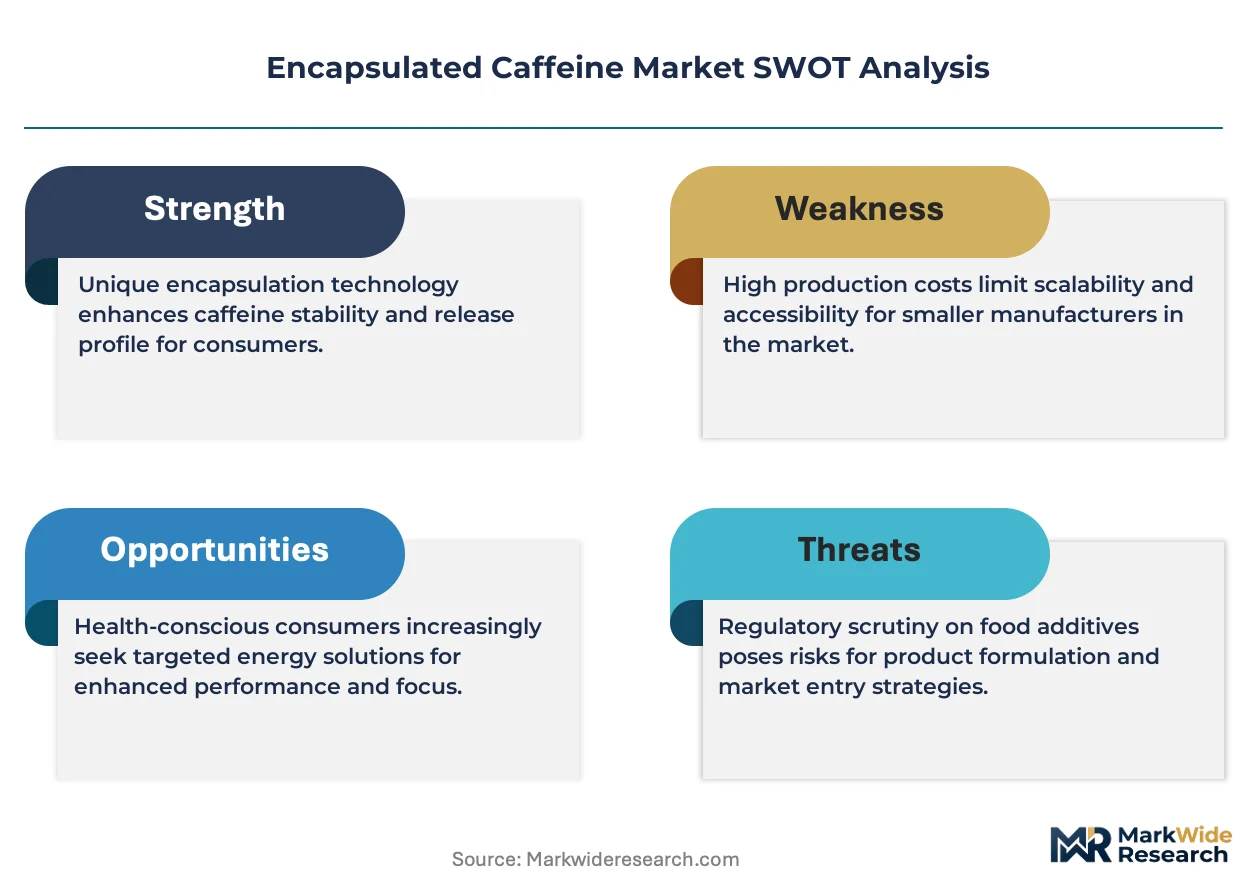
FDA GRAS notifications and DSHEA labeling requirements shape product development pathways and market access thresholds for encapsulated caffeine sold in U.S. dietary supplement channels. EFSA health claim evaluations and novel food assessments under EU Regulation 2015/2283 constrain rapid European commercialization, creating divergent compliance timelines across Atlantic markets. Stakeholders must monitor evolving caffeine maximum-level discussions at Codex Alimentarius and national regulator levels, as tightening exposure limits would force reformulation investments across energy supplement and weight management portfolios.
Market Dynamics
Fluid bed coating microencapsulation is compressing production costs while tightening particle-size uniformity, forcing contract manufacturers to retool equipment or lose sports nutrition contracts to precision-equipped rivals.
Growth Catalysts
- DSHEA Compliance Frameworks:FDA GRAS determinations for novel coating matrices accelerate product launches across U.S. dietary supplement channels, reducing time-to-shelf for new entrants.
- Pre-Workout Formulation Demand:Sports nutrition brands are procuring time-release encapsulated caffeine to differentiate endurance products from commodity anhydrous alternatives.
- Spray-Drying Advances:Continuous processing improvements in carbohydrate-shell microencapsulation are expanding batch throughput for beverage-ready powder formats.
Market Restraints
- Ethanol Price Volatility:Lipid-shell encapsulation depends on food-grade ethanol for solvent-based coating processes, exposing margin structures to agricultural commodity swings.
- Equipment Supplier Concentration:Precision fluid bed coating systems for pharmaceutical-grade particle engineering concentrate among German and Swiss equipment vendors, creating single-source vulnerabilities.
- Bitterness Masking Limitations:Protein-based matrices still permit residual caffeine astringency in high-dose applications above 200mg per serving, constraining clean-label positioning.
Strategic Opportunities
- Indian Functional Beverage Entry:FSSAI novel food approval pathways for encapsulated bioactives remain underutilized by international suppliers, creating first-mover potential in energy drink contract manufacturing.
- pH-Dependent Release Convergence:Combining enteric coating chemistry with sustained-release polymer matrices enables gastric-bypass-resistant formulations for weight management segments.
- Direct-to-Consumer Stick Packs:E-commerce subscription models for on-the-go energy gels bypass traditional retail slotting fees, capturing margin pools previously allocated to distributors.
Industry Challenges
- Microencapsulation Process Engineering Talent:The intersection of food science and pharmaceutical particle engineering creates acute hiring competition in regions with limited specialized training programs.
- Dual-Use Export Classification Complexity:Caffeine encapsulation equipment with pharmaceutical-grade precision triggers controlled-substance manufacturing licensing requirements in multiple jurisdictions, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Caffeine Market |
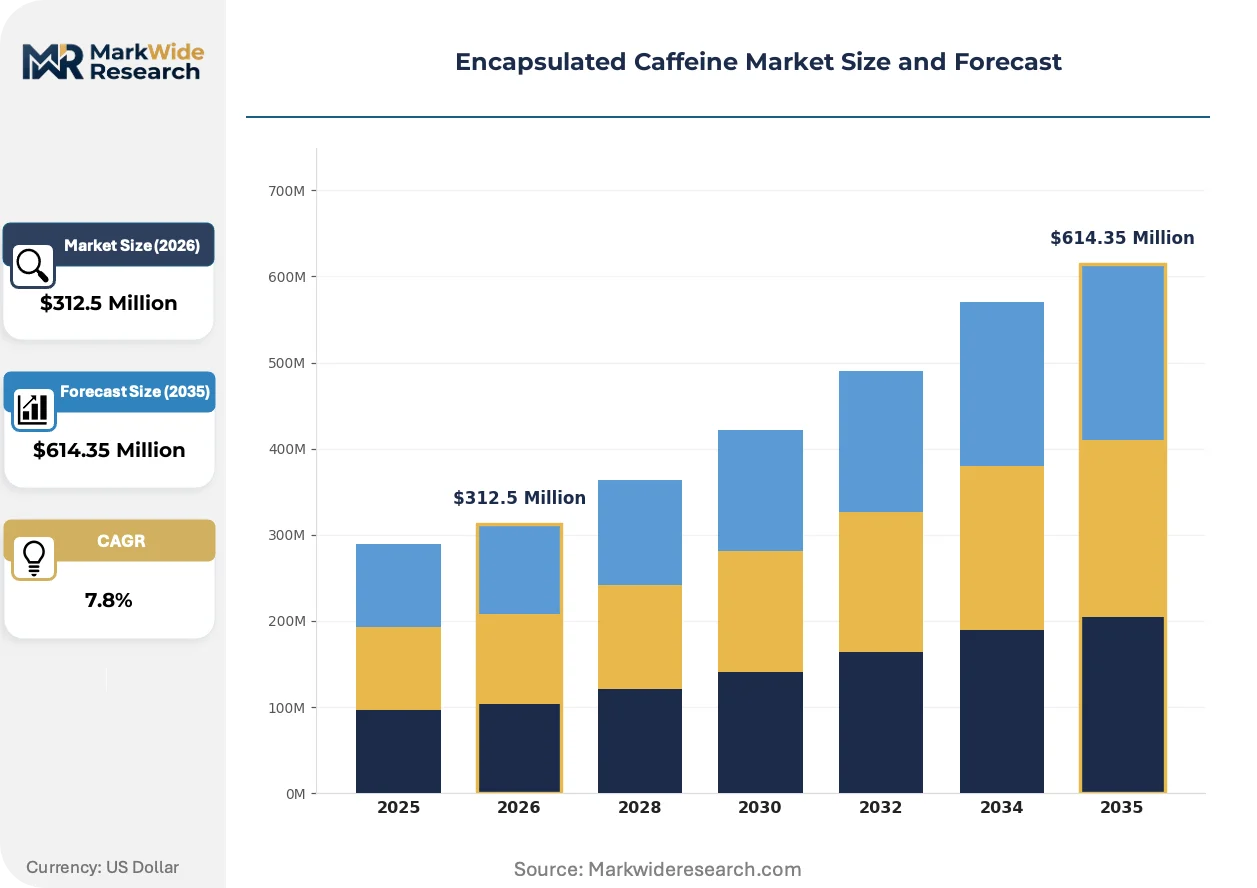
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powders, Gels, Capsules End User: Fitness Enthusiasts, Students, Professionals, Athletes Application: Energy Supplements, Weight Management, Cognitive Enhancement, Sports Nutrition Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Givaudan SA, Lycored, Balchem Corporation, Watson Inc, Firmenich SA, FrieslandCampina Ingredients, Sensient Technologies Corporation, Taste Tech, Glatt GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Caffeine Market Shifts & Advancements
Active coating automation and regulatory harmonization pressures are compressing equipment replacement cycles while fragmenting procurement authority between R&D and commercial teams.
Precision fluid bed coating systems with integrated real-time particle size analyzers are automating quality control checkpoints that previously required offline laboratory sampling. Contract manufacturers serving North American sports nutrition brands are adopting these integrated lines to meet lot-to-lot uniformity specifications. The technology is automating batch release decisions, reducing technician headcount per production shift while accelerating throughput.
EU Regulation 2015/2283 novel food assessments are extending commercialization timelines for new encapsulation matrices beyond the 18-month window typical for U.S. GRAS notifications. EFSA caffeine exposure limit discussions are forcing reformulation investments across energy supplement portfolios sold in member states. German and French regulators are tightening enforcement of maximum caffeine concentration thresholds in single-serve formats, compressing allowable dose ranges for pre-workout powders.
Ingredient buyer committees are consolidating procurement authority for encapsulated actives away from individual brand managers into centralized technical sourcing functions. Sports nutrition and functional beverage divisions within multinational food companies now share specifications for coating performance metrics, replacing siloed purchasing. This concentration is most visible in U.S. coastal markets where portfolio companies operate integrated innovation campuses with shared pilot-scale encapsulation suites.
Encapsulated Caffeine Market Segmentation
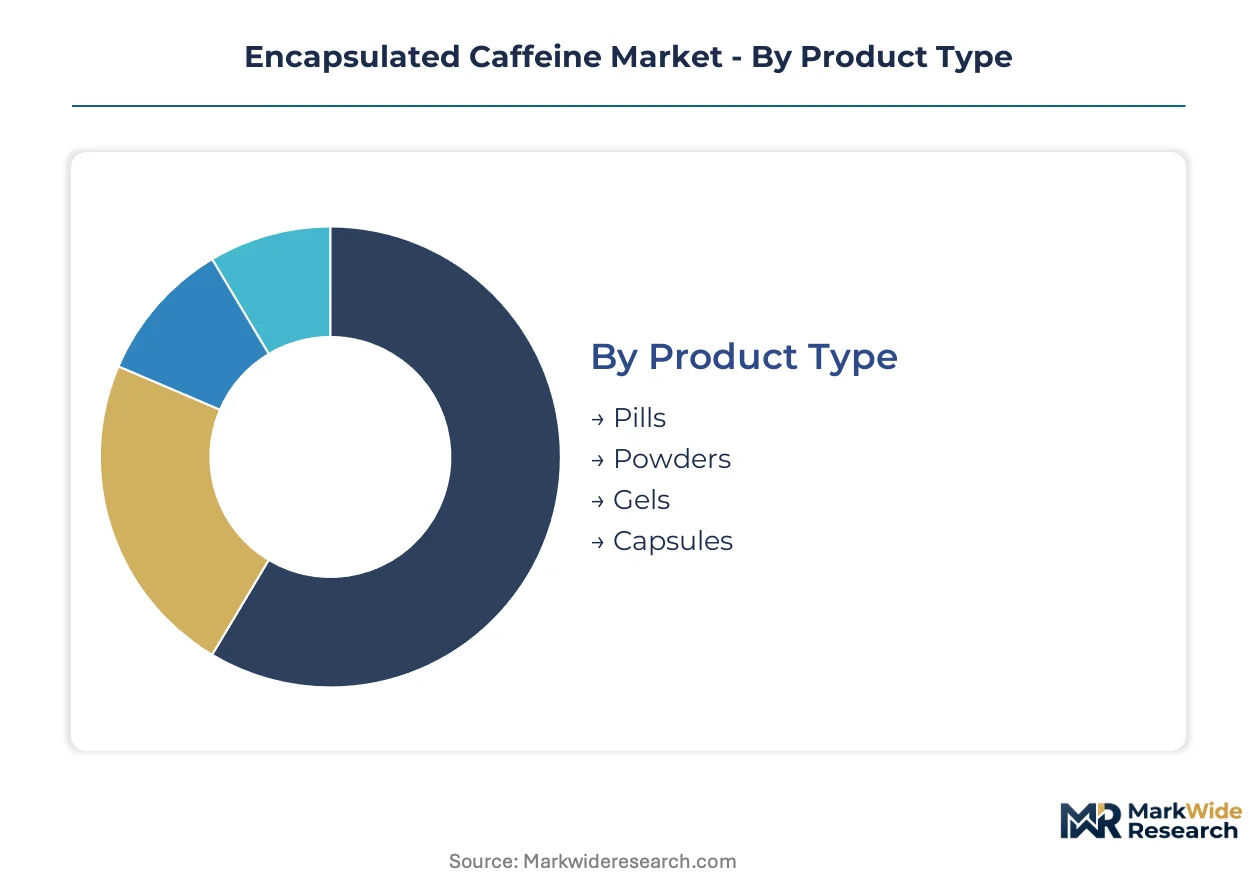
Encapsulated caffeine procurement patterns diverge sharply across delivery formats and consumption contexts. Manufacturers configure coating technologies and release profiles to match the shelf-stability demands and dosing protocols of each distinct user segment.
Product Type:
Supply concentration clusters around powder production infrastructure, with fluid bed coating lines and spray-drying towers representing the dominant capital deployment across contract manufacturers.
- Powders:Dry-blend formulations dominate bulk ingredient procurement for sports nutrition brands and functional beverage premixes. Manufacturers favor carbohydrate-shell microencapsulation for thermal stability during pasteurization cycles. United States dietary supplement channels absorb the largest volume flows due to DSHEA-compliant labeling flexibility.
- Gels:Liquid-filled stick packs and squeeze formats enable precise single-serve dosing for on-the-go energy positioning. Beverage brands in coastal U.S. markets are accelerating gel format adoption to bypass powder dissolution limitations in cold-water applications.
- Pills:Compressed tablet formats with lipid-based coatings serve pharmaceutical-grade specifications for controlled-release caffeine delivery.
- Capsules:Hard-shell gelatin and HPMC variants accommodate dual-active formulations combining caffeine with amino acids or botanical extracts.
Powders absorb the bulk of installed capacity; gels are expanding most quickly.
End User:
Volume concentration tilts toward recreational fitness participants rather than elite competitors, reshaping dose standardization and flavor masking priorities across formulation labs.
- Fitness Enthusiasts:Recreational gym-goers purchasing through subscription e-commerce channels drive demand for mid-dose formats (100-200mg) with rapid onset profiles. These consumers prioritize convenience and taste masking over pharmaceutical-grade precision.
- Professionals:White-collar productivity seekers favor discreet, low-dose formats for workplace consumption without jitter-inducing peaks. Urban centers in the United States and Germany show concentrated demand for microencapsulated caffeine integrated into functional foods.
- Athletes:Collegiate and professional sports programs require batch-tested, banned-substance-free certification for all encapsulated inputs.
- Students:Price-sensitive demand concentrates in exam-period seasonal purchasing with tolerance for simpler coating matrices.
Fitness enthusiasts absorb the bulk of installed capacity; professionals are climbing the fastest.
Application:
Margin concentration pools in sports nutrition, where time-release coating premiums command substantial formulation markups over commodity caffeine alternatives.
- Sports Nutrition:Pre-workout and endurance formulations specify pH-dependent and sustained-release coatings to modulate caffeine absorption across training sessions. Brands procure these inputs through integrated innovation campuses with captive pilot-scale encapsulation suites.
- Weight Management:Thermogenic supplement stacks combine encapsulated caffeine with green tea catechins, requiring enteric coatings to protect actives from gastric degradation.
- Energy Supplements:Generic alertness products compete primarily on cost, limiting encapsulation sophistication to basic moisture barriers.
- Cognitive Enhancement:Nootropic formulations targeting mental acuity specify smaller particle sizes for rapid buccal absorption.
Sports nutrition absorbs the bulk of installed capacity; weight management is gaining share fastest.
Distribution Channel:
Procurement authority is migrating toward centralized technical sourcing functions, compressing supplier negotiation leverage for fragmented retail channels.
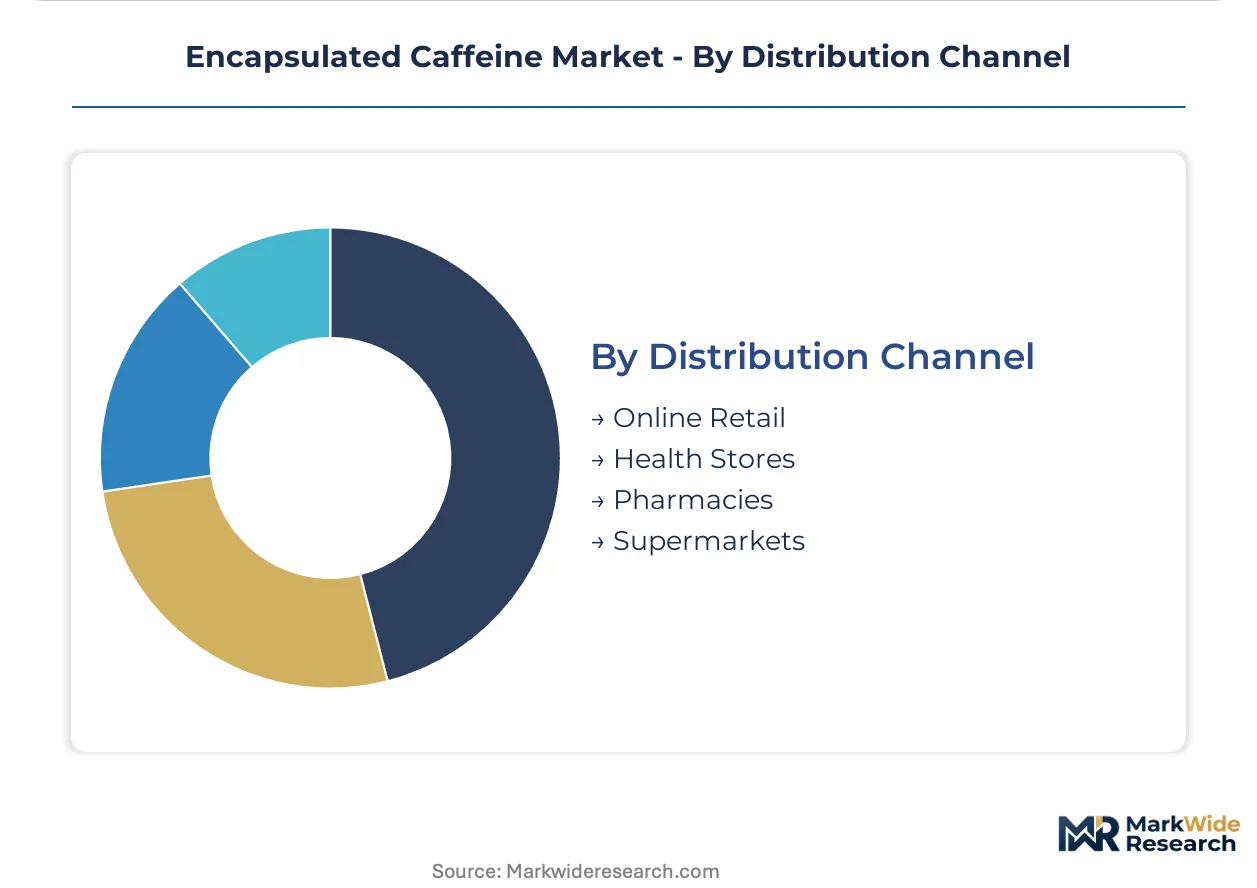
- Online Retail:Direct-to-consumer subscription models bypass traditional distributor markups and slotting fees, capturing margin pools for vertically integrated brands. Amazon and specialized sports nutrition e-commerce platforms concentrate demand in the United States and United Kingdom.
- Health Stores:Specialty retailers like GNC and Vitamin Shoppe maintain stringent quality certification requirements that favor established encapsulation suppliers with documented GRAS dossiers.
- Pharmacies:CVS and Walgreens chains impose pharmaceutical-grade documentation standards that exclude smaller contract manufacturers lacking validated quality systems.
- Supermarkets:Mass-market grocery placement demands economy pricing tiers with simplified coating specifications and higher batch-to-batch variability tolerance.
Online retail absorbs the bulk of installed capacity; pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caffeine raw material supply chains originate in tropical growing belts, yet value-added encapsulation concentrates in industrial clusters with pharmaceutical-grade processing infrastructure and permissive regulatory pathways for novel delivery formats.
United States
Sports nutrition brands in California and Florida drive procurement of time-release encapsulated caffeine for pre-workout portfolios. FDA GRAS notifications for novel coating matrices enable rapid product launches across dietary supplement channels. The New Jersey-Pennsylvania corridor hosts contract manufacturing clusters with integrated fluid bed coating lines serving national supplement distributors.
Germany
Precision equipment vendors in Baden-Württemberg and North Rhine-Westphalia supply fluid bed coating systems to pharmaceutical-grade caffeine processors across Europe. EFSA novel food assessments under EU Regulation 2015/2283 extend commercialization timelines for new encapsulation matrices. Frankfurt and Munich anchor demand from white-collar productivity seekers favoring microencapsulated caffeine in functional foods.
India
FSSAI novel food approval pathways for encapsulated bioactives remain underutilized by international suppliers, creating first-mover potential in energy drink contract manufacturing. Maharashtra and Karnataka host emerging functional beverage formulation labs serving domestic and export markets. Bangalore's innovation ecosystem attracts sports nutrition brands testing pH-dependent release formats for tropical climate stability.
China
Yangtze River Delta and Pearl River Delta manufacturing bases supply carbohydrate-shell microencapsulation for beverage-ready powder formats. NMPA regulatory frameworks for novel food ingredients shape product development timelines for encapsulated actives. Shanghai and Shenzhen concentrate demand from e-commerce subscription brands targeting fitness enthusiasts with stick-pack energy gels.
Brazil
São Paulo and Rio de Janeiro anchor Latin American demand for mid-dose encapsulated caffeine formats in recreational fitness segments. ANVISA novel ingredient assessments create compliance thresholds for imported encapsulation technologies. The Southeast region's contract manufacturing infrastructure serves Argentine and Chilean markets through Mercosur trade integration.
Encapsulated Caffeine Market Competitive Landscape
Global majors compete with regional champions across equipment supply and contract manufacturing dimensions, producing a tiered structure where pharmaceutical-grade precision separates premium-tier suppliers from commodity processors. The vendor base spans integrated flavor houses, captive mineral delivery platforms, and specialized coating technology licensors. Three archetypes dominate: integrated nutrient delivery conglomerates, precision equipment vendors with manufacturing services, and flavor-color-active integration specialists. Competitive moves concentrate on strategic partnerships for coating know-how and geographic expansion into underpenetrated functional beverage markets.
Among integrated delivery platforms, Balchem Corporation and FrieslandCampina Ingredients exemplify the captive supply archetype, leveraging backward integration into mineral and dairy protein matrices to control input costs. Sensient Technologies Corporation occupies a position bridging color-flavor integration with active encapsulation, serving beverage-ready format demand. Glatt GmbH represents the precision equipment-to-services model, anchoring European pharmaceutical-grade caffeine processing through fluid bed technology licensing and contract manufacturing.
| Leading Market Players |
|---|
| Givaudan SA |
| Lycored |
| Balchem Corporation |
| Watson Inc |
| Firmenich SA |
| FrieslandCampina Ingredients |
| Sensient Technologies Corporation |
| Taste Tech |
| Glatt GmbH |
| Others |
Supply & Pricing Matrix
Procurement consolidation among North American sports nutrition brands is compressing supplier margins and forcing contract manufacturers to absorb coating technology investments or cede volume to integrated rivals with captive fluid bed capacity.
Pricing Analysis
Service bundling separates pharmaceutical-grade documentation from commodity coating tiers, with validation packages and batch certification commanding substantial premiums over bare ingredient supply. Three-tier pricing structure across premium, standard, and economy levels reflects coating complexity, particle-size uniformity guarantees, and regulatory dossier completeness. Cost compression in economy tiers is intensifying because carbohydrate-shell processors in China and India are expanding spray-drying capacity. Fitness enthusiasts purchasing through e-commerce channels exhibit highest price sensitivity, while collegiate athletic programs accepting banned-substance certification requirements show lowest.
Supply Chain Analysis
Workforce scarcity in Baden-Württemberg and North Rhine-Westphalia is constraining expansion of precision fluid bed coating operations despite equipment availability from German vendors. Manufacturing concentrates in the United States, Germany, and China, with each hub serving distinct regulatory compliance tiers. Raw material supply draws from Brazilian and Vietnamese coffee growing belts for caffeine extraction, food-grade ethanol from agricultural processors for lipid-shell coating, and specialized polymers from petrochemical suppliers for enteric matrices. Single-source vulnerability concentrates in precision particle engineering equipment where Swiss and German vendors dominate pharmaceutical-grade specifications. Distribution runs through contract manufacturing networks rather than merchant ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid bed coating equipment lead times extending beyond standard procurement cycles are propping pricing premiums for manufacturers with installed precision capacity.
For Market Incumbents: Acquire captive pilot-scale encapsulation suites at integrated innovation campuses to defend against emerging contract manufacturers offering integrated R&D services. Consolidate procurement authority into centralized technical sourcing functions to extract volume discounts from coating suppliers. Prioritize backward integration into food-grade ethanol supply to hedge agricultural commodity volatility threatening lipid-shell margin structures. For New Entrants and Emerging Players: Enter via FSSAI novel food approval pathways for encapsulated bioactives in Indian energy drink contract manufacturing, where international supplier penetration remains shallow. Target pH-dependent release format development for tropical climate stability applications in Southeast Asian functional beverage markets. Pursue direct-to-consumer stick pack positioning through e-commerce subscription models to bypass retail slotting fees. For Investors and Strategic Acquirers: The window for entry favors precision equipment vendors with manufacturing service capabilities bridging pharmaceutical-grade specifications and food-grade scale. Long-term viability rests on coating technology licensors with demonstrated regulatory dossier success across FDA GRAS and EFSA novel food pathways. Watch EFSA caffeine exposure limit enforcement intensity as signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Matrix Supply | Captive supply of carbohydrate and lipid shell materials insulates margin structures from ethanol price volatility. |
| Precision Fluid Bed Equipment Deployment | Real-time particle size automation tightens lot-to-lot uniformity specifications demanded by sports nutrition brands. |
| pH-Dependent Release Format Development | Gastric-bypass-resistant formulations unlock weight management segment premium pricing pools. |
| FSSAI Novel Food Approval Pathway Investment | First-mover positioning in Indian functional beverage contract manufacturing captures underpenetrated demand. |
| Direct-to-Consumer Stick Pack Launch | E-commerce subscription models bypass distributor markups and capture margin pools in on-the-go energy positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with contract manufacturing executives, sports nutrition brand formulation directors, fluid bed equipment vendors, and FSSAI regulatory consultants. FDA GRAS notification databases, EFSA novel food assessment registers, and dietary supplement channel shipment records provided demand-side validation. Bottom-up modeling of coating technology deployment and top-down reconciliation against functional beverage production estimates triangulated market sizing.
Data-stream reconciliation across equipment installation records, raw material trade flows, and end-product formulation specifications enabled segmentation modeling. The analytical framework spans product type, end user archetype, application segment, and distribution channel across the projection horizon. CAGRs derived from capacity expansion announcements, patent filing trajectories, and brand procurement pattern shifts. Coating matrix innovation cycles and regulatory approval timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA caffeine exposure limit tightening or FSSAI approval pathway delays. Assumptions reflect sustained DSHEA compliance flexibility and continued GRAS notification velocity. Codex Alimentarius maximum-level discussions, ethanol price volatility spikes, and equipment supplier concentration disruptions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
India Coffee Roaster Market
Coffee
Portable Espresso Machines Market
Coffee
Nitrogenated Coffee Market
Coffee
Coffee Bottle Market
Coffee
Coffee Roaster Machine Market
Coffee
Global Cafe Market
Coffee
Coffee Concentrate Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
UK Coffee Roaster Market
Coffee
Singapore Coffee Roaster Market
Coffee
Butter Coffee Market
Coffee
US Instant Coffee Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Sparkling Coffee Market
Coffee
Reusable Coffee Cup Market