
 Germany Coffee Market | 2026-2036
Germany Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Coffee Market Analysis
Germany is tilting its roasting capacity toward specialty and certified-grade production to serve premium domestic consumption. Melitta Group leverages its vertically integrated filter and roasting operations to dominate the home-brewing segment. JJ Darboven GmbH & Co. KG anchors its position through sustained R&D intensity in sustainable sourcing protocols. Tchibo competes through direct-to-consumer subscription models and proprietary retail formats.
Coffee comprises roasted seeds of Coffea arabica and Coffea canephora, processed through wet or dry methods to achieve moisture content below 12% and flavor profiles ranging from acidic-fruit to chocolate-bitter, serving as a functional beverage and culinary ingredient across industrial and commercial channels. Ground coffee occupies the largest volume share in German retail, though specialty coffee records the fastest value expansion as consumers trade upward on provenance and processing transparency. The HoReCa sector channels disproportionate margin capture through espresso-based preparation formats and equipment-locked supply relationships.
The EU Deforestation Regulation and Germany's national implementation through the Federal Food and Agriculture Ministry tighten traceability mandates for imported green coffee, while the German Coffee Association enforces quality grading standards that filter market access for non-compliant traders. BfR guidelines on acrylamide and contaminant thresholds further constrain processing methodologies. Stakeholders must monitor enforcement timelines for EUDR due diligence obligations and calibrate sourcing portfolios accordingly.
Market Dynamics
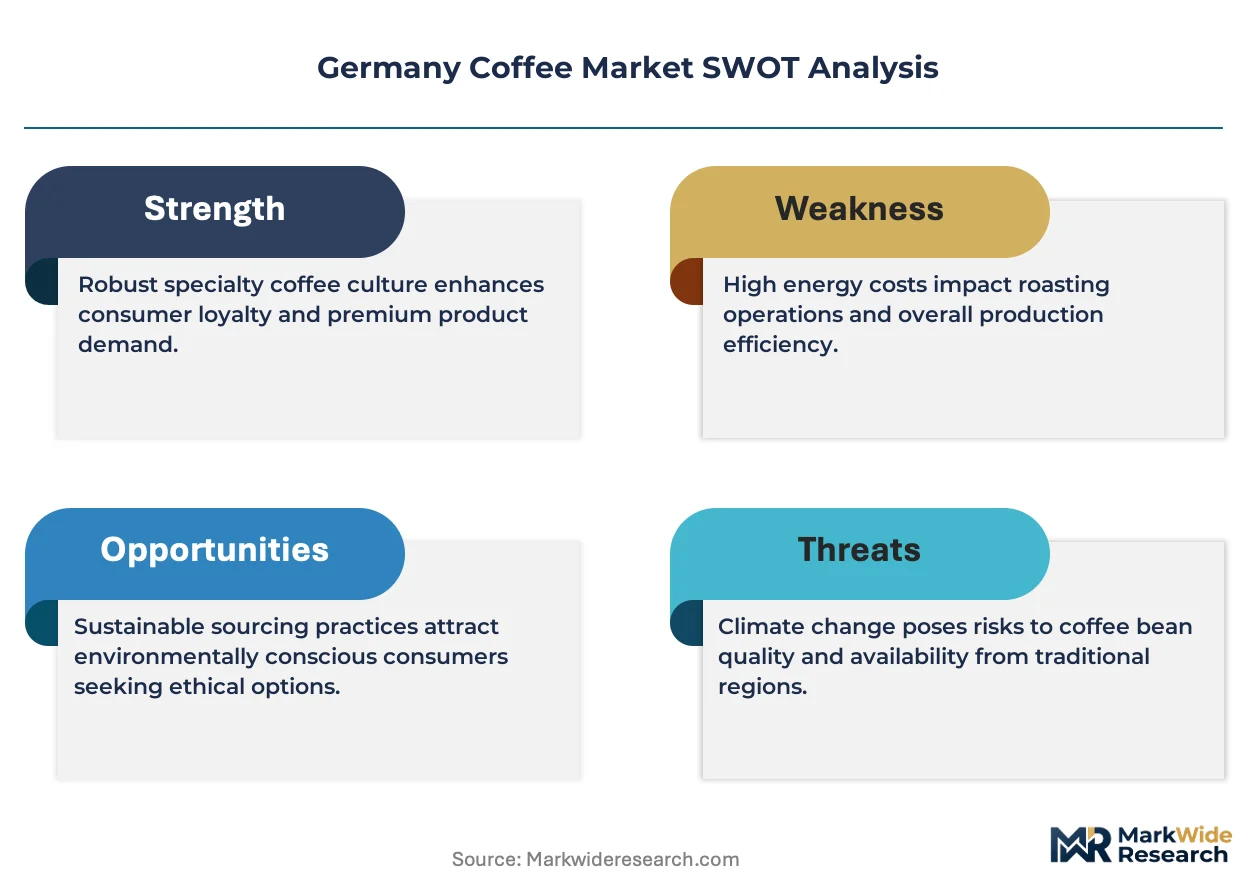
The EU Deforestation Regulation is forcing German roasters to reconfigure sourcing networks toward traceable supply chains, compressing procurement timelines while elevating compliance costs across the value chain.
Growth Catalysts
- Specialty HoReCa adoption:Berlin, Hamburg, and Munich operators are expanding single-origin espresso programs, pulling premium arabica volumes through certified channels.
- EUDR traceability mandates:The Federal Food and Agriculture Ministry's implementation timeline is accelerating investment in blockchain-enabled supply chain documentation systems.
- Home-brewing equipment penetration:Filter coffee preparation is displacing instant consumption in German households, sustaining ground coffee volume leadership.
Market Restraints
- Green coffee price volatility:Brazilian and Vietnamese arabica-robusta harvest fluctuations transmit directly to German roasting margins, compressing working capital flexibility.
- Acrylamide compliance thresholds:BfR guidelines on contaminant limits constrain dark-roast product development, forcing reformulation investments.
- Specialty sourcing concentration:Ethiopian and Colombian high-grade bean availability concentrates in limited auction windows, creating procurement bottlenecks.
Strategic Opportunities
- Direct trade micro-lots:Bavarian and Baden-Württemberg roasters are bypassing traditional importers to secure exclusive farmer relationships with transparent pricing.
- Subscription channel expansion:D2C platforms are capturing recurring revenue from urban professionals seeking curated origin rotations without retail friction.
- Carbon-neutral certification:EU Green Deal-aligned roasting facilities qualify for preferential HoReCa procurement criteria, creating differentiation leverage.
Industry Challenges
- Q-grader talent scarcity:Certified cupping specialists capable of evaluating micro-lot quality are concentrated in Hamburg and Berlin, constraining regional expansion.
- EUDR due diligence integration:Legacy ERP systems require costly retrofitting to capture geolocation and deforestation-risk data at farm level.
- Roaster-retailer margin compression:Equipment-locked supply agreements in the HoReCa channel limit pricing autonomy for independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Coffee Market |
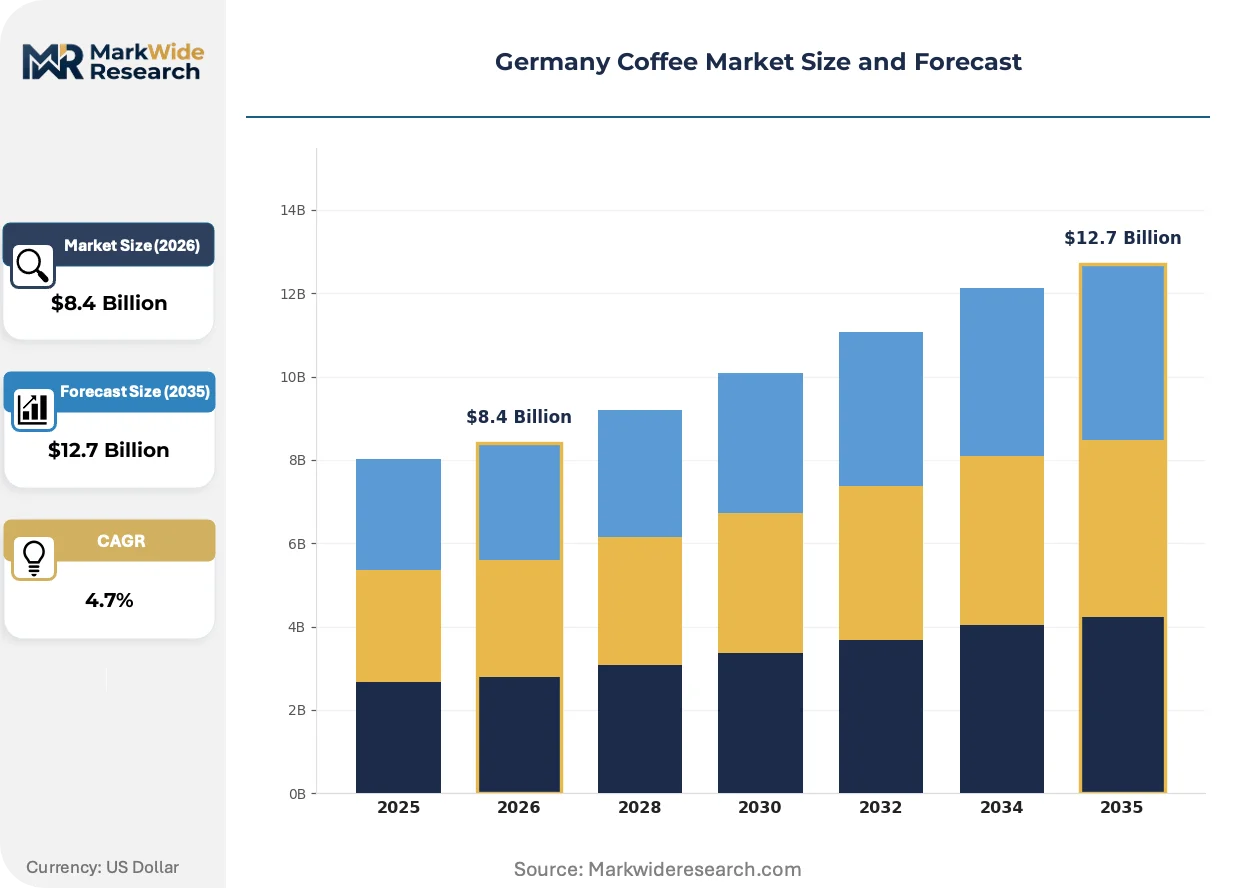
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Bean, Ground Coffee, Instant Coffee, Specialty Coffee Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Coffee Shops Consumer Type: Home Users, Office Users, HoReCa Sector, Retail Customers Packaging Type: Bagged, Canned, Bottled, Pods |
| Companies Covered | Melitta Group, JJ Darboven GmbH & Co. KG, Tchibo, Jab Holding Company, Alois Dallmayr KG, Nestle SA, Luigi Lavazza SpA, Kruger GmbH & Co. KG, JDE Peet's, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Coffee Market Emerging Trajectories
Processing transparency and provenance verification are reshaping competitive positioning in German coffee, with technology convergence and regulatory pressure driving capital allocation toward traceability infrastructure.
Blockchain-enabled supply chain documentation is hybridizing traditional paper-based certification with real-time farm-to-roaster tracking. Medium-sized Hamburg and Berlin roasters are piloting these systems ahead of EUDR enforcement deadlines. The technology is compressing audit cycles from months to days while elevating consumer-facing storytelling capabilities.
The EU Deforestation Regulation's due diligence obligations are mandating geolocation capture for every batch of imported green coffee. German importers must now maintain satellite-verified farm boundary records and risk assessment documentation. Smallholder-dependent origins face the steepest compliance burden, accelerating consolidation toward estate-sourced volumes.
HoReCa procurement is gravitating toward fixed-origin contracts with multi-year price locks, displacing spot-market purchasing for core espresso blends. Munich and Frankfurt hotel chains are leading this shift, seeking supply predictability amid currency and harvest volatility. The model transfers price risk upstream while locking roasters into volume commitments.
Germany Coffee Market Segmentation
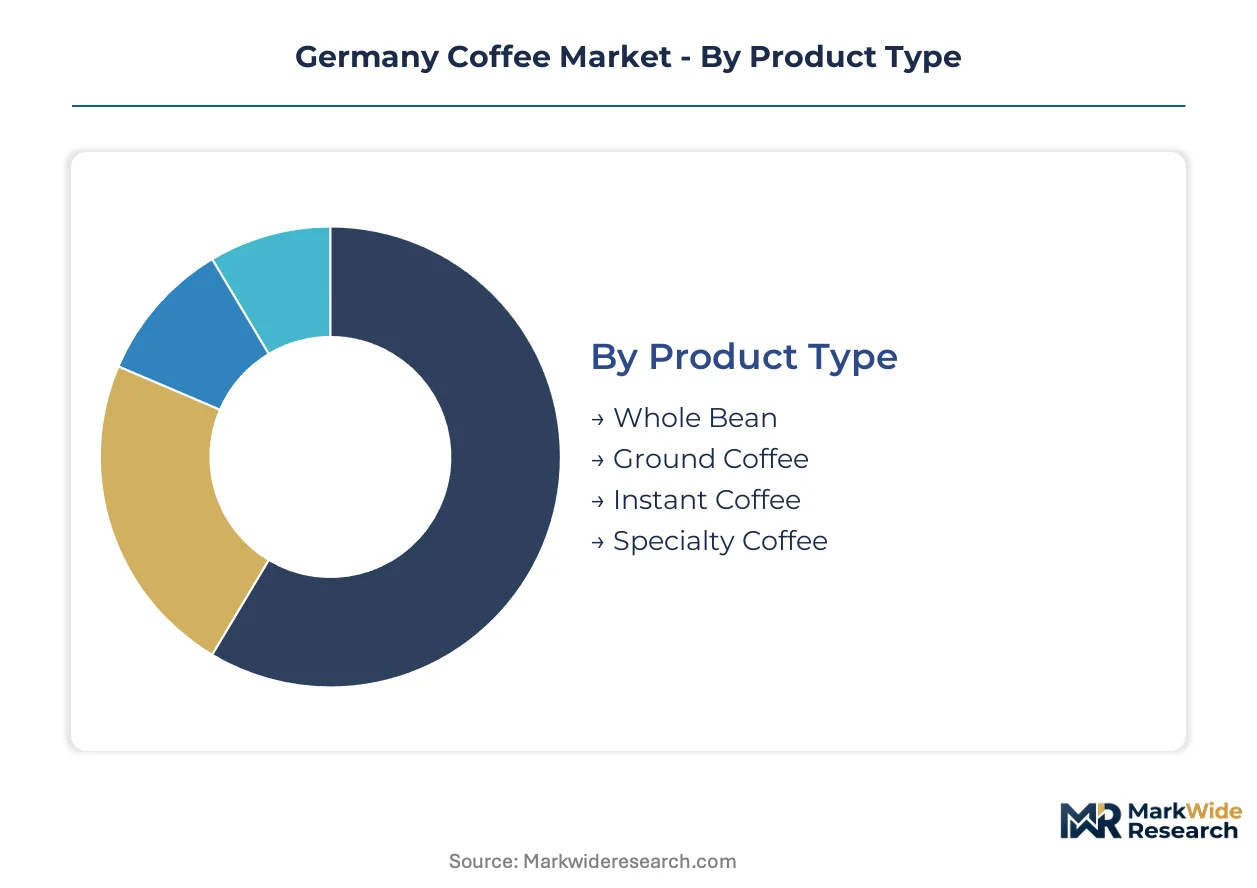
German coffee segmentation reflects divergent preparation rituals across household, workplace, and hospitality environments. Each dimension captures distinct margin structures and loyalty patterns that shape manufacturer portfolio strategy.
Product Type:
The use-case spectrum spans ritualistic home brewing to convenience-driven consumption, with preparation method dictating bean specification and roast profile.
- Ground Coffee:Medium-to-coarse particle size optimized for filter and French press extraction dominates German household consumption. Melitta Group's vertical integration into filter equipment locks in recurring ground coffee demand across Bavaria and North Rhine-Westphalia.
- Specialty Coffee:Single-origin arabica with traceable provenance and processing transparency commands premium positioning in Berlin and Hamburg independent cafés. HoReCa operators leverage rotating micro-lot programs to differentiate espresso-based menus amid intense metropolitan competition.
- Whole Bean:Unprocessed roasted seeds requiring consumer-operated grinding equipment appeal to enthusiast segments seeking freshness control.
- Instant Coffee:Spray-dried or freeze-dried soluble granules serve convenience-oriented office and travel contexts with minimal preparation infrastructure.
Established volume favors Ground Coffee; emerging adoption favors Specialty Coffee.
Distribution Channel:
Channel economics stratify by customer acquisition cost and inventory velocity, with digital platforms disrupting traditional grocery dominance.
- Supermarkets:Mass-market retail chains aggregate household staple purchases with high-frequency replenishment cycles. EDEKA and REWE leverage private-label roasting contracts to capture price-sensitive volume across suburban and rural postcodes.
- Online Retail:Direct-to-consumer platforms bypass retail margin stacking through subscription-based replenishment models. Tchibo's digital infrastructure captures recurring revenue from urban professionals seeking curated origin rotations without physical store friction.
- Specialty Stores:Independent roaster-retailers in Munich and Frankfurt offer cupping experiences and equipment consultation alongside bean sales.
- Coffee Shops:On-premise consumption venues integrate retail bean sales with beverage service to extend customer lifetime value.
Supermarkets retain volume leadership; Online Retail climbs the fastest in subscriber acquisition.
Consumer Type:
End-user environments dictate equipment investment, consumption frequency, and quality sensitivity thresholds.
- HoReCa Sector:Hotels, restaurants, and cafés deploy professional espresso equipment with locked-in supply agreements and technical service dependencies. Munich hotel chains negotiate multi-year fixed-origin contracts to secure supply predictability amid currency volatility.
- Home Users:Residential consumers balance convenience against preparation ritual, with filter equipment penetration sustaining ground coffee demand across German households.
- Office Users:Workplace coffee services prioritize speed and standardization through automated brewing systems and portion-controlled formats.
- Retail Customers:Gift purchasers and occasional buyers drive seasonal volume spikes through premium packaged offerings.
HoReCa commands margin concentration; Home Users anchor absolute volume.
Packaging Type:
Format selection balances shelf-life extension, portion precision, and environmental compliance against unit economics.
- Pods:Single-serve aluminum or compostable capsules deliver consistent extraction with minimal user skill. Nespresso-compatible systems penetrate German households seeking café-quality espresso without equipment complexity.
- Bagged:Flexible laminate pouches with degassing valves preserve aromatics for whole bean and ground formats across retail shelves.
- Canned:Metal containers with inert gas flushing extend shelf stability for instant coffee in ambient storage conditions.
- Bottled:Ready-to-drink cold brew and iced coffee formats serve immediate consumption occasions through convenience retail.
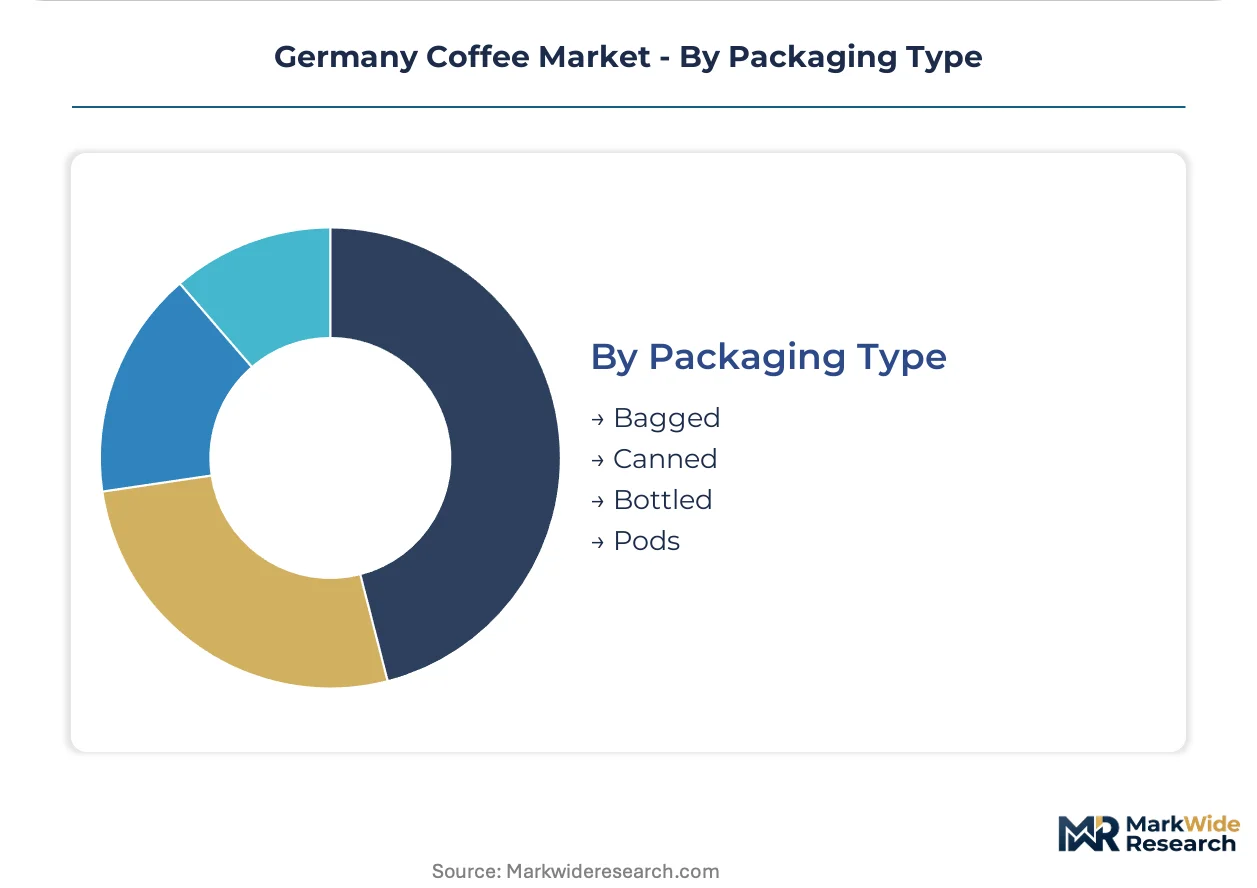
Bagged formats dominate roast-and-ground volume; Pods gain share fastest in household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Roasting capacity clusters in Germany's southern and western industrial corridors, with green coffee import infrastructure concentrating at Hamburg and Bremen ports. Bavarian and Baden-Württemberg processors dominate specialty-grade output, while North Rhine-Westphalia anchors mass-market production volumes.
North Rhine-Westphalia
HoReCa procurement from Düsseldorf and Cologne hotel chains drives demand for espresso-compatible blends. The Federal Food and Agriculture Ministry enforces EUDR traceability protocols through regional customs checkpoints. Roasting facilities in the Ruhr industrial zone retrofit legacy equipment to meet BfR acrylamide thresholds.
Bavaria
Munich's café density sustains specialty micro-lot consumption among affluent demographics. State-level environmental regulations align with EU Green Deal carbon-neutral facility standards. Nuremberg-based equipment manufacturers supply precision grinders to regional roasters expanding single-origin programs.
Baden-Württemberg
Stuttgart's automotive workforce generates consistent office-coffee service demand. The state's energy transition policies incentivize renewable-powered roasting operations. Freiburg im Breisgau hosts cupping laboratories certifying Q-grader talent for southwestern roasters.
Hamburg
Port infrastructure handles the majority of German green coffee imports from Brazilian and Vietnamese origins. Customs authorities pilot blockchain-enabled documentation systems ahead of EUDR enforcement deadlines. Speicherstadt warehouse districts concentrate independent roasting operations serving northern HoReCa networks.
Berlin-Brandenburg
Third-wave café culture in Kreuzberg and Neukölln accelerates direct-trade sourcing from Ethiopian and Colombian origins. Municipal waste regulations mandate compostable packaging for single-serve formats. Potsdam logistics hubs distribute subscription-model coffee to eastern German households.
Germany Coffee Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The German coffee market structures around vertically integrated roasting groups, mid-scale specialty operators, and multinational beverage conglomerates. Three archetypes dominate: equipment-locked ecosystem builders, direct-trade sourcing specialists, and mass-market distribution optimizers. Competitive moves center on subscription channel expansion and EUDR-compliant supply chain retrofitting.
Among Germany-based integrated groups, Melitta Group exemplifies the equipment-coffee bundling archetype through its filter manufacturing heritage. JJ Darboven GmbH & Co. KG occupies a position within the mid-tier roasting specialist segment, while Tchibo anchors the direct-to-consumer subscription tier. These three entities collectively represent the strategic diversity spanning industrial scale, sourcing transparency, and digital channel innovation in the domestic market.
| Leading Market Players |
|---|
| Melitta Group |
| JJ Darboven GmbH & Co. KG |
| Tchibo |
| Jab Holding Company |
| Alois Dallmayr KG |
| Nestle SA |
| Luigi Lavazza SpA |
| Kruger GmbH & Co. KG |
| JDE Peet's |
| Others |
Supply Flow & Price Mechanics
Brazilian and Vietnamese arabica-robusta harvest fluctuations concentrate upstream pricing power in Hamburg import houses, compressing roasting margins while elevating margin capture for traceability-certified specialty tiers downstream.
Pricing Analysis
The EU Deforestation Regulation dictates the pricing tier structure across German coffee, separating EUDR-compliant certified lots from conventional volumes through documentation cost pass-through. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and provenance transparency, with specialty micro-lots commanding substantial premia over commodity-grade blends. Cost compression in mass-market ground coffee is intensifying because supermarket private-label contracts limit pricing autonomy. HoReCa buyers exhibit the least price sensitivity due to equipment-locked supply agreements, while suburban household segments drive volume through promotional responsiveness.
Supply Chain Analysis
The EU Deforestation Regulation's geolocation capture requirements function as export-control-style documentation limits on smallholder-dependent origins, redirecting German import flows toward estate-sourced volumes with verifiable farm boundaries. Green coffee supply concentrates in Brazil, Vietnam, and Colombia, with German roasting capacity drawing from Hamburg and Bremen port infrastructure. Arabica and robusta bean dependencies, alongside jute bag and container logistics, rest on maritime shipping schedules through the Suez route. Single-source vulnerability concentrates in Ethiopian high-grade auction windows. Distribution runs through vertically integrated roasting groups, specialty importer-roasters, and multinational beverage conglomerates serving distinct channel tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified Q-grader cupping specialists are concentrated in Hamburg and Berlin, constraining regional specialty expansion and creating acquisition premiums for roasters with in-house evaluation capabilities.
For Market Incumbents: Entrench market position by securing multi-year fixed-origin contracts with Ethiopian and Colombian estate suppliers before EUDR enforcement tightens available certified volumes. Invest in blockchain-enabled traceability infrastructure to satisfy Federal Food and Agriculture Ministry documentation mandates and differentiate from competitors reliant on paper-based certification. Melitta Group's filter equipment bundling demonstrates how channel control limits substitution risk from emerging D2C entrants. For New Entrants and Emerging Players: Eastern German metropolitan zones outside Berlin present the most penetrable white-space for subscription-model specialty coffee, with Potsdam logistics hubs enabling efficient last-mile distribution without Hamburg-Berlin rent premiums. Target office-coffee service contracts in Baden-Württemberg automotive corridors where standardization requirements favor new automated brewing system suppliers over entrenched equipment-locked incumbents. Direct-trade micro-lot sourcing from bypassed importer networks offers transparent pricing storytelling for urban professional segments. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale roasting specialists with established EUDR-compliant sourcing protocols and existing Q-grader talent benches, as regulatory compliance costs will accelerate consolidation toward documented supply chain capabilities. The long-term viability window favors operators combining carbon-neutral facility certification with subscription channel infrastructure. Watch for inflection when Federal Food and Agriculture Ministry announces definitive EUDR enforcement timelines, which will trigger distressed divestitures from non-compliant import-dependent roasters.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | EUDR compliance compresses audit cycles from months to days while enabling consumer-facing origin storytelling. |
| Direct Trade Micro-Lot Sourcing | Bavarian and Baden-Württemberg roasters bypass traditional importers to secure exclusive farmer relationships with transparent pricing. |
| Carbon-Neutral Facility Certification | EU Green Deal-aligned roasting operations qualify for preferential HoReCa procurement criteria in Munich hotel chains. |
| Subscription Channel Expansion | D2C platforms capture recurring revenue from urban professionals seeking curated origin rotations without retail friction. |
| Q-Grader Talent Acquisition | Certified cupping specialists concentrated in Hamburg command premium compensation, constraining regional specialty expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from green coffee import managers, roasting operations directors, HoReCa procurement leads, and specialty café operators and refined through secondary validation against customs trade records, German Coffee Association quality grading protocols, BfR contaminant threshold documentation, and Federal Food and Agriculture Ministry EUDR implementation guidance. Bottom-up volume estimates from port import data and top-down consumption surveys were triangulated to establish market sizing.
Demand-supply balance dynamics across the analysis window were modeled through segmented projections spanning product type, distribution channel, consumer environment, and packaging format, with CAGRs derived from historical growth pattern extrapolation adjusted for regulatory inflection points. Green coffee price volatility indices, EUDR compliance cost assumptions, and HoReCa equipment penetration rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational beverage conglomerates acquiring German specialty roasters would shift outcomes through accelerated channel consolidation. Material shifts in Brazilian harvest yields or EUDR enforcement timeline delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Australia Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
North America Specialty Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
Green Coffee Extract Market
Coffee
Out-Of-Home Coffee Market
Coffee
Espresso Tamper Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
South America Coffee Market
Coffee
US Coffee Machine Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
South Korea Coffee Roaster Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Coffee Cherry Market