
 Food Texturing Agents Market | 2026-2036
Food Texturing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Food Texturing Agents Market Foresight
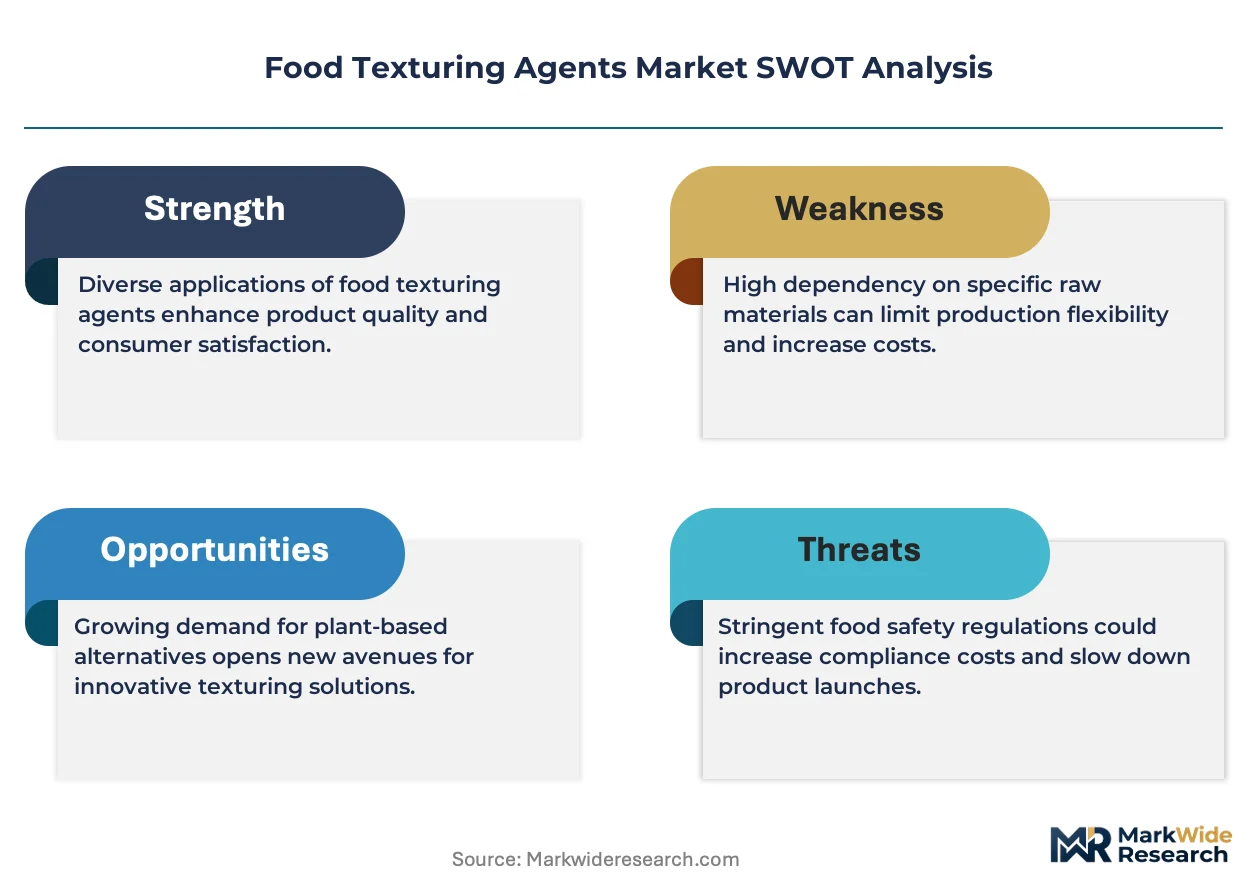
Plant-based meat alternatives is decoupling from traditional dairy applications as the primary growth vertical for texturing agents. Cargill leverages its integrated supply chain from specialty starches to finished hydrocolloid blends for alternative protein matrices. Ingredion anchors its position through deep R&D intensity in clean-label starch modification, while CP Kelco dominates niche microbial gum production for high-performance vegan textures.
Food texturing agents comprise functional ingredients—hydrocolloids, emulsifiers, modified starches, proteins, and specialty gums—that modify rheological properties including viscosity, gelation, and mouthfeel through molecular interaction with water and lipids. These agents serve industrial food manufacturing by stabilizing emulsions, controlling syneresis, and replicating fat-like sensations in reduced-calorie formulations. Hydrocolloids occupy the largest functional margin pool due to their irreplaceability in gluten-free and plant-based systems, while proteins represent the fastest-expanding category driven by extrusion technology advances in meat analogs. Emulsifiers sustain mature volume positions in conventional dairy and bakery segments where cost optimization outweighs premium positioning.
EFSA evaluates novel texturing ingredients under evolving Novel Food regulations, while REACH compliance constrains synthetic emulsifier chemistries and propels bio-based alternatives. FDA GRAS self-affirmation pathways shape US market entry timelines for fermented texturing agents, creating asynchronous approval advantages for established suppliers. Stakeholders must monitor regulatory divergence between EU precautionary frameworks and US notification-based systems when prioritizing R&D portfolios and geographic launch sequencing.
Market Dynamics
Plant-based protein matrices are forcing hydrocolloid suppliers to engineer novel gelling systems that replicate animal-derived textures without gluten or methylcellulose dependency, compressing formulation cycles and rewarding R&D-intensive players.
Growth Catalysts
- Clean-label mandates under EFSA Novel Food regulations:European manufacturers accelerate reformulation of dairy and bakery portfolios to reduce synthetic additive counts, expanding demand for native starches and fermented gums.
- Extrusion technology maturation:High-moisture extrusion lines in meat analog production now require specialized protein-hydrocolloid synergies, pulling investment toward texturing systems that withstand shear stress above 140°C.
- Germany's additive reduction targets:Food manufacturers in Bavaria and Baden-Württemberg are stripping E-numbers from traditional applications, creating immediate pull for label-friendly texturing alternatives.
Market Restraints
- Carrageenan supply concentration:Philippines and Indonesia control 85% of raw seaweed extraction, exposing European formulators to climate-driven harvest volatility and freight cost spikes.
- REACH compliance burdens:Synthetic emulsifier chemistries face escalating registration costs and hazard classification reviews, forcing mid-tier suppliers to abandon modified cellulose derivatives.
- Protein-hydrocolloid incompatibility:Native pea protein aggregates irreversibly with low-acyl gellan gum above pH 6.5, limiting clean-label combinations in neutral pH beverages.
Strategic Opportunities
- Fermented texturing agents via FDA GRAS self-affirmation:US pathway enables 12-18 month faster market entry than EFSA Novel Food routes, rewarding first movers in precision-fermented gums.
- Cell-cultured meat scaffolding:Emerging application demands edible hydrogel matrices with tunable degradation rates, opening premium positioning for microbial polysaccharide specialists.
- Direct-to-manufacturer digital platforms:Ingredient distributors in the Netherlands are bypassing traditional broker networks, compressing procurement cycles and capturing formulation data.
Industry Challenges
- Food rheology expertise scarcity:Formulation chemists with combined hydrocolloid-protein interaction knowledge command 40% salary premiums, constraining mid-cap expansion.
- Clean-label certification timelines:Non-GMO Project and EU organic approvals extend 14-22 months, freezing inventory turns for suppliers without pre-certified raw material pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Texturing Agents Market |
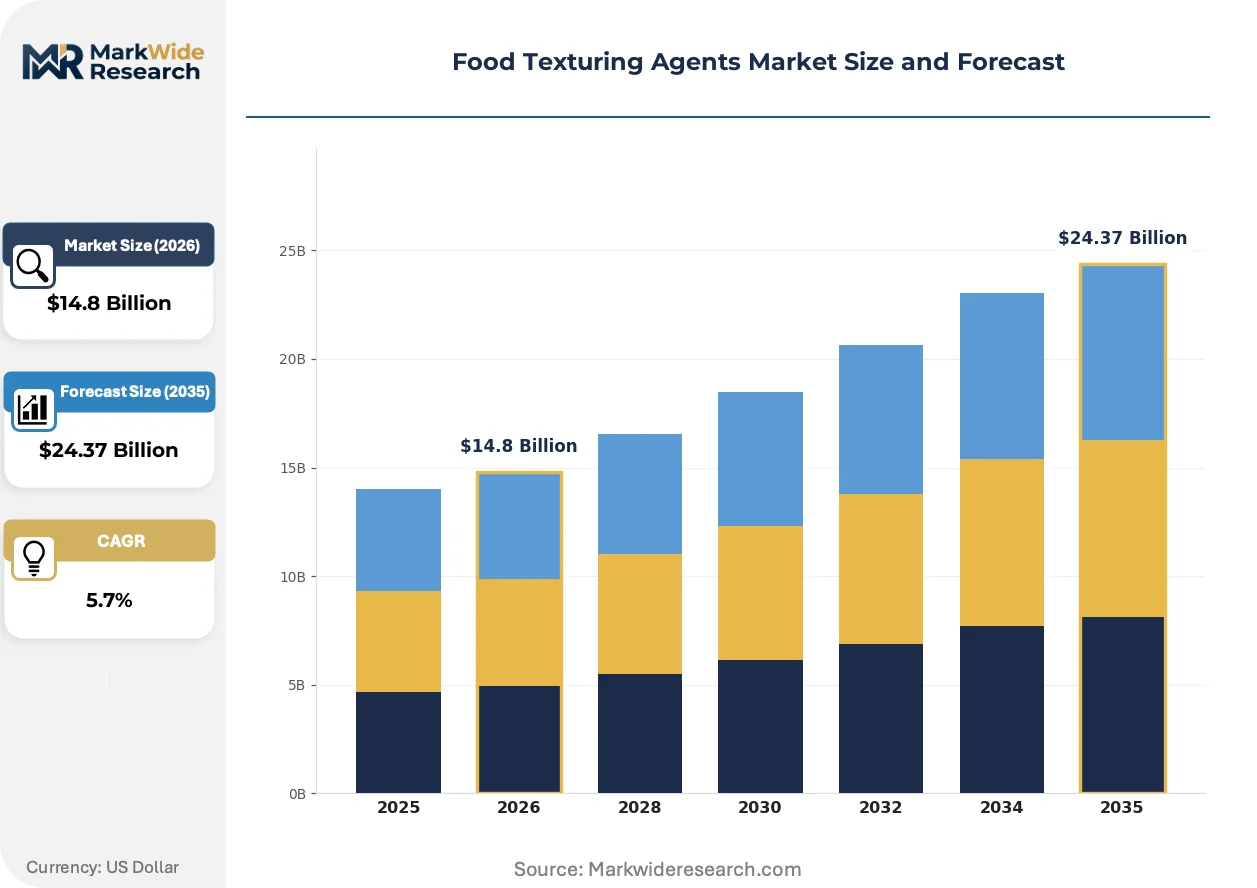
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloids, Emulsifiers, Starches, Proteins, Gums Application: Dairy Products, Bakery Goods, Confectionery, Meat Alternatives, Sauces & Dressings Form: Powder, Liquid, Granules, Flakes, Gels End User: Food Manufacturers, Beverage Companies, Foodservice Providers, Nutraceutical Producers, Frozen Food Makers |
| Companies Covered | Cargill, DuPont de Nemours, Archer Daniels Midland, Tate & Lyle, Kerry Group, Ingredion, CP Kelco, FMC Corporation, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Texturing Agents Market Shifts & Advancements
Computational formulation tools and bio-fermentation platforms are compressing development cycles while regulatory divergence between precautionary and notification-based systems is fragmenting geographic launch strategies.
Precision fermentation of microbial exopolysaccharides is automating the production of high-acyl gellan and curdlan variants with batch-to-batch consistency previously unattainable through agricultural extraction. Meat analog manufacturers in Germany and the Netherlands are adopting these ingredients at 3x the rate of conventional hydrocolloid switches. This technology is automating quality control protocols that previously required manual rheological testing, collapsing the supplier qualification timeline from 18 months to under 6 months.
REACH authorization requirements for synthetic emulsifiers are redirecting R&D investment toward bio-based lecithin and enzymatically modified phospholipids. The industrial consequence is a supply squeeze in conventional mono- and diglycerides as European producers de-prioritize registration renewals. Bakery applications across France, Italy, and Spain are most affected, with manufacturers accelerating trials of sunflower-derived alternatives despite 15-20% cost premiums.
Food manufacturers are consolidating texturing agent procurement under centralized technical buying teams, displacing decentralized category management that prioritized cost-per-kilogram over total formulation performance. This shift compresses supplier rosters from 12-15 vendors to 3-4 strategic partners with integrated application laboratories. The restructuring is most visible in German dairy alternatives, where buyers now demand co-development agreements rather than spot purchasing.
Food Texturing Agents Market Segmentation
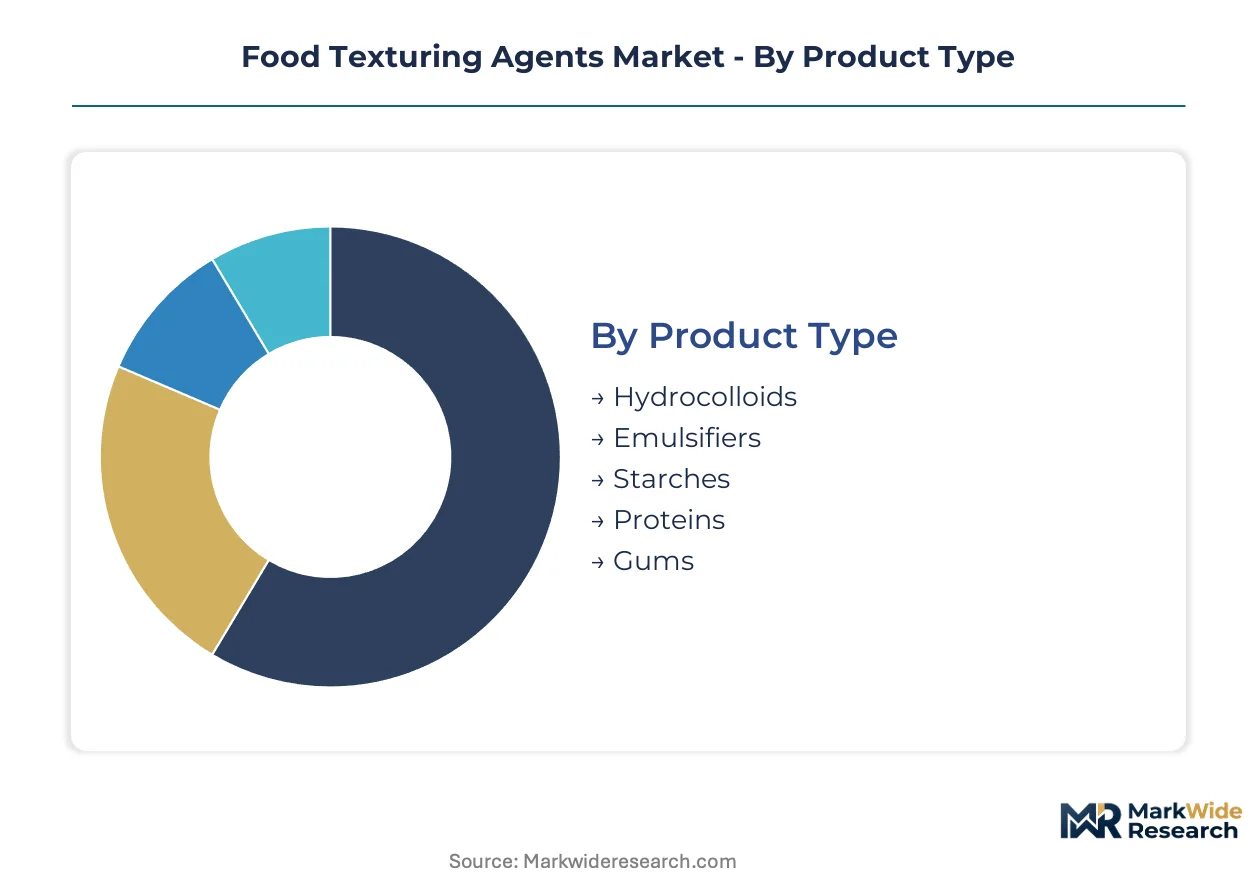
Segmentation in food texturing agents reveals how formulation requirements diverge across protein matrices, thermal processing conditions, and clean-label compliance tiers. Buyers prioritize different functional properties depending on whether they serve plant-based analogs or traditional dairy systems.
Product Type:
Cost tier separates commodity buyers seeking volume pricing from premium formulators demanding batch-to-batch rheological consistency.
- Hydrocolloids:Polysaccharide and protein-based water binders including pectin, xanthan, and carrageenan that control viscosity and gelation through hydrogen bonding. Demand concentrates in German dairy alternatives where manufacturers replicate mouthfeel without casein or methylcellulose, constrained by Philippines seaweed harvest volatility.
- Emulsifiers:Surface-active agents stabilizing oil-water interfaces in reduced-fat formulations. Applications in French and Italian bakery segments face supply pressure as REACH registration costs force abandonment of modified cellulose derivatives.
- Starches:Native and modified carbohydrates providing viscosity and freeze-thaw stability.
- Proteins:Plant-derived functional ingredients enabling extrusion-based fibrous structures.
- Gums:Microbial and seed-derived hydrocolloids including gellan and locust bean variants.
Hydrocolloids lead volumes today; proteins are gaining share fastest.
Application:
Application focus determines whether buyers prioritize thermal stability, shear resistance, or label simplicity.
- Dairy Products:Yogurt, cheese, and ice cream applications requiring syneresis control and fat mimcry. German manufacturers in Bavaria strip E-numbers from traditional portfolios, pulling native starches and fermented gums.
- Meat Alternatives:High-moisture extrusion applications demanding protein-hydrocolloid synergies above 140°C shear stress. Netherlands and German producers adopt precision-fermented microbial gums at triple the rate of conventional switches.
- Bakery Goods:Gluten-free and clean-label bread systems.
- Confectionery:Gelling and texturizing for gummies and aerated products.
- Sauces & Dressings:Pourable viscosity control and emulsion stability.
Dairy Products anchor current revenue; Meat Alternatives show the steepest expansion trajectory.
Form:
Form selection tracks manufacturing infrastructure and dispersion requirements.
- Powder:Spray-dried and milled particles offering shelf stability and precise dosing in automated batching systems. Dominates German food manufacturer procurement for dry-mix beverage and bakery applications.
- Liquid:Pre-hydrated suspensions eliminating dust exposure and hydration time. Preferred by Netherlands dairy alternative producers running continuous processing lines with inline dosing.
- Granules:Agglomerated particles for rapid dispersion.
- Flakes:Sheet-dried hydrocolloids for specific rehydration profiles.
- Gels:Pre-formed hydrated matrices.
Powder commands installed base; Liquid is climbing the fastest among new line investments.
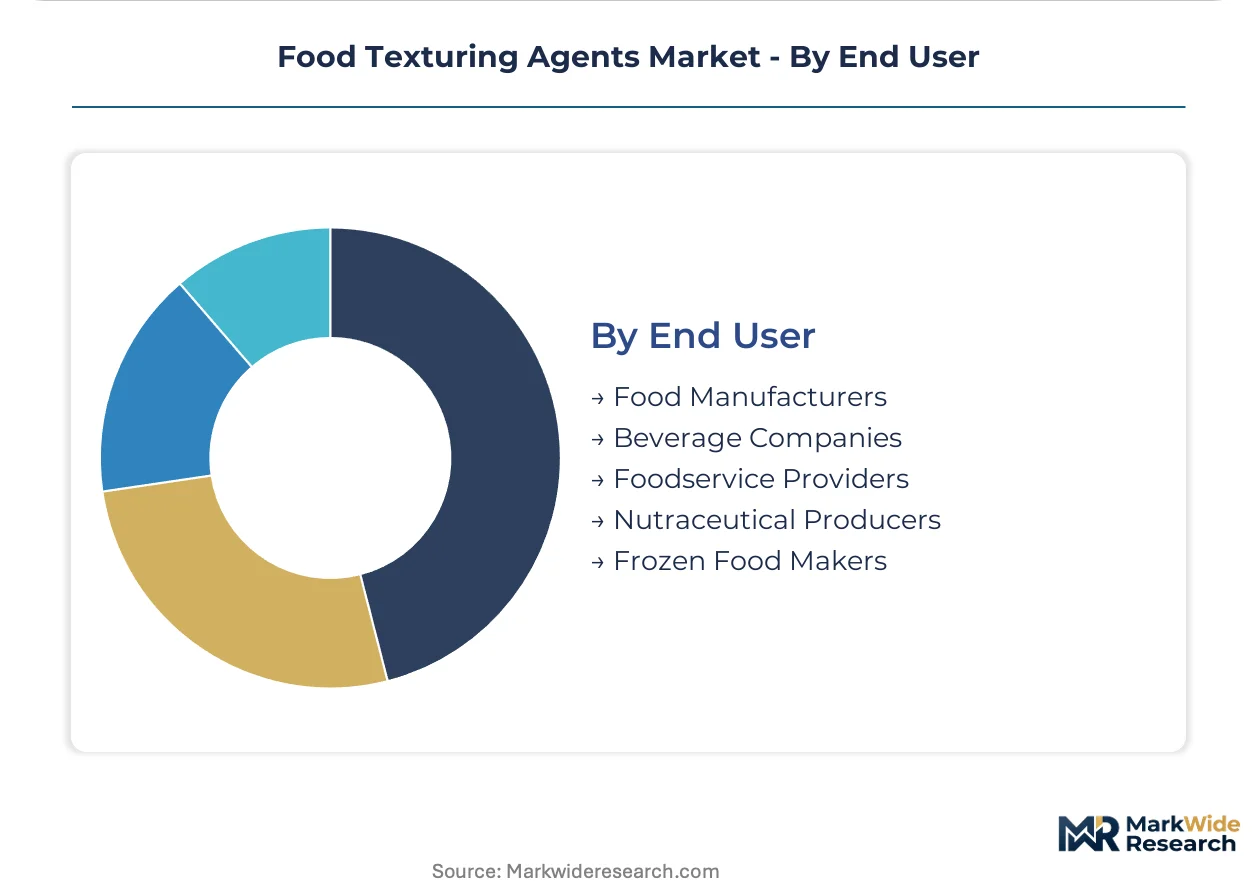
End User:
End user type dictates technical service intensity and procurement centralization.
- Food Manufacturers:Industrial-scale producers of packaged goods with dedicated formulation laboratories. German dairy alternative makers now consolidate procurement under centralized technical buying teams, compressing vendor rosters from 12-15 to 3-4 strategic partners.
- Beverage Companies:Drink formulators managing suspension stability and mouthfeel in neutral pH systems. Pea protein aggregate incompatibility with low-acyl gellan above pH 6.5 limits clean-label options in this segment.
- Foodservice Providers:Commercial and institutional kitchen suppliers.
- Nutraceutical Producers:Functional food and supplement manufacturers.
- Frozen Food Makers:Ready-meal and dessert producers requiring freeze-thaw stability.
Food Manufacturers generate the largest contract values; Beverage Companies are expanding specification fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions with faster approval pathways for novel texturing ingredients, as EFSA Novel Food timelines stretch 24-36 months while FDA GRAS self-affirmation compresses market entry to 12-18 months.
Germany
Clean-label reformulation in Bavaria and Baden-Württemberg is stripping E-numbers from traditional dairy and bakery portfolios. EFSA Novel Food regulations under REACH constrain synthetic emulsifier usage, pulling native starches and fermented gums. Ingredient distributors in Hamburg are consolidating procurement under centralized technical buying teams.
United States
Precision-fermented microbial gums are accelerating through FDA GRAS self-affirmation pathways, rewarding first movers in high-acyl gellan variants. The regulatory notification system enables 12-18 month faster entry than European routes. Meat analog manufacturers in California and Illinois are adopting these ingredients at triple the rate of conventional switches.
Netherlands
High-moisture extrusion facilities in Noord-Brabant and Gelderland demand protein-hydrocolloid synergies withstanding shear stress above 140°C. EFSA compliance requirements shape formulation choices for export-oriented producers. Direct-to-manufacturer digital platforms in Rotterdam are bypassing traditional broker networks and capturing formulation data.
France
Bakery applications across Île-de-France and Auvergne-Rhône-Alpes face supply pressure as REACH registration costs force abandonment of modified cellulose derivatives. Sunflower-derived lecithin alternatives command 15-20% cost premiums. French manufacturers are accelerating trials of bio-based emulsifiers despite price differentials.
Indonesia
Raw seaweed extraction for carrageenan supply concentrates harvest operations vulnerable to climate-driven volatility. The Philippines-Indonesia supply corridor controls 85% of global raw material, exposing European formulators to freight cost spikes. Processing clusters in Sulawesi and Sumatra face mounting pressure to diversify extraction sources.
Food Texturing Agents Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek to compress formulation development cycles and secure co-development agreements with consolidated buying teams. The vendor base organizes around three tiers: integrated agricultural processors with captive raw material supply, specialized microbial fermentation houses with precision-controlled bioprocessing, and regional distributors building digital procurement platforms. Two competitive moves define current positioning: backward integration into specialty crop cultivation to secure non-GMO certified feedstocks, and technology licensing arrangements that transfer rheological expertise to meat analog manufacturers lacking in-house formulation capabilities.
Within the integrated processor tier, Cargill and Ingredion exemplify archetypes of agricultural commodity players extending downstream into functional ingredient blending. CP Kelco occupies a distinct position among microbial gum specialists leveraging precision fermentation platforms. These three anchors represent divergent strategic postures: agricultural supply chain control versus bioprocessing specialization versus application-specific technical service intensity.
| Leading Market Players |
|---|
| Cargill |
| DuPont de Nemours |
| Archer Daniels Midland |
| Tate & Lyle |
| Kerry Group |
| Ingredion |
| CP Kelco |
| FMC Corporation |
| BASF |
| Others |
Supply & Pricing Matrix
Centralized technical buying teams at German dairy alternative manufacturers are consolidating vendor rosters from 12-15 suppliers to 3-4 strategic partners, forcing mid-tier hydrocolloid suppliers to absorb certification costs or exit contract negotiations. This procurement compression rewards integrated players with captive raw material supply and collapses price premiums for commodity-grade texturing agents.
Pricing Analysis
Distributor margins in European hydrocolloid supply chains compress as direct-to-manufacturer digital platforms in the Netherlands bypass traditional broker networks. Three-tier pricing structure across precision-fermented premium grades, standard agricultural extracts, and economy modified starches reflects batch-to-batch rheological consistency and Non-GMO Project certification status. Cost compression in synthetic emulsifiers intensifies because REACH registration burdens force mid-tier suppliers to abandon modified cellulose derivatives. Beverage companies demonstrate highest price sensitivity due to pea protein-hydrocolloid incompatibility limiting formulation flexibility, while meat analog manufacturers accept 15-20% premiums for shear-stable microbial gums.
Supply Chain Analysis
Non-GMO Project and EU organic certification gating extends supplier qualification timelines from 18 months to under 6 months only for pre-certified raw material pipelines. Raw seaweed extraction for carrageenan concentrates in the Philippines and Indonesia, with processing clusters in Sulawesi and Sumatra feeding European formulators. Specialty crop cultivation for non-GMO starches rests on Midwest US corn belts and Thai tapioca regions. Single-source vulnerability in the Philippines-Indonesia corridor exposes buyers to climate-driven harvest volatility and freight cost spikes. Distribution runs through Rotterdam and Hamburg port complexes into centralized technical buying teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food texturing agents function as a stable compounder anchored by irreformable formulation requirements in plant-based protein matrices that demand specialized hydrocolloid-protein synergies.
For Market Incumbents: Lock in co-development agreements with consolidated German dairy alternative buying teams before precision-fermented microbial gums commoditize. Defend margin position by securing captive supply of non-GMO certified tapioca and corn feedstocks through backward integration into Thai and Midwest specialty crop cultivation. Accelerate FDA GRAS self-affirmation pathways for fermented texturing agents to exploit 12-18 month regulatory arbitrage against EFSA Novel Food timelines. For New Entrants and Emerging Players: Begin with cell-cultured meat scaffolding applications demanding edible hydrogel matrices with tunable degradation rates, where microbial polysaccharide specialists command premium positioning absent agricultural extraction incumbents. Target Netherlands high-moisture extrusion facilities running continuous processing lines with inline dosing preferences for liquid pre-hydrated suspensions. Establish digital procurement platforms capturing formulation data to bypass traditional broker networks. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-fermentation houses automating batch-to-batch consistency in high-acyl gellan and curdlan variants. Five-to-ten year viability hinges on regulatory divergence persisting between FDA notification-based and EFSA precautionary approval frameworks. Target microbial gum specialists with existing GRAS self-affirmations. Monitor EFSA Novel Food timeline extensions as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Automates high-acyl gellan production with batch consistency unattainable through seaweed extraction. |
| Backward Integration into Specialty Crops | Secures non-GMO certified corn and tapioca feedstocks for clean-label starch modification. |
| Direct-to-Manufacturer Digital Platforms | Rotterdam-based distributors bypass broker networks and capture formulation data from Dutch extrusion facilities. |
| Co-Development Agreements | German dairy alternative makers now demand technical service partnerships rather than spot purchasing. |
| FDA GRAS Self-Affirmation Pathway | Enables 12-18 month faster market entry than EFSA Novel Food routes for fermented texturing agents. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food formulation chemists, procurement leads at German dairy alternative manufacturers, technical directors at hydrocolloid suppliers, and regulatory affairs specialists navigating EFSA Novel Food pathways with secondary validation. Customs and trade data, EFSA submission databases, FDA GRAS notifications, and SEC filings from integrated agricultural processors anchored supply-side modeling. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Historical reference periods anchored volume and value projections across the analysis window, with CAGRs derived from segmented growth trajectory modeling. Segmentation dimensions included hydrocolloid type, protein source compatibility, thermal processing requirement, clean-label certification tier, and geographic regulatory cluster. Forecast inputs incorporated extrusion technology maturation rates, EFSA approval timeline elasticity, and precision-fermentation capacity buildout schedules.
Several conditions sit outside the modeled scope, including abrupt climate events disrupting Philippines-Indonesia seaweed harvests, sudden REACH reclassification of residual synthetic emulsifiers, and breakthroughs in protein-hydrocolloid compatibility solving current pH limitations. Forecasts reflect documented assumptions about regulatory divergence persistence and procurement centralization velocity. A model refresh is warranted upon material change in EFSA Novel Food processing timelines or FDA GRAS notification volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Bakery Enzymes Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Baking Enzymes Market