
 Global Private 5G Network Market | 2026-2036
Global Private 5G Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Private 5G Network Market Foresight
Radio access network manufacturing capacity in South Korea is shifting toward enterprise-grade small cell and baseband unit production. Samsung Electronics leverages its semiconductor fabrication scale to sustain cost advantages in integrated radio designs. Nokia Corporation anchors European supply through its Oulu R&D campus and AirScale portfolio specialization. Cisco Systems competes through software-defined core platforms that extend its enterprise networking dominance into cellular domains.
A private 5G network constitutes a localized cellular deployment using licensed, shared, or unlicensed spectrum with dedicated core and radio infrastructure operating independently of public operator services. These systems employ 3GPP Release 16 and 17 specifications with sub-6 GHz and millimeter-wave bands to deliver sub-10 millisecond latency and 99.999% reliability for machine-to-machine coordination. On-premise deployment configurations command the largest current revenue share due to data sovereignty requirements in defense and critical infrastructure settings. Cloud-hosted solutions represent the fastest-expanding segment as hyperscalers integrate 5G core functions with edge computing platforms. Security solutions within the solution type taxonomy concentrate margin pools because enterprise buyers mandate encryption, network slicing isolation, and zero-trust architectures as non-negotiable procurement criteria.
The FCC governs spectrum allocation through CBRS and Auction 110 mechanisms while the EU AI Act and CE marking frameworks impose operational technology cybersecurity standards on industrial network deployments. Germany's BNetzA and Japan's MIC have established local licensing frameworks that shape vendor market access conditions and equipment certification pathways. Stakeholders must monitor spectrum harmonization negotiations between national regulators and 3GPP standardization timelines to align capital deployment with emerging enterprise service requirements.
Market Dynamics
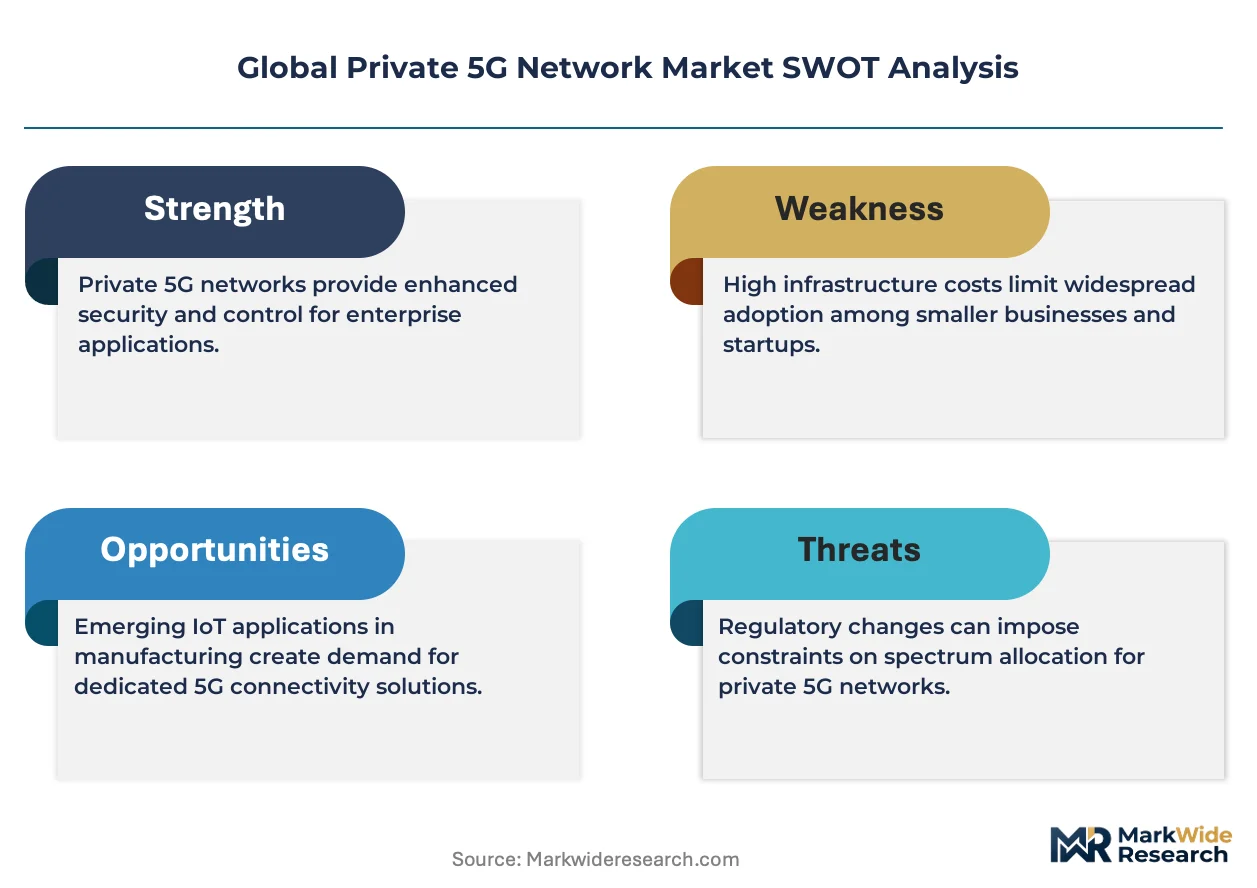
Spectrum licensing frameworks are fragmenting procurement patterns across industrial verticals, with national regulators creating incompatible certification pathways that force vendors to maintain parallel equipment variants.
Growth Catalysts
- Industry 4.0 factory retrofits:German automotive and precision manufacturing facilities are deploying dedicated radio infrastructure to synchronize robotic assembly lines with sub-millisecond coordination requirements.
- CBRS spectrum access:The FCC's three-tier priority framework in the United States has validated licensed-shared access as a commercially viable alternative to exclusive spectrum auctions.
- Edge computing convergence:Hyperscaler platforms are integrating 5G core functions with containerized edge workloads, collapsing network and compute procurement cycles into unified infrastructure decisions.
Market Restraints
- Radio unit supply concentration:Baseband processor and massive MIMO antenna fabrication capacity clusters in South Korean and Finnish manufacturing facilities, creating single-source vulnerability for integrated designs.
- Millimeter-wave propagation physics:Sub-6 GHz deployments dominate current installations because high-frequency bands require dense small cell grids that multiply equipment counts for equivalent coverage.
- Cross-border certification friction:Japan's MIC and Germany's BNetzA impose divergent electromagnetic compatibility testing regimes that extend equipment approval timelines by six to eighteen months.
Strategic Opportunities
- India's enterprise spectrum liberalization:TRAI's proposed direct assignment framework for captive non-public networks would unlock manufacturing and port automation demand previously blocked by carrier-dependent leasing models.
- Defense and critical infrastructure sovereignty mandates:NATO member states and Five Eyes partners are mandating on-premise core infrastructure for classified communications, creating isolated procurement pools with premium margin structures.
- Network slicing monetization:Virtualized core architectures enable quality-of-service guarantees for industrial IoT traffic that public operators cannot replicate, positioning private deployers as vertical-specific connectivity utilities.
Industry Challenges
- Radio frequency engineering talent scarcity:Enterprise IT departments lack cellular propagation modeling expertise, forcing reliance on system integrators that capture implementation margin and extend deployment timelines.
- Legacy operational technology integration:Brownfield manufacturing facilities operate PROFINET and EtherCAT industrial ethernet protocols that require protocol translation gateways, adding latency and failure points to otherwise deterministic networks.
- Zero-trust security architecture implementation:Enterprise buyers mandate micro-segmentation and continuous authentication, but 3GPP Release 16 security specifications predate these frameworks, creating compliance interpretation disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Private 5G Network Market |
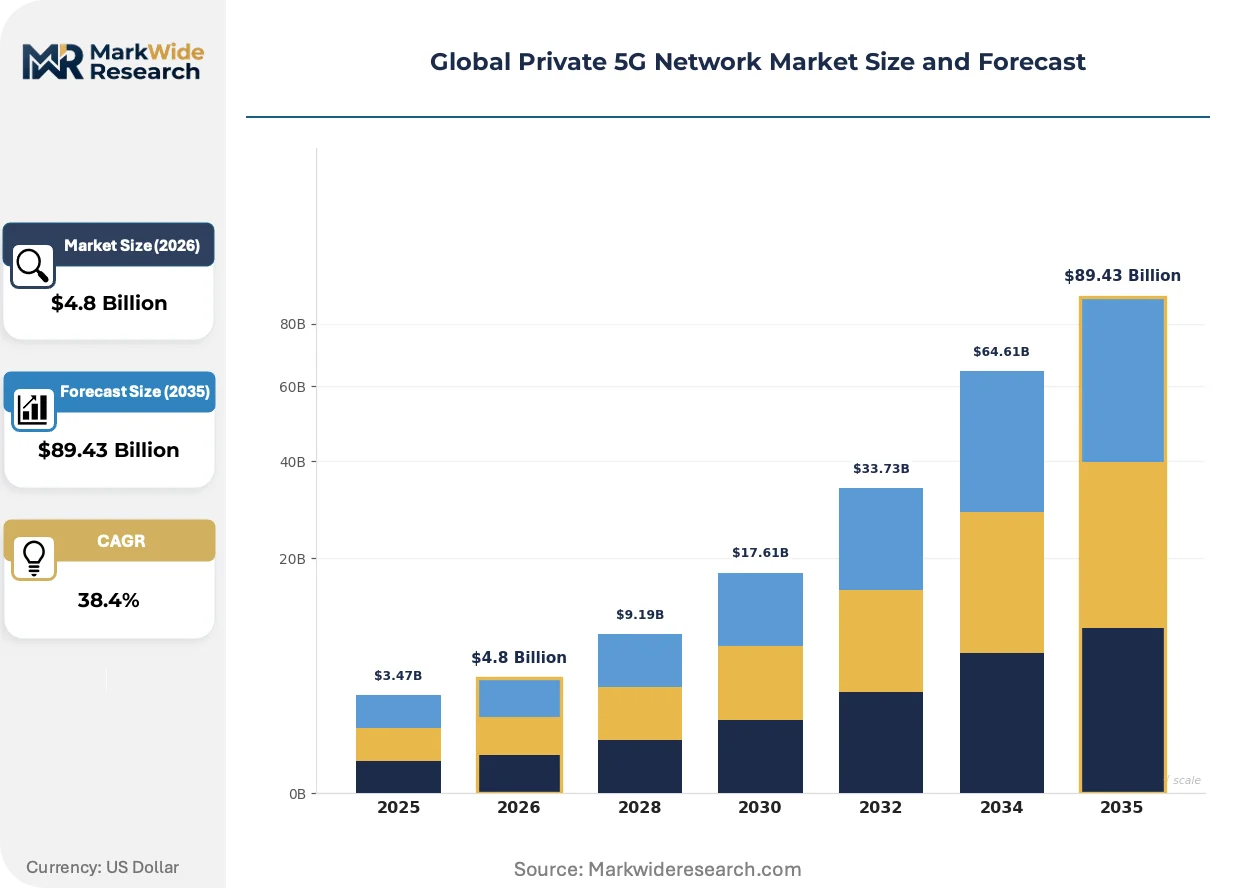
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $89.43 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud Hosted, Hybrid, Edge Computing Solution Type: Network Infrastructure, Security Solutions, Network Management, Application Enablement Use Case: Smart Manufacturing, Connected Logistics, Public Safety Communications, Remote Monitoring End User: Telecom Operators, Energy Companies, Transportation Providers, Educational Institutions |
| Companies Covered | Huawei Technologies Co., Ltd., Cisco Systems, Inc., Telefonaktiebolaget LM Ericsson, NEC Corporation, Qualcomm Technologies, Inc., Nokia Corporation, ZTE Corporation, Verizon Communications, Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Private 5G Network Market Shifts & Advancements
Open radio access network architectures are dismantling vendor lock-in structures that have dominated cellular infrastructure procurement for three decades. This disaggregation is redistributing value capture across the stack.
Open RAN specifications are decentralizing baseband processing functions from proprietary hardware into software containers running on commodity servers. Mining operations in Western Australia and container terminals in Rotterdam are deploying multi-vendor radio units with centralized cloud-native cores, compressing equipment costs by eliminating single-source dependencies. This architecture is decentralizing supply chain risk across radio, hardware, and software layers.
The EU AI Act's risk classification framework is imposing operational technology cybersecurity obligations on industrial network deployments that process automated decision-making data. Manufacturing facilities must now document algorithmic transparency and human oversight mechanisms for quality control systems connected to private cellular infrastructure. German automotive plants are responding by segregating AI inference workloads onto network slices with enhanced logging and audit capabilities.
Enterprise buyers are consolidating radio, core, and edge compute procurement under single-vendor managed service contracts rather than assembling multi-supplier solutions. This pattern compresses vendor negotiation cycles and shifts technical risk to system integrators. Japanese automotive suppliers and Singaporean port operators have adopted this model most aggressively, treating private 5G as a utility service with uptime guarantees rather than a capital asset.
Global Private 5G Network Market Segmentation
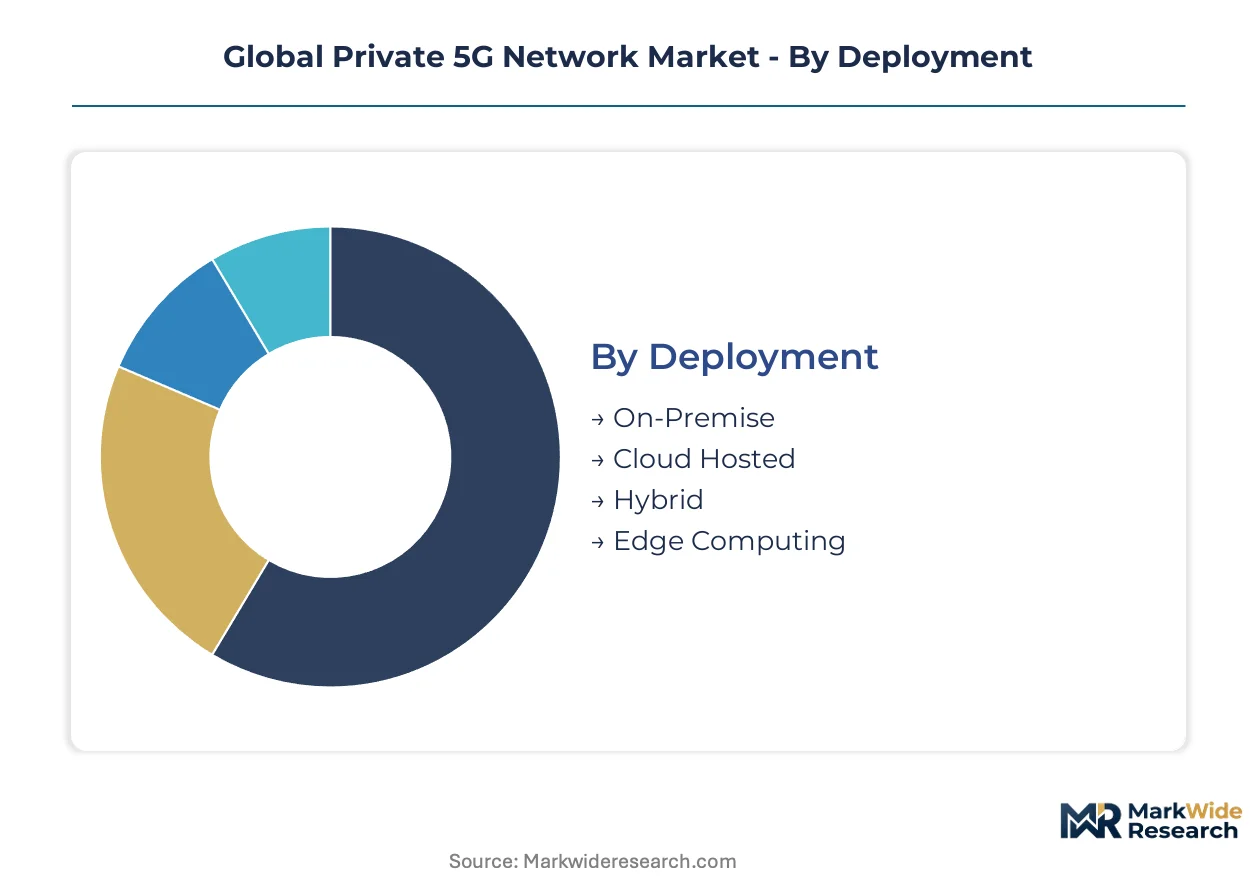
Private 5G deployments fragment across infrastructure configurations, solution layers, and operational use cases. Each segmentation axis reveals distinct procurement patterns, capital requirements, and vendor competitive dynamics that shape enterprise adoption trajectories.
Deployment:
Capital intensity varies sharply across deployment modalities, with on-premise configurations demanding substantial upfront infrastructure investment while cloud-hosted alternatives shift expenditure toward recurring operational models.
- On-Premise:Dedicated radio units, core network servers, and edge computing hardware installed within facility boundaries. German automotive plants and US defense installations absorb the bulk of current deployments due to data sovereignty mandates and classified communications requirements.
- Cloud Hosted:Virtualized core functions delivered via hyperscaler platforms with subscription-based pricing. Singaporean port operators and Japanese automotive suppliers are expanding most quickly here, treating connectivity as a utility service rather than capital asset.
- Hybrid:Split architecture combining on-premise radio access with cloud-hosted core processing. Mining operations in Western Australia leverage this model for remote site connectivity with centralized management.
- Edge Computing:Containerized compute workloads colocated with radio infrastructure for sub-10 millisecond latency. Container terminals in Rotterdam deploy this configuration for automated guided vehicle coordination.
On-premise deployments absorb the bulk of installed capacity; cloud-hosted alternatives are expanding most quickly.
Solution Type:
Margin concentration follows technical differentiation, with security and management layers commanding premium pricing against commoditized radio hardware.
- Network Infrastructure:Radio access units, baseband processors, and core network equipment forming the physical connectivity layer. Samsung Electronics and Nokia Corporation dominate supply through semiconductor fabrication scale and Oulu R&D specialization respectively.
- Security Solutions:Encryption modules, network slicing isolation, and zero-trust architecture implementations. Enterprise buyers mandate these as non-negotiable procurement criteria, concentrating margin pools in this layer.
- Network Management:Orchestration platforms for spectrum allocation, subscriber provisioning, and performance monitoring. Cisco Systems extends its enterprise networking dominance into cellular domains through software-defined platforms here.
- Application Enablement:APIs and development frameworks for industrial IoT integration. PROFINET and EtherCAT protocol translation gateways represent critical integration points for brownfield manufacturing retrofits.
Network infrastructure claims the largest revenue share; security solutions are climbing the fastest as compliance frameworks tighten.
Use Case:
Operational requirements dictate spectrum band selection and latency specifications, with manufacturing applications driving sub-6 GHz deployments while logistics use cases exploit millimeter-wave density.
- Smart Manufacturing:Robotic assembly line synchronization with sub-millisecond coordination requirements. Bosch, Siemens, and Volkswagen factory retrofits in Germany anchor demand for deterministic machine-to-machine communication.
- Connected Logistics:Real-time inventory tracking and automated vehicle routing across warehouse and port environments. Rotterdam container terminals deploy dense small cell grids to support high-frequency band propagation.
- Public Safety Communications:Mission-critical voice and data services for emergency response coordination. FCC CBRS priority access licenses enable dedicated spectrum for municipal and federal agencies.
- Remote Monitoring:Sensor networks for asset condition tracking in dispersed industrial facilities. Western Australian mining operations leverage this use case with centralized cloud-native core architectures.
Smart manufacturing dominates current deployment value; connected logistics is gaining share fastest as port automation accelerates.
End User:
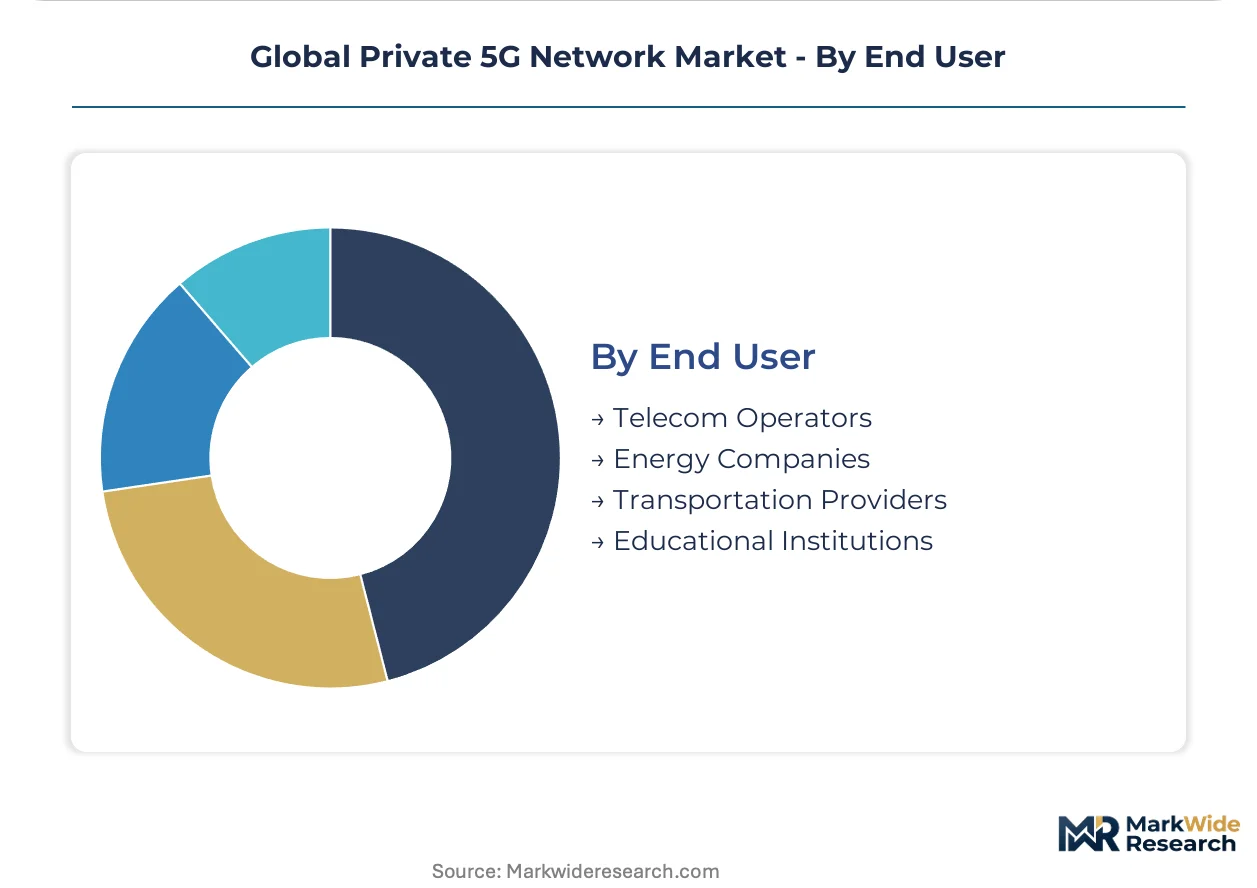
Procurement sophistication varies dramatically across buyer categories, with energy and transportation providers driving complex multi-site rollouts while educational institutions pilot limited coverage zones.
- Telecom Operators:Wholesale network slicing and managed private network services for enterprise customers. These entities leverage existing spectrum holdings to compete against dedicated enterprise deployments.
- Energy Companies:Offshore platform connectivity and pipeline monitoring across geographically dispersed infrastructure. North Sea oil operations and US utility grids represent anchor deployments.
- Transportation Providers:Port automation, railway signaling, and airport ground operations requiring high-reliability coverage. Singaporean port operators have adopted single-vendor managed service contracts most aggressively.
- Educational Institutions:Campus-wide coverage for research collaboration and IoT laboratory environments. Limited pilot deployments concentrate in research-intensive universities with manufacturing engineering programs.
Energy companies command the largest project scale; transportation providers are expanding most rapidly as port and rail automation mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean semiconductor fabrication anchors radio access network supply for private 5G deployments worldwide. German industrial automation demand and United States spectrum liberalization shape procurement patterns across enterprise verticals.
United States
Defense installations and smart manufacturing facilities drive on-premise deployment demand. The FCC's CBRS three-tier priority framework enables licensed-shared access without exclusive spectrum auctions. Pittsburgh steel mills and Austin semiconductor fabs anchor enterprise adoption.
Germany
Industry 4.0 retrofits at Bosch, Siemens, and Volkswagen factories create anchor demand for deterministic machine-to-machine coordination. BNetzA local licensing frameworks impose equipment certification pathways distinct from EU harmonized standards. Stuttgart automotive cluster and Munich industrial corridor concentrate deployment activity.
Japan
Automotive suppliers and port operators adopt single-vendor managed service contracts treating private 5G as utility infrastructure. MIC electromagnetic compatibility testing regimes extend equipment approval timelines versus European benchmarks. Nagoya manufacturing belt and Yokohama port complex lead operational rollouts.
South Korea
Samsung Electronics leverages semiconductor fabrication scale to sustain cost advantages in integrated radio designs for enterprise small cells. National spectrum policy prioritizes industrial automation and defense applications. Suwon R&D cluster and Incheon port automation projects anchor domestic deployment.
India
Manufacturing and port automation demand awaits unlock through TRAI's proposed direct assignment framework for captive non-public networks. Current carrier-dependent leasing models block enterprise procurement. Mumbai port trust and Gujarat industrial corridor represent prospective deployment zones.
Global Private 5G Network Market Competitive Landscape
Global majors compete with regional champions across radio access network supply and core network software layers. Market structure consolidates around integrated infrastructure vendors with semiconductor fabrication scale or R&D specialization. Three archetypes dominate: Asian electronics conglomerates with captive chip supply, European telecom equipment heritage players with standards body influence, and North American enterprise networking vendors with software-defined platform expertise. Competitive moves center on Open RAN multi-vendor interoperability certification and hyperscaler edge computing partnership structures.
Among Asian electronics conglomerates, Samsung Electronics Co., Ltd. and Huawei Technologies Co., Ltd. occupy positions reflecting integrated semiconductor and radio design capabilities. European heritage is exemplified by Nokia Corporation and Telefonaktiebolaget LM Ericsson, representing Oulu and Stockholm R&D campus specialization respectively. North American enterprise networking presence is anchored by Cisco Systems, Inc., extending software-defined dominance into cellular core functions. These three groupings collectively span the infrastructure stack from baseband processing through orchestration platforms.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| Telefonaktiebolaget LM Ericsson |
| NEC Corporation |
| Qualcomm Technologies, Inc. |
| Nokia Corporation |
| ZTE Corporation |
| Verizon Communications |
| Samsung Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
EU AI Act operational technology cybersecurity obligations gate qualified supply for private 5G network infrastructure, with compliant vendors commanding premium-tier pricing access while non-compliant equipment faces procurement exclusion across German automotive and defense installations.
Pricing Analysis
Warranty and managed service bundling separates pricing tiers in private 5G procurement, with subscription-based core-as-a-service models commanding recurring revenue premiums against capital-intensive on-premise deployments. Price differentiation hinges on certification grade under BNetzA and MIC electromagnetic compatibility regimes plus geographic delivery cost for remote site installations. Cost compression in cloud-hosted segments is intensifying because hyperscaler platforms commoditize virtualized core functions. Energy companies and transportation providers exhibit lowest price sensitivity due to uptime guarantee requirements, while educational institutions piloting limited coverage zones drive economy-tier demand.
Supply Chain Analysis
Trans-Pacific freight cost volatility and semiconductor shipping lane congestion amplify landed cost uncertainty for baseband processors and massive MIMO antenna shipments originating in South Korea and Finland. Radio access network manufacturing concentrates in South Korea, Finland, and China, with Samsung Electronics and Nokia Corporation anchoring integrated design supply. Fabrication draws from advanced node semiconductor wafers, rare earth magnet components for antenna arrays, and specialized RF substrate materials. Single-source vulnerability clusters in South Korean baseband processor foundries. Distribution runs through system integrator channels that capture implementation margin and extend deployment timelines for enterprise buyers lacking cellular engineering expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for operational technology cybersecurity erects a compliance moat that rewards certified vendors with procurement preference across NATO defense installations and German Industry 4.0 retrofits.
For Market Incumbents: Anchor market position through Open RAN multi-vendor interoperability certification investments that neutralize emerging software-defined radio competitors, while deepening captive semiconductor supply relationships to defend against South Korean fabrication capacity constraints. Prioritize BNetzA and MIC pre-certification pathways to compress approval timelines versus rivals facing eighteen-month electromagnetic compatibility testing delays. For New Entrants and Emerging Players: Begin with India's captive non-public network segment awaiting unlock through TRAI's direct assignment framework, where carrier-dependent leasing models currently block enterprise procurement. Target Western Australian mining operations and Rotterdam port automation projects for hybrid deployment architectures combining on-premise radio with cloud-native core management. Lead with security solutions layer specialization to capture margin concentration from zero-trust architecture mandates. For Investors and Strategic Acquirers: TRAI's finalization of direct assignment regulations for captive non-public networks is the leading indicator that Indian manufacturing and port automation demand will convert from prospective to active procurement pools. Long-term viability centers on vendors with integrated semiconductor fabrication scale or hyperscaler edge computing partnership structures. Acquisition focus should center on Open RAN software specialists with containerized baseband processing capabilities. Watch for FCC Auction 110 spectrum allocation patterns as signal of licensed-shared access model expansion beyond CBRS framework.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Multi-Vendor Certification | Disaggregates supply chain risk across radio, hardware, and software layers for mining and port operators. |
| Hyperscaler Edge Computing Partnership | Integrates 5G core functions with containerized workloads for Singaporean utility service procurement models. |
| Defense Sector Security Clearance | Unlocks NATO member state classified communications procurement pools with premium margin structures. |
| Indian Spectrum Regulatory Engagement | Positions for TRAI direct assignment framework activation across Gujarat industrial corridor deployments. |
| Legacy Protocol Translation Gateway Development | Enables PROFINET and EtherCAT integration for brownfield German automotive facility retrofits. |
Research Methodology
Independent corroboration across network infrastructure procurement managers, cellular system integration specialists, defense telecommunications officers, and industrial automation engineers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation through FCC spectrum auction records, BNetzA equipment certification databases, 3GPP standardization release documentation, and hyperscaler capex disclosures. Bottom-up deployment tracking across German automotive plants, Singaporean port operators, and Western Australian mining sites triangulates against top-down vendor revenue segmentation.
Rate-of-change decomposition across the projection horizon isolates spectrum licensing framework maturation, Open RAN architecture adoption velocity, and edge computing convergence effects from underlying industrial automation demand growth. Segmentation dimensions modeled span deployment configuration, solution type, operational use case, and end-user vertical with regional regulatory cluster overlays. CAGR derivation incorporated equipment shipment volumes, subscription service bookings, and professional services attachment rates. Industry-specific forecast inputs include CBRS priority access license uptake trajectories and EU AI Act implementation timelines for operational technology cybersecurity compliance.
Underlying measurement precision varies by segment; on-premise deployment configurations and German automotive end-use carry tighter precision than emerging cloud-hosted alternatives and educational institution pilots. Forecasts reflect documented assumptions regarding spectrum harmonization negotiations, semiconductor fabrication capacity expansion, and regulatory approval pathway standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Optical Network Equipment Market
Network Technology
Network Emulator Market
Network Technology
Global Industrial Ethernet Switch Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Global Wireless Router Market
Network Technology
Germany Residential Gateway Market
Network Technology
Global Network Monitoring Market
Network Technology
Mobile Backhaul Market
Network Technology
Self-Healing Networks Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Global Network Switches Market
Network Technology
Gigabit Ethernet Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Digital Repeater Market