
 Global Carrier Wi-Fi Equipment Market | 2026-2036
Global Carrier Wi-Fi Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carrier Wi-Fi Equipment Market Foresight
Enterprise campus networks are unwinding legacy reliance on standalone wireless LAN vendors as telecom operators reclaim ownership of indoor connectivity. Cisco Systems leverages its Meraki cloud architecture to anchor multi-tenant carrier deployments across North American stadiums and airports. Huawei Technologies dominates dense-access-point rollouts through its in-house silicon-to-software stack, while Nokia Corporation competes on Open RAN interoperability pledges that appeal to European operators seeking vendor diversification.
Carrier Wi-Fi equipment encompasses access points, controllers, and gateways engineered for seamless authentication, policy enforcement, and traffic handoff between cellular and unlicensed spectrum. These systems typically integrate 802.11ax or 802.11be radios with Hotspot 2.0 and Passpoint protocols to enable automatic subscriber roaming without manual login. Wi-Fi 6 and Wi-Fi 6E radios now lead procurement volumes as operators seek 6 GHz spectrum relief in congested venues, while Wi-Fi 7 silicon anchors premium bids for ultra-low-latency factory and stadium backhaul. Enterprise networks and smart cities concentrate margin pools through multi-year managed service contracts, whereas public hotspots mature into thin-margin throughput commodities.
The FCC governs unlicensed spectrum power limits and device certification in the United States, while ETSI harmonizes 6 GHz access rules across European member states; both frameworks directly shape radio design cycles and regional product SKUs. China's MIIT issues GB standards that mandate domestic encryption modules, creating parallel certification tracks for equipment vendors. Stakeholders must monitor spectrum reallocation proceedings in Brazil and India, where pending 6 GHz declassification decisions will determine whether Wi-Fi 6E inventory investments convert to revenue or strand as region-locked assets.
Market Dynamics
Mobile network operators are consolidating indoor connectivity ownership from enterprise IT departments, forcing equipment vendors to rearchitect around cloud-native controller platforms and Hotspot 2.0 roaming federation.
Growth Catalysts
- Wi-Fi 6E spectrum liberalization:The FCC's 6 GHz unlicensed rules and ETSI's harmonized European framework unlock 1,200 MHz of contiguous bandwidth for stadium and airport deployments.
- Smart city infrastructure mandates:Municipal governments in China embed carrier-grade Wi-Fi into unified public networks spanning transit hubs, street furniture, and emergency response systems.
- Cellular traffic offload economics:Dense urban corridors in Brazil and India drive operator procurement of dual-radio access points to relieve licensed spectrum congestion during peak hours.
Market Restraints
- Silicon supply concentration:Advanced 802.11be baseband fabrication depends on a concentrated foundry base in Taiwan, creating lead-time vulnerability for premium equipment tiers.
- Regional certification fragmentation:China's MIIT GB standards mandate domestic encryption modules, forcing parallel hardware SKUs that inflate inventory carrying costs for multinational vendors.
- Passive optical network substitution:Fiber-to-the-room deployments in greenfield commercial buildings reduce reliance on Wi-Fi backhaul in premium enterprise segments.
Strategic Opportunities
- Private 5G-Wi-Fi convergence:CBRS spectrum sharing rules in the United States enable neutral-host business models where single infrastructure serves both cellular and unlicensed subscribers.
- Industrial IoT backhaul:Ultra-reliable low-latency communication requirements in German automotive factories position Wi-Fi 7 as a wireline replacement for mobile robotics control.
- Managed service bundling:Japanese building automation integrators are consolidating network operations contracts that combine Wi-Fi assurance with energy management and physical security.
Industry Challenges
- RF engineering talent scarcity:The intersection of cellular and unlicensed optimization requires skills concentrated among legacy macro network planners, constraining deployment velocity for neutral-host operators.
- Multi-vendor interoperability testing:Open RAN disaggregation pledges force extended certification cycles against Passpoint and Hotspot 2.0 roaming profiles before commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carrier Wi-Fi Equipment Market |
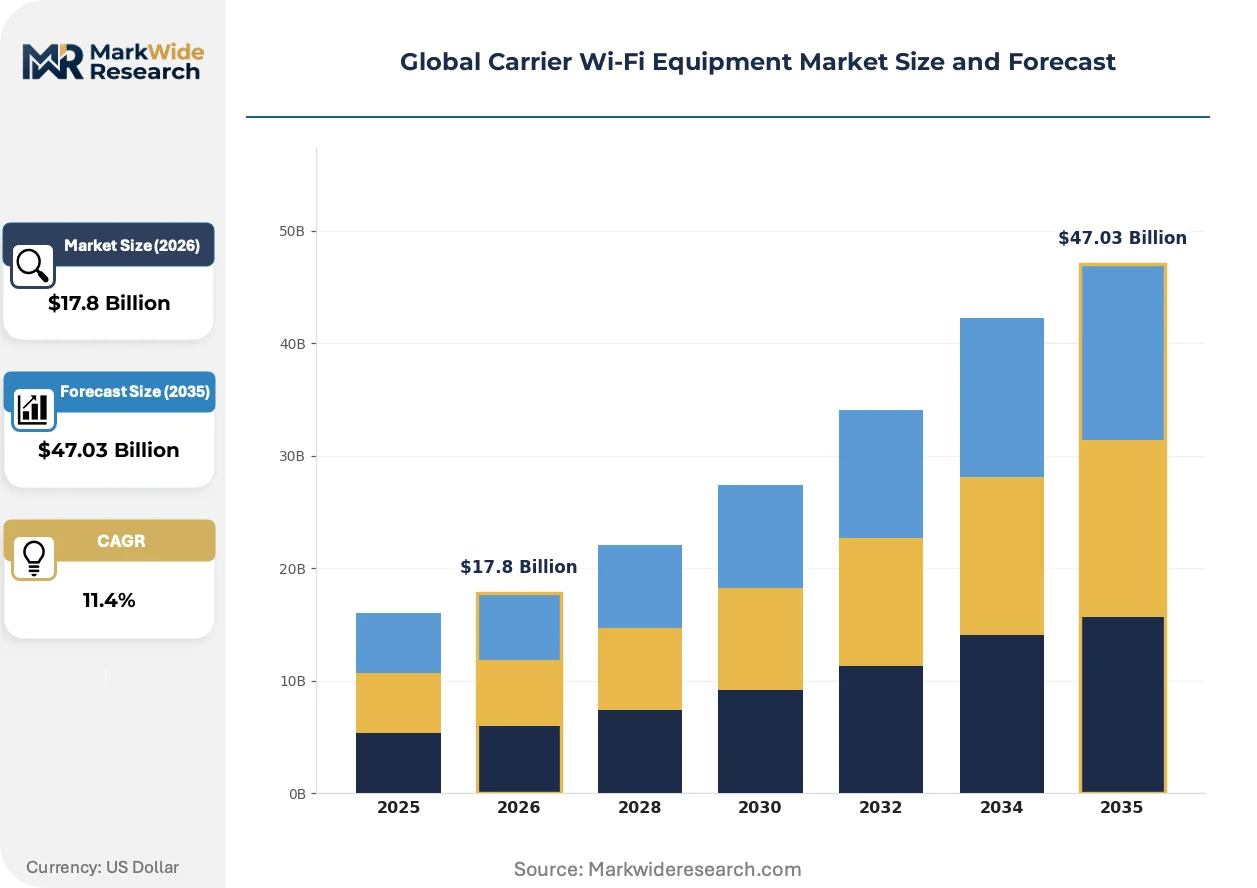
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $47.03 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Points, Controllers, Gateways, Network Interface Cards Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7 Application: Public Hotspots, Enterprise Networks, Transportation Nodes, Smart Cities, Hospitality Venues End User: Telecom Operators, Managed Service Providers, Internet Companies, Educational Institutions, Government Agencies |
| Companies Covered | Cisco Systems, Huawei Technologies, Nokia Corporation, Ericsson, Ruckus Networks, Extreme Networks, Aruba Networks, ADTRAN, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carrier Wi-Fi Equipment Market Shifts & Advancements
Radio architecture is compressing toward single-chip solutions that collapse MAC, baseband, and RF front-end functions, eroding the historical separation between enterprise and carrier-grade equipment tiers.
Wi-Fi 7 silicon is miniaturizing across 320 MHz channel bonding and 4K-QAM modulation, enabling multi-gigabit throughput in access points no larger than paperback books. Stadium operators in Spain and Australia are piloting these compact radios for rapid redeployment between event configurations. The form-factor reduction is eliminating the dedicated equipment room, pushing compute and power distribution into ceiling tile enclosures.
The EU's Wi-Fi 6E implementation decision and subsequent ETSI harmonization are mandating automated frequency coordination databases for standard-power outdoor operations. Equipment vendors must embed geolocation-aware firmware that queries these databases before channel selection, adding software complexity but preventing interference with incumbent satellite services. Outdoor stadium and smart city deployments across France, Germany, and Italy face the steepest compliance ramps.
Enterprise buyers are consolidating network operations under telecom operator managed service contracts, displacing traditional value-added reseller maintenance agreements. German automotive suppliers and Singaporean healthcare campus operators now specify performance-based SLAs covering latency, roaming handoff times, and mean-time-to-repair rather than hardware refresh cycles. This procurement compression rewards vendors with existing carrier relationships and global network operations centers.
Global Carrier Wi-Fi Equipment Market Segmentation
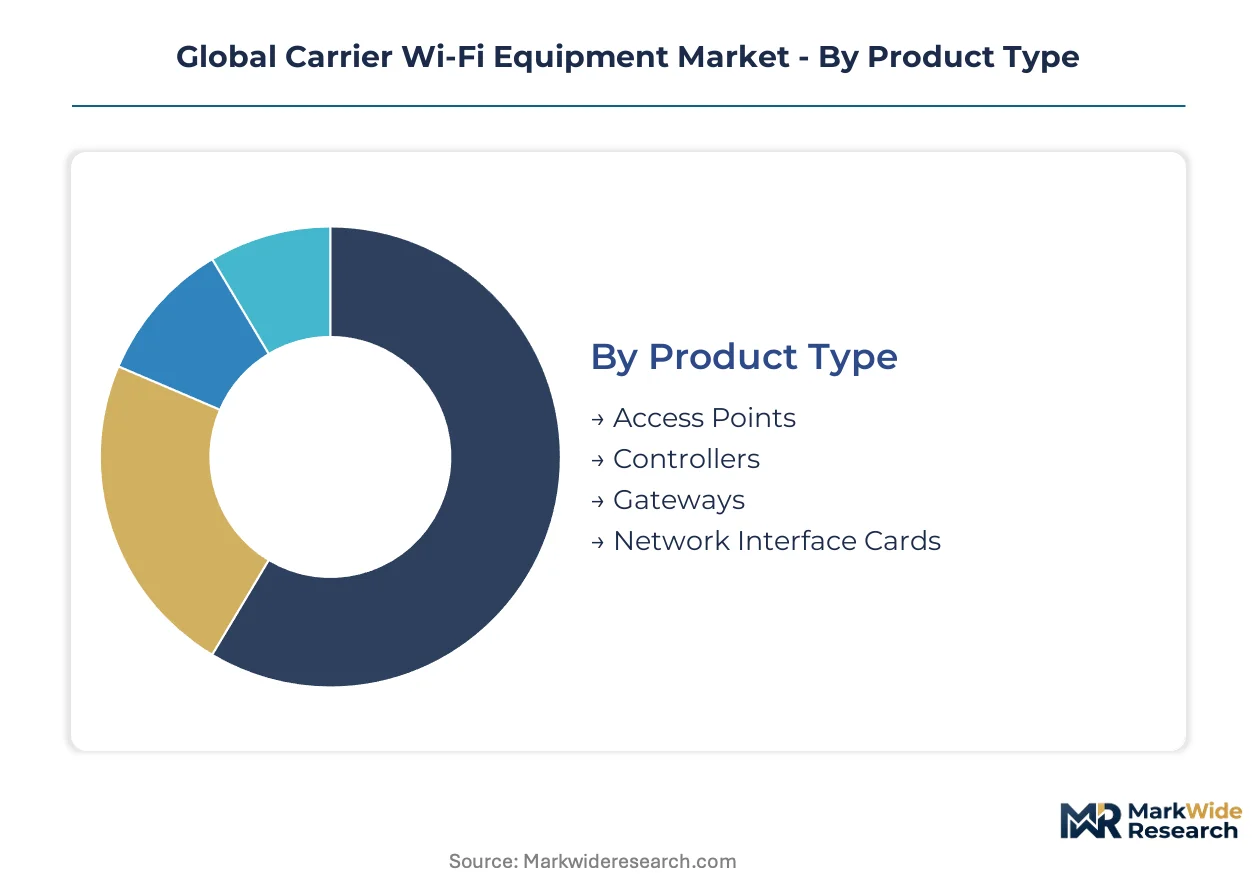
Carrier Wi-Fi equipment procurement patterns diverge sharply across product architectures, spectrum generations, and buyer categories. Understanding these fault lines reveals where margin pools concentrate and which segments command premium pricing versus commodity throughput.
Product Type:
Access points and controllers flow disproportionately to export-led deployments in Asia-Pacific and Middle Eastern smart city programs, while gateways and network interface cards serve more domestically anchored enterprise refresh cycles in North America and Europe.
- Access Points:Dual-radio and tri-radio units integrating 802.11ax or 802.11be basebands with automated frequency coordination for 6 GHz outdoor operations. Dense urban corridors in China and stadium complexes in Spain absorb the highest volumes as operators offload licensed spectrum congestion.
- Controllers:Cloud-native platforms managing authentication, policy enforcement, and roaming federation across thousands of distributed radios. North American telecom operators favor these for multi-tenant neutral-host deployments in airports and convention centers where subscriber density peaks.
- Gateways:Edge aggregation devices bridging cellular core networks with unlicensed radio access layers. German automotive campuses deploy these for factory-floor Wi-Fi 7 backhaul.
- Network Interface Cards:Modular radio cards for integration into third-party enclosures and custom industrial housings. Japanese building automation integrators specify these for combined energy-security-network managed service bundles.
Access points hold the largest share; momentum sits with cloud-native controllers as operators reclaim indoor connectivity ownership from enterprise IT departments.
Technology:
Procurement volume stratifies across cost-performance tiers, with Wi-Fi 6 anchoring mid-market refresh cycles and Wi-Fi 7 commanding premium bids for latency-sensitive industrial applications.
- Wi-Fi 5:Legacy 802.11ac radios now confined to budget-constrained public hotspot extensions and developing market coverage fill-in. Brazilian operators still procure these for secondary transit corridors where spectral efficiency demands remain modest.
- Wi-Fi 6:802.11ax with OFDMA and 1024-QAM modulation dominates current procurement volumes across enterprise campus and hospitality verticals. Singaporean healthcare campuses specify these for density-optimized patient and staff connectivity.
- Wi-Fi 6E:Extended 6 GHz band access unlocking 160 MHz channels for interference relief in congested venues. French and German stadium operators face the steepest compliance ramps with ETSI-mandated automated frequency coordination databases.
- Wi-Fi 7:802.11be silicon with 320 MHz bonding and 4K-QAM enabling multi-gigabit throughput in ultra-compact form factors. Australian event venues pilot these for rapid radio redeployment between concert and sporting configurations.
Wi-Fi 6 anchors current procurement volume; Wi-Fi 7 is climbing the fastest as industrial IoT backhaul requirements stiffen.
Application:
Customer concentration varies by deployment maturity, with smart cities and transportation nodes consolidating under multi-year managed services while public hotspots fragment into thin-margin throughput commodities.
- Public Hotspots:Municipal and commercial open-access networks with minimal authentication layers. These mature deployments in North American retail corridors now compete primarily on price-per-gigabyte.
- Enterprise Networks:Campus and headquarters deployments requiring granular policy control and roaming integration with cellular subscriber databases. German automotive suppliers specify performance-based SLAs covering latency and handoff times.
- Transportation Nodes:Airport, railway, and port connectivity with high-density transient subscriber loads. Spanish and Italian operators prioritize these for Hotspot 2.0 roaming federation.
- Smart Cities:Unified public infrastructure spanning transit hubs, street furniture, and emergency response systems. Chinese municipal governments embed carrier-grade Wi-Fi into these multi-system contracts.
- Hospitality Venues:Hotel and resort networks where guest experience metrics drive procurement. Japanese operators bundle these with building automation and physical security under consolidated operations contracts.
Enterprise networks hold the largest share; smart cities are gaining share fastest as municipal infrastructure mandates proliferate.
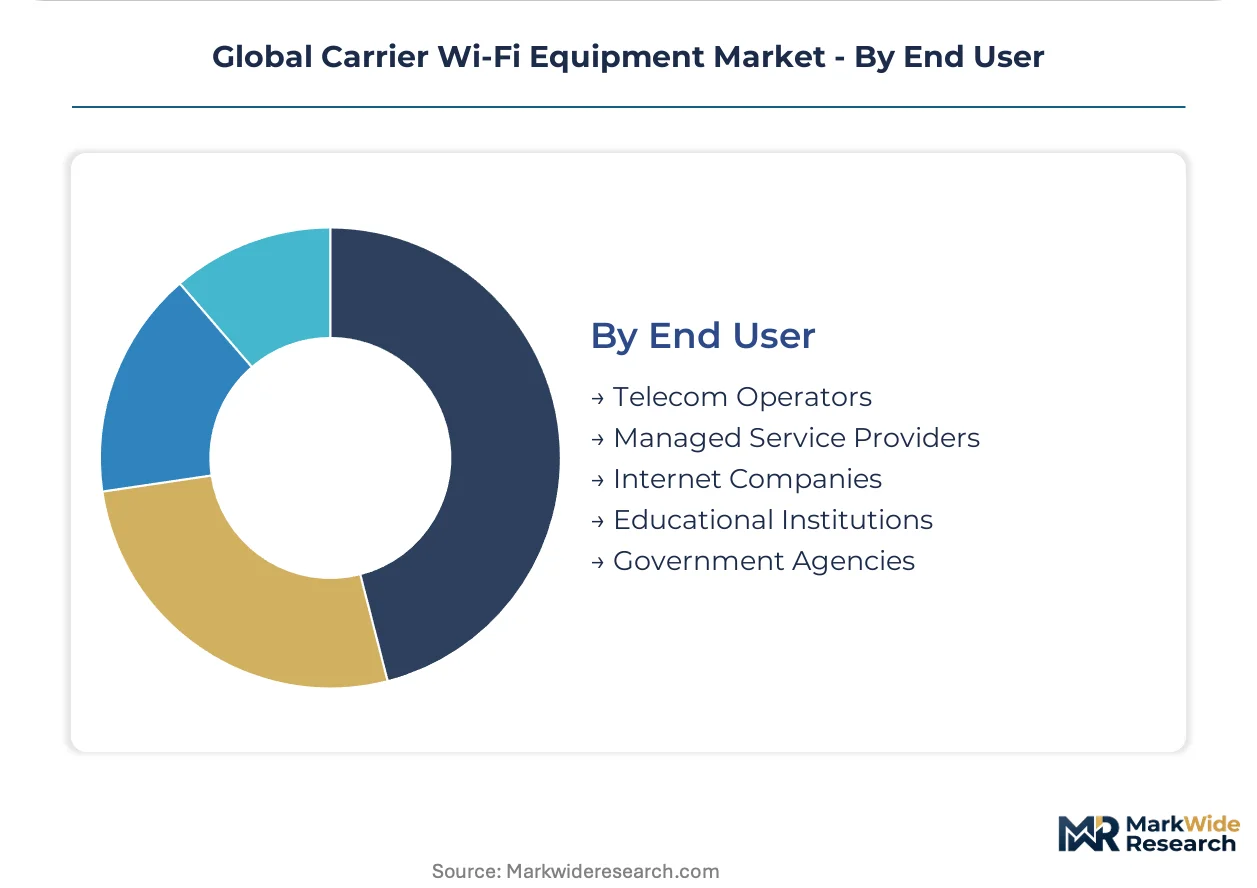
End User:
Buyer sophistication determines contract structure complexity, with telecom operators and managed service providers driving cloud-native architectural shifts while educational and government buyers lag on procurement modernization.
- Telecom Operators:Mobile network operators reclaiming indoor connectivity ownership and deploying neutral-host infrastructure. These buyers command the deepest vendor relationships and global network operations center requirements.
- Managed Service Providers:Third-party network operations specialists consolidating multi-site contracts under performance-based SLAs. Japanese building automation integrators exemplify this consolidation pattern.
- Internet Companies:Cloud and content providers extending edge presence through distributed Wi-Fi anchoring. These buyers prioritize rapid deployment velocity over long-term vendor entanglement.
- Educational Institutions:University and K-12 campus networks with budget-constrained refresh cycles. These segments lag in Wi-Fi 6E and Wi-Fi 7 adoption due to extended capital planning horizons.
- Government Agencies:Federal, state, and municipal procurement with domestic encryption and certification mandates. China's MIIT GB standards create parallel hardware tracks for these buyers.
Telecom operators hold the largest share; managed service providers are expanding most quickly as enterprise buyers outsource network operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters concentrate in Taiwan and mainland China, where advanced baseband silicon foundries anchor global supply chains for 802.11be radios. This geographic concentration creates lead-time vulnerability for premium Wi-Fi 7 tiers while shaping regional procurement patterns.
United States
Stadium and airport neutral-host deployments drive equipment demand as mobile operators reclaim indoor connectivity ownership. The FCC's CBRS spectrum sharing rules enable converged private 5G-Wi-Fi infrastructure models. Dallas-Fort Worth and Atlanta metropolitan clusters anchor multi-tenant managed service rollouts across transit hubs.
China
Municipal smart city mandates embed carrier-grade Wi-Fi into unified public infrastructure spanning transit and emergency systems. MIIT GB standards mandate domestic encryption modules, forcing parallel certification tracks for multinational vendors. Yangtze River Delta megacities concentrate dense-access-point procurement volumes.
Germany
Automotive factory floors specify Wi-Fi 7 backhaul for mobile robotics control under ultra-reliable low-latency requirements. ETSI harmonized 6 GHz rules mandate automated frequency coordination databases for outdoor operations. Bavarian industrial corridors pilot compact multi-gigabit radios for manufacturing automation.
Japan
Building automation integrators consolidate network operations contracts combining Wi-Fi assurance with energy management and physical security. METI industrial digitization programs subsidize private wireless infrastructure in manufacturing zones. Tokyo-Osaka corridor anchors premium managed service bundling for hospitality and commercial real estate.
Australia
Event venue operators pilot Wi-Fi 7 silicon for rapid radio redeployment between concert and sporting configurations. The country's national communications regulator governs 6 GHz power limits for outdoor stadium deployments. Melbourne and Sydney entertainment precincts concentrate compact form-factor trials.
Global Carrier Wi-Fi Equipment Market Competitive Landscape
Concentration sits with diversified telecom infrastructure conglomerates that span cellular and unlicensed spectrum portfolios. The vendor base separates into three strategic tiers: cloud-native platform specialists, silicon-to-software integrated manufacturers, and Open RAN interoperability champions. Competitive positioning hardens around M&A activity targeting roaming federation software and capacity expansion into 6 GHz radio fabrication.
Within the integrated infrastructure tier, Cisco Systems, Huawei Technologies, and Nokia Corporation exemplify contrasting architectural philosophies. Cisco Systems occupies a position as a North American cloud-native platform anchor. Huawei Technologies represents the silicon-to-software vertical integration model. Nokia Corporation sits within the Open RAN interoperability camp appealing to European operator diversification strategies.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Nokia Corporation |
| Ericsson |
| Ruckus Networks |
| Extreme Networks |
| Aruba Networks |
| ADTRAN |
| ZTE Corporation |
| Others |
Supply & Pricing Matrix
Foundry-scale economies in Taiwan anchor global 802.11be baseband production, compressing unit economics for Wi-Fi 7 silicon while simultaneously concentrating pricing power among integrated manufacturers with captive wafer access. This scale dynamic stratifies vendor tiers: cloud-native platform specialists absorb margin pressure through software recurring revenue, whereas hardware-dependent entrants face floor pricing set by vertically integrated competitors.
Pricing Analysis
Volume-discount tiering structures separate enterprise managed service bundles from commodity public hotspot hardware. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with MIIT GB-compliant modules commanding hardware premiums for Chinese government buyers. Pricing pressure stems from Brazilian and Indian operators delaying Wi-Fi 6E procurement until pending 6 GHz declassification resolves. Educational institutions exhibit highest price sensitivity due to extended capital planning horizons, while telecom operators prioritize total cost of ownership over upfront unit costs.
Supply Chain Analysis
Inventory lead-time vulnerability concentrates in Taiwan for advanced baseband fabrication and mainland China for final assembly and domestic encryption module integration. Raw material dependencies span gallium nitride substrates for RF front-ends, high-density PCB laminates, and specialized power amplifiers. Single-source vulnerability sits with concentrated foundry capacity for 802.11be chips. Distribution runs through telecom operator direct procurement for stadium and airport deployments, with systems integrators managing smart city and enterprise campus fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carrier Wi-Fi equipment market is recovering from supply-constrained trough conditions as foundry capacity normalization and 6 GHz spectrum liberalization unlock deferred procurement cycles. Capital expenditure intensity among mobile network operators is the named cyclical driver justifying recovery framing.
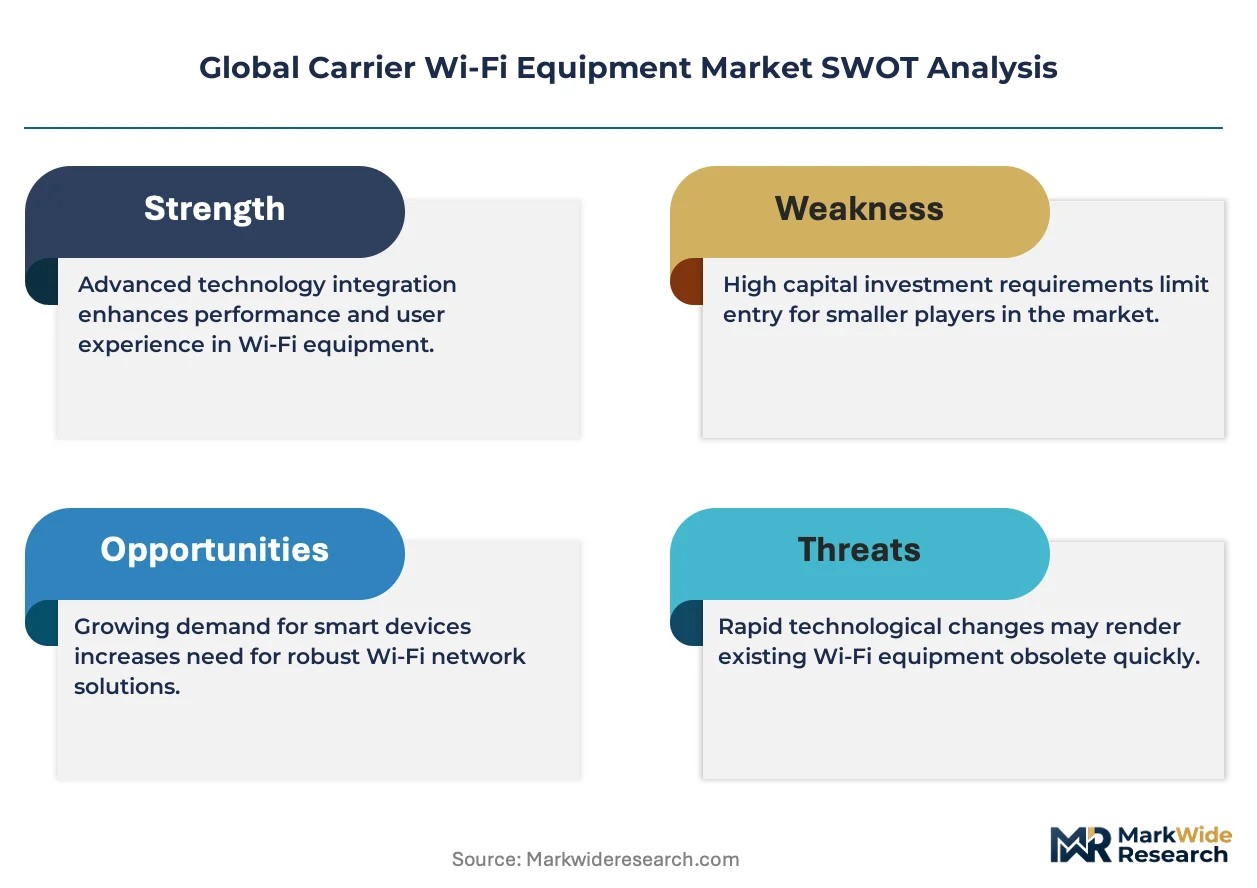
For Market Incumbents: Secure cloud-native controller platform dominance through API ecosystem expansion that locks in multi-tenant neutral-host deployments. Anchor 6 GHz radio fabrication capacity in Taiwan to defend against lead-time volatility threatening premium Wi-Fi 7 tiers. Vertical integration into automated frequency coordination software mitigates ETSI compliance cost inflation for European outdoor stadium contracts. For New Entrants and Emerging Players: Anchor in Japanese building automation integrator channels where Wi-Fi assurance bundles with energy management and physical security create service revenue attach opportunities. Target Australian event venue operators piloting rapid-redeployment Wi-Fi 7 configurations as the most penetrable geography for compact form-factor disruption. Lead with outcome-based SLAs covering latency and roaming handoff times rather than hardware specifications. For Investors and Strategic Acquirers: Roaming federation software specialists with Passpoint certification depth represent priority acquisition targets given multi-vendor interoperability testing bottlenecks delaying commercial launches. Long-term viability over the next decade hinges on private 5G-Wi-Fi convergence enablement under CBRS and similar spectrum-sharing frameworks. The signal to monitor is FCC and ETSI proceedings on 6 GHz power limit adjustments, which would instantly revalue outdoor stadium equipment inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Controller Platform Expansion | API ecosystem lock-in secures multi-tenant neutral-host revenue streams across North American transit hubs. |
| 6 GHz Radio Fabrication Capacity Addition | Taiwan foundry reservations defend Wi-Fi 7 lead times against silicon supply concentration risks. |
| Automated Frequency Coordination Software Investment | ETSI-compliant firmware accelerates European outdoor stadium deployment certification cycles. |
| Managed Service Bundling Partnership | Japanese building automation integrator channels combine Wi-Fi assurance with energy and security operations. |
| Private 5G-Wi-Fi Convergence Enablement | CBRS spectrum sharing rules unlock neutral-host infrastructure models serving cellular and unlicensed subscribers. |
Research Methodology
The analysis maps access point, controller, gateway, and network interface card sub-sectors, each validated through network operations center directors, RF engineering leads, telecom procurement officers, and smart city infrastructure planners. Primary interview insights triangulate against FCC docket filings, ETSI harmonization documents, MIIT GB standard releases, and hyperscaler capex disclosures. Bottom-up equipment shipment modeling and top-down operator expenditure tracking cross-validate volume and value outputs.
Consistency checks against external benchmarks validate projection outputs across the analysis window. Segmentation dimensions include product architecture, spectrum generation tier, deployment application, and end-user buyer sophistication. CAGRs derive from equipment procurement run-rate analysis and operator traffic offload economics modeling. Industry-specific forecast inputs incorporate 6 GHz regulatory proceeding timelines and foundry capacity utilization trajectories.
Material uncertainties — spectrum reclassification decisions in Brazil and India, foundry disruption events, and tariff regime adjustments — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory harmonization pace and silicon supply normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Home Networking Device Market
Network Technology
Gigabit Ethernet Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Europe Private 5G Network Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Wi-Fi Router Market
Network Technology
Managed MPLS Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Managed Switches Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Network Telemetry Market
Network Technology
Mobile Accelerator Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Residential Routers Market