
 5G Network Infrastructure Market | 2026-2036
5G Network Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
5G Network Infrastructure Market Analysis
3GPP Release 17 certification is reorganizing vendor eligibility across the 5G network infrastructure supply base. Nokia Corporation leverages its Open RAN portfolio to sustain European operator relationships. Huawei Technologies Co., Ltd. anchors its position through integrated baseband-to-antenna systems. Samsung Electronics Co., Ltd. competes aggressively in millimeter wave subsystems for North American carriers.
5G network infrastructure comprises radio access networks, transport networks, and core networks operating across sub-6 GHz and millimeter wave spectrum bands with latency targets below one millisecond for ultra-reliable low-latency communication. The primary purpose is enabling massive machine-type communications, enhanced mobile broadband, and critical IoT services for industrial automation and connected mobility. Cloud RAN architectures are attracting capital as operators virtualize baseband processing to reduce site costs and improve spectral efficiency. Macro Cells still generate the majority of installed base revenue, though Small Cells are expanding fastest in dense urban corridors where spectrum reuse demands multiply. Network Slicing capabilities are creating new margin pools for telecom operators selling differentiated quality-of-service guarantees to enterprise verticals.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct spectrum allocation frameworks and equipment authorization regimes that determine which vendors qualify for national 5G rollouts. These regulatory divergences fragment procurement standards and force multi-market suppliers to maintain parallel certification tracks. Stakeholders must monitor evolving open interface mandates and spectrum reallocation proceedings to anticipate shifts in vendor competitiveness and deployment economics.

Market Dynamics
Open RAN interoperability mandates are fragmenting vendor qualification pathways and forcing multi-market suppliers to maintain parallel certification tracks across divergent national frameworks. This regulatory pressure is compressing incumbent advantages while creating entry points for specialized subsystem providers.
Growth Catalysts
- Industrial Automation Demand:Smart manufacturing facilities in Germany are expanding private network deployments to enable ultra-reliable low-latency communication for robotic control systems and predictive maintenance workflows.
- ETSI Open Interface Mandates:European standardization bodies are accelerating disaggregation requirements that separate radio units from baseband processing, creating procurement flexibility for operator consortiums.
- Millimeter Wave Spectrum Allocation:North American carriers are densifying urban corridors with small cell architectures to exploit higher frequency bands for enhanced mobile broadband capacity.
Market Restraints
- Semiconductor Supply Concentration:Advanced baseband processor fabrication depends on concentrated East Asian foundry capacity, exposing deployment timelines to geopolitical friction and export control volatility.
- Site Acquisition Costs:Urban small cell rollouts face municipal permitting bottlenecks and recurring right-of-way fees that erode the unit economics of dense network architectures.
- Energy Input Volatility:Base station power consumption requirements expose operational expenditure budgets to electricity price fluctuations, particularly affecting markets with carbon-intensive grid mixes.
Strategic Opportunities
- Network Slicing Monetization:Telecom operators are developing differentiated quality-of-service guarantees for enterprise verticals, creating recurring revenue streams beyond connectivity provision.
- Cloud RAN Virtualization:Centralized baseband processing pools enable resource pooling across multiple cell sites, reducing hardware redundancy and improving spectral efficiency for capital-constrained carriers.
- South Korean Industrial Corridors:Manufacturing clusters around Busan and Ulsan present concentrated demand for private 5G networks supporting automated guided vehicles and digital twin implementations.
Industry Challenges
- Multi-Vendor Integration Complexity:Open RAN architectures require systems integration capabilities across radio units, distributed units, and centralized units from disparate suppliers, stretching operator engineering resources.
- Legacy 4G Core Interworking:Non-standalone deployment models demand seamless handover management between evolved packet cores and 5G cores, complicating service continuity assurance during transition phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Network Infrastructure Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Cells, Macro Cells, Cloud RAN, Distributed Antenna Systems Technology: Millimeter Wave, Sub-6 GHz, Beamforming, Network Slicing Installation: Indoor, Outdoor, Urban, Rural End User: Telecom Operators, Enterprises, Government, OEMs |
| Companies Covered | Huawei Technologies Co., Ltd., Nokia Corporation, Telefonaktiebolaget LM Ericsson, ZTE Corporation, Samsung Electronics Co., Ltd., Cisco Systems, Inc., Qualcomm Incorporated, NEC Corporation, Hewlett Packard Enterprise Development LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Network Infrastructure Market Emerging Trajectories
Deployment architectures are diverging between centralized cloud-native implementations and distributed edge configurations, with each path attracting distinct capital allocation strategies from operator groups. This technical schism is reshaping vendor relationship structures and subsystem procurement patterns.
Cloud RAN architectures are bifurcating the traditional baseband hardware market by virtualizing signal processing functions onto commercial off-the-shelf servers. Tier-one operators in Japan and South Korea are deploying centralized pools to serve multiple macro sites simultaneously. This consolidation is compressing dedicated hardware revenue streams while expanding software licensing and systems integration service contracts.
FCC spectrum reallocation proceedings are accelerating mid-band availability for 5G deployment while tightening equipment authorization requirements for foreign-sourced components. The industrial consequence is extended certification timelines for multi-market suppliers seeking US market entry. North American carriers are responding by diversifying vendor portfolios and pre-qualifying alternative radio suppliers ahead of procurement cycles.
Enterprise procurement patterns are fragmenting across build-operate-transfer models and pure equipment purchase arrangements, with automotive and logistics verticals favoring outcome-based network performance contracts. Systems integrators and managed service providers are capturing margin pools that previously accrued to infrastructure vendors. This shift is most visible in German automotive manufacturing clusters, where factory operators demand guaranteed latency thresholds rather than capital asset ownership.
5G Network Infrastructure Market Segmentation
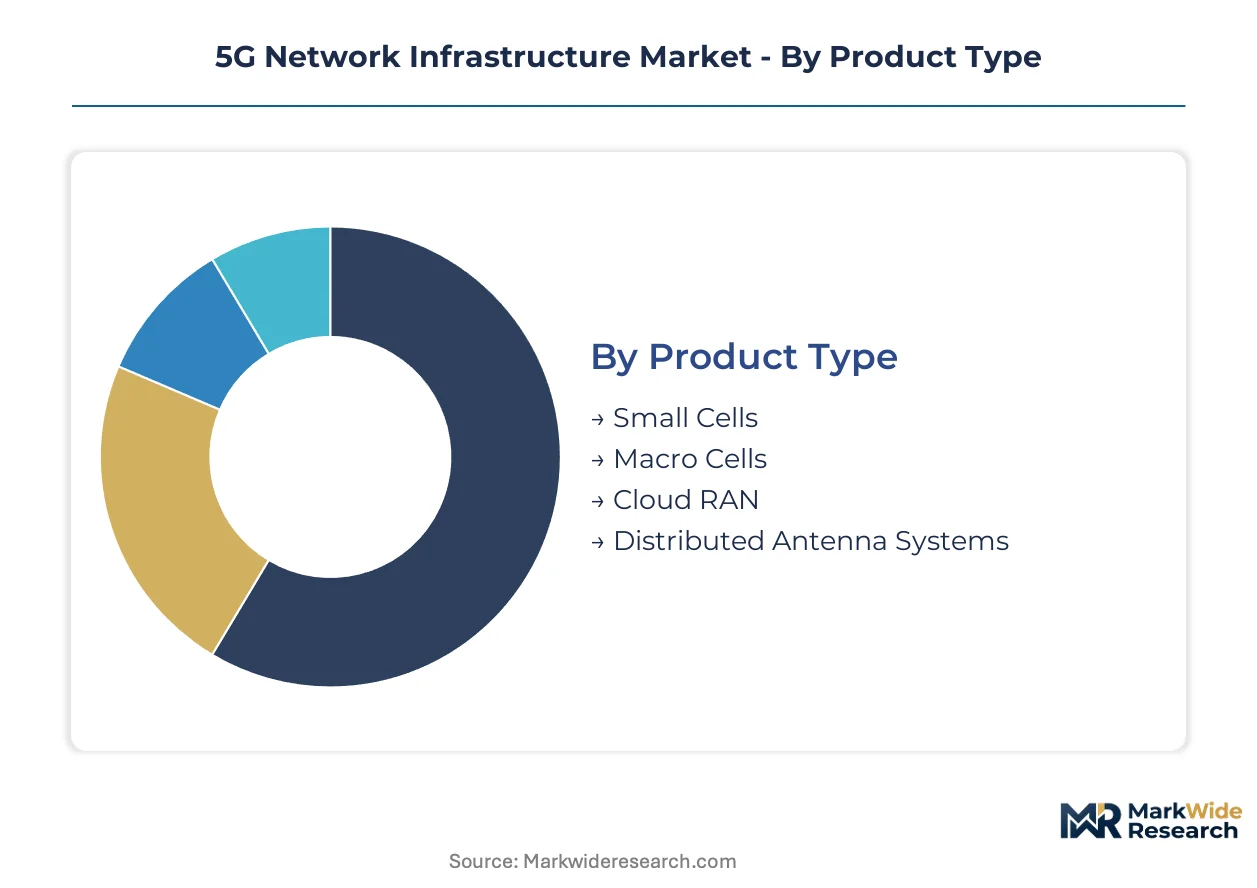
5G network infrastructure procurement patterns diverge sharply across deployment scenarios, spectrum bands, and buyer sophistication. Segmentation reveals where capital concentrates and which technical configurations command premium positioning.
Product Type:
FCC equipment authorization timelines and ETSI open interface mandates reshape procurement economics differently across hardware categories.
- Macro Cells:High-power base stations with integrated radio and antenna systems serve wide-area coverage requirements. German industrial corridors and South Korean manufacturing clusters anchor demand as operators prioritize reliability over density in initial rollout phases.
- Small Cells:Low-power nodes enable spectrum reuse in dense urban environments. North American carriers densify downtown corridors and stadium venues where municipal permitting bottlenecks constrain deployment velocity.
- Cloud RAN:Virtualized baseband processing pools consolidate signal processing onto commercial servers. Japanese operators lead centralized deployments serving multiple macro sites.
- Distributed Antenna Systems:Passive and active antenna networks extend coverage through buildings and tunnels. Airport and healthcare facility managers in the United States drive indoor penetration requirements.
Macro Cells handle the majority of throughput; Small Cells is the fastest mover on share.
Technology:
Cost tier differentiation separates premium beamforming implementations from commodity sub-6 GHz deployments.
- Sub-6 GHz:Mid-band spectrum delivers balanced coverage and capacity for broad deployment. Rural municipalities in the United States leverage this band where millimeter wave propagation fails.
- Millimeter Wave:High-frequency bands above 24 GHz enable multi-gigabit throughput over short distances. Verizon and AT&T densify urban corridors despite rain fade susceptibility.
- Beamforming:Active antenna systems with phased arrays concentrate signal energy toward user equipment. South Korean carriers deploy massive MIMO configurations in Seoul metropolitan zones.
- Network Slicing:Virtual network partitioning enables differentiated quality-of-service guarantees. German automotive manufacturers purchase guaranteed latency tiers for robotic control systems.
Sub-6 GHz carries the bulk of connected devices; Network Slicing is climbing the fastest as enterprise verticals adopt outcome-based contracts.
Installation:
Application context determines power requirements, backhaul topology, and regulatory exposure.
- Outdoor:Street-level and rooftop deployments dominate carrier capex. Urban small cell rollouts face recurring right-of-way fees that erode unit economics.
- Indoor:Enterprise-owned distributed systems penetrate manufacturing floors and logistics hubs. Private 5G networks in Busan shipyards rely on indoor coverage for automated guided vehicles.
- Urban:Dense population centers demand heterogeneous network architectures combining macro and small cell layers. Site acquisition costs concentrate procurement decisions.
- Rural:Sparse subscriber density challenges return-on-investment calculations. USDA rural development programs in the United States subsidize coverage expansion.
Outdoor installations absorb the largest capital allocation; Indoor deployments are expanding most quickly as enterprises bypass public networks.
End User:
Customer type dictates contract structure, performance guarantees, and vendor relationship intensity.
- Telecom Operators:Mobile network operators purchase equipment through multi-year framework agreements. Deutsche Telekom and SK Telecom drive Open RAN interoperability requirements into procurement specifications.
- Enterprises:Manufacturing, logistics, and energy firms acquire private network infrastructure. German automotive clusters demand guaranteed latency thresholds rather than asset ownership.
- Government:Defense and public safety agencies procure hardened infrastructure with sovereign supply chain requirements. FCC rip-and-replace programs affect vendor qualification.
- OEMs:Systems integrators and managed service providers bundle infrastructure with implementation services. Margin pools shift from hardware vendors to service layers.
Telecom Operators remain the dominant revenue source; Enterprises are gaining share fastest as private network adoption accelerates.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators anchor procurement volume across industrialized economies, while enterprise verticals concentrate demand in manufacturing corridors where private network latency guarantees command premium positioning.
United States
Verizon and AT&T densify urban corridors with millimeter wave small cell architectures. FCC equipment authorization timelines extend certification tracks for multi-market suppliers. Seattle and Austin metro areas concentrate cloud-native RAN development activity.
Germany
Deutsche Telekom drives Open RAN interoperability requirements into procurement specifications for smart manufacturing facilities. ETSI open interface mandates accelerate radio-baseband disaggregation. Bavarian automotive clusters demand guaranteed latency thresholds for robotic control systems.
South Korea
SK Telecom and KT Corporation deploy massive MIMO configurations across Seoul metropolitan zones. MIIT spectrum frameworks in neighboring China create parallel certification pressures for regional suppliers. Busan-Ulsan industrial corridors anchor private 5G network demand for automated guided vehicles.
Japan
NTT Docomo and KDDI virtualize baseband processing onto centralized server pools serving multiple macro sites. METI industrial policy incentivizes domestic equipment procurement. Tokyo-Osaka corridor concentrates cloud RAN deployment velocity.
China
China Mobile and China Telecom expand integrated baseband-to-antenna systems across Yangtze River Delta manufacturing zones. MIIT enforces distinct spectrum allocation frameworks determining vendor qualification for national rollouts. Shenzhen and Beijing anchor domestic equipment supply chain concentration.
5G Network Infrastructure Market Vendor Landscape
Player mix skews toward integrated infrastructure vendors with end-to-end radio-to-core portfolios, though Open RAN disaggregation is creating entry points for specialized subsystem providers. Tier-one operators favor suppliers with multi-market certification capabilities. Strategic archetypes include integrated stack vendors, disaggregated radio specialists, and cloud-native software providers. Competitive moves center on interoperability certification investments and geographic diversification of manufacturing footprints.
Among integrated infrastructure vendors, Huawei Technologies Co., Ltd. and Nokia Corporation exemplify contrasting approaches to operator relationships. Samsung Electronics Co., Ltd. occupies a position within the millimeter wave subsystem tier. These entities represent archetypes rather than exhaustive market coverage, with each anchoring distinct competitive vectors based on portfolio breadth and geographic certification scope.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| ZTE Corporation |
| Samsung Electronics Co., Ltd. |
| Cisco Systems, Inc. |
| Qualcomm Incorporated |
| NEC Corporation |
| Hewlett Packard Enterprise Development LP |
| Others |
Supply Flow & Price Mechanics
Long-term framework agreements with semiconductor foundries lock in baseband processor supply and provide cost visibility against volatile wafer pricing. These contractual structures insulate Tier-1 operators from spot-market fluctuations while constraining margin flexibility for equipment vendors competing on total cost of ownership.
Pricing Analysis
Cost-plus contracts indexed to silicon wafer spot prices dominate baseband processor procurement between equipment vendors and foundry partners. Pricing stratifies across Open RAN certification tiers, with 3GPP Release 17 compliance commanding premiums over legacy implementations. Cost compression in small cell subsystems intensifies as municipal permitting delays stretch deployment timelines and erode project returns. Enterprise buyers in German automotive clusters demonstrate lowest price sensitivity, prioritizing guaranteed latency thresholds over capital expenditure minimization.
Supply Chain Analysis
Taiwan and South Korea anchor advanced baseband processor fabrication, with concentrated foundry capacity feeding radio unit assembly operations in China and Vietnam. Supply chains draw from gallium nitride substrates, high-frequency RF components, and specialized thermal management materials. Single-source vulnerability in 7nm and 5nm process nodes exposes deployment schedules to export control volatility. Distribution runs through direct OEM relationships with tier-one operators, supplemented by systems integrator channels for enterprise private network deployments.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability mandates are accelerating vendor displacement across a high-growth infrastructure expansion, with regulatory certification requirements creating asymmetric barriers to market participation.
For Market Incumbents: Consolidate around multi-market certification capabilities to defend against specialized subsystem entrants exploiting ETSI and FCC interface mandates. Prioritize backward integration into baseband processor design to reduce exposure to East Asian foundry concentration. Secure long-term supply agreements with alternative radio unit suppliers ahead of procurement cycle renewals. For New Entrants and Emerging Players: Differentiate on cloud-native software stacks for centralized unit deployments, targeting Japanese and South Korean operators virtualizing baseband processing pools. Focus initial penetration on indoor private network segments in Busan-Ulsan industrial corridors where public carrier coverage gaps create procurement urgency. Pursue outcome-based performance contracts with German automotive manufacturers seeking guaranteed latency tiers rather than equipment ownership. For Investors and Strategic Acquirers: Disaggregated radio specialists with O-RAN Alliance certification and proven interoperability testing present acquisition targets with embedded growth optionality. Long-term viability hinges on sustained capital allocation to cloud RAN virtualization and millimeter wave subsystem development. Monitor FCC equipment authorization timeline extensions as early indicators of vendor competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | ETSI and FCC mandates are restructuring vendor qualification pathways across European and North American procurement cycles. |
| Cloud RAN Virtualization Investment | NTT Docomo and KDDI deployments demonstrate capital efficiency gains from centralized baseband processing pools. |
| Millimeter Wave Subsystem Development | Verizon and AT&T densification programs create procurement volume for high-frequency radio unit specialists. |
| Private Network Systems Integration | German automotive clusters are shifting margin pools from hardware vendors to managed service providers. |
| Alternative Foundry Qualification | Geopolitical friction is forcing diversification away from concentrated Taiwan and South Korea fabrication capacity. |
Methodological Framework
Cross-validation between operator procurement disclosures and vendor certification filings anchors the qualitative findings in documented market activity. Primary interviews with network planning executives, regulatory affairs specialists, and systems integration architects combined with secondary validation from FCC equipment authorization databases, ETSI standardization proceedings, and 3GPP release documentation. Bottom-up segmentation modeling triangulates against top-down infrastructure capex forecasts from disclosed operator guidance.
Sensitivity analysis across deployment scenario probabilities tests forecast robustness over the projection horizon. Segmentation dimensions include product type, spectrum band, installation environment, and end-user archetype, with regional regulatory cluster as an additional modeling layer. CAGRs derive from installed base replacement cycles and greenfield deployment velocity, incorporating MIIT spectrum allocation timelines and USDA rural development subsidy trajectories as industry-specific inputs.
Material uncertainties — semiconductor export control expansion, municipal permitting regime changes, and electricity price volatility — sit outside the modeled envelope. Forecasts reflect assumptions about sustained industrial automation demand and Open RAN standardization convergence. Recalibration cycles align with material shifts in regulatory certification requirements and spectrum reallocation proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Israel Telecom Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Canada Telecom Towers Market