
 Cell Tracing and Tracking Test Market | 2026-2036
Cell Tracing and Tracking Test Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Tracing and Tracking Test Market Outlook
A shift from single-source fluorescent dye procurement to multi-source supply strategies is expanding across pharmaceutical quality control labs. Thermo Fisher Scientific leverages its vertically integrated chemical synthesis network to secure raw material access for proprietary label chemistries. Bio-Rad Laboratories sustains competitive positioning through concentrated R&D spending on multiplexed imaging reagents. Danaher Corporation anchors its presence via diagnostic workflow integration across cell analysis platforms.
Cell tracing and tracking tests comprise labeled detection systems—fluorescent, bioluminescent, radioactive, or nanoparticle-based—that enable real-time monitoring of cell migration, proliferation, and differentiation through microscopy, flow cytometry, or PCR-based readout, with typical label concentrations ranging from nanomolar to micromolar depending on target abundance and detection modality. These tests serve fundamental roles in validating cell therapy potency, quantifying tumor metastasis models, and mapping developmental lineages in regenerative medicine research. Fluorescent labels occupy the largest revenue share due to established protocol compatibility and instrument ubiquity, while nanoparticle tracers represent the fastest-expanding category driven by quantum dot brightness and reduced photobleaching in longitudinal studies. Cancer Research commands the highest application-specific margins, as tracer validation for immuno-oncology trials demands custom conjugation services and extended stability testing.
The FDA enforces cell therapy product characterization standards under 21 CFR 1271, directly mandating traceability validation for ex vivo modified cell products. EMA's ATMP guidelines and ISO 10993 biocompatibility frameworks further shape reagent qualification requirements for European clinical translation. Stakeholders must monitor evolving GMP tracer documentation standards and pre-emptively qualify alternative label chemistries before supply disruptions or regulatory reclassifications constrain manufacturing continuity.
Market Dynamics
CRISPR lineage mapping protocols are forcing fluorescent label manufacturers to revalidate photostability specifications under accelerated degradation testing, compressing product development cycles and tightening quality gates across supply chains.
Growth Catalysts
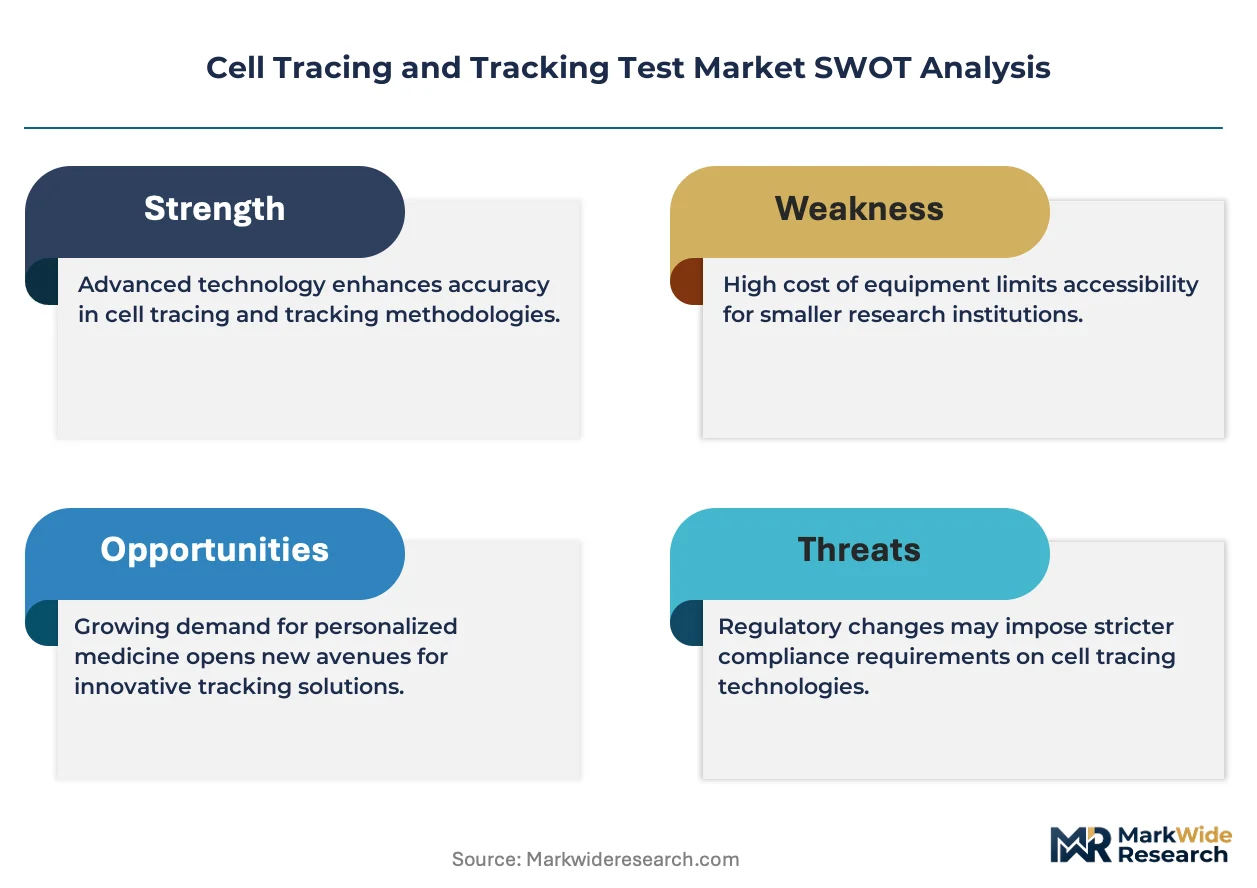
- 21 CFR 1271 Traceability Mandates:FDA cell therapy characterization rules require validated tracer stability documentation, driving reagent procurement upgrades across ex vivo modification facilities in the United States.
- Quantum Dot Brightness Advantages:Nanoparticle tracers with reduced photobleaching properties are displacing organic fluorophores in longitudinal stem cell tracking studies.
- NIH-Funded Consortia Concentration:Massachusetts and California anchor purchasing volume through dedicated stem cell research infrastructure, creating demand density for multiplexed imaging reagents.
Market Restraints
- Rare Earth Element Supply Concentration:Quantum dot manufacturing depends on cadmium and indium feedstocks concentrated in Chinese processing facilities, exposing label producers to export restriction risk.
- GMP Documentation Burden:EMA ATMP guidelines impose extensive batch record requirements for clinical-grade tracers, extending qualification timelines for European market entry.
- Radioisotope Half-Life Limitations:PET-based cell tracking faces technical constraints from short-lived isotopes like fluorine-18, restricting longitudinal observation windows in oncology studies.
Strategic Opportunities
- Bioluminescent Reporter Convergence:Luciferase imaging is merging with CRISPR knock-in techniques to enable non-invasive whole-body cell tracking without tissue autofluorescence interference.
- ISO 10993 Pre-Qualification:Early biocompatibility testing alignment creates competitive positioning for suppliers targeting European regenerative medicine translation pipelines.
- Academic Kit Standardization:German research organizations are consolidating procurement around validated fluorescent label panels, opening volume contracts for qualified reagent vendors.
Industry Challenges
- Multiplex Spectral Overlap:Simultaneous detection of five or more fluorescent labels demands complex compensation algorithms, straining microscopy workflow integration in quality control labs.
- Cross-Platform Validation Gaps:Tracer performance varies between flow cytometry and confocal microscopy readouts, forcing redundant qualification studies for multi-modal research programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Tracing and Tracking Test Market |
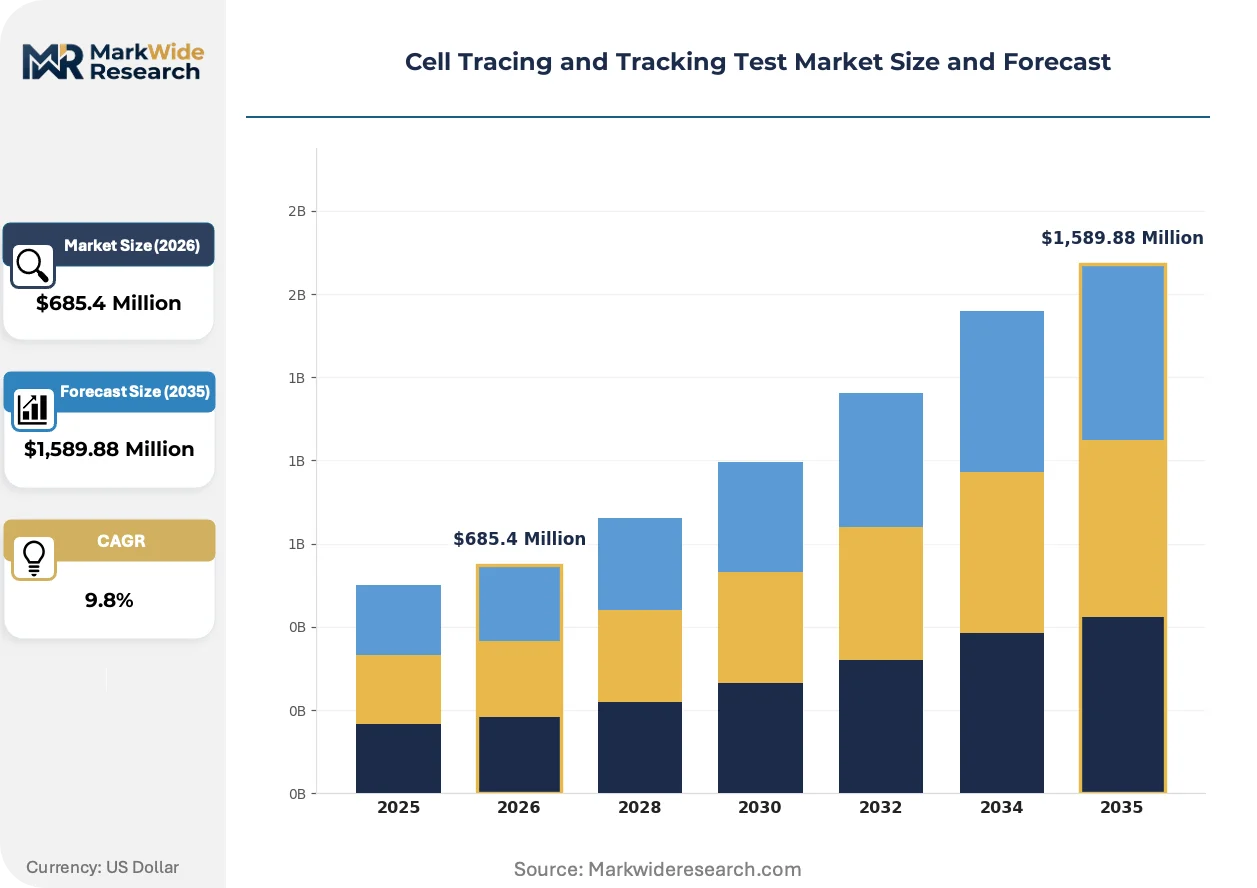
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,589.88 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Labels, Bioluminescent Tags, Radioactive Tracers, Nanoparticles Application: Cell Biology, Drug Development, Tissue Engineering, Cancer Research Technology: Microscopy, Flow Cytometry, Imaging Systems, PCR Technology End User: Research Institutions, Pharmaceutical Companies, Biotech Firms, Academic Organizations |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Bio-Rad Laboratories, PerkinElmer, Agilent Technologies, BD, Danaher Corporation, Miltenyi Biotec, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Tracing and Tracking Test Market Strategic Shifts
Near-infrared fluorescent proteins are displacing visible-spectrum labels in deep-tissue imaging applications, while regulatory documentation requirements are hardening around tracer stability validation protocols.
Quantum dot nanocrystals is expanding into longitudinal developmental biology studies where photobleaching resistance determines experimental feasibility. Academic consortia in Germany and the United States are adopting these materials for CRISPR lineage tracing despite higher per-test costs. The technology is expanding into previously inaccessible observation windows, compressing the viable market position of organic dye alternatives.
EMA's updated ATMP guidelines now mandate extended stability testing for ex vivo modified cell product characterization. European clinical translation programs must document tracer performance across 24-month storage conditions before regulatory submission. Cell therapy developers in Germany and Switzerland are responding by pre-qualifying alternative label chemistries to avoid manufacturing continuity disruption.
Consolidated procurement through NIH-funded stem cell research consortia is displacing decentralized laboratory purchasing in the United States. Massachusetts and California research clusters now negotiate multi-year reagent supply agreements with embedded technical support services. This concentration is most visible in fluorescent label kit purchasing, where volume discounts and protocol standardization drive vendor selection criteria.
Cell Tracing and Tracking Test Market Segmentation
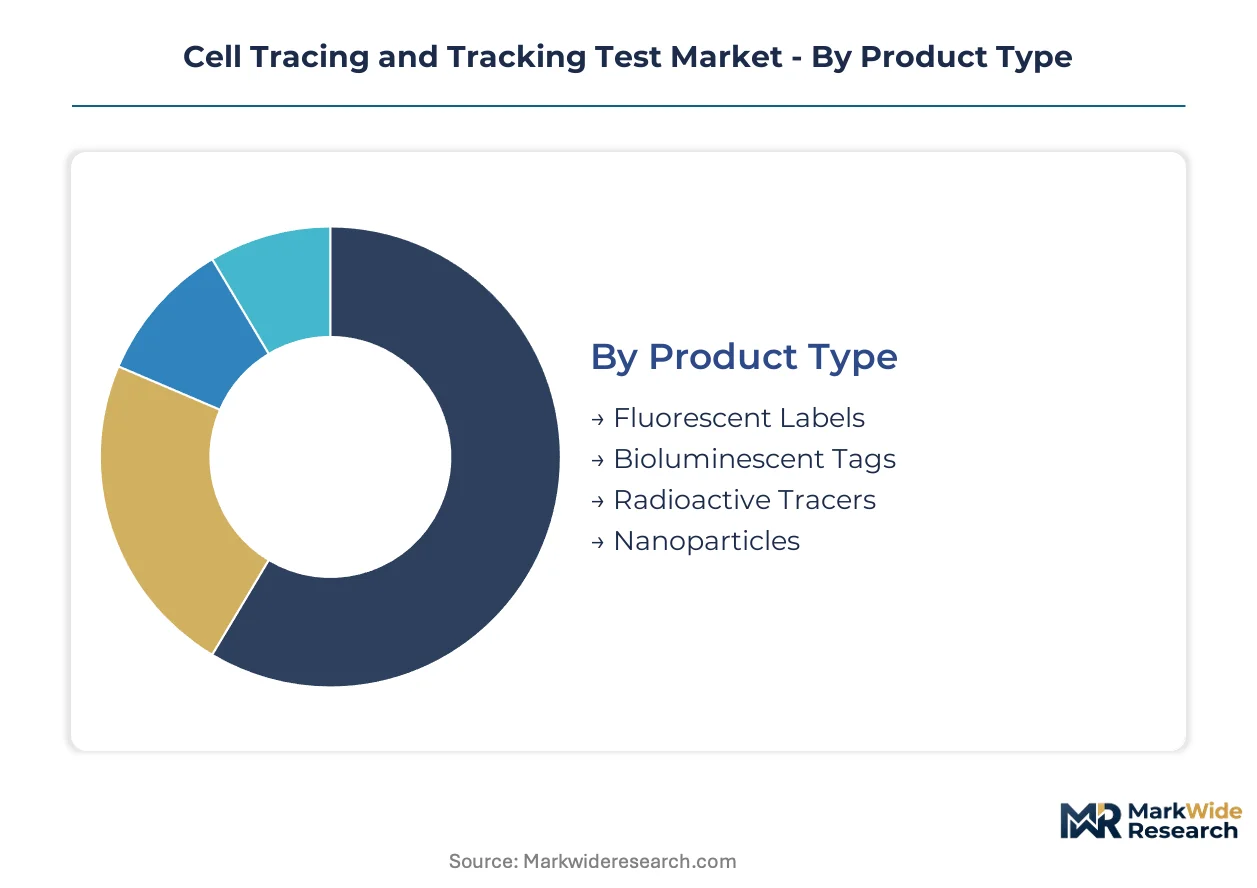
Tracer selection determines experimental feasibility across longitudinal studies. Each segmentation axis shapes procurement patterns, validation requirements, and pricing structures for cell tracking reagents.
Product Type:
Photostability specifications and detection sensitivity separate commercial-grade from research-grade tracers.
- Fluorescent Labels:Organic dyes and fluorescent proteins dominate current procurement volumes due to established protocol compatibility with existing microscopy infrastructure. Demand concentrates in Massachusetts and California stem cell consortia, where NIH-funded facilities require validated label panels for CRISPR lineage mapping.
- Nanoparticles:Quantum dot nanocrystals deliver superior brightness and photobleaching resistance for extended observation windows. German academic organizations are scaling procurement of cadmium-based and cadmium-free variants for developmental biology studies despite higher per-test costs.
- Bioluminescent Tags:Luciferase-based reporters enable non-invasive whole-body tracking without tissue autofluorescence interference.
- Radioactive Tracers:PET-based cell tracking using short-lived isotopes serves oncology applications with constrained longitudinal windows.
Mature deployment sits with fluorescent labels. Newer deployment is concentrated in nanoparticles.
Application:
Regulatory stringency and customization requirements determine margin structures across use cases.
- Cancer Research:Immuno-oncology trials demand custom conjugation services and extended stability testing, producing the highest application-specific margins. FDA cell therapy characterization rules under 21 CFR 1271 mandate traceability validation for ex vivo modified cell products.
- Cell Biology:Fundamental research applications drive volume procurement of standardized label kits with established photostability specifications.
- Drug Development:Pharmaceutical quality control labs require multi-source supply strategies and redundant qualification studies for tracer validation.
- Tissue Engineering:Regenerative medicine translation pipelines in Germany and Switzerland require ISO 10993 biocompatibility pre-qualification for clinical-grade tracers.
Revenue concentration sits with cancer research. Fastest expansion is occurring in tissue engineering.
Technology:
Instrument ubiquity and workflow integration shape vendor selection criteria across detection platforms.
- Microscopy:Confocal and widefield systems anchor fluorescent label consumption through established protocol libraries. Multiplex spectral overlap challenges strain workflow integration when simultaneous detection exceeds five labels.
- Flow Cytometry:High-throughput single-cell analysis demands tracer performance validation distinct from microscopy readouts, forcing redundant qualification studies.
- Imaging Systems:Whole-body bioluminescence and near-infrared imaging platforms serve longitudinal stem cell tracking without tissue autofluorescence.
- PCR Technology:Genomic integration assays validate cell lineage through quantitative detection of tracer-associated sequences.
Established deployment sits with microscopy. Emerging deployment is concentrated in imaging systems.
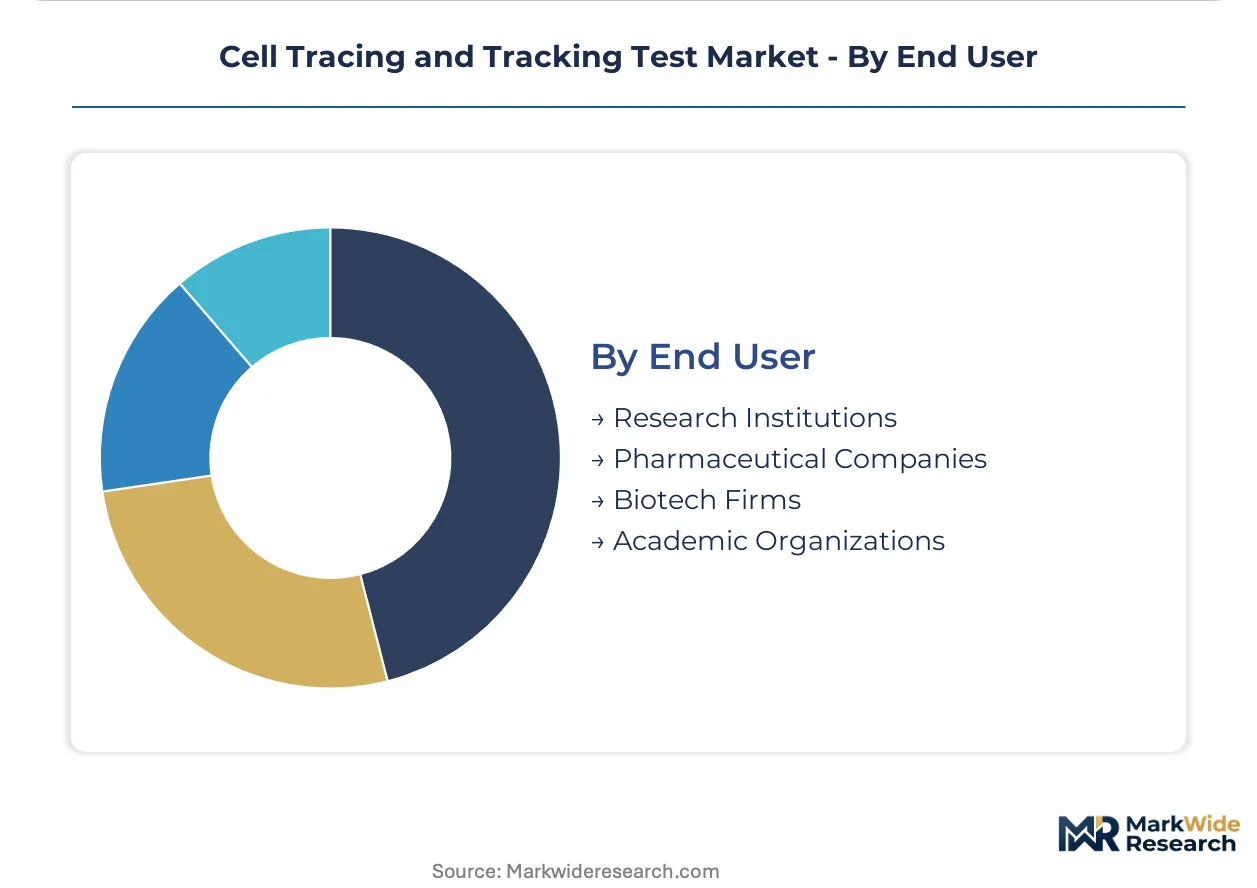
End User:
Purchasing consolidation and technical support requirements differentiate customer segments.
- Academic Organizations:German research institutions are consolidating procurement around validated fluorescent label panels, opening multi-year volume contracts for qualified reagent vendors with embedded technical services.
- Research Institutions:NIH-funded stem cell consortia in the United States anchor demand density through dedicated infrastructure and protocol standardization.
- Pharmaceutical Companies:Quality control labs require GMP documentation and batch record compliance for clinical translation programs.
- Biotech Firms:Cell therapy developers pre-qualify alternative label chemistries to avoid manufacturing continuity disruption from supply constraints or regulatory reclassification.
Volume concentration sits with academic organizations. Procurement sophistication is highest among biotech firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cadmium and indium processing facilities in China anchor raw material access for quantum dot manufacturing, while NIH-funded research infrastructure in the United States and academic procurement consolidation in Germany concentrate demand for fluorescent label systems.
United States
Massachusetts and California stem cell consortia anchor purchasing volume for multiplexed imaging reagents. FDA 21 CFR 1271 mandates traceability validation for ex vivo modified cell products, tightening reagent qualification requirements. Boston-Cambridge and San Francisco Bay Area clusters negotiate multi-year supply agreements with embedded technical support services.
Germany
Academic organizations are consolidating procurement around validated fluorescent label panels for CRISPR lineage studies. EMA ATMP guidelines impose extensive batch record requirements for clinical-grade tracers, extending European market entry timelines. Heidelberg and Munich research institutes open volume contracts for qualified reagent vendors with protocol standardization mandates.
China
Rare earth element processing concentration in Chinese facilities supplies cadmium and indium feedstocks for quantum dot manufacturing. NMPA cell therapy characterization standards align with international traceability requirements for modified cell products. Shanghai and Beijing biotech clusters scale domestic tracer production to reduce import dependency for longitudinal stem cell studies.
Switzerland
Cell therapy developers pre-qualify alternative label chemistries to avoid manufacturing continuity disruption. Swissmedic enforces stability documentation standards for ATMP characterization protocols matching EMA frameworks. Basel and Zurich regenerative medicine pipelines require ISO 10993 biocompatibility pre-qualification for clinical-grade tracer deployment.
Japan
PMDA guidelines for regenerative medicine products mandate validated tracer stability documentation for cell therapy submissions. Tokyo and Osaka research clusters adopt near-infrared fluorescent proteins for deep-tissue imaging applications. METI funding programs support domestic quantum dot development to reduce reliance on Chinese rare earth supply chains.
Cell Tracing and Tracking Test Market Competitive Environment
Global majors compete with regional champions across reagent supply networks, with vertically integrated chemical synthesis operations facing specialized imaging technology developers. The vendor base stratifies into three tiers: diversified life science conglomerates with captive raw material access, mid-scale reagent specialists with concentrated R&D programs, and niche quantum dot developers with proprietary nanocrystal formulations. Dominant competitive moves include backward integration into rare earth processing and strategic partnerships with academic consortia for protocol co-development.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify players leveraging scale-driven supply chain control. Merck KGaA and Sartorius AG occupy positions among European-based specialists with deep exposure to GMP documentation services. Bio-Rad Laboratories represents the mid-scale archetype with concentrated investment in multiplexed imaging reagent portfolios. These groupings illustrate how competitive positioning separates raw material security from technical service depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Bio-Rad Laboratories |
| PerkinElmer |
| Agilent Technologies |
| BD |
| Danaher Corporation |
| Miltenyi Biotec |
| Sartorius AG |
| Others |
Value Chain & Pricing Dynamics
Photostability-grade divergence between GMP-validated clinical tracers and research-grade fluorescent labels manifests in both pricing premiums and supply chain qualification depth. FDA 21 CFR 1271 traceability mandates force cell therapy developers toward multi-source procurement of stability-documented reagents, while academic consortia negotiate volume discounts on standardized kits without embedded validation services.
Pricing Analysis
Technical support bundling separates premium vendor contracts from unbundled research-grade transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden: GMP-batch-record tracers command substantial premiums over ISO-grade research reagents, with economy organic dyes serving high-volume screening programs. Pricing pressure stems from quantum dot feedstock volatility as cadmium and indium costs fluctuate with Chinese export policy. Pharmaceutical quality control labs show lowest price sensitivity due to regulatory non-negotiability, while academic stem cell consortia in Massachusetts and California drive hard volume negotiations.
Supply Chain Analysis
EMA ATMP batch-record requirements and FDA 21 CFR 1271 stability documentation act as gating mechanisms for supplier qualification. Rare earth element processing concentrates in China, with cadmium and indium feedstock supply anchored in Jiangxi and Inner Mongolia facilities. Quantum dot manufacturing rests on semiconductor-grade chemical precursors and specialized nanocrystal synthesis equipment. Single-source vulnerability runs through Chinese rare earth export licensing. Distribution runs through authorized distributor networks with technical field support for GMP customers, direct e-commerce for research-grade reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell tracing technology is transitioning from organic fluorophore dominance toward nanoparticle and bioluminescent reporter convergence, with quantum dot brightness advantages displacing legacy dyes in longitudinal studies.
For Market Incumbents: Acquire specialized nanocrystal synthesis capabilities to secure quantum dot formulation expertise before feedstock constraints tighten. Incumbent reagent suppliers must backward integrate into rare earth processing partnerships or captive indium sourcing to defend margin position against Chinese export restriction risk. Thermo Fisher Scientific's vertically integrated chemical synthesis network exemplifies the defensive moat required. For New Entrants and Emerging Players: Launch via ISO 10993 pre-qualification services targeting European regenerative medicine translation pipelines in Germany and Switzerland. White-space concentration sits with cadmium-free quantum dot alternatives for developmental biology studies, where photobleaching resistance justifies premium positioning. Academic kit standardization contracts in Heidelberg and Munich research institutes offer the most penetrable entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale reagent specialists possessing GMP documentation depth given EMA ATMP guideline expansion. Long-term viability favors suppliers with dual capability in fluorescent labels and nanoparticle tracers across the 5-10 year technology transition. The signal to watch is NIH consortium procurement consolidation velocity in Massachusetts and California.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Tracer Validation Service Expansion | EMA ATMP batch-record requirements extend qualification timelines, creating service revenue anchoring. |
| Rare Earth Processing Partnership | Cadmium and indium feedstock security in Chinese processing facilities reduces supply disruption exposure. |
| Academic Consortium Protocol Co-Development | NIH-funded stem cell consortia in Massachusetts and California lock in multi-year reagent supply agreements. |
| Cadmium-Free Quantum Dot Formulation Launch | Reduced toxicity profiles align with ISO 10993 biocompatibility pre-qualification for clinical translation. |
| Multiplexed Imaging Reagent R&D Concentration | Bio-Rad Laboratories' concentrated spending demonstrates competitive positioning through spectral overlap solutions. |
Study Parameters
Independent corroboration across reagent procurement managers at pharmaceutical quality control labs, regulatory affairs leads at cell therapy developers, academic principal investigators in CRISPR lineage studies, and distributor technical sales specialists underwrites the qualitative findings. Primary interviews combined with secondary validation from FDA 21 CFR 1271 guidance documents, EMA ATMP guideline publications, NIH funding disbursement records, and ISO 10993 biocompatibility standards. Bottom-up reagent volume modeling and top-down market sizing triangulate through quantum dot manufacturing capacity assessments and fluorescent label kit shipment data.
Rate-of-change decomposition across the analysis window segments expansion by product type (fluorescent labels, nanoparticles, bioluminescent tags, radioactive tracers), application (cancer research, cell biology, drug development, tissue engineering), technology platform (microscopy, flow cytometry, imaging systems, PCR), and end-user archetype (academic organizations, research institutions, pharmaceutical companies, biotech firms). CAGRs derived from fitted growth curves incorporating CRISPR protocol adoption rates, cell therapy clinical trial registration velocity, and quantum dot brightness improvement trajectories.
Rare earth export restrictions, EMA regulatory reclassification of tracer stability standards, and CRISPR protocol standardization velocity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on NIH funding continuity and quantum dot manufacturing scale-up feasibility. A model refresh is warranted upon material change in Chinese rare earth element processing policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Plant Stem Cell Market