
 Global Tissue Microarray Market | 2026-2036
Global Tissue Microarray Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tissue Microarray Market Foresight
Histopathology technician availability is bifurcating the competitive landscape between automated and manual platform providers. Thermo Fisher Scientific leverages its installed base of diagnostic instruments to cross-sell tissue microarray workflows. BioChain Institute Inc. specializes in custom array fabrication for translational oncology programs. Leica Biosystems anchors its position through integrated digital pathology ecosystems that bundle hardware with tissue microarray consumables.
Tissue microarrays consist of paraffin blocks containing hundreds of tissue cores arranged in precise grid patterns, enabling simultaneous immunohistochemical or in situ hybridization analysis across multiple specimens. These platforms standardize biomarker validation and reduce reagent consumption by orders of magnitude compared to whole-section methods. Automated tissue microarrays command premium positioning due to throughput requirements in pharmaceutical toxicology screening, while manual systems persist in resource-constrained academic settings where protocol flexibility outweighs speed. Immunohistochemistry technology dominates current revenue contribution, though fluorescence in situ hybridization applications are expanding in companion diagnostic development for targeted oncology therapies.
FDA oversight of companion diagnostics under the In Vitro Diagnostic Regulations shapes product development priorities for US market entry, while EMA's Medical Device Regulation in Europe imposes additional clinical evidence requirements on integrated tissue microarray systems. ISO 15189 accreditation standards for diagnostic laboratories in Japan and South Korea drive quality system investments among instrument manufacturers. Stakeholders must weigh regulatory pathway complexity against the margin structure of automated platforms when prioritizing geographic expansion and partnership strategies.
Market Dynamics
Companion diagnostic mandates under FDA oversight are compressing development timelines for tissue microarray manufacturers, forcing alignment between instrument validation and pharmaceutical trial protocols.
Growth Catalysts
- Companion Diagnostic Mandates:FDA's In Vitro Diagnostic Regulations require biomarker validation infrastructure that tissue microarrays deliver at scale. Pharmaceutical toxicology screening programs in the United States now specify automated platforms by default.
- Japan's ISO 15189 Accreditation Drive:Diagnostic laboratories across Tokyo, Osaka, and Fukuoka prefectures are upgrading quality systems. This creates instrument replacement cycles for manufacturers with certified quality management frameworks.
- Fluorescence In Situ Hybridization:Targeted oncology therapy pipelines in Germany and Switzerland are expanding FISH-based companion diagnostic protocols. Tissue microarray consumables enable parallel specimen processing that whole-section methods cannot match.
Market Restraints
- Histopathology Technician Scarcity:Automated platform premiums reflect labor substitution economics. Manual system providers face margin compression in academic settings where technician availability constrains throughput expansion.
- Paraffin Supply Concentration:Histology-grade paraffin production concentrates among petroleum refiners in the US Gulf Coast and Rotterdam clusters. Price volatility in feedstock naphtha transmits directly to consumable cost structures.
- EMA Medical Device Regulation Complexity:Integrated tissue microarray systems face extended clinical evidence requirements for CE marking. European market entry timelines stretch 18-24 months beyond comparable US pathways.
Strategic Opportunities
- South Korean Biobanking Infrastructure:MFDS quality standards and national precision medicine initiatives are consolidating specimen repositories in Seoul, Busan, and Daegu. Local distributors with ISO 13485 certification hold first-mover advantage.
- Digital Pathology Convergence:Whole-slide imaging platforms from Leica Biosystems and 3DHISTECH are creating bundled procurement opportunities. Tissue microarray consumables integrated with slide scanners command pricing premiums.
- India's CDSCO Streamlined Approvals:Medical device rules amendments are reducing import license timelines for Class B instruments. Academic medical centers in Delhi, Mumbai, and Bangalore represent underpenetrated demand for manual platforms.
Industry Challenges
- Multiplex Staining Protocol Standardization:Chromogenic and fluorescent detection chemistries lack cross-platform comparability. Contract research organizations face validation burden when switching between Thermo Fisher, Agilent, and Roche instrument ecosystems.
- Legacy LIMS Integration Complexity:Biobank information management systems from disparate vendors require custom middleware development. Data integrity compliance with 21 CFR Part 11 extends implementation timelines for automated installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tissue Microarray Market |
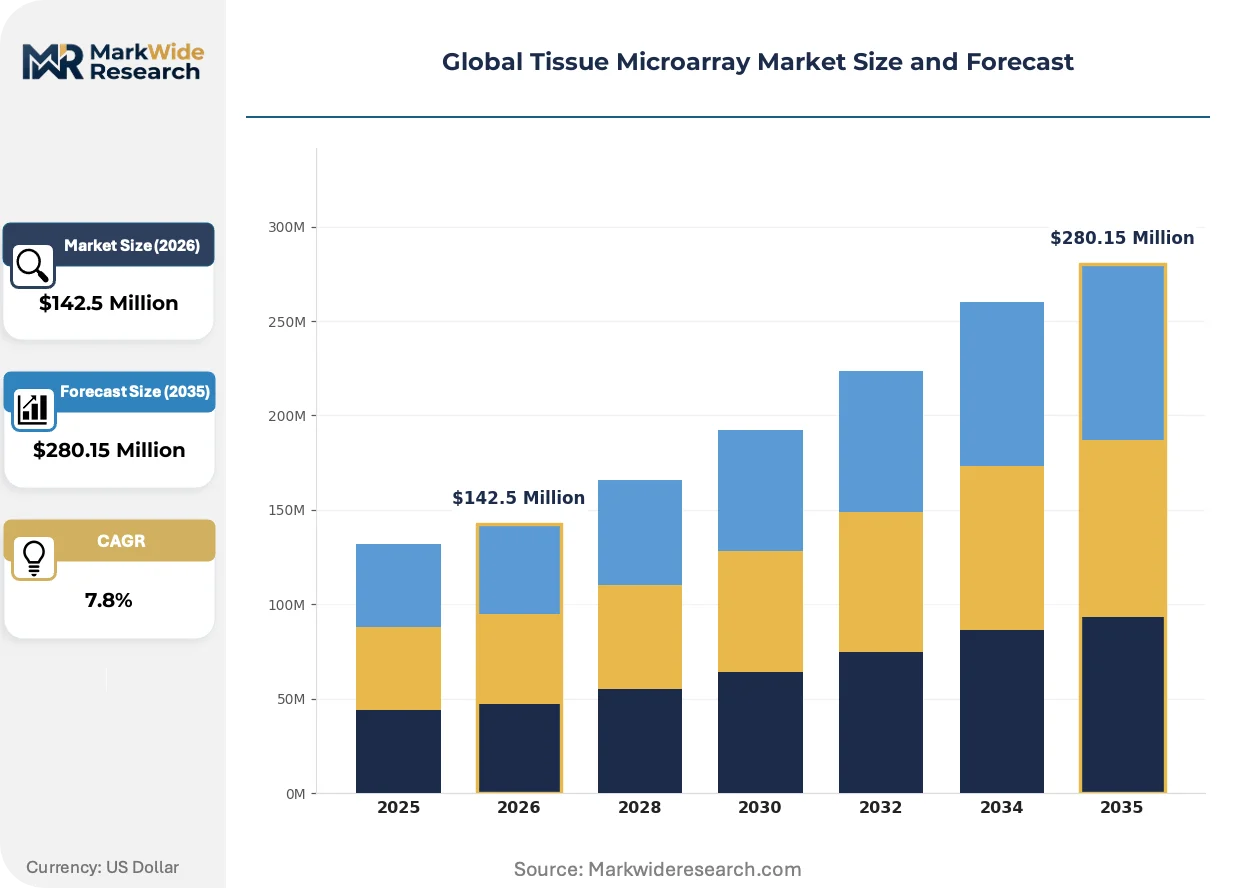
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $280.15 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Tissue Microarrays, Manual Tissue Microarrays, Semi-Automated Tissue Microarrays, Custom Tissue Microarrays Application: Cancer Research, Drug Discovery, Biomarker Validation, Pathology, Molecular Profiling End User: Academic Institutions, Biopharmaceutical Companies, Diagnostic Laboratories, Contract Research Organizations Technology: Paraffin-Based, Frozen Tissue, In Situ Hybridization, Immunohistochemistry, Fluorescence In Situ Hybridization |
| Companies Covered | Agilent Technologies Inc., Thermo Fisher Scientific, OriGene Technologies Inc., US Biomax Inc., BioChain Institute Inc., Merck KGaA, Leica Biosystems, Roche Diagnostics, 3DHISTECH Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tissue Microarray Market Shifts & Advancements
Detection chemistry evolution and regulatory alignment requirements are restructuring competitive positioning across instrument and consumable tiers. Manufacturers now compete on protocol transferability rather than throughput specifications alone.
Multiplex immunohistochemistry is bifurcating the detection reagent market. Academic research centers in the Netherlands and Sweden are adopting 6-plex and 8-plex panels for immune-oncology biomarker studies. This technology is bifurcating vendor strategies between open-architecture reagent suppliers and locked instrument-consumable bundles.
REACH authorization requirements for chromogenic substrates are extending reformulation timelines for European-market reagents. Manufacturers must substitute legacy DAB enhancers with REACH-compliant alternatives. Germany's toxicology screening segment faces 12-18 month protocol revalidation cycles as a direct consequence.
Consolidated procurement through national university purchasing consortia is displacing individual laboratory negotiations. The UK's National Procurement Service and Germany's Konsortial-Beschaffung are mandating total-cost-of-ownership metrics. Service bundling and reagent lock-in terms now determine vendor selection more than instrument capital cost.
Global Tissue Microarray Market Segmentation
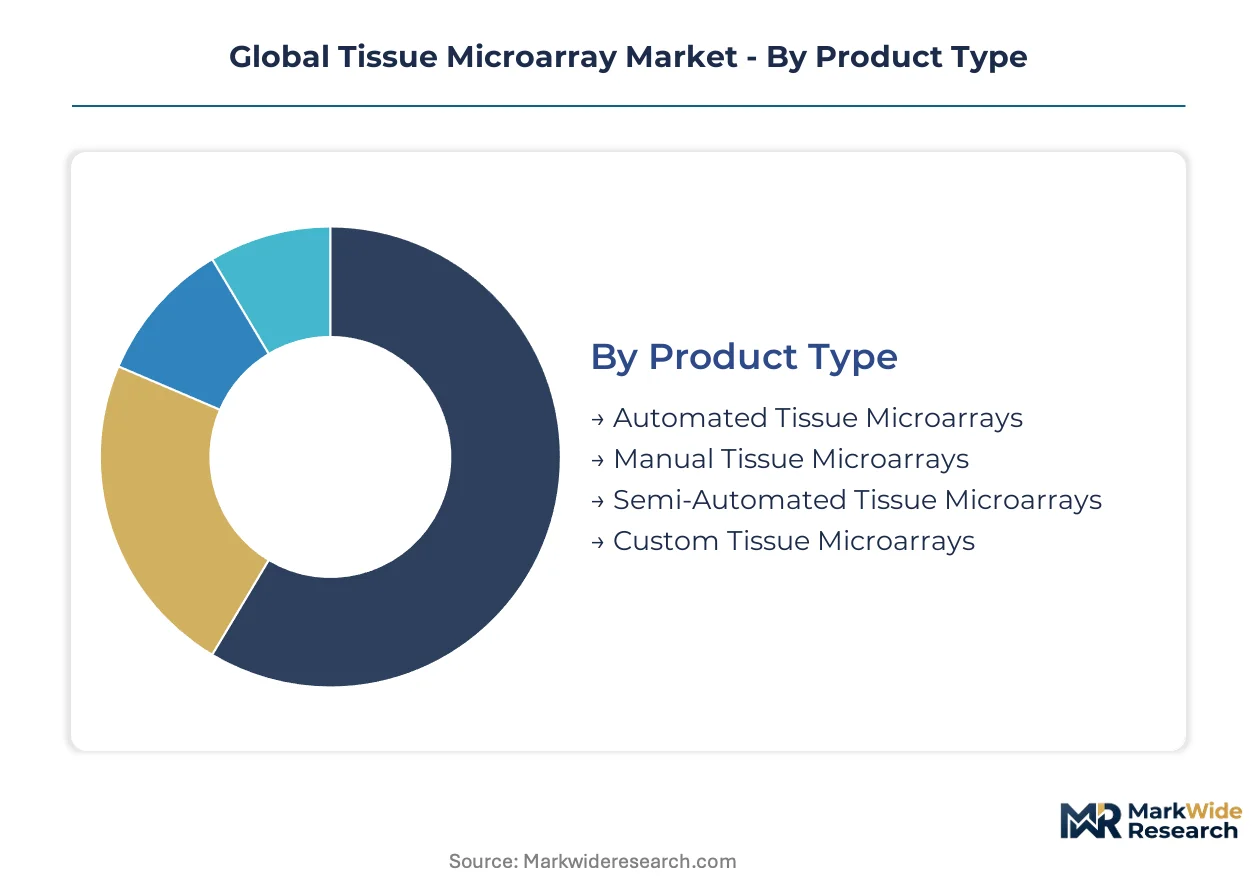
Segmentation in tissue microarrays reflects divergent procurement patterns across pharmaceutical toxicology programs and academic biomarker studies. Channel strategies differ sharply between automated platform vendors targeting centralized biobanking infrastructure and manual system providers serving distributed research networks.
Product Type:
Channel concentration varies by automation tier, with pharmaceutical procurement favoring capital-intensive automated platforms while academic purchasing flows through distributor networks for manual systems.
- Automated Tissue Microarrays:These systems integrate robotic core extraction, array construction, and sectioning with throughput exceeding 500 cores per hour. Pharmaceutical toxicology screening programs in the United States and Germany specify automated platforms by default to compress biomarker validation timelines under FDA companion diagnostic mandates.
- Manual Tissue Microarrays:Hand-operated arrayers using micrometer-positioned punches allow protocol flexibility for small-batch translational studies. Academic medical centers in India and Brazil procure manual systems through regional distributors where capital constraints outweigh throughput requirements.
- Semi-Automated Tissue Microarrays:Hybrid platforms combine motorized positioning with manual core loading, targeting mid-scale biobanks in South Korea and Australia seeking incremental automation without full capital commitment.
- Custom Tissue Microarrays:Fabrication services producing patient-derived xenograft arrays or rare disease tissue collections for contract research organizations in Switzerland and the Netherlands.
By volume, Manual Tissue Microarrays leads due to installed base across resource-constrained settings. By growth pace, Automated Tissue Microarrays is climbing the fastest on pharmaceutical procurement expansion.
Application:
Application demand concentrates where regulatory pressure intersects with throughput requirements, creating divergent margin profiles across discovery versus diagnostic endpoints.
- Cancer Research:Immuno-oncology biomarker studies drive 6-plex and 8-plex multiplex immunohistochemistry panel adoption. Academic consortia in the Netherlands and Sweden require standardized array formats for multi-site reproducibility.
- Drug Discovery:High-throughput toxicity screening mandates automated platforms with integrated digital pathology workflows. Pharmaceutical programs in Germany and Switzerland face REACH-driven reagent reformulation cycles extending protocol validation timelines.
- Biomarker Validation:Companion diagnostic development requires CLIA-compliant array processing with full chain-of-custody documentation. Contract research organizations in the United States specialize in FDA-aligned validation packages.
- Pathology:Diagnostic laboratories in Japan pursuing ISO 15189 accreditation upgrade to automated sectioning systems with barcode tracking.
- Molecular Profiling:Genomics-integrated arrays combining tissue morphology with sequencing readouts for precision medicine initiatives in South Korea.
Cancer Research commands the largest addressable base. Drug Discovery exhibits the steepest expansion trajectory on toxicology screening automation.
End User:
End-user procurement authority is consolidating through national university purchasing consortia and pharmaceutical centralization of outsourced biomarker services.
- Academic Institutions:Distributed purchasing through departmental budgets favors manual and semi-automated platforms with lower capital thresholds. The UK's National Procurement Service and Germany's Konsortial-Beschaffung now mandate total-cost-of-ownership metrics displacing individual laboratory negotiations.
- Biopharmaceutical Companies:Centralized procurement of automated platforms for toxicology and companion diagnostic programs. FDA In Vitro Diagnostic Regulations compress development timelines, forcing alignment between instrument validation and pharmaceutical trial protocols.
- Diagnostic Laboratories:ISO 15189 accreditation drives in Japan and South Korea create instrument replacement cycles for manufacturers with certified quality management frameworks.
- Contract Research Organizations:Multiplex staining protocol standardization burdens create demand for open-architecture reagent suppliers across Thermo Fisher, Agilent, and Roche instrument ecosystems.
Academic Institutions represent the broadest installed footprint. Biopharmaceutical Companies are gaining share fastest on companion diagnostic mandate expansion.
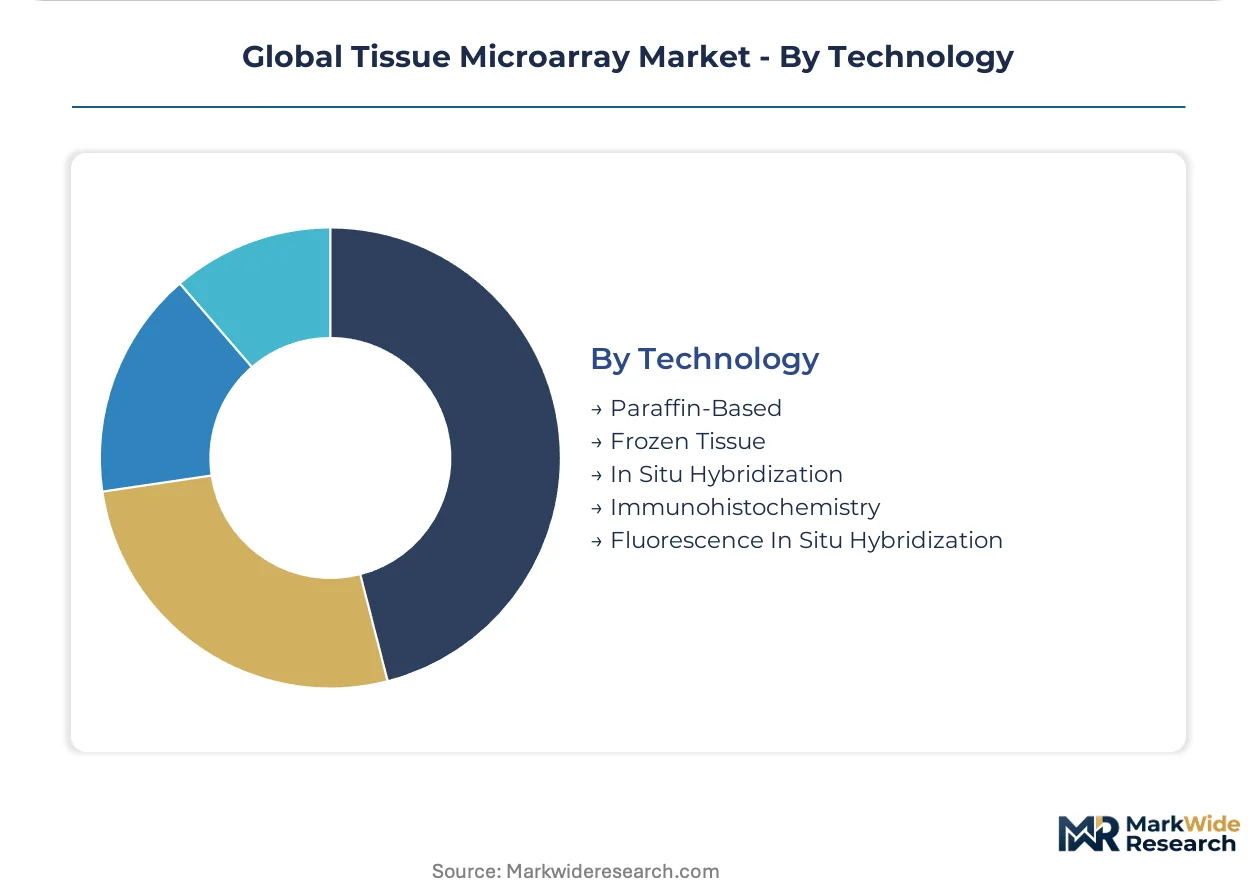
Technology:
Technology selection tracks detection chemistry evolution and regulatory alignment requirements across chromogenic and fluorescent modalities.
- Paraffin-Based:Formalin-fixed paraffin-embedded tissue cores enable long-term archival stability and standardized immunohistochemistry protocols. Histology-grade paraffin supply concentrates among US Gulf Coast and Rotterdam petroleum refiners, transmitting naphtha price volatility to consumable cost structures.
- Frozen Tissue:Cryopreserved arrays preserve nucleic acid integrity for RNA in situ hybridization applications in molecular profiling workflows.
- In Situ Hybridization:DNA and RNA probe detection for gene expression mapping in developmental biology research.
- Immunohistochemistry:Chromogenic antibody detection dominates current revenue contribution with established diagnostic reimbursement pathways.
- Fluorescence In Situ Hybridization:Targeted oncology therapy pipelines in Germany and Switzerland expand FISH-based companion diagnostic protocols requiring parallel specimen processing capabilities.
Paraffin-Based technology holds the deepest penetration. Fluorescence In Situ Hybridization is expanding most quickly on targeted therapy pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's In Vitro Diagnostic Regulations establish the regulatory baseline that shapes tissue microarray procurement patterns across the United States. Companion diagnostic mandates compress biomarker validation timelines and drive pharmaceutical toxicology programs toward automated platform specifications.
United States
Pharmaceutical toxicology screening programs in Boston, San Francisco, and Research Triangle Park specify automated tissue microarray platforms by default under FDA companion diagnostic mandates. CLIA-compliant array processing with full chain-of-custody documentation dominates contract research organization procurement in Maryland and North Carolina clusters.
Germany
Targeted oncology therapy pipelines in Munich and Heidelberg expand fluorescence in situ hybridization protocols requiring parallel specimen processing capabilities. REACH authorization requirements for chromogenic substrates extend reformulation timelines, forcing 12-18 month protocol revalidation cycles in the toxicology screening segment.
Japan
Diagnostic laboratories across Tokyo, Osaka, and Fukuoka prefectures pursue ISO 15189 accreditation, creating instrument replacement cycles for manufacturers with certified quality management frameworks. PMDA oversight aligns with METI industrial standards to drive quality system investments among instrument suppliers.
South Korea
National precision medicine initiatives consolidate specimen repositories in Seoul, Busan, and Daegu under MFDS quality standards. Local distributors with ISO 13485 certification capture first-mover advantage in biobanking infrastructure expansion.
India
Academic medical centers in Delhi, Mumbai, and Bangalore represent underpenetrated demand for manual platforms following CDSCO streamlined approvals for Class B instruments. Capital constraints in departmental budgets favor lower-threshold procurement through regional distributor networks.
Global Tissue Microarray Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the tissue microarray market. Consolidated procurement through national university purchasing consortia and pharmaceutical centralization of outsourced biomarker services compresses vendor margins. Three archetypes dominate: diversified life science conglomerates with cross-selling capabilities, specialized pathology instrument manufacturers with digital ecosystem integration, and custom array fabrication services for translational programs. Competitive moves center on strategic partnerships for protocol standardization and backward integration into consumable supply chains.
Among diversified life science conglomerates, Thermo Fisher Scientific leverages diagnostic instrument installed bases to cross-sell tissue microarray workflows. Leica Biosystems anchors the integrated digital pathology ecosystem segment through bundled hardware-consumable offerings. BioChain Institute Inc. exemplifies the custom fabrication specialist archetype serving translational oncology programs.
| Leading Market Players |
|---|
| Agilent Technologies Inc. |
| Thermo Fisher Scientific |
| OriGene Technologies Inc. |
| US Biomax Inc. |
| BioChain Institute Inc. |
| Merck KGaA |
| Leica Biosystems |
| Roche Diagnostics |
| 3DHISTECH Ltd. |
| Others |
Supply & Pricing Matrix
Capacity utilization at automated platform manufacturers in the United States and Germany creates scale economies that compress per-unit costs while simultaneously concentrating pricing power among vendors with certified quality management frameworks. This dynamic elevates price floors for entry-tier manual systems as petroleum feedstock volatility transmits through histology-grade paraffin supply chains.
Pricing Analysis
Price spreads between automated and manual tissue microarray platforms widen by geography, with pharmaceutical procurement in the United States commanding premium positioning against academic purchasing in India and Brazil. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated automated systems from ISO 15189-compliant mid-tier instruments and unbundled manual arrayers. Cost compression in economy-tier manual systems intensifies because regional distributors absorb margin erosion to maintain volume. Academic institutions exhibit highest price sensitivity, while biopharmaceutical toxicology programs demonstrate lowest sensitivity due to companion diagnostic timeline pressures.
Supply Chain Analysis
Rotterdam petrochemical cluster transit underwrites European consumable supply security, though naphtha price volatility from US Gulf Coast refiners transmits directly to paraffin block cost structures. Manufacturing concentrates in the United States, Germany, and China for instrument assembly, while histology-grade paraffin feedstock draws from petroleum refining corridors in Texas, Louisiana, and the Netherlands. Single-source vulnerability in chromogenic substrate formulations exposes European reagent suppliers to REACH-driven reformulation delays. Distribution runs through national university purchasing consortia in the United Kingdom and Germany alongside pharmaceutical centralized procurement offices in Boston and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
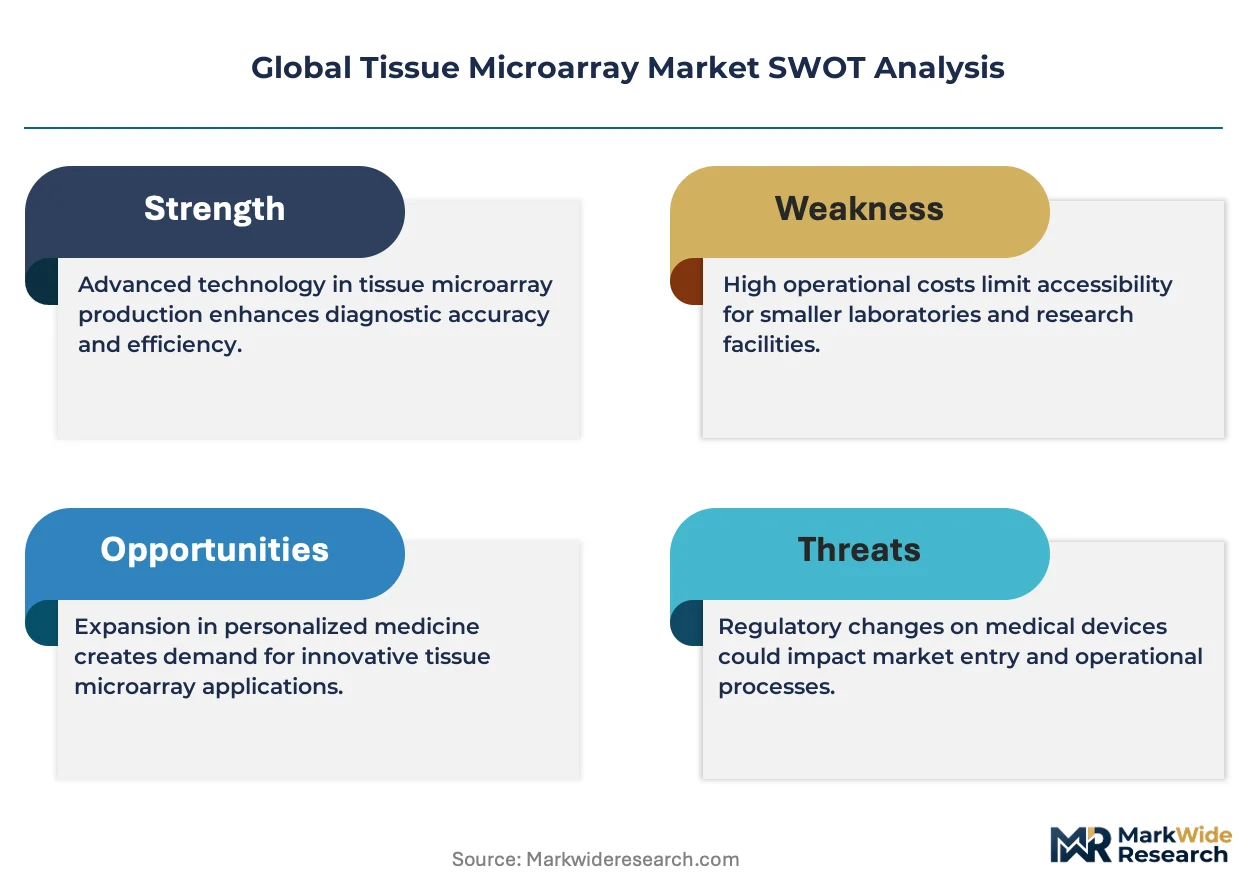
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA companion diagnostic mandates and EMA Medical Device Regulation complexity create switching costs that lock validated instrument platforms into multi-year procurement cycles.
For Market Incumbents: Shield installed base revenue through backward integration into consumable supply chains, particularly chromogenic substrate formulations facing REACH reauthorization cycles. Prioritize ISO 15189 certification maintenance to capture Japanese diagnostic laboratory replacement demand. Capacity addition in South Korea addresses MFDS-aligned biobanking infrastructure expansion.
For New Entrants and Emerging Players: CDSCO streamlined Class B approval pathways in India represent the fastest certification fast-track for manual platform market entry. Academic medical centers in Delhi, Mumbai, and Bangalore offer underpenetrated demand with capital-constrained procurement profiles. Partner with regional distributors possessing existing pathology instrument relationships to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom array fabrication specialists serving translational oncology programs with project-based re-order cycles. Long-term viability over the next decade rests on digital pathology ecosystem integration capabilities. Monitor fluorescence in situ hybridization protocol adoption rates in German and Swiss pharmaceutical pipelines as inflection indicator for automated platform demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Pathology Ecosystem Integration | Leica Biosystems and 3DHISTECH bundled offerings command consumable pricing premiums. |
| REACH-Compliant Reagent Reformulation | German toxicology screening programs face 12-18 month protocol revalidation cycles. |
| ISO 15189 Quality System Certification | Japanese diagnostic laboratories in Tokyo and Osaka drive instrument replacement demand. |
| South Korean Biobank Infrastructure Partnership | MFDS-aligned distributors in Seoul capture precision medicine initiative procurement. |
| Multiplex Immunohistochemistry Panel Development | Netherlands and Sweden academic consortia standardize 6-plex and 8-plex formats. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA Medical Device Regulation guidance documents, and ISO 15189 accreditation databases. Interviews with histopathology laboratory directors, pharmaceutical toxicology program managers, biomedical procurement officers at academic medical centers, and regional distribution channel partners inform demand-side validation. Trade data from USITC and Eurostat, alongside SEC 10-K instrument revenue disclosures, provide supply-side triangulation through bottom-up and top-down reconciliation.
Segmentation dimensions modeled span automation tier, detection technology, end-user procurement authority, and regional regulatory cluster across the analysis window. CAGRs derive from instrument shipment tracking, consumable reorder rate analysis, and pharmaceutical pipeline biomarker validation timeline compression. Companion diagnostic mandate expansion rates and biobanking infrastructure investment flows constitute disease-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA In Vitro Diagnostic Regulation enforcement and stable petroleum feedstock pricing; material deviation in regulatory stringency or naphtha cost volatility would warrant model refresh. Practitioners should keep alternative scenarios live as EMA Medical Device Regulation implementation timelines and REACH authorization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Fluorescent in Situ Hybridization Market