
 Bioprocess Technology Market | 2026-2036
Bioprocess Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Bioprocess Technology Market Analysis
Direct procurement partnerships between biopharmaceutical manufacturers and equipment vendors is reshaping how bioprocess technology reaches end users. Thermo Fisher Scientific leverages its integrated consumables-instrument-service portfolio to lock in multi-year supply agreements with top-tier drug makers. Sartorius sustains dominance in single-use bioreactor systems through membrane and sensor technologies that reduce cross-contamination risk. Danaher Corporation anchors its position via Pall Life Sciences filtration and chromatography platforms that span upstream through downstream processing.
Bioprocess technology encompasses the engineered systems, analytical methods, and control strategies used to cultivate living cells or biocatalysts under controlled conditions, typically operating at scales from bench-top liters to commercial bioreactors exceeding 20,000 liters, with critical parameters including dissolved oxygen, pH, temperature, and nutrient feed rates maintained within tight tolerances to ensure product yield and quality. The primary purpose is to manufacture biologics such as therapeutic proteins, viral vectors, and cell therapies with reproducible purity profiles and regulatory-compliant documentation. Bioreactors command the largest installed base among product types, yet chromatography systems capture disproportionate margin pools due to resin replacement cycles and method development complexity. Cell therapy applications are expanding fastest within the application dimension, though monoclonal antibody production still absorbs the majority of capital deployment across pharmaceutical company end users.
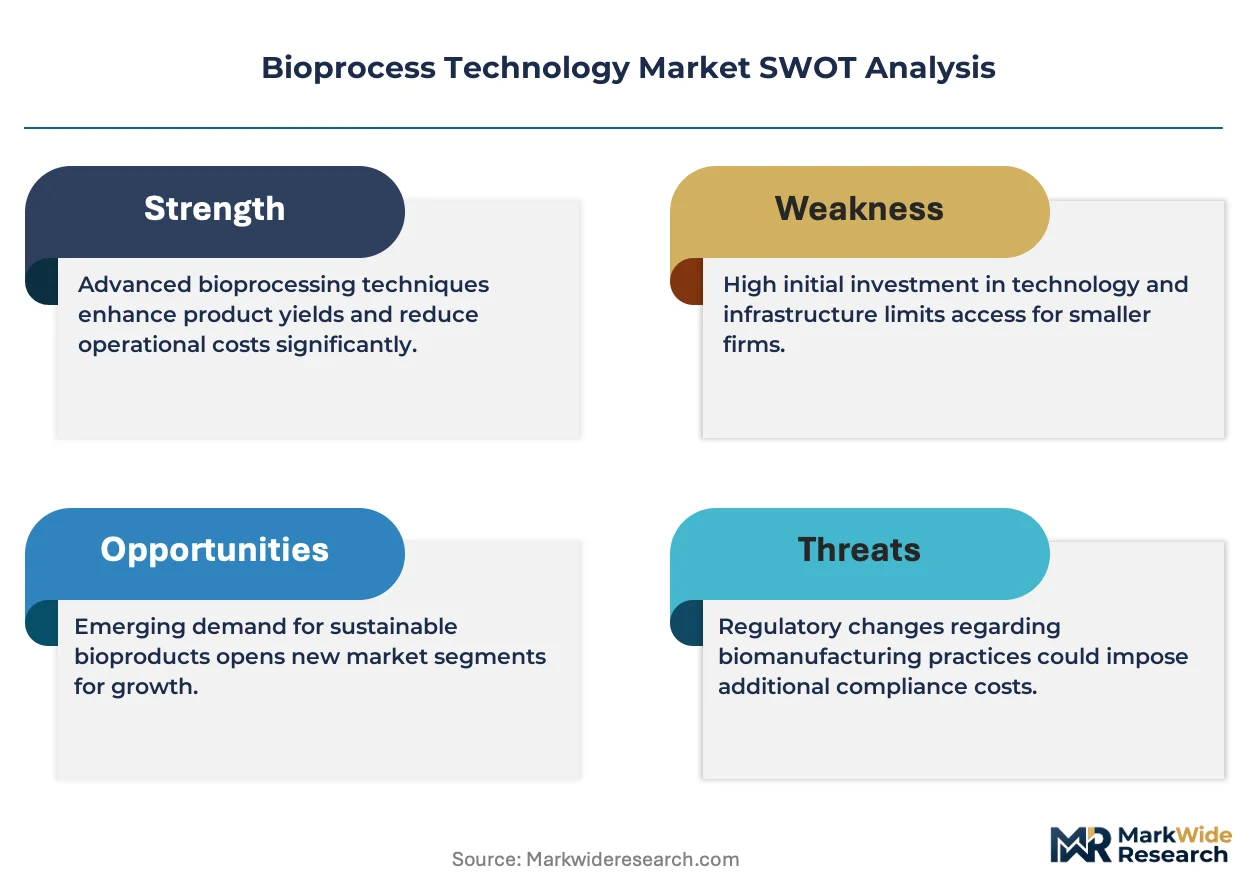
FDA process validation guidance, EMA good manufacturing practice annexes for biologicals, and ISO 14644 cleanroom classifications collectively dictate facility design, equipment qualification, and batch release protocols for bioprocess operators. These frameworks elevate barrier-to-entry for new technology vendors while creating recurring revenue streams for incumbents through validation support and compliance auditing services. Stakeholders must monitor evolving regulatory positions on continuous manufacturing and real-time release testing, as these shifts will determine which platform technologies achieve preferred vendor status in the next investment cycle.
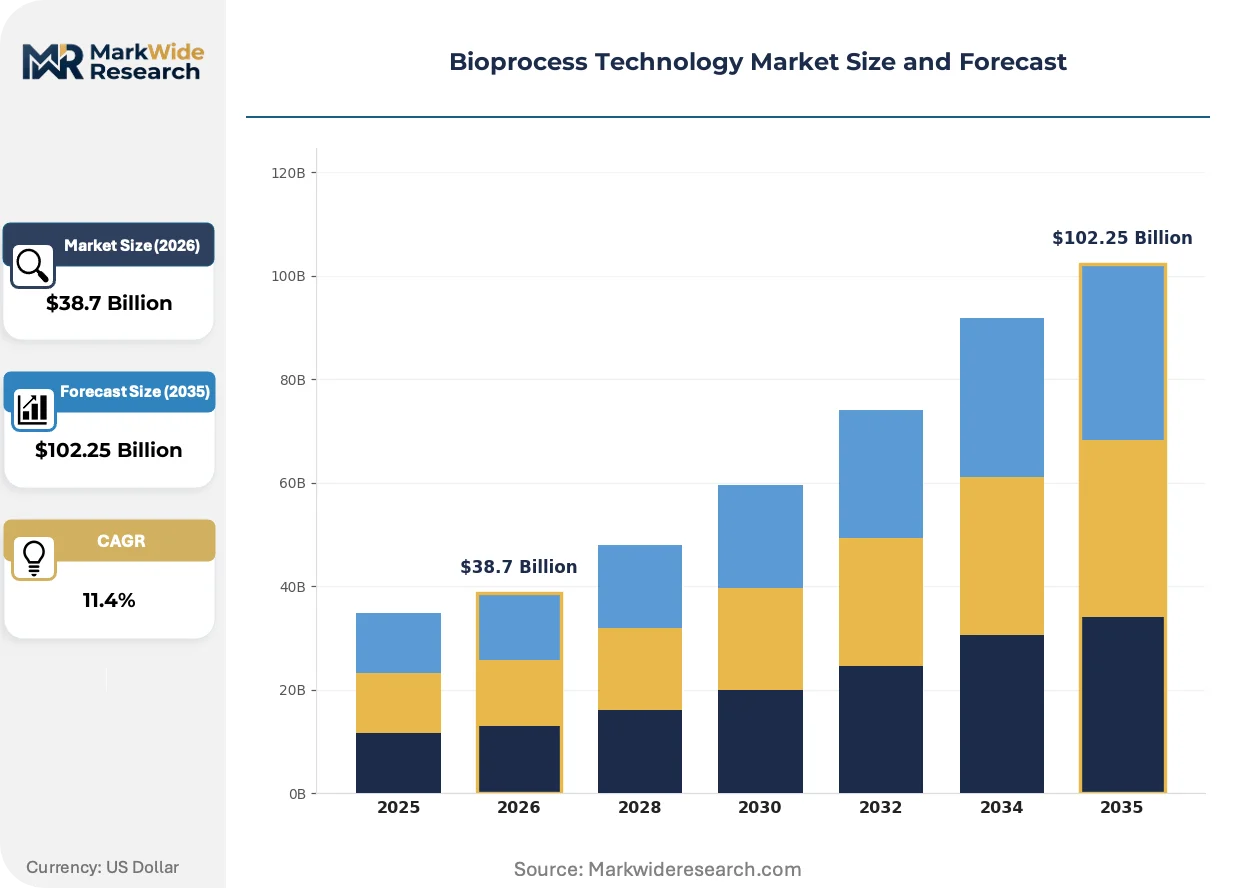
Market Dynamics
Continuous manufacturing mandates from FDA and EMA are compressing batch release timelines while forcing biopharmaceutical manufacturers to revalidate legacy stainless-steel infrastructure against real-time release testing protocols.
Growth Catalysts
- EMA GMP Annex 2A:The revised biological manufacturing framework accelerates adoption of closed-system single-use technologies that eliminate clean-in-place validation bottlenecks.
- Cell therapy commercialization:Autologous CAR-T manufacturing scales are driving demand for flexible bioreactor footprints that accommodate patient-specific batch sizes.
- United States biologics capacity expansion:Domestic monoclonal antibody production facilities in Massachusetts and North Carolina are commissioning 20,000-liter single-use trains.
Market Restraints
- Resin supply concentration:Protein A chromatography resin production clusters with two Japanese chemical suppliers, creating input vulnerability for mRNA and antibody purification workflows.
- Stainless-steel asset stranding:Existing 12,000-liter stirred-tank bioreactors face depreciation acceleration as FDA process analytical technology guidance favors disposable flow paths.
- Skilled operator scarcity:Advanced therapy medicinal product manufacturing requires GMP-qualified cell culture specialists that training programs in Germany and Switzerland cannot produce at replacement rates.
Strategic Opportunities
- India CDMO buildout:Contract development and manufacturing organizations in Hyderabad and Bengaluru are installing single-use suites to capture outsourced biologics production from Western sponsors.
- Digital twin integration:Process simulation software combined with sensor arrays enables predictive control of perfusion cell culture without physical scale-down models.
- Continuous downstream processing:Multi-column periodic counter-current chromatography reduces resin volume requirements by sixty percent versus batch capture steps.
Industry Challenges
- Legacy SCADA integration:Distributed control systems from the 1990s lack OPC-UA connectivity required for FDA data integrity guidance on electronic batch records.
- Vendor qualification burden:Each single-use assembly supplier requires eighteen-month change notification protocols that delay technology refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioprocess Technology Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Filtration Systems, Chromatography Systems, Cell Culture Systems End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturers Application: Monoclonal Antibody Production, Vaccine Development, Enzyme Production, Cell Therapy Delivery Mode: On-premise, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Thermo Fisher Scientific, Sartorius, Danaher Corporation, Merck KGaA, GE Healthcare, Bio-Rad Laboratories, Repligen, Lonza Group, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioprocess Technology Market Emerging Trajectories
Digitalization of process development is collapsing the traditional scale-up funnel while regulatory frameworks coalesce around continuous manufacturing paradigms that redefine batch identity.
Digital twin platforms are virtualizing upstream process development by creating computational replicas of mammalian cell culture behavior across temperature, pH, and dissolved oxygen setpoints. Biopharmaceutical process development groups at Merck and Roche deploy these models to predict titer outcomes before pilot-scale runs. The technology is virtualizing physical experimentation, compressing timeline and raw material consumption for IND-enabling campaigns.
FDA's emerging guidance on real-time release testing removes the analytical hold-time that has historically separated upstream production from final product disposition. The framework permits parametric release based on in-process measurements rather than end-point testing. Monoclonal antibody facilities in Puerto Rico and Ireland are restructuring quality control laboratories to support reduced testing protocols.
Biopharmaceutical procurement organizations are consolidating supplier panels from twenty-plus vendors to five strategic partners capable of delivering integrated consumables-instrument-service bundles. Thermo Fisher and Sartorius capture multi-year sole-source agreements that lock in resin, media, and hardware pricing. This concentration is most advanced among top-ten pharmaceutical manufacturers headquartered in the United States and Switzerland.
Bioprocess Technology Market Segmentation
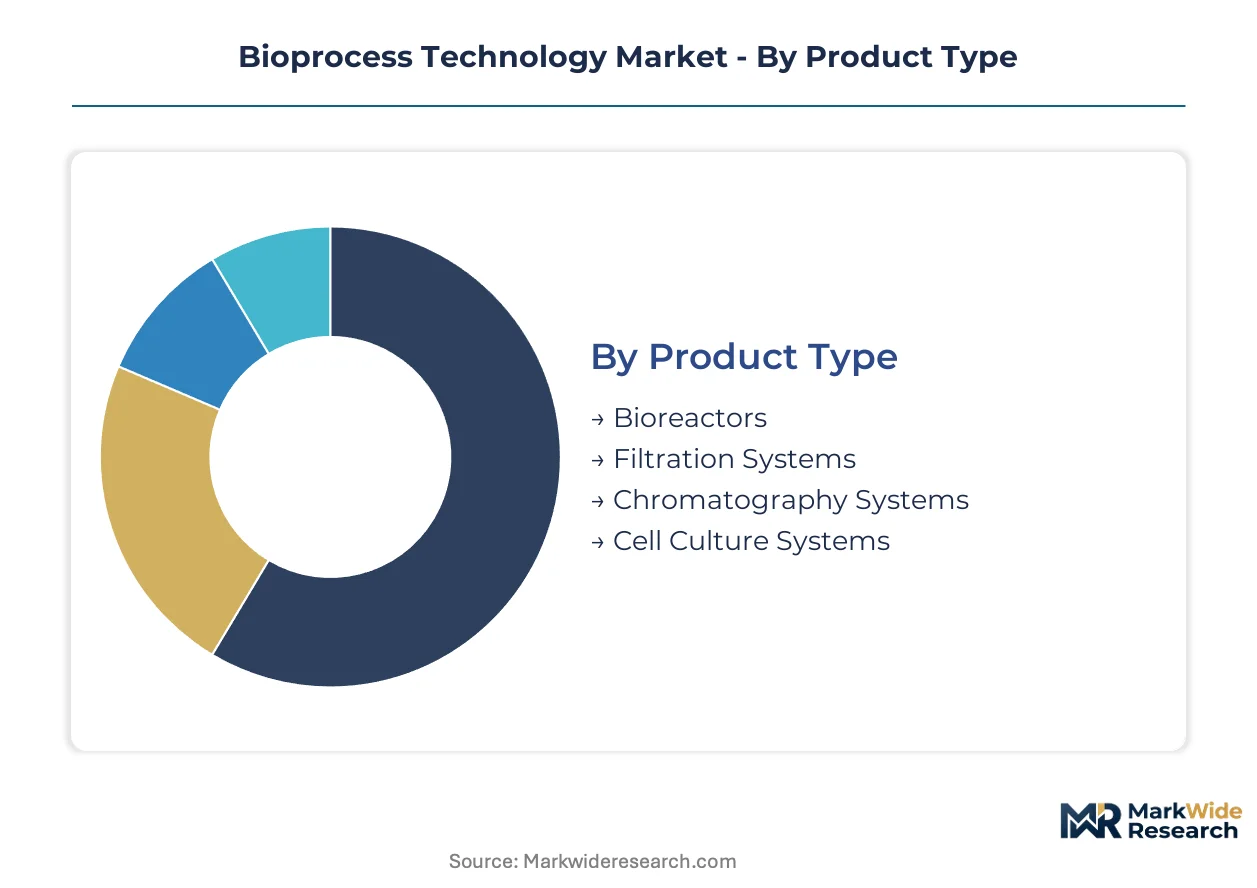
Bioprocess technology procurement patterns diverge sharply across product categories, with installed base longevity and consumables replenishment cycles creating distinct service revenue profiles. Equipment vendors calibrate aftermarket strategies differently for capital-intensive bioreactors versus resin-dependent chromatography platforms.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with membrane replacement schedules and sensor calibration demands driving multi-year revenue recognition models.
- Bioreactors:Stainless-steel and single-use vessels ranging from 50-liter pilot scales to 20,000-liter commercial trains, with agitation systems and sparger designs optimized for mammalian or microbial culture. Demand clusters in Massachusetts and North Carolina facilities where FDA process analytical technology compliance mandates real-time monitoring retrofits.
- Filtration Systems:Tangential flow and normal flow configurations employing polyethersulfone or regenerated cellulose membranes for cell retention and virus clearance. German biologics manufacturers in Bavaria and Baden-Württemberg drive replacement membrane procurement through EMA GMP Annex 2A validation requirements.
- Chromatography Systems:Protein A affinity and ion exchange platforms with resin lifecycles dictating recurring consumables revenue.
- Cell Culture Systems:Media preparation and storage vessels supporting seed train expansion from vial thaw to production inoculation.
By volume, bioreactors lead. By growth pace, chromatography systems are expanding most quickly.
End User:
Capital deployment authority and validation burden intensity segment the customer base, with procurement complexity escalating alongside regulatory exposure.
- Pharmaceutical Companies:Integrated biologics divisions at top-twenty drug makers operating captive manufacturing networks across multiple jurisdictions. These organizations in Switzerland and the United States impose eighteen-month supplier qualification protocols that freeze vendor panels.
- Biotechnology Firms:Venture-backed developers advancing assets through Phase II, outsourcing commercial manufacturing while retaining process development in-house. Cambridge, Massachusetts and South San Francisco clusters concentrate equipment procurement for IND-enabling campaigns.
- Research Institutions:Academic labs and national research centers operating at bench and pilot scales with limited GMP compliance obligations.
- Contract Manufacturers:CDMOs in Hyderabad and Bengaluru installing single-use suites to capture Western sponsor outsourcing.
Pharmaceutical companies absorb the majority of capital expenditure. Contract manufacturers are gaining share fastest.
Application:
Process complexity and batch failure cost profiles determine equipment specification stringency across therapeutic modalities.
- Monoclonal Antibody Production:Fed-batch and perfusion mammalian cell culture at 2,000-20,000 liter scales, with Protein A capture and polish chromatography steps yielding 95% purity targets. Chinese facilities in Suzhou and Shanghai commission stainless-steel trains for biosimilar output.
- Cell Therapy:Autologous CAR-T manufacturing requiring closed-system bioreactors accommodating patient-specific batch sizes from 0.5-50 liters. FDA real-time release testing pilots in Maryland and Pennsylvania accelerate flexible platform adoption.
- Vaccine Development:Viral vector and recombinant protein production with egg-free and cell-based platform transitions.
- Enzyme Production:Microbial fermentation for industrial and therapeutic biocatalysts with lower purity thresholds.
Monoclonal antibody production dominates current capacity. Cell therapy shows the steepest expansion trajectory.
Delivery Mode:
Data sovereignty requirements and validation documentation standards fragment software and service deployment architectures.
- On-premise:Local server installations for electronic batch record and manufacturing execution systems subject to FDA 21 CFR Part 11 audit trails. Irish and Puerto Rican facilities maintain this architecture for legacy SCADA integration.
- Cloud-based:SaaS platforms for process development data management and remote equipment monitoring. Swiss manufacturers in Basel leverage these deployments for multi-site standardization.
- Hybrid:Split architectures segregating GMP-critical functions on-premise while deploying analytics workloads to cloud infrastructure.
- Managed Services:Outsourced validation, calibration, and maintenance contracts with equipment vendors.
On-premise retains the largest installed base. Cloud-based deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Boston's specialized cold-chain infrastructure underwrites Massachusetts' dominance in monoclonal antibody manufacturing, while the Rhine-Main corridor's chemical logistics network anchors German bioprocess equipment distribution.
United States
FDA process analytical technology mandates and monoclonal antibody capacity expansion drive equipment procurement. The Biologics Price Competition and Innovation Act accelerates biosimilar manufacturing investments. Facilities in Massachusetts and North Carolina commission 20,000-liter single-use bioreactor trains to meet domestic biologics demand.
Germany
EMA GMP Annex 2A validation requirements and single-use technology adoption reshape facility design. The country's national pharmaceutical regulator enforces closed-system manufacturing standards. Bavarian and Baden-Württemberg biologics manufacturers drive replacement membrane procurement for filtration systems.
China
NMPA biologics approval pathway reforms and biosimilar localization policies stimulate capital deployment. Dual carbon goals accelerate energy-efficient bioreactor adoption. Suzhou and Shanghai facilities commission stainless-steel trains for biosimilar output targeting domestic and export markets.
Switzerland
Swissmedic quality standards and multi-site manufacturing coordination requirements elevate vendor qualification protocols. Federal technology transfer initiatives support continuous processing adoption. Basel-headquartered pharmaceutical manufacturers impose eighteen-month supplier panels that freeze vendor relationships.
India
CDSCO biologics manufacturing guidelines and contract manufacturing organization buildout attract Western sponsor outsourcing. Production-linked incentive schemes for pharmaceuticals reduce import dependence. Hyderabad and Bengaluru CDMOs install single-use suites to capture outsourced biologics production.
Bioprocess Technology Market Vendor Landscape
On the supply side, the industry is consolidating around integrated consumables-instrument-service portfolios that lock in multi-year agreements. Equipment vendors and consumables suppliers increasingly merge capabilities to offer bundled validation and compliance auditing. Three archetypes dominate: integrated life science conglomerates, specialized single-use technology pure-plays, and filtration-chromatography platform specialists. Competitive moves center on strategic partnerships for digital twin integration and geographic expansion through contract manufacturing organization alliances.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify portfolio breadth strategies that span upstream through downstream processing. Sartorius occupies a distinct position among specialized single-use technology providers. These three anchors collectively represent the vendor consolidation trajectory reshaping procurement patterns among top-tier pharmaceutical manufacturers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius |
| Danaher Corporation |
| Merck KGaA |
| GE Healthcare |
| Bio-Rad Laboratories |
| Repligen |
| Lonza Group |
| Agilent Technologies |
| Others |
Supply Flow & Price Mechanics
Protein A chromatography resin concentration in Japanese chemical suppliers determines both margin compression in downstream purification tiers and the geographic shape of biopharmaceutical supply security investments. This single-source dependency forces tiered pricing spreads between validated resin lots and spot-market alternatives while redirecting procurement toward long-term offtake contracts with supply guarantees.
Pricing Analysis
Volume-discount tiering structures dominate bioprocess equipment procurement, with pharmaceutical manufacturers securing 18-36 month sole-source agreements that lock resin, media, and hardware pricing across the contract term. Price differentiation rests on validation documentation depth and FDA master file completeness rather than raw performance specifications alone. Cost compression in standard-grade single-use assemblies is intensifying because Indian CDMOs are absorbing surplus Chinese manufacturing capacity. Biotechnology firms with IND-stage assets exhibit highest price sensitivity, while Swiss and US top-ten pharmaceutical manufacturers prioritize supply assurance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from equipment vendors are restructuring working capital flows for CDMOs in Hyderabad and Bengaluru. Geographic supply concentration centers on Germany for filtration membranes, Japan for Protein A resins, and the United States for bioreactor control systems. Raw material dependencies include polyethersulfone membranes, recombinant Protein A ligands, and pharmaceutical-grade silicone tubing. Single-source vulnerability in chromatography resin production creates regulatory chokepoint exposure for mRNA and antibody workflows. Distribution runs through direct procurement partnerships that bypass traditional distributor networks for GMP-validated consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioprocess technology markets are approaching a platform-economics inflection where digital twin interoperability standards determine vendor ecosystem lock-in. FDA real-time release testing pilots in Maryland and Pennsylvania are accelerating this shift toward integrated data architectures.
For Market Incumbents: Build regulatory validation moats by embedding FDA process analytical technology compliance documentation into standard equipment offerings. Incumbents should deepen backward integration into membrane manufacturing to capture resin replacement cycles while defending against emerging digital-native entrants with cloud-native control platforms. Certification investment in ISO 14644 cleanroom classifications and EMA GMP Annex 2A validation protocols freezes vendor panels for 18-month qualification windows.
For New Entrants and Emerging Players: Build out flexible bioreactor footprints targeting autologous CAR-T manufacturing scales from 0.5-50 liters, the most penetrable segment where incumbent stainless-steel assets face stranding risk. New entrants should prioritize India CDMO alliances in Hyderabad and Bengaluru as anchor customers, leveraging production-linked incentive schemes to reduce import dependence. Go-to-market positioning should emphasize closed-system single-use technologies that eliminate clean-in-place validation bottlenecks for cell therapy developers.
For Investors and Strategic Acquirers: FDA real-time release testing guidance reshapes the acquisition landscape by elevating digital twin and predictive control platform valuations above traditional hardware multiples. Long-term viability over the next decade hinges on continuous manufacturing technology readiness rather than batch-processing legacy assets. Acquisition targets should display multi-column periodic counter-current chromatography capabilities or sensor-integrated perfusion control systems. The signal to monitor is EMA adoption timelines for parametric release frameworks, which will determine which platform technologies achieve preferred vendor status.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Merck and Roche deploy virtual cell culture replicas to compress IND-enabling campaign timelines. |
| Continuous Manufacturing Transition | Puerto Rican and Irish monoclonal antibody facilities restructure QC laboratories for reduced testing protocols. |
| Resin Supply Security Investment | Long-term offtake agreements with Japanese chemical suppliers mitigate Protein A purification workflow vulnerability. |
| CDMO Geographic Expansion | Hyderabad and Bengaluru single-use suite installations capture Western sponsor biologics outsourcing demand. |
| Regulatory Validation Bundling | Thermo Fisher and Sartorius lock multi-year agreements through integrated consumables-instrument-service portfolios. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EMA GMP Annex 2A submissions, and ISO 14644 cleanroom classification databases. Primary interviews engaged bioprocess development executives, regulatory affairs leads at top-twenty pharmaceutical manufacturers, GMP-qualified cell culture specialists, and CDMO procurement directors in India and Switzerland. Secondary validation drew from SEC 10-K equipment vendor disclosures, NMPA biologics approval pathway records, and customs data on chromatography resin trade flows. Bottom-up segment sizing triangulated against top-down market envelope checks.
Forecast inputs include capacity utilization rates at Massachusetts and North Carolina biologics facilities, EMA validation timeline assumptions, and NMPA biosimilar localization policy implementation progress across the analysis window. Segmentation modeling spans product type, end user archetype, therapeutic application, and delivery mode dimensions. CAGRs were derived from installed base growth projections and consumables replenishment cycle analysis. Industry-specific inputs incorporate single-use technology adoption curves and digital twin platform penetration rates among Phase III biotechnology developers.
Stress conditions across resin supply disruption, FDA continuous manufacturing mandate acceleration, and India CDMO buildout pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory framework evolution and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
Global Transfection Market