
 Synovial Sarcoma Market | 2026-2036
Synovial Sarcoma Market Size, Share, and Industry Trends Forecast 2026-2036
Synovial Sarcoma Market Outlook
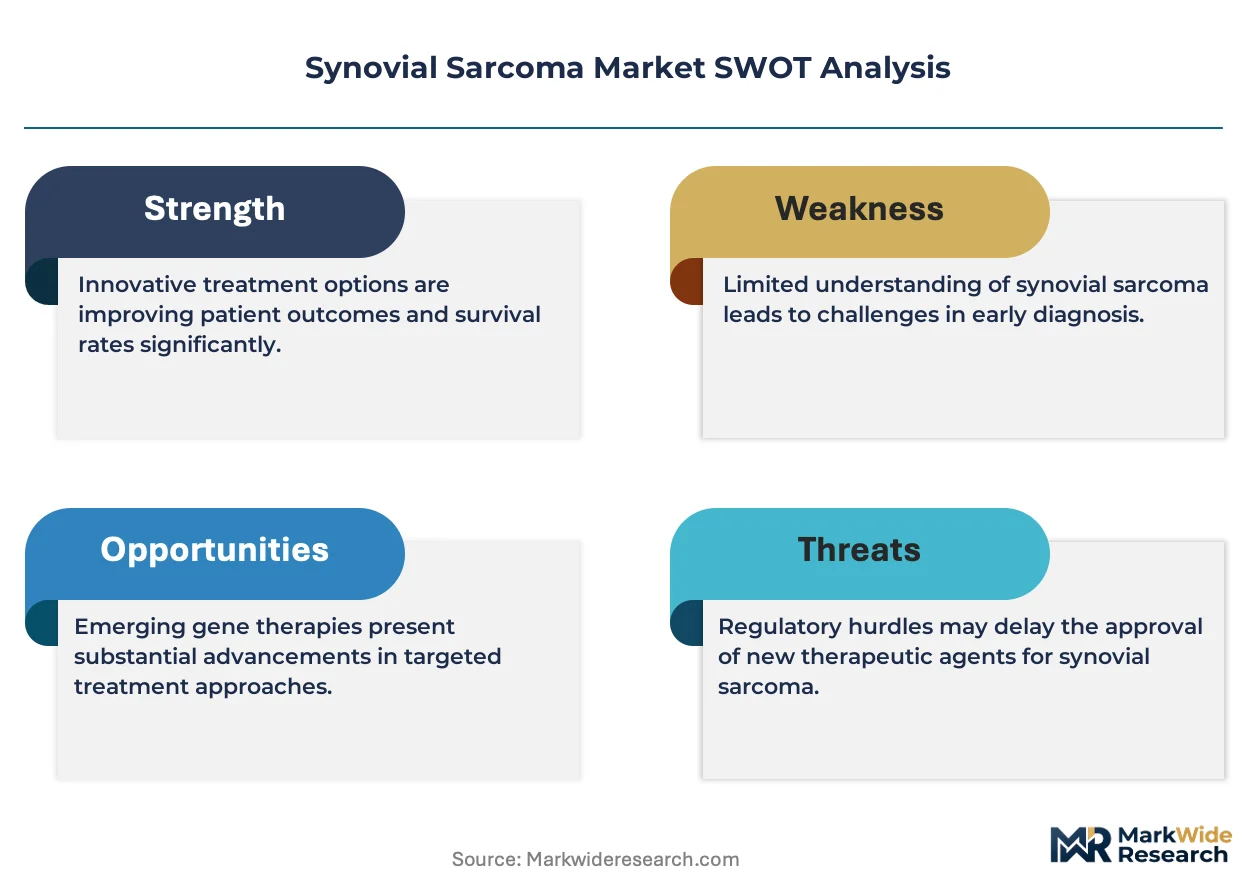
China is tilting toward biologics manufacturing scale for rare oncology indications. Merck & Co. leverages its checkpoint inhibitor platform across sarcoma subsets. AstraZeneca anchors its presence through antibody-drug conjugate pipelines. Novartis competes with radioligand therapy assets in soft tissue malignancies.
Synovial sarcoma is a malignant soft tissue tumor arising from chromosomal translocation t(X;18)(p11;q11), producing SS18-SSX fusion proteins that dysregulate chromatin remodeling and drive oncogenesis. The condition primarily demands multimodal intervention combining cytoreductive surgery with systemic therapy to address high metastatic propensity. Targeted therapy segments attract R&D investment due to SS18-SSX fusion-directed mechanisms, while immunotherapy segments show structural promise despite checkpoint inhibitor limitations in microsatellite-stable disease. Hospitals occupy the dominant end-user position given inpatient surgical requirements, though academic research centers capture growing trial enrollment volume.
The FDA's orphan drug designation and breakthrough therapy pathways shape clinical development economics for sponsors. EMA's PRIME scheme and Japan's PMDA sakigake designation create parallel regulatory momentum for novel sarcoma therapeutics. Stakeholders must monitor biomarker-driven patient stratification and fusion-protein targeting modalities to anticipate therapeutic standard shifts.
Market Dynamics
FDA's accelerated approval pathways for rare oncology indications compress development timelines and reshape competitive entry economics for synovial sarcoma therapeutics. Academic research centers deepen adoption of novel immunotherapy protocols, pulling trial infrastructure toward fusion-protein targeting modalities.
Growth Catalysts
- Orphan Drug Incentives:FDA's orphan drug designation and breakthrough therapy pathways reduce regulatory friction and extend market exclusivity periods for sponsors developing SS18-SSX fusion-directed agents.
- Biomarker Stratification:Academic research centers deploy next-generation sequencing to identify fusion-positive subpopulations, sharpening patient selection for targeted therapy trials.
- Sarcoma Specialist Networks:United States-based sarcoma consortiums concentrate trial enrollment and accelerate protocol adoption across major cancer centers.
Market Restraints
- Microsatellite-Stable Biology:Checkpoint inhibitor monotherapy shows limited efficacy in microsatellite-stable synovial sarcoma, constraining immunotherapy penetration in the dominant patient population.
- Small Addressable Population:Ultra-rare incidence rates across all geographies compress commercial revenue potential and deter late-stage development investment.
- Diagnostic Complexity:SS18-SSX fusion detection requires specialized molecular pathology infrastructure unavailable in community oncology settings.
Strategic Opportunities
- Antibody-Drug Conjugate Expansion:ADC platforms targeting surface antigens on synovial sarcoma cells offer differentiated mechanisms beyond fusion-directed approaches.
- Radioligand Therapy Integration:Novartis-type radioligand assets in soft tissue malignancies create precedent for targeted radiotherapy development in sarcoma subsets.
- Japan's Sakigake Pathway:PMDA's priority review scheme accelerates access for novel sarcoma therapeutics in Asia-Pacific's second-largest oncology market.
Industry Challenges
- Trial Enrollment Velocity:Ultra-rare incidence requires multi-center international coordination to achieve statistical powering within feasible timelines.
- Companion Diagnostic Development:SS18-SSX fusion assay standardization demands alignment between CDx manufacturers and therapy sponsors under FDA's in vitro diagnostic regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synovial Sarcoma Market |
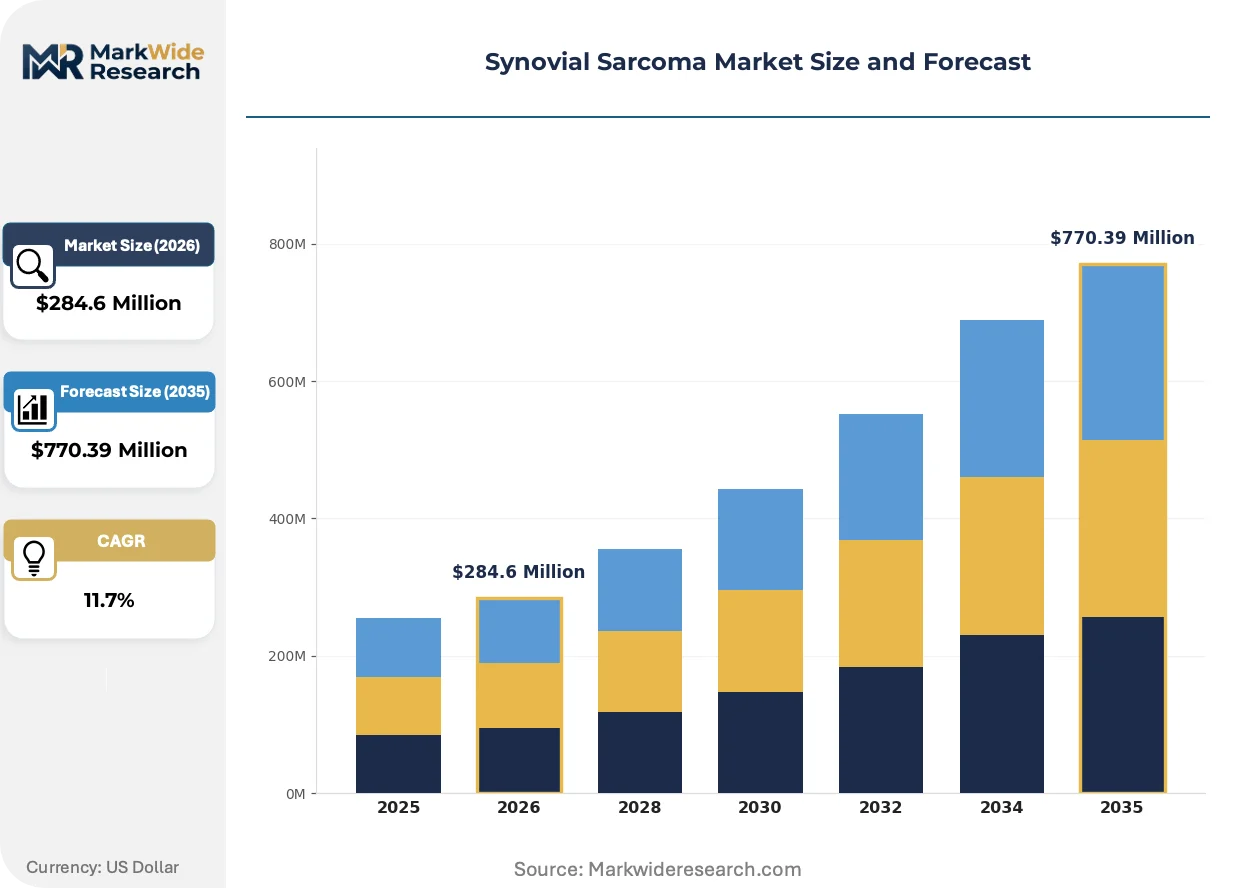
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $770.39 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Targeted Therapy, Immunotherapy Treatment Stage: Neoadjuvant, Adjuvant, Palliative, Post-surgical End User: Hospitals, Outpatient Clinics, Academic Research Centers, Specialty Clinics Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Distributors |
| Companies Covered | Merck & Co., Inc., AstraZeneca PLC, Novartis AG, Advenchen Laboratories, Amgen Inc., Pfizer Inc., Bristol-Myers Squibb Company, Takara Bio, Roche Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synovial Sarcoma Market Strategic Shifts
Novel therapeutic modalities are converging on chromatin dysregulation mechanisms, compressing the historical dominance of cytotoxic chemotherapy in sarcoma management. Three forces are actively restructuring development priorities.
Cell therapy platforms targeting NY-ESO-1 antigen expression are hybridizing with lymphodepletion regimens to enhance expansion and persistence in synovial sarcoma patients. Academic centers at Memorial Sloan Kettering and MD Anderson are advancing Phase II protocols with engineered T-cell receptors. This hybridization is compressing the timeline between proof-of-concept and registrational studies for adoptive cell therapies.
EMA's PRIME scheme is compressing scientific advice timelines for sarcoma developers seeking conditional marketing authorization in Europe. The scheme enables parallel EMA-FDA alignment on novel endpoints for rare oncology indications. European academic networks are responding by centralizing biomarker validation and patient registry infrastructure across France, Germany, and Italy.
Hospital procurement of sarcoma therapeutics is fragmenting toward value-based access agreements that tie reimbursement to progression-free survival outcomes. United States cancer centers are piloting these arrangements through specialty pharmacy networks and integrated delivery systems. This shift is most visible in Medicare Advantage–dominated markets where risk-bearing entities control formulary placement.
Synovial Sarcoma Market Segmentation
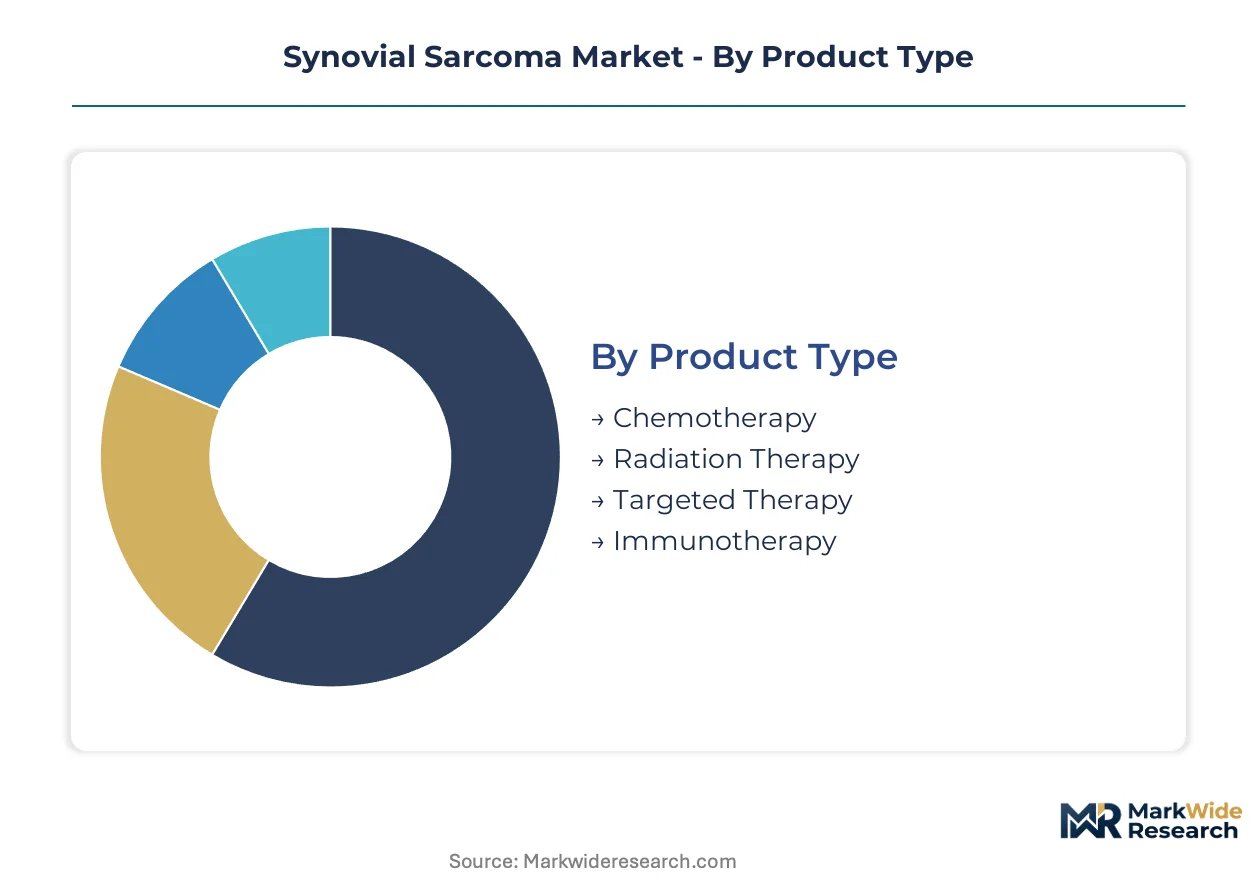
Synovial sarcoma treatment selection hinges on fusion protein status, surgical resectability, and metastatic burden. Segmentation reveals how therapeutic modality, care setting, and procurement channel each impose distinct operational requirements on manufacturers and providers.
Product Type:
After-sales service intensity varies sharply across modalities, with cell therapies demanding cold-chain logistics and patient monitoring infrastructure that chemotherapy distributors rarely maintain.
- Targeted Therapy:SS18-SSX fusion-directed agents exploit chromatin dysregulation mechanisms unique to synovial sarcoma pathogenesis. Academic research centers in the United States concentrate demand for these agents, driven by biomarker-driven trial enrollment and FDA breakthrough therapy pathway acceleration.
- Immunotherapy:Checkpoint inhibitors and engineered T-cell receptor therapies target NY-ESO-1 antigen expression in fusion-positive patients. Memorial Sloan Kettering and MD Anderson anchor adoption, though microsatellite-stable biology constrains efficacy in the dominant patient population.
- Chemotherapy:Anthracycline-ifosfamide regimens retain first-line utility in metastatic settings where fusion-directed options remain investigational.
- Radiation Therapy:Intensity-modulated and proton beam approaches serve limb-sparing surgical protocols in extremity-primary cases.
By volume, chemotherapy leads. By growth pace, targeted therapy is ahead.
Treatment Stage:
Cost tier stratification separates curative-intent multimodal protocols from resource-intensive salvage regimens in recurrent disease.
- Neoadjuvant:Preoperative systemic therapy reduces tumor burden to enable limb-sparing surgery. Sarcoma specialist networks in the United States standardize these protocols through consortium guidelines.
- Adjuvant:Postoperative radiation and chemotherapy address microscopic residual disease. EMA's PRIME scheme accelerates access to novel adjuvant agents in France, Germany, and Italy.
- Post-surgical:Surveillance protocols and local recurrence management occupy outpatient settings with lower acuity infrastructure requirements.
- Palliative:Symptom-directed interventions prioritize quality-of-life endpoints in metastatic or unresectable presentations.
By patient volume, adjuvant therapy leads. By unmet need concentration, palliative care is expanding most quickly.
End User:
Customer type determines procurement sophistication, with integrated delivery systems negotiating value-based contracts that standalone specialty clinics cannot replicate.
- Hospitals:Inpatient surgical resection and complex chemotherapy administration require oncology-certified nursing and stem cell transplant capabilities. Major cancer centers in the United States capture the highest case volumes.
- Academic Research Centers:Phase I/II trial infrastructure and biomarker laboratories concentrate fusion-positive patient identification. Japan's PMDA sakigake designation pulls sponsor investment toward Tokyo and Osaka academic hospitals.
- Specialty Clinics:Sarcoma-dedicated practices manage long-term surveillance and recurrence monitoring in ambulatory settings.
- Outpatient Clinics:Community oncology sites handle stable patients on oral targeted agents with limited molecular pathology support.
By procedure revenue, hospitals lead. By trial enrollment growth, academic research centers are gaining share fastest.
Distribution Channel:
Supply concentration in specialty pharmacy networks shapes channel economics, with limited-distribution drugs bypassing traditional wholesale relationships entirely.
- Direct Sales:Manufacturer-to-provider relationships dominate high-cost cell therapies and radioligand assets requiring specialized handling. Novartis-type direct distribution models in soft tissue malignancies establish precedent.
- Distributors:Regional oncology distributors serve community practices with chemotherapy and supportive care agents across the United States.
- Retail Pharmacies:Oral targeted therapy fulfillment extends into specialty pharmacy networks with prior authorization expertise.
- Online Pharmacies:Digital procurement platforms capture oral agent refills in markets with established telemedicine oncology services.
By transaction volume, distributors lead. By margin capture, direct sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's accelerated approval pathways and orphan drug incentives anchor the United States as the dominant geography for synovial sarcoma therapeutic development. Academic research centers and sarcoma specialist networks concentrate trial infrastructure and patient access. Regulatory frameworks in Japan and Europe create parallel momentum for novel agents targeting SS18-SSX fusion mechanisms.
United States
Sarcoma specialist networks at Memorial Sloan Kettering and MD Anderson drive biomarker-driven trial enrollment for fusion-directed therapies. FDA's breakthrough therapy pathway compresses development timelines for sponsors targeting chromatin dysregulation mechanisms. Boston and Houston academic clusters anchor cell therapy protocol development for NY-ESO-1 antigen targeting.
Japan
PMDA's sakigake designation accelerates priority review for novel sarcoma therapeutics in Asia-Pacific's second-largest oncology market. Tokyo and Osaka academic hospitals concentrate patient registries and biomarker validation infrastructure for fusion-positive subpopulations. Domestic biologics manufacturing scale supports regional supply security for adoptive cell therapies.
Germany
EMA's PRIME scheme enables parallel scientific advice alignment for sarcoma developers seeking conditional marketing authorization. Heidelberg and Berlin academic networks centralize molecular pathology infrastructure for SS18-SSX fusion detection. Hospital procurement pilots tie reimbursement to progression-free survival outcomes in Medicare-equivalent systems.
United Kingdom
NHS England's specialized commissioning frameworks concentrate sarcoma surgical expertise at designated supra-regional centers. London and Manchester academic clusters participate in EMA-aligned biomarker validation consortia for rare oncology indications. NICE technology appraisals shape access negotiations for premium-priced targeted therapies.
Switzerland
Swissmedic's streamlined procedures for orphan medicines complement EMA regulatory pathways for rare oncology indications. Basel and Zurich pharmaceutical clusters host radioligand therapy development programs targeting soft tissue malignancies. Domestic pricing and reimbursement frameworks accommodate value-based access agreements for cell therapies.
Synovial Sarcoma Market Competitive Environment
Checkpoint inhibitor platforms and antibody-drug conjugate pipelines split the market between immunotherapy anchoring and targeted delivery specialization. The competitive structure consolidates around multinational pharmaceutical conglomerates with rare oncology franchises rather than emerging biotech specialists. Large-cap diversified pharmas and mid-cap oncology-focused developers represent the dominant archetypes. Vertical integration into companion diagnostic partnerships and radioligand manufacturing capacity constitute the primary competitive moves.
Within the large-cap tier, Merck & Co. and AstraZeneca occupy positions defined by immunotherapy platform extension and ADC pipeline depth respectively. Novartis anchors the radioligand therapy vector with precedent-setting assets in soft tissue malignancies. These three pharmas exemplify how regulatory pathway expertise and manufacturing scale create defensive positioning in ultra-rare indications with compressed commercial windows.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Novartis AG |
| Advenchen Laboratories |
| Amgen Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Takara Bio |
| Roche Holding AG |
| Others |
Value Chain & Pricing Dynamics
Boston's cell therapy manufacturing cluster anchors production capacity for adoptive T-cell therapies, concentrating supply-side leverage among academic medical centers that negotiate value-based contracts tied to progression-free survival outcomes. This geographic concentration of GMP manufacturing infrastructure enables premium pricing for NY-ESO-1 directed cell therapies while compressing margins for commoditized chemotherapy agents distributed through wholesale channels.
Pricing Analysis
Price spreads between the United States and Japan exceed those within Europe, reflecting divergent reimbursement frameworks for radioligand and cell therapy assets. Three-tier pricing structure across premium, standard, and economy levels separates fusion-directed biologics from anthracycline regimens and supportive care agents. Cost compression in the chemotherapy tier is intensifying as biosimilar ifosfamide enters hospital formularies. Community oncology practices exhibit highest price sensitivity, while academic research centers prioritize clinical efficacy endpoints over acquisition cost.
Supply Chain Analysis
Lonza and Catalent hold contract manufacturing capacity for autologous cell therapy production, with Thermo Fisher anchoring plasmid and viral vector supply. Manufacturing concentrates in the United States, Switzerland, and Singapore to align with FDA, Swissmedic, and PMDA regulatory requirements. Cold-chain logistics for patient-derived cell products rests on liquid nitrogen distribution networks with single-source vulnerability at regional cryogenic storage hubs. Distribution runs through specialty pharmacy networks with limited-distribution designations for fusion-directed agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation into integrated delivery systems is shifting buyer power toward risk-bearing entities that demand outcome-based pricing for premium therapeutics. This consolidation fragments access negotiations across Medicare Advantage-dominated markets and traditional fee-for-service environments.
For Market Incumbents: Insulate market position through captive companion diagnostic partnerships that lock in SS18-SSX fusion testing workflows at major cancer centers. Secure backward integration into radioligand manufacturing isotope supply to defend against Novartis-type competitors entering soft tissue malignancies. Prioritize FDA breakthrough therapy pathway maintenance to compress competitor entry timelines. For New Entrants and Emerging Players: Japan's palliative care segment offers underpenetrated access for symptom-directed therapies, with PMDA sakigake designation accelerating priority review timelines. Target academic research centers in Osaka and Tokyo for biomarker-driven trial enrollment, leveraging domestic biologics manufacturing scale for regional supply security. Pursue lymphodepletion regimen partnerships with Memorial Sloan Kettering and MD Anderson to accelerate cell therapy protocol adoption. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among antibody-drug conjugate platforms with surface antigen targeting mechanisms beyond SS18-SSX fusion approaches. Long-term viability hinges on regulatory pathway expertise in ultra-rare oncology indications with compressed commercial windows. Target mid-cap developers with radioligand therapy assets in soft tissue malignancies. Watch for EMA-FDA parallel scientific advice alignment as inflection signal for accelerated approval probability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Memorial Sloan Kettering and MD Anderson anchor Phase II NY-ESO-1 T-cell receptor protocols. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for fusion-directed agents. |
| Licensing Agreement | Companion diagnostic partnerships lock in SS18-SSX fusion assay standardization at major centers. |
| Manufacturing Scale-Up | Boston's GMP cell therapy cluster expands cold-chain capacity for autologous product distribution. |
| Pipeline Diversification | Antibody-drug conjugate platforms target surface antigens beyond chromatin dysregulation mechanisms. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient volume modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Forecast inputs considered treatment line, administration route, patient population, and regional regulatory cluster segmentation dimensions. CAGRs were derived from epidemiological incidence projections, trial enrollment velocity assumptions, and pricing evolution under value-based access agreements. Biomarker penetration rates and fusion-directed therapy adoption curves shaped volume forecasts.
Practitioners should monitor checkpoint inhibitor efficacy readouts in microsatellite-stable subpopulations and companion diagnostic assay standardization progress for early signals of therapeutic standard shifts. Forecasts reflect assumptions about regulatory pathway maintenance and reimbursement framework stability. Quarterly review of FDA breakthrough therapy designations and EMA PRIME scheme admissions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market