
 Cognitive Ingredients Market | 2026-2036
Cognitive Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Ingredients Market Analytics
Buyer concentration among functional food and beverage manufacturers is consolidating as large CPG portfolios absorb smaller wellness brands seeking cognitive positioning. Nestle leverages its nutritional science infrastructure to anchor premium nootropic product lines across multiple continents. Koninklijke DSM competes through its specialized micronutrient premix capabilities, while Kerry Group extends its flavor-masked active delivery systems into gummy and beverage formats for cognitive claims.
Cognitive ingredients comprise bioactive compounds including nootropics, herbal extracts, amino acids, and vitamins formulated to modulate neurotransmitter activity, cerebral blood flow, or neuroplasticity pathways, typically standardized to specific marker compound concentrations such as 20-50% bacosides for Bacopa monnieri or 98% purity for synthetic racetams. These ingredients serve primary commercial purposes in dietary supplements, fortified foods, and clinical nutrition products targeting measurable cognitive endpoints. Nootropics command the largest current revenue pool due to established prescriber familiarity and direct-to-consumer marketing scale, while gummy formats represent the fastest-growing delivery segment as palatability requirements reshape compliance among student and professional end users. Memory enhancement applications sustain premium pricing relative to energy boosters, which face commoditization from mainstream caffeine alternatives.
FDA oversight of dietary supplement GMPs, EFSA novel food authorization requirements, and Health Canada's Natural Health Product regulations collectively determine market access timelines and substantiation burdens for cognitive ingredient suppliers. DSHEA's structure permits structure-function claims while prohibiting disease treatment language, creating a compliance boundary that shapes formulation marketing and clinical trial investment. Stakeholders must monitor evolving substantiation standards across jurisdictions where regulators increasingly demand human intervention data rather than mechanistic or animal evidence for cognitive benefit claims.
Market Dynamics
Functional food and beverage manufacturers are consolidating cognitive ingredient procurement around vertically integrated suppliers capable of delivering validated nootropic formulations with palatable delivery systems, compressing the vendor base and elevating substantiation requirements for market access.
Growth Catalysts
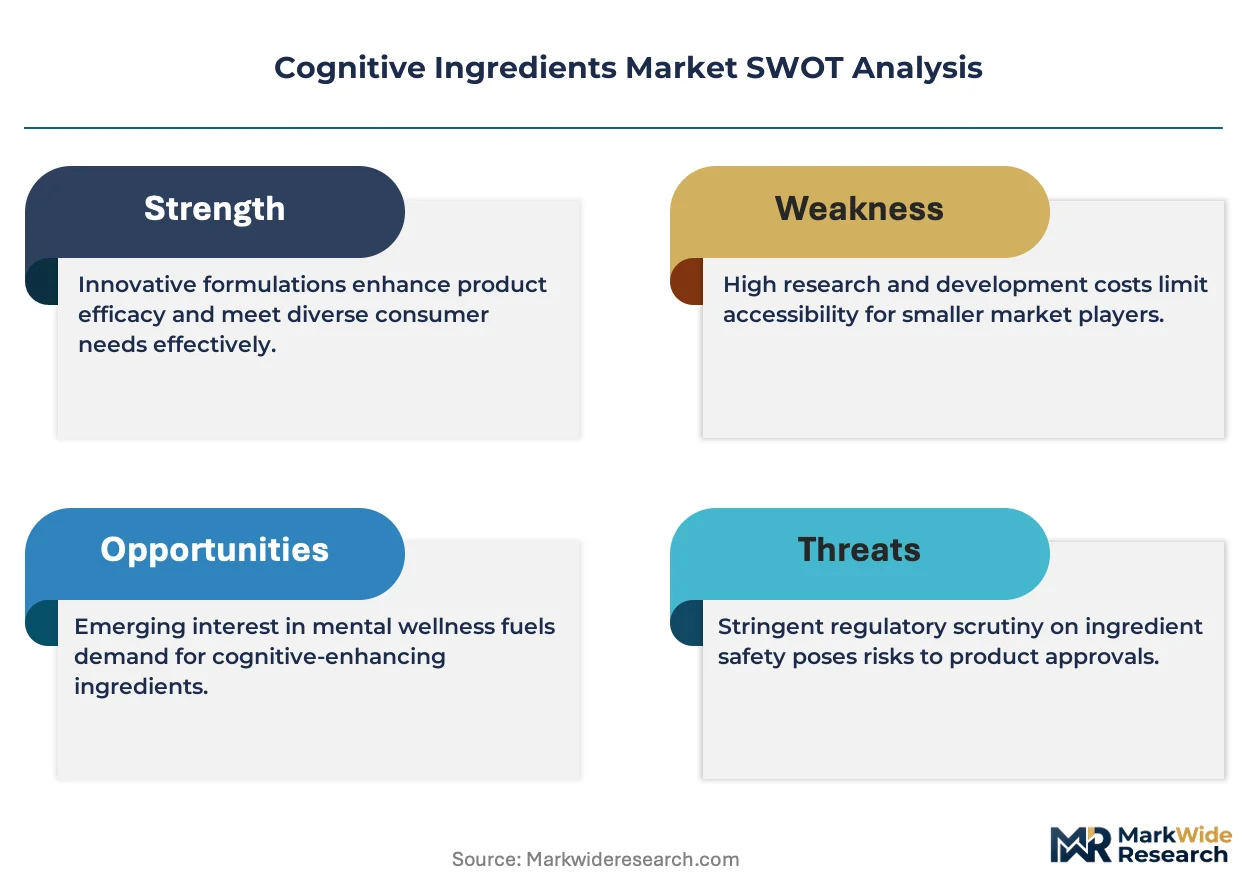
- EFSA novel food pathway:The European Food Safety Authority's structured authorization process provides regulatory certainty for botanical nootropics entering fortified food matrices, accelerating European market entry timelines for compliant suppliers.
- Gummy format innovation:Flavor-masked active delivery systems are expanding compliance among student and professional demographics who reject traditional capsule formats, opening new consumption occasions for cognitive products.
- Clinical validation infrastructure:Investment in human intervention trials for memory and focus endpoints satisfies escalating retailer and consumer demands for evidence-based claims beyond mechanistic or animal data.
Market Restraints
- Raw material concentration:Bacopa monnieri and Ginkgo biloba extract supply concentrates in Indian and Chinese agricultural zones, exposing formulators to monsoon variability and export policy shifts.
- Substantiation cost escalation:EFSA and FDA demands for human clinical data on cognitive endpoints require multi-million dollar trial investments that exclude smaller ingredient suppliers from premium positioning.
- Caffeine commoditization:Mainstream energy boosters face price compression from synthetic caffeine and guarana alternatives, narrowing margin pools for novel stimulant development.
Strategic Opportunities
- Esports and gaming vertical:Professional gaming organizations in South Korea and the United States are adopting nootropic stacks for reaction-time optimization, creating a channel distinct from traditional supplement retail.
- Personalized nutrition platforms:Direct-to-consumer genetic testing and microbiome analysis services enable tailored cognitive formulations based on individual neurotransmitter metabolism profiles.
- Geriatric clinical nutrition:Hospital and long-term care facilities in Japan are integrating standardized nootropic premixes into medical foods for mild cognitive impairment management under PMDA guidance.
Industry Challenges
- Cross-jurisdictional claim alignment:Marketing teams must reconcile DSHEA-permitted structure-function language with EFSA's stricter health claim substantiation requirements, fragmenting global campaign execution.
- Active stability in matrices:Heat and pH sensitivity of racetams and botanical glycosides complicates integration into ready-to-drink beverages and baked goods, demanding specialized encapsulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Ingredients Market |
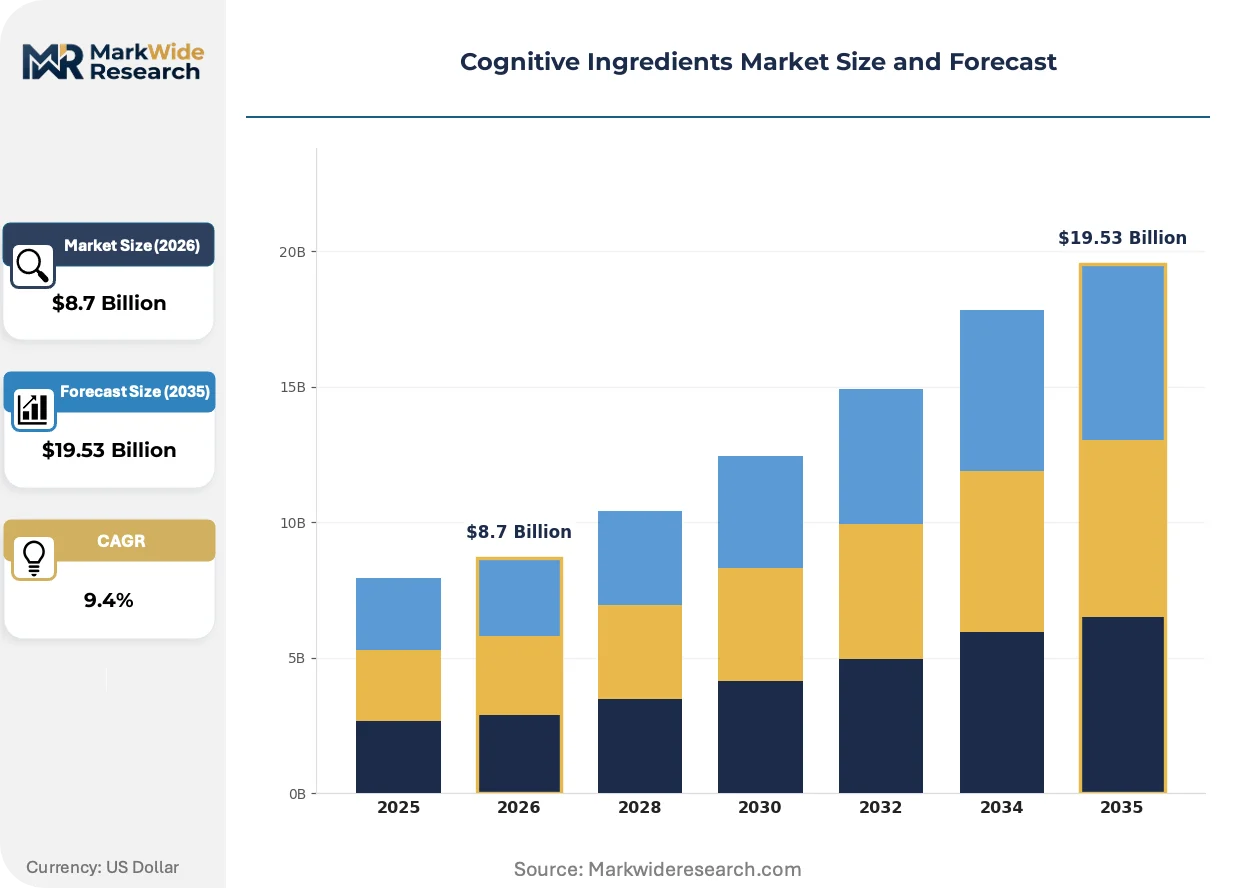
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nootropics, Herbal Extracts, Amino Acids, Vitamins Application: Energy Boosters, Memory Enhancement, Mood Support, Focus Improvement End User: Students, Professionals, Athletes, Elderly Form: Pills, Powders, Gummies, Beverages |
| Companies Covered | Nestle, Danone, Koninklijke DSM, BASF, Cargill, DuPont de Nemours, Kerry Group, Herbalife Nutrition, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Ingredients Market Evolving Landscape
Delivery technology advances and regulatory convergence are compressing the gap between pharmaceutical-grade nootropic development and mainstream food and beverage integration, reshaping how cognitive benefits reach consumers.
Microencapsulation of heat-sensitive actives is converging with beverage manufacturing lines previously incompatible with nootropic stability requirements. Functional drink producers in Germany and California are adopting lipid-based shell technologies at pilot scale. This convergence is collapsing the traditional separation between supplement and food-grade processing infrastructure.
EFSA's evolving novel food catalog is tightening botanical extract specifications for synthetic adulterant detection and marker compound standardization. European formulators must now document supply chain integrity from cultivation to extraction. Memory enhancement applications face the highest scrutiny, with bacoside content verification becoming a gatekeeper for premium positioning.
Subscription-based replenishment models are displacing conventional retail purchasing for cognitive supplement users. Direct-to-consumer platforms in the United States capture recurring revenue through personalized stack recommendations based on usage pattern analytics. This behavioral shift concentrates buyer data with vertically integrated brands and weakens traditional wholesale relationships.
Cognitive Ingredients Market Segmentation
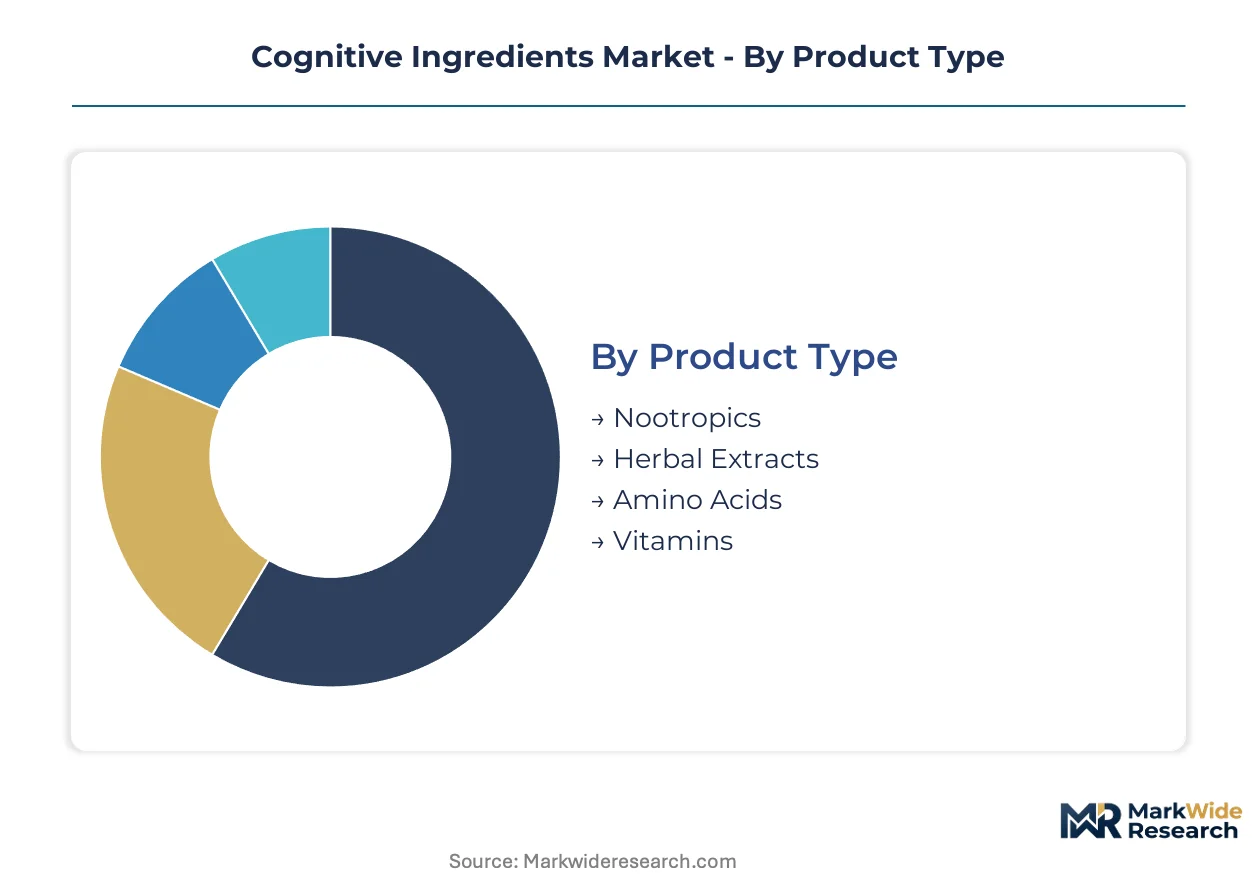
Cognitive ingredient suppliers configure product portfolios around distinct efficacy profiles and delivery constraints. Each segmentation axis reveals divergent margin structures and substantiation burdens that shape competitive positioning.
Product Type:
Nootropics anchor volume demand while herbal extracts command premium positioning through traceability requirements.
- Nootropics:Synthetic and semi-synthetic compounds including racetams and cholinergics standardized to 98% purity specifications. Demand concentrates in United States dietary supplement channels where DSHEA permits structure-function claims without disease treatment language, though FDA GMP compliance costs exclude smaller formulators.
- Herbal Extracts:Botanical concentrates such as Bacopa monnieri and Ginkgo biloba with defined marker compound ranges, typically 20-50% bacosides. European functional food manufacturers in Germany and Netherlands drive premium procurement as EFSA novel food approvals require cultivation-to-extraction documentation.
- Amino Acids:Precursor compounds including L-theanine and acetyl-L-carnitine supporting neurotransmitter synthesis.
- Vitamins:B-complex and fat-soluble micronutrients formulated for cerebral metabolism support.
Today's leader: Nootropics. Tomorrow's challenger: Herbal Extracts.
Application:
Memory enhancement sustains pricing power while energy boosters face commodity pressure from mainstream caffeine alternatives.
- Memory Enhancement:Formulations targeting episodic and working memory endpoints through neuroplasticity modulation. Clinical trial investment for substantiation runs highest here, with Japanese hospital nutrition departments integrating standardized premixes into medical foods under PMDA guidance.
- Energy Boosters:Acute alertness and fatigue-masking products competing with synthetic caffeine and guarana. Price compression is severe in United States mass-market channels where energy drink manufacturers internalize stimulant sourcing.
- Mood Support:Serotonin and GABA pathway modulators addressing stress response.
- Focus Improvement:Sustained attention formulations popular among knowledge workers.
Memory Enhancement captures margin. Focus Improvement climbs fastest.
End User:
Professional demographics drive gummy format innovation while elderly segments anchor clinical nutrition contracts.
- Professionals:Corporate employees and remote workers seeking productivity optimization without prescription stimulants. South Korean esports organizations and United States tech sector employers subsidize nootropic stacks, creating direct procurement channels outside retail.
- Elderly:Aging populations in Japan and Germany consuming clinically validated formulations for mild cognitive impairment management. Long-term care facilities specify premixed medical foods with documented bacoside content.
- Students:Academic performance seekers in examination-intensive education systems.
- Athletes:Competitors targeting reaction time and decision speed under anti-doping constraints.
Professionals define format innovation. Elderly segments lock in contract stability.
Form:
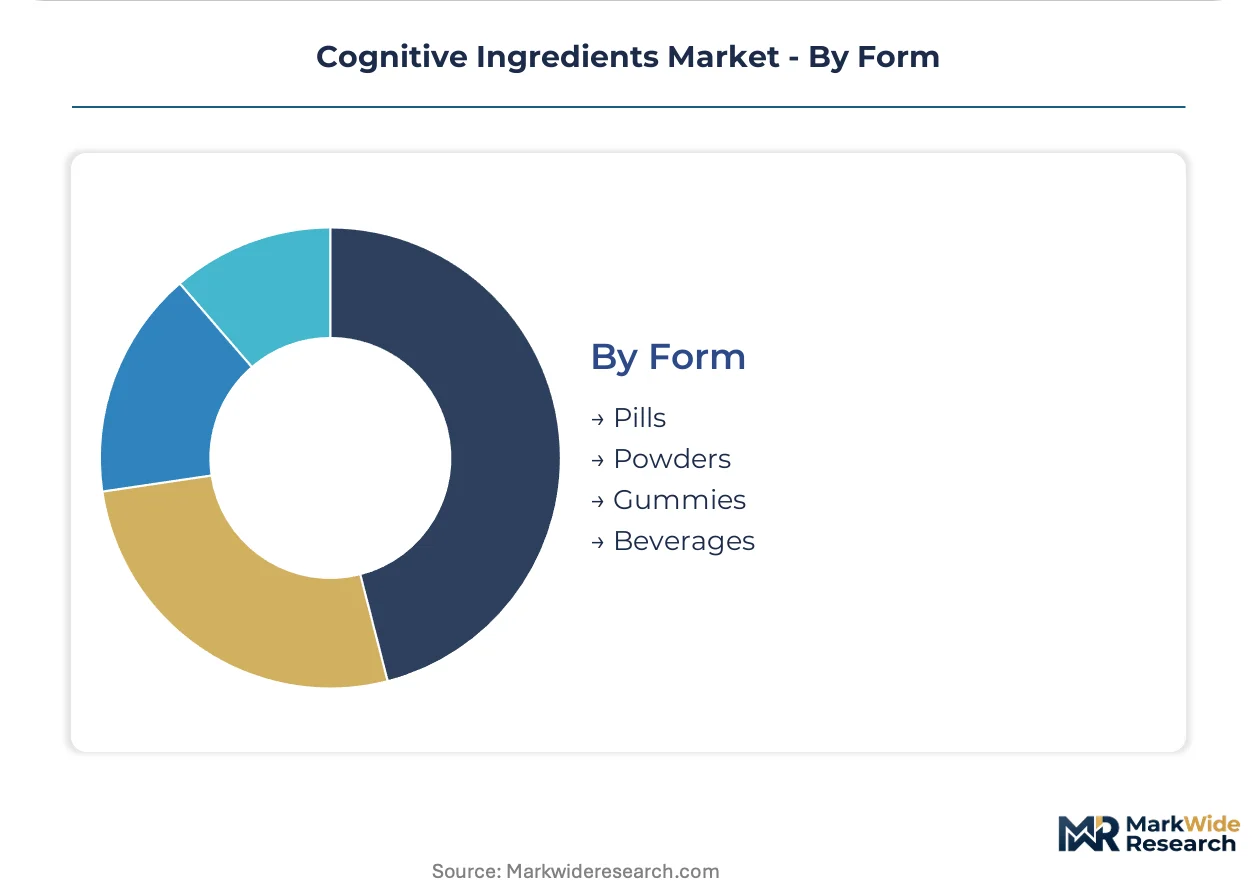
Gummy and beverage formats are collapsing the traditional supplement-food boundary through palatability engineering.
- Gummies:Flavor-masked active delivery systems expanding compliance among demographics rejecting capsules. Kerry Group and specialized contract manufacturers in California and Germany scale lipid-based encapsulation to protect heat-sensitive racetams and botanical glycosides during processing.
- Beverages:Ready-to-drink functional formats requiring pH-stable active integration. German and Californian pilot lines adopt microencapsulation to enable nootropic inclusion in carbonated and still drinks previously incompatible with botanical stability profiles.
- Pills:Traditional capsule and tablet formats with established manufacturing infrastructure.
- Powders:Bulk active materials for stack customization and foodservice integration.
Gummies gain share fastest. Beverages await stability breakthroughs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan diverge sharply in cognitive ingredient deployment: German functional food manufacturers prioritize EFSA-compliant botanical extracts for mass-market fortification, while Japanese clinical nutrition channels integrate nootropic premixes into medical foods under PMDA oversight for elderly care applications.
United States
DSHEA framework permits structure-function claims for nootropic supplements, driving direct-to-consumer subscription models and esports procurement channels. FDA GMP enforcement elevates compliance costs, squeezing smaller formulators from premium positioning. California and Massachusetts clusters host flavor-masked delivery system innovators serving gummy and beverage format producers.
Germany
EFSA novel food approvals accelerate botanical nootropic integration into fortified foods and ready-to-drink beverages. REACH chemical registration requirements apply to synthetic racetam imports, extending authorization timelines. Bavaria and Baden-Württemberg concentrate microencapsulation technology providers enabling heat-sensitive active stability in beverage matrices.
Japan
PMDA medical food guidance permits nootropic premixes in hospital and long-term care nutrition for mild cognitive impairment management. Aging demographics sustain contract stability for clinically validated formulations. Kanto region anchors pharmaceutical-grade ingredient manufacturing, while Kansai processors specialize in geriatric-targeted delivery formats.
South Korea
MFDS dietary supplement regulations accommodate esports and gaming vertical demand for reaction-time optimization stacks. Professional gaming organizations procure directly, bypassing traditional retail channels. Seoul Capital Area concentrates formulation houses serving both domestic teams and export markets.
India
FSSAI food safety standards govern Bacopa monnieri extract exports to European and North American formulators. Monsoon variability and export policy shifts expose supply chain concentration risks. Maharashtra and Karnataka agricultural zones dominate raw material cultivation, with Hyderabad processing clusters handling standardized bacoside extraction.
Cognitive Ingredients Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Large CPG portfolios absorb smaller wellness brands seeking cognitive positioning, compressing vendor diversity. Three archetypes dominate: nutritional science conglomerates leveraging R&D infrastructure, micronutrient premix specialists, and flavor-masked delivery system providers. M&A activity and clinical validation partnerships constitute the primary competitive moves, as substantiation costs exclude marginal players from premium segments.
Within the nutritional science tier, Nestle and Danone exemplify diversified conglomerates anchoring premium nootropic product lines across multiple continents. Koninklijke DSM occupies a specialized position among micronutrient premix providers, while Kerry Group represents the delivery system archetype extending flavor-masked active technologies into gummy and beverage formats. These three entities collectively illustrate the vertical integration pressures reshaping supplier relationships with functional food and beverage manufacturers.
| Leading Market Players |
|---|
| Nestle |
| Danone |
| Koninklijke DSM |
| BASF |
| Cargill |
| DuPont de Nemours |
| Kerry Group |
| Herbalife Nutrition |
| Lonza Group |
| Others |
Value Network & Pricing Analysis
Bacoside spot indices from Maharashtra agricultural auctions cascade through extraction tolls, EFSA certification premiums, and gummy format encapsulation costs to stratify cognitive ingredient pricing across pharmaceutical-grade, functional food, and mass-market supplement tiers.
Pricing Analysis
Capacity additions in Bavaria and Baden-Württemberg are reshaping price floors for microencapsulated botanical extracts. Three-tier pricing structure across premium, standard, and economy levels separates EFSA novel food-certified extracts from DSHEA-compliant dietary supplement grades and uncertified commodity powders. Price differentiation hinges on bacoside standardization precision and cultivation-to-extraction traceability documentation. Cost compression in energy booster segments runs through synthetic caffeine substitution, while memory enhancement formulations retain pricing power with elderly care facilities in Japan.
Supply Chain Analysis
Bacopa monnieri biomass supply rests on monsoon-dependent cultivation zones in Maharashtra and Karnataka, with Hyderabad processing clusters handling standardized extraction. Synthetic racetam production draws from Chinese pharmaceutical intermediate manufacturers and Indian contract synthesis facilities. Ginkgo biloba leaf sourcing concentrates in Chinese agricultural cooperatives subject to export license variability. Single-source vulnerability in monsoon-exposed Indian agricultural zones threatens bacoside concentrate availability. Distribution runs through vertically integrated CPG procurement offices, direct-to-consumer subscription platforms, and hospital nutrition service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as elderly care facilities and esports organizations alike shift procurement toward clinically validated, traceable formulations with documented marker compound specifications.
For Market Incumbents: Anticipate margin compression from flavor-masked delivery system commoditization by locking in multi-year Bacopa monnieri offtake agreements with Maharashtra cultivators before monsoon volatility escalates raw material costs. Backward integration into Hyderabad extraction infrastructure defends positioning against DSM and Kerry Group premix competition. Prioritize EFSA novel food dossier maintenance as regulatory scrutiny tightens on synthetic adulterant detection. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting United States remote workers and South Korean esports organizations, bypassing retail margin extraction entirely. White-space concentration sits in personalized nutrition platforms integrating genetic testing with nootropic stack customization. The most penetrable segment comprises student demographics in examination-intensive Asian education systems seeking palatable gummy alternatives to capsule fatigue. For Investors and Strategic Acquirers: Consolidation pressure builds where clinical validation costs exclude sub-scale botanical extract suppliers from EFSA novel food approval pathways. Long-term viability favors acquisition targets possessing captive cultivation relationships in India, microencapsulation IP for beverage matrix stability, and existing hospital nutrition service contracts. Watch for MFDS regulatory expansion permitting medical food claims as the signal indicating Japanese-style clinical integration spreading to South Korean elderly care markets.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Partnership | Human intervention trials for memory endpoints satisfy EFSA substantiation requirements for novel food approvals. |
| Backward Integration into Cultivation | Captive Bacopa monnieri farming in Maharashtra insulates against monsoon-driven supply disruptions and export policy shifts. |
| Flavor-Masked Delivery System Scale-Up | Lipid-based encapsulation technology enables racetam stability in German and Californian beverage pilot lines. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models concentrate buyer data and weaken traditional wholesale channel dependence. |
| Esports Organization Procurement Contract | South Korean and United States gaming teams create direct procurement channels outside conventional supplement retail. |
Research Methodology
Multiple input streams — regulatory filing databases, agricultural commodity auction records, and hospital nutrition procurement contracts — were reconciled through structured interviews with botanical extract procurement managers, EFSA regulatory consultants, functional food R&D directors, and long-term care facility nutrition officers. Secondary validation incorporated FDA warning letter archives, EFSA novel food catalog updates, FSSAI export certification registries, and PMDA medical food guidance documents. Bottom-up volume modeling triangulated against top-down spending estimates from CPG R&D budget disclosures.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type purity specifications, application endpoint requirements, end-user demographic profiles, and delivery format stability constraints. CAGRs derived from volume trajectory analysis incorporating raw material availability projections, regulatory approval timeline assumptions, and format adoption curve patterns. Industry-specific forecast inputs encompassed monsoon variability indices for Indian agricultural zones and esports organization sponsorship spending trends.
Several conditions sit outside the modeled scope, including abrupt EFSA novel food approval reversals, synthetic racetam scheduling reclassification by national regulators, and catastrophic monsoon failure events. Forecasts reflect documented assumptions about regulatory stability, cultivation yield continuity, and consumer willingness-to-pay for substantiated cognitive claims. A small set of named triggers warrants ongoing watch: MFDS medical food pathway expansion, REACH registration burden escalation for racetam imports, and carbonated beverage manufacturer adoption of microencapsulated nootropic formats.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
APAC Savoury Ingredients Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Almond Flour Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Germany Protein Market
Ingredients
US Ingredients Market
Ingredients
Non-GMO Oil Market
Ingredients
Dark Yeast Extract Market
Ingredients
Seaweed Derivatives Market
Ingredients
Casein and Caseinates Market
Ingredients
North America Feed Yeast Market