
 Textured Milk Protein Market | 2026-2036
Textured Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Textured Milk Protein Market Outlook
Asset-light contract manufacturing and third-party toll processing is reshaping competitive entry in textured milk protein production, lowering capital barriers for mid-scale entrants. Fonterra Co-Operative Group leverages its New Zealand dairy sourcing network to anchor supply security for international customers. Glanbia plc sustains R&D intensity in protein texturization systems that improve hydration rates. Arla Foods Ingredients differentiates through specialized fractionation capabilities that yield consistent functional performance.
Textured milk protein denotes dairy-derived proteins that undergo thermo-mechanical processing to create fibrous or layered structures mimicking meat tissue, typically achieving protein contents between 50% and 90% depending on concentration grade. These ingredients function primarily as structural binders and moisture-retention agents in plant-forward food formulations. Whey protein fractions command premium positioning in nutritional supplements where rapid amino-acid absorption drives formulation preference, while milk protein concentrate segments serve cost-sensitive meat-alternative applications with balanced casein-to-whey ratios. Bakery-product demand for granule-form textured proteins is accelerating as clean-label reformulation replaces chemical emulsifiers.
The EU Green Deal and REACH chemical safety standards constrain ingredient sourcing for European food manufacturers, pushing verification of sustainable dairy supply chains. FDA GRAS self-affirmation and USDA organic certification govern US market access, with the latter commanding price premiums in nutraceutical channels. Stakeholders must monitor evolving protein-labeling regulations that redefine how dairy-derived ingredients position against emerging precision-fermentation competitors.
Market Dynamics
Carbon-accounting mandates under the EU Green Deal are forcing plant-based meat manufacturers to requalify ingredient sourcing, accelerating textured milk protein adoption as a verified lower-emission binder versus soy isolates.
Growth Catalysts
- REACH chemical safety standards:European formulators face restricted emulsifier palettes, pushing substitution toward clean-label dairy proteins with equivalent functional performance in meat analogues.
- Industrial bakery clean-label reformulation:German manufacturers replace chemical dough conditioners with granule-form textured proteins that deliver equivalent crumb structure without E-number declarations.
- Precision fractionation technologies:Advanced membrane separation yields consistent casein-to-whey ratios, enabling repeatable hydration behavior that contract manufacturers require for toll-processing agreements.
Market Restraints
- Whey protein concentrate input volatility:Dairy commodity price swings transmit directly to textured protein production economics, compressing margin visibility for mid-scale toll processors.
- New Zealand supply concentration:Fonterra's dominance in international dairy protein trade creates single-source vulnerability for European and Asian manufacturers without backward integration into milk powder supply.
- Precision-fermentation substitution threat:Lab-derived whey proteins from Perfect Day and competitors achieve equivalent amino-acid profiles without dairy supply chain carbon intensity, threatening premium positioning.
Strategic Opportunities
- USDA organic certification tailwind:American nutraceutical channels command 15-30% price premiums for certified organic textured proteins, opening margin expansion for fractionators with dual conventional-organic lines.
- India PLI scheme for food processing:Production-linked incentives for value-added dairy products attract contract manufacturing investment to serve Southeast Asian meat-alternative formulators.
- Direct-to-manufacturer digital procurement platforms:B2B ingredient marketplaces disintermediate traditional distributor networks, enabling smaller textured protein producers to access plant-based startup customers without field sales investment.
Industry Challenges
- Thermo-mechanical process engineering talent scarcity:Equipment optimization for fiber orientation requires specialized dairy technology expertise concentrated in Danish and Dutch technical universities.
- FDA GRAS self-affirmation documentation burden:Novel fractionation processes trigger extensive safety dossier requirements, extending commercialization timelines for innovative textured protein variants.
- Legacy ERP integration with batch-tracking systems:Full dairy supply chain traceability for EU Green Deal verification demands real-time data architecture upgrades that smaller toll processors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textured Milk Protein Market |
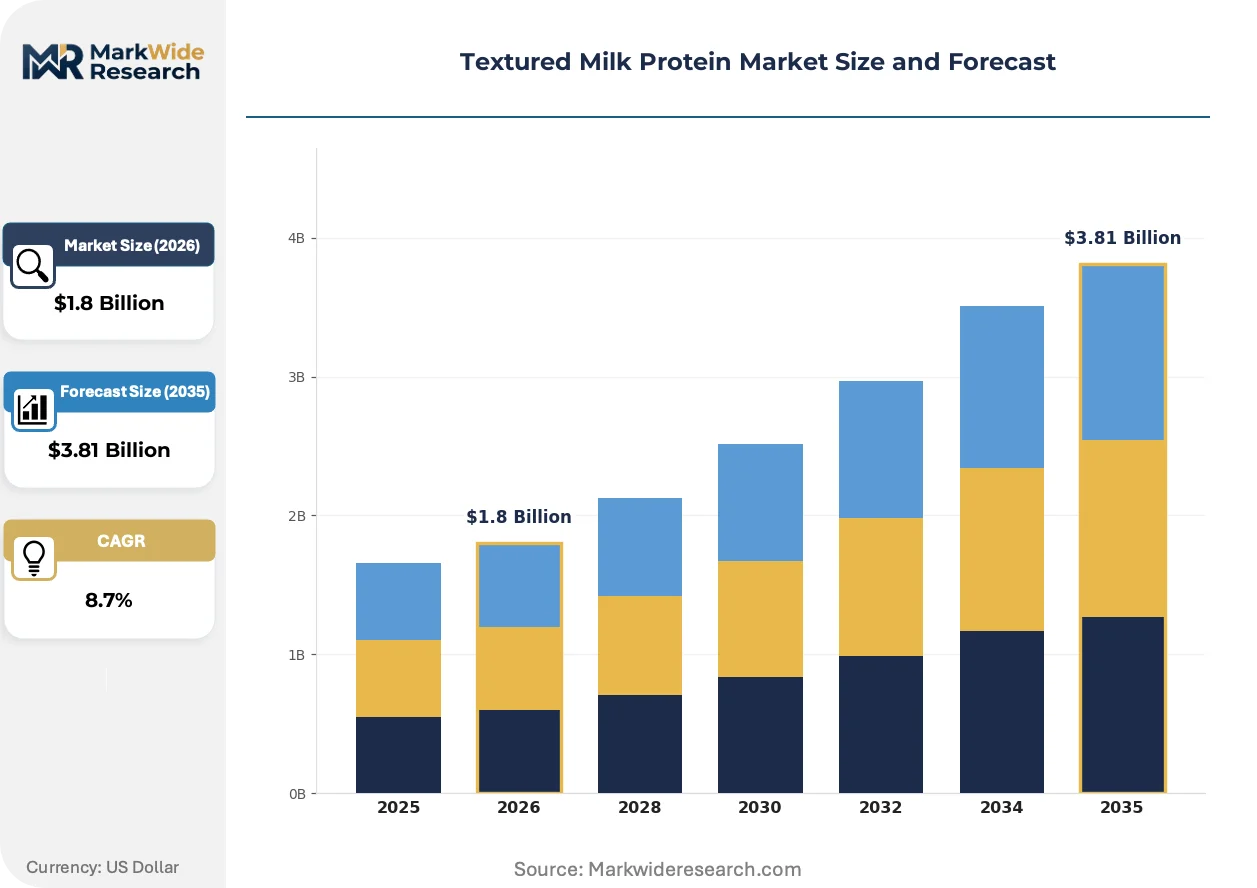
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casein, Whey Protein, Milk Protein Concentrate, Milk Protein Isolate Application: Dairy Products, Nutritional Supplements, Meat Alternatives, Bakery Products Form: Powder, Liquid, Granules, Solid End User: Food Industry, Beverage Industry, Nutraceuticals, Animal Feed |
| Companies Covered | Fonterra Co-Operative Group, Société FIT, Ingredia SA, Kerry Group plc, Socius Ingredients, FrieslandCampina Ingredients, Glanbia plc, Arla Foods Ingredients, Milk Specialties Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textured Milk Protein Market Strategic Shifts
High-moisture extrusion systems and advanced drying technologies are compressing equipment footprints while expanding the texture range achievable from standard milk protein concentrates.
High-moisture twin-screw extrusion achieves fibrous meat-like textures without post-extraction drying steps, reducing energy intensity by half versus traditional processes. European plant-based meat startups in the Netherlands and Germany adopt these systems within 18-month equipment payback periods. Batch-consistent fiber alignment is rendering obsolete the need for lengthy hydration protocols that previously constrained production scheduling.
The EU Green Deal's tightening Scope 3 emissions disclosure requirements force ingredient suppliers to document farm-level methane and energy inputs. Dairy processors respond by installing biogas capture at cooperative member farms to qualify textured proteins for carbon-neutral procurement tenders. German industrial bakery customers now specify verified low-carbon supply chains in annual ingredient agreements.
Ingredient buyers in meat-alternative manufacturing consolidate supplier relationships from twelve to three qualified vendors, prioritizing those with integrated fractionation-to-texturization capabilities. This concentration rewards Arla Foods Ingredients and Glanbia with multi-year volume commitments while squeezing pure-play toll processors. The shift is most visible in Scandinavian markets where sustainability scorecarding drives procurement decisions.
Textured Milk Protein Market Segmentation
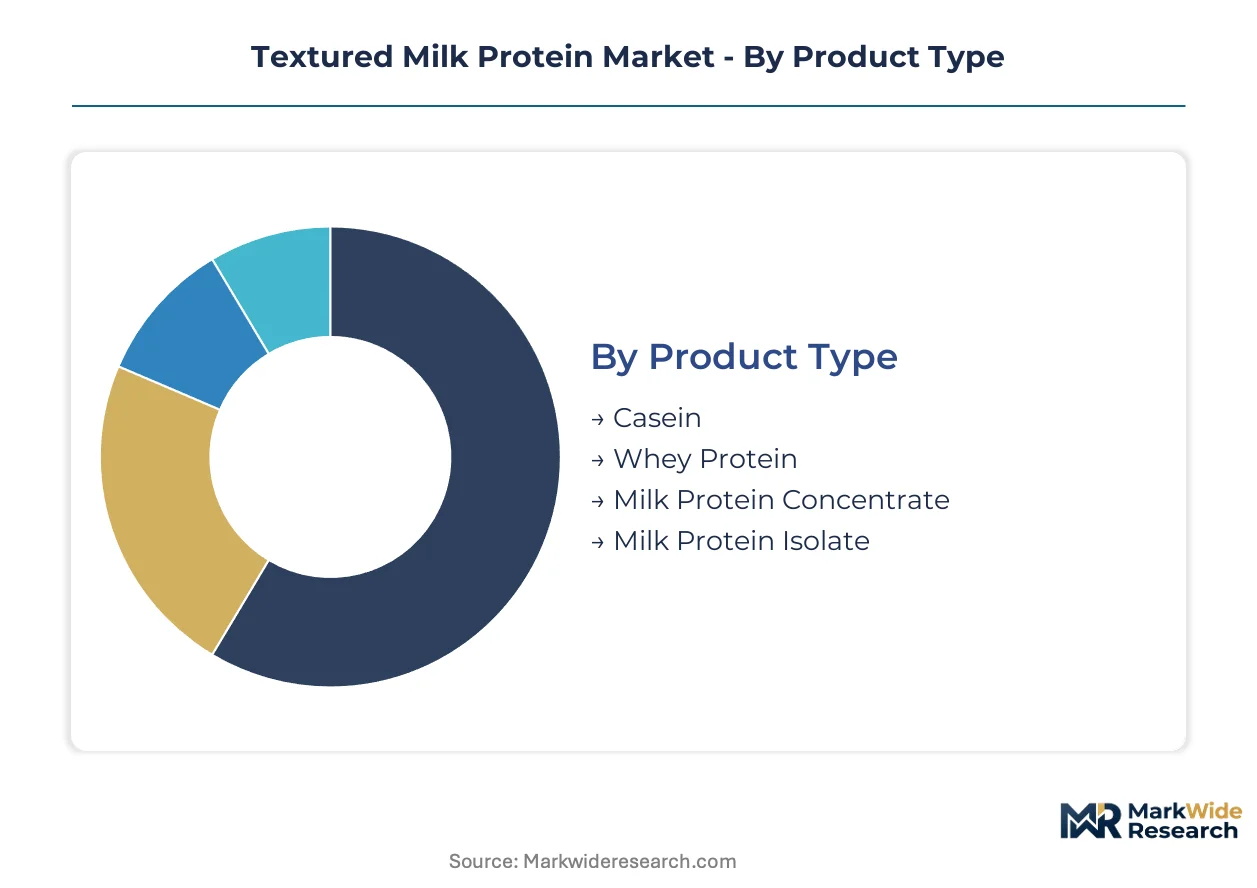
Segmentation in textured milk protein markets reveals how protein fractionation capabilities align with distinct functional requirements across food manufacturing. Each category reflects divergent cost structures, processing intensities, and regulatory exposure that shape supplier positioning.
Product Type:
Mature protein fractions dominate volume throughput while emerging concentrates capture reformulation-driven expansion.
- Casein:Slow-digesting micellar structures deliver sustained amino-acid release for sports nutrition and clinical applications. German dairy processors prioritize casein for clean-label pudding and dessert applications where EU additive restrictions limit hydrocolloid alternatives.
- Whey Protein:Rapidly absorbed beta-lactoglobulin and alpha-lactalbumin fractions command premium positioning in post-workout formulations. American nutraceutical channels specify whey for rapid absorption protocols, though precision-fermentation substitutes threaten this segment's carbon-accounting advantage.
- Milk Protein Concentrate:Balanced casein-to-whey ratios at 40-85% protein content serve cost-sensitive meat-analogue binders.
- Milk Protein Isolate:90%+ protein purity enables low-moisture applications where minimal carbohydrate carryover matters.
Milk protein concentrate handles the majority of throughput; whey protein is the fastest mover on share.
Application:
Cost tier differentiation separates commodity binders from performance-grade nutritional ingredients.
- Dairy Products:Textured proteins replace skim milk powder in Greek yogurt and cheese analogues to boost protein claims without lactose concentration. Dutch dairy cooperatives deploy these ingredients to meet retailer clean-label requirements while maintaining yield economics.
- Nutritional Supplements:Instantized and agglomerated forms dissolve rapidly in ready-to-drink formats. Sports nutrition brands in the United States specify cold-processed whey isolates to preserve bioactive peptide integrity for immune-positioned products.
- Meat Alternatives:Fibrous extrudates mimic myofibrillar texture in plant-based burgers and sausages.
- Bakery Products:Granule-form proteins replace DATEM and SSL emulsifiers in clean-label bread formulations.
Meat alternatives concentrate procurement volume growth; bakery products are expanding most quickly as E-number elimination accelerates.
Form:
Customer type preferences diverge between industrial-scale powder handlers and specialized liquid processors.
- Powder:Spray-dried agglomerates with controlled particle size distribution dominate bulk ingredient logistics. Contract manufacturers in India prefer powder forms for PLI scheme-compliant dairy value-addition facilities serving Southeast Asian export markets.
- Liquid:Pre-hydrated protein suspensions eliminate reconstitution steps in continuous-process beverage lines.
- Granules:Controlled-density particles disperse uniformly in dough systems without pre-shear requirements.
- Solid:Compressed or extruded blocks suit limited-ingredient pet food and feed applications.
Powder maintains dominant share in international trade; liquid forms are gaining share fastest among integrated beverage processors.
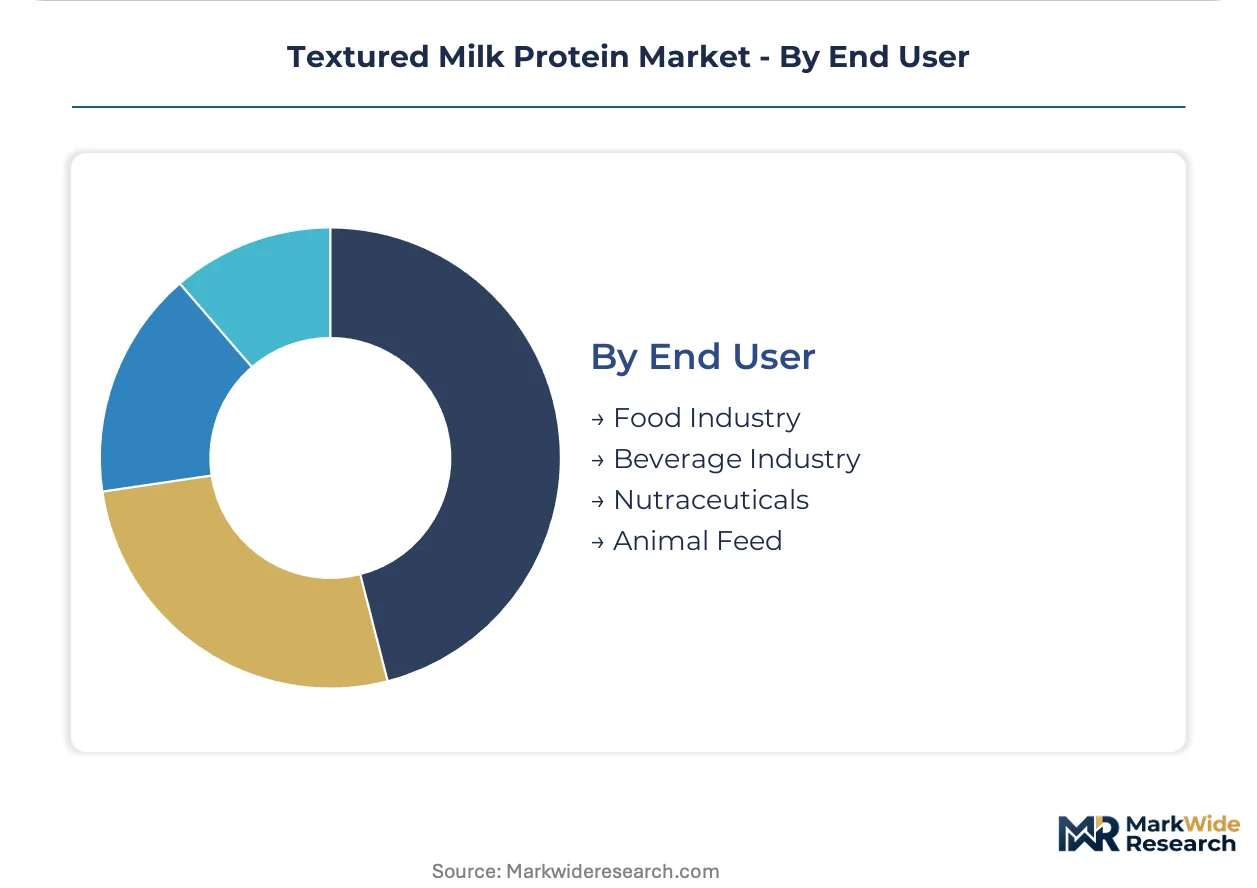
End User:
Volume concentration in food manufacturing contrasts with margin premium capture in specialized channels.
- Food Industry:Industrial bakeries and meat-analogue manufacturers drive tonnage demand for standard-grade concentrates. German industrial bakery procurement specifications now mandate verified low-carbon supply chains under annual ingredient agreements.
- Nutraceuticals:Clinical nutrition and sports performance brands specify certified organic and grass-fed protein derivatives. USDA organic certification commands 15-30% price premiums in American direct-to-consumer channels.
- Beverage Industry:Ready-to-drink protein fortification requires heat-stable, low-viscosity solutions.
- Animal Feed:Pet food premiumization and calf milk replacer applications absorb lower-grade protein streams.
Food industry channels absorb the majority of volume; nutraceuticals climb the fastest on value contribution per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German industrial buyers while New Zealand suppliers capture margin through supply security premiums. European carbon-accounting mandates compress procurement flexibility for meat-alternative manufacturers. Asian contract manufacturers exploit production-linked incentives to undercut European toll-processing rates.
Germany
Industrial bakery reformulation and clean-label dairy substitution drive textured protein procurement volume. The EU Green Deal's Scope 3 disclosure rules force ingredient suppliers to document farm-level methane emissions. The Cologne-Düsseldorf corridor hosts major meat-alternative R&D facilities where high-moisture extrusion adoption accelerates.
United States
Sports nutrition brands and ready-to-drink beverage manufacturers sustain whey protein isolate demand. FDA GRAS self-affirmation governs novel fractionation process entry, while USDA organic certification commands 15-30% price premiums in direct-to-consumer channels. California's precision-fermentation startups threaten dairy-derived protein positioning in carbon-sensitive buyer segments.
India
The PLI scheme for food processing attracts contract manufacturing investment targeting Southeast Asian export markets. FSSAI safety standards and BIS quality certifications structure domestic market access. Maharashtra and Gujarat dairy cooperatives expand fractionation capacity to serve regional meat-alternative formulators.
Netherlands
Plant-based meat startups concentrate procurement around suppliers with integrated carbon-verification systems. ECHA REACH standards restrict chemical emulsifier use in European formulations. Wageningen University's food technology cluster trains specialized thermo-mechanical process engineers for equipment optimization roles.
New Zealand
Fonterra's cooperative network anchors international dairy protein trade through supply security guarantees. The country's national dairy regulator oversees export certification for carbon-accounting compliance in EU markets. Canterbury region processing facilities concentrate high-volume milk protein concentrate output for Asian contract manufacturers.
Textured Milk Protein Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with fractionation and texturization capabilities. The vendor base stratifies between multinational dairy cooperatives with captive milk supply and independent toll processors dependent on commodity whey markets. Three archetypes dominate: cooperative-backed integrators, private-label fractionators, and precision-fermentation entrants. Competitive moves concentrate on backward integration into milk powder supply and multi-year procurement contracting to lock volume commitments.
Among cooperative-backed integrators, Fonterra Co-Operative Group and Arla Foods Ingredients occupy positions that exemplify supply-security differentiation. Glanbia plc sits within the specialized fractionation tier where R&D intensity in protein texturization systems creates positioning distance from pure-play toll processors. These three entities represent how geographic milk sourcing networks translate into procurement preference for carbon-accounting-compliant European manufacturers.
| Leading Market Players |
|---|
| Fonterra Co-Operative Group |
| Société FIT |
| Ingredia SA |
| Kerry Group plc |
| Socius Ingredients |
| FrieslandCampina Ingredients |
| Glanbia plc |
| Arla Foods Ingredients |
| Milk Specialties Global |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European high-moisture extrusion lines drives supplier behavior toward premium pricing for configured-to-order textured proteins while compressing margins on standard-grade concentrates. German meat-alternative manufacturers absorb 15-30% premiums for verified low-carbon supply chains under EU Green Deal procurement rules, reshaping how Fonterra and Arla Foods Ingredients negotiate annual volume agreements.
Pricing Analysis
The customization-premium spread separates standard milk protein concentrates from configured-to-order extrudates with specified fiber alignment and hydration profiles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with USDA organic and EU carbon-verified proteins commanding top positions. Cost compression in standard concentrates is intensifying because Indian PLI-subsidized contract manufacturers undercut European toll-processing rates. Industrial bakeries in Germany exhibit highest price sensitivity due to thin margins on clean-label bread, while American nutraceutical brands show lowest sensitivity for rapid-absorption whey isolates.
Supply Chain Analysis
Upstream feedstock for textured milk proteins draws from New Zealand cooperative farms, German dairy processors, and Indian Maharashtra-Gujarat milk sheds. Fonterra's dominance in international dairy protein trade creates single-source vulnerability for European and Asian manufacturers without backward integration into milk powder supply. Skim milk powder, whey protein concentrate, and membrane filtration equipment constitute critical input dependencies. Commodity price volatility in dairy markets transmits directly to production economics. Distribution runs through B2B ingredient marketplaces and traditional distributor networks serving plant-based meat startups and industrial bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Green Deal carbon-accounting mandates force ingredient requalification across European plant-based meat manufacturing. Clean-label reformulation in German industrial bakery accelerates procurement of granule-form textured proteins.
For Market Incumbents: Pre-empt precision-fermentation substitution by deepening backward integration into verified low-carbon dairy supply chains and locking multi-year procurement contracts with German meat-alternative manufacturers. Invest in high-moisture extrusion capacity additions in the Netherlands and Germany to capture equipment payback periods under eighteen months. Fortify fractionation-to-texturization capabilities against pure-play toll processors. For New Entrants and Emerging Players: Mid-scale contract manufacturers in India targeting Southeast Asian export markets represent the most penetrable entry point for toll-processing agreements under PLI scheme subsidies. White-space exists in USDA-certified organic textured proteins for American direct-to-consumer nutraceutical channels. Digital procurement platforms enable plant-based startup access without field sales investment. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-linked ingredient play because carbon-accounting compliance will persist as a procurement filter across European food manufacturing. Target acquisition archetypes include specialized fractionators with dual conventional-organic lines and integrated texturization capabilities. Watch for inflection signals in precision-fermentation scale-up announcements from Perfect Day and competitors achieving cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Verified Dairy Supply | Fonterra's biogas capture at cooperative farms qualifies textured proteins for EU carbon-neutral procurement tenders. |
| High-Moisture Extrusion Capacity Expansion | Dutch and German startups adopt these systems within compressed payback periods, displacing traditional drying-intensive processes. |
| USDA Organic Certification Investment | American nutraceutical channels command substantial premiums for certified organic proteins, opening margin expansion for dual-line fractionators. |
| Digital Procurement Platform Partnership | B2B ingredient marketplaces disintermediate distributor networks, enabling smaller producers to access plant-based startup customers. |
| Precision Fractionation Technology Licensing | Advanced membrane separation yields consistent casein-to-whey ratios required for repeatable hydration behavior in toll-processing agreements. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with dairy technology directors, plant-based meat R&D leads, European procurement managers, and contract manufacturing executives; and secondary validation through Fonterra cooperative disclosures, EU ETS carbon-accounting filings, FSSAI safety standards documentation, and BIS quality certifications. Bottom-up volume modeling triangulated against top-down expenditure analysis across the projection horizon.
Forecast inputs considered protein fractionation grade, application end-use, form type, and regional regulatory cluster throughout the modeling period. CAGRs derived from segment-level growth rate reconciliation against macro dairy commodity trends. Industry-specific inputs included EU Green Deal Scope 3 disclosure implementation timelines and India PLI scheme subsidy absorption rates for food processing investment.
Practitioners should monitor precision-fermentation cost curves and EU methane-emission verification protocol changes for early signals of forecast revision. Cross-checking against ECHA REACH chemical restriction updates and FSSAI safety standard amendments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Microbial Food Ingredients Market
Ingredients
North America Malt Ingredients Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Global Dietary Fibers Market
Ingredients
Microencapsulated Oil Market
Ingredients
Pet Food Ingredients Market
Ingredients
Corn Peptide Market
Ingredients
Banana Essence Market
Ingredients
Hexane-Free Protein Market
Ingredients
Konjac Root Fiber Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Potato Peel Powder Market
Ingredients
North America Dairy Ingredients Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Biotech Ingredients Market